
 Blood and Organ Bank Market | 2026-2036
Blood and Organ Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Blood and Organ Bank Market Analysis
North American plasma collection infrastructure is rebalancing after pandemic-era disruptions strained donor recruitment and inventory buffers. CSL Plasma leverages its center density across the United States to sustain high-volume source plasma output. Vitalant competes through its integrated hospital-service model, while Sanquin anchors European supply security with its nonprofit, government-backed operational structure in the Netherlands.
Blood and organ banking encompasses the procurement, testing, processing, storage, and distribution of human-derived biological materials for therapeutic transplantation and clinical research, requiring maintenance at precise temperatures between one and six degrees Celsius for whole blood and controlled-rate freezing for cryopreserved stem cells. The primary commercial purpose centers on ensuring safe, type-matched biological products reach end users within regulated viability windows. Blood components occupy the largest volume share within product-type segmentation, reflecting chronic demand for red-cell and platelet units in surgical and oncology settings. Cryopreservation technology leads margin pools due to the specialized equipment and technical expertise required for viable long-term stem-cell and tissue storage.
The FDA governs donor eligibility and product safety through its blood and biologics regulations, while the EU Tissue and Cells Directive harmonizes handling standards across member states, and Health Canada enforces its own biologics framework for domestic banks. These layered requirements shape market access by mandating costly certification, traceability systems, and facility inspections that favor established operators with compliance infrastructure. Stakeholders must monitor evolving donor-deferral policies and emerging pathogen-reduction technologies to anticipate shifts in product availability and competitive positioning.
Market Dynamics
Automated cold-chain monitoring systems are compressing temperature-excursion rates below legacy thresholds, forcing banks to retire manual logging protocols and absorb sensor-network capital costs.
Growth Catalysts
- Pathogen-reduction technologies:The FDA's updated guidance on pathogen-reduced platelets accelerates hospital adoption of INTERCEPT-treated units, reducing septic transfusion reactions and extending shelf-life parameters.
- Germany:The country's national donor registry expansion creates matched-donor density for hematopoietic stem-cell transplants, shortening search times from months to weeks for leukemia patients.
- Japan's PMDA:Streamlined biologics licensing pathways for cord-blood products accelerate commercial bank approvals, unlocking private storage demand among expectant families.
Market Restraints
- Plasma protein pricing volatility:Fractionation feedstock costs swing with immunoglobulin demand cycles, squeezing margin predictability for collection centers dependent on contract manufacturing.
- Single-source dependency:Cryopreservation media formulations concentrate among three specialty chemical suppliers, creating input vulnerability for stem-cell banks.
- EU Tissue and Cells Directive:Harmonized traceability mandates impose documentation burdens that favor high-volume operators and disadvantage regional hospital-affiliated banks.
Strategic Opportunities
- India:Underdeveloped bone-marrow registries present white-space potential for public-private partnership models linking urban collection centers to transplant programs.
- Perioperative autologous blood salvage:Cell-saver technology convergence with point-of-care processing enables same-surgery reinfusion, reducing allogeneic unit dependency in cardiac and orthopedic settings.
- Health Canada biologics framework:Emerging incentives for domestic plasma self-sufficiency create procurement tailwinds for vertically integrated collection-to-fractionation operations.
Industry Challenges
- Cryobiologist talent scarcity:Specialized competency in controlled-rate freezing protocols remains concentrated among aging practitioners, constraining expansion of viable long-term tissue storage programs.
- ISO 20387 biobank certification:Multi-year accreditation timelines delay operational revenue for new facilities, particularly in emerging markets lacking qualified auditors.
- Legacy inventory system integration:Proprietary donor-management platforms resist interoperability with national traceability networks, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood and Organ Bank Market |
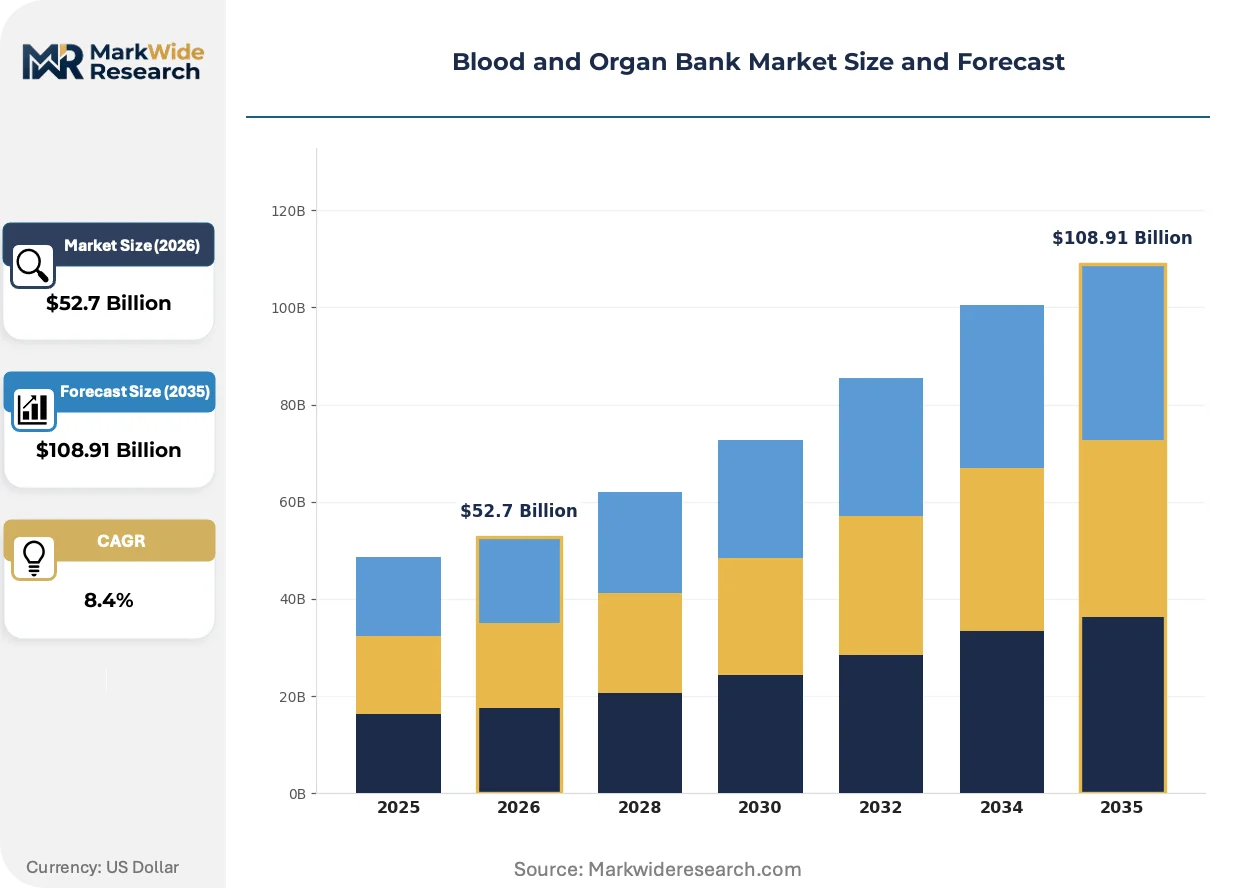
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Components, Organs, Tissue Products, Stem Cells Application: Transfusion Medicine, Organ Transplantation, Research, Cellular Therapy End User: Hospitals, Blood Banks, Research Institutions, Tissue Banks Technology: Cold Storage, Blood Bag Technology, Biobanking Systems, Cryopreservation |
| Companies Covered | American National Red Cross, New York Blood Center, NHS Blood and Transplant, CSL Plasma, Vitalant, Sanquin, New England Organ Bank, Australian Red Cross Lifeblood, Canadian Blood Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood and Organ Bank Market Emerging Trajectories
Biopreservation science is advancing along three vectors: automation replacing manual handling, regulatory frameworks tightening viability documentation, and hospital procurement consolidating supplier relationships.
Closed-system automated blood component separators are overtaking open-bowl centrifugation in high-volume collection centers. The ALYX and Trima Accel platforms reduce bacterial contamination risk and operator variability. Hospital transfusion services now specify closed-system processing in tenders, compressing market share for legacy equipment.
REACH chemical-registration requirements are reshaping cryopreservation media composition. Dimethyl sulfoxide alternatives face toxicological scrutiny, compelling reformulation investments. European stem-cell banks accelerate validation of non-DMSO cryoprotectants ahead of 2026 authorization deadlines.
Consolidated procurement through group purchasing organizations concentrates contract awards among three to five national blood suppliers. Independent community blood centers lose hospital service agreements to integrated networks. This pattern is most visible across the United States, where Vitalant and the American Red Cross capture regional system contracts.
Blood and Organ Bank Market Segmentation
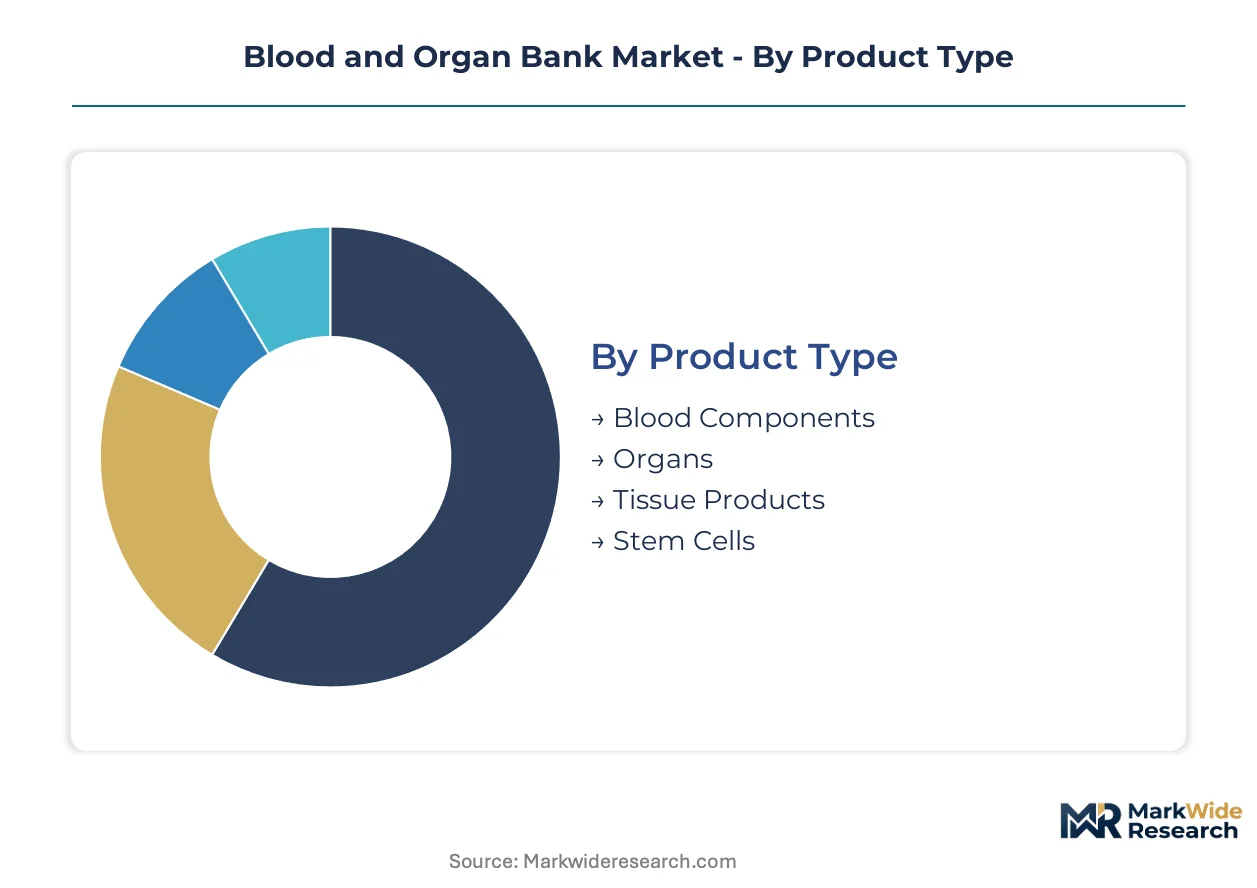
Blood and organ bank procurement decisions hinge on viability windows, regulatory compliance tiers, and therapeutic specificity. Segment boundaries reflect divergent cold-chain requirements, donor matching complexity, and end-user technical capabilities.
Product Type:
Hospital procurement teams prioritize shelf-life stability and cross-matching speed when selecting biological products.
- Blood Components:Red cell concentrates, platelet units, and plasma fractions constitute the highest procurement volume. United States hospital networks drive demand through standardized massive transfusion protocols for trauma and surgical services. FDA pathogen-reduction mandates are accelerating INTERCEPT-treated platelet adoption.
- Stem Cells:Hematopoietic and mesenchymal populations require controlled-rate freezing and liquid nitrogen vapor-phase storage. Germany's national donor registry expansion shortens unrelated donor search times for leukemia patients. Cryopreservation media costs and cryobiologist scarcity constrain bank expansion.
- Organs:Hearts, lungs, livers, and kidneys demand specialized preservation solutions and rapid logistics coordination.
- Tissue Products:Corneas, bone grafts, and skin substitutes serve reconstructive and ophthalmic applications.
Volume sits with blood components; growth tilts toward stem cells.
Application:
Clinical utility and reimbursement pathways determine adoption velocity across therapeutic categories.
- Transfusion Medicine:Perioperative blood management and oncology support account for sustained unit consumption. United States trauma centers specify leukoreduced and irradiated components for immunocompromised recipients. Automated component separation technology reduces bacterial contamination risk.
- Cellular Therapy:CAR-T manufacturing and regenerative medicine applications require GMP-compliant biobanking infrastructure. Japan's PMDA streamlined licensing for cord-blood products unlocks private storage demand among expectant families. Manufacturing scale-up challenges limit commercial availability.
- Organ Transplantation:Immunosuppression protocols and organ allocation systems shape procurement patterns.
- Research:Academic and pharmaceutical biobanking supports biomarker discovery and clinical trial enrollment.
Transfusion medicine commands current throughput; cellular therapy exhibits the steepest expansion trajectory.
End User:
Facility scale and integration depth determine technology investment capacity.
- Hospitals:Integrated health systems consolidate blood supplier contracts through group purchasing organizations. Vitalant and American Red Cross capture multi-hospital service agreements. Transfusion services specify closed-system processing equipment in procurement tenders.
- Blood Banks:Community collection centers face margin pressure from consolidated procurement and plasma protein pricing volatility.
- Tissue Banks:Eye, skin, and musculoskeletal tissue specialists navigate EU Tissue and Cells Directive traceability mandates.
- Research Institutions:Academic biobanks pursue ISO 20387 certification for sample quality assurance.
Hospitals dominate current procurement volume; research institutions are gaining share fastest through biobank infrastructure investment.
Technology:
Capital intensity and operational expertise requirements segment the supplier landscape.
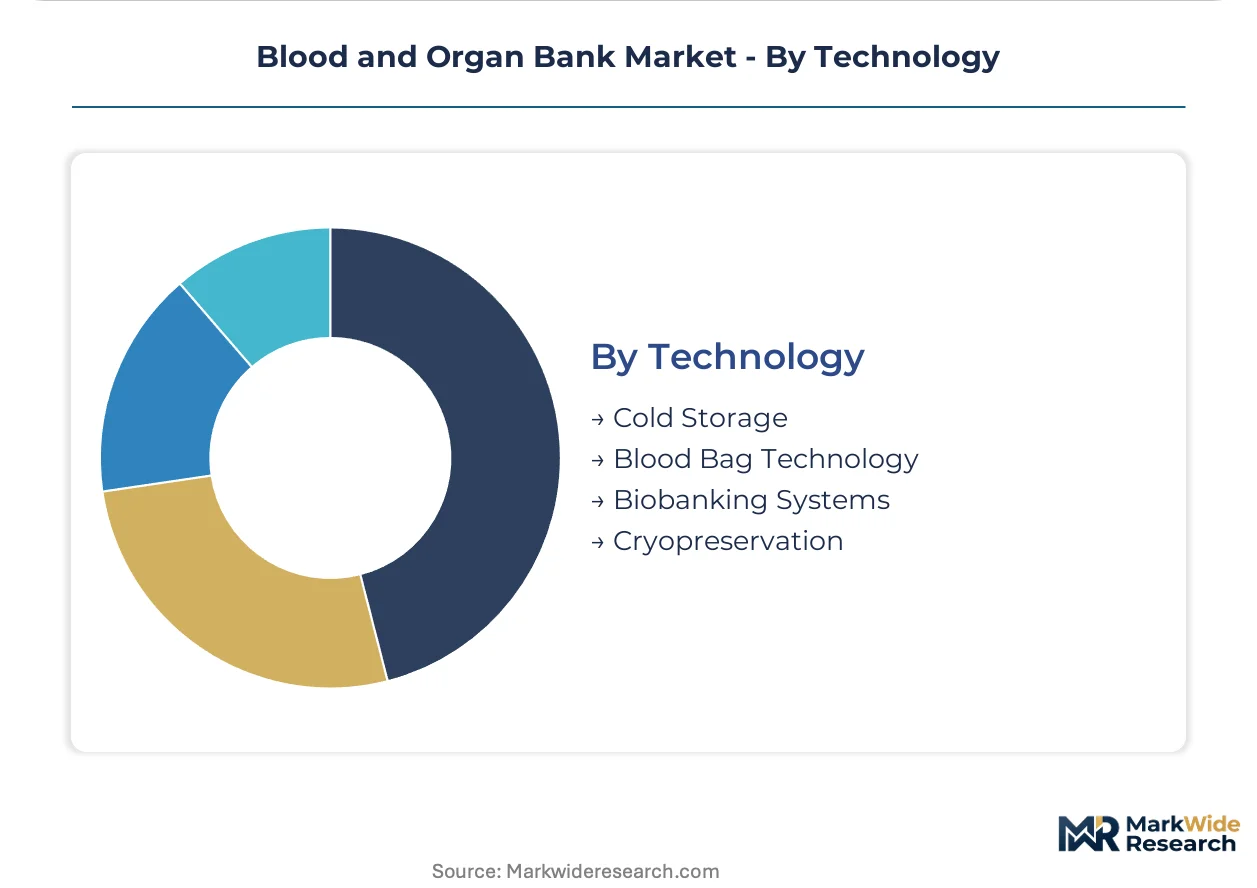
- Cryopreservation:Controlled-rate freezing and vapor-phase nitrogen storage preserve long-term stem-cell and tissue viability. REACH chemical-registration deadlines are compelling European banks to validate non-DMSO cryoprotectants ahead of authorization thresholds. Equipment and media costs concentrate margin pools among established operators.
- Cold Storage:Refrigerated blood bank inventory maintains one-to-six-degree Celsius parameters for short-term component holding.
- Biobanking Systems:Automated inventory management and sample tracking integrate with national traceability networks.
- Blood Bag Technology:Closed-system collection and processing containers reduce contamination risk during component separation.
Cold storage underpins routine operations; cryopreservation captures premium margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Source plasma collection infrastructure concentrates in donor-dense metropolitan corridors where cold-chain logistics and fractionation capacity co-locate. National health systems drive procurement consolidation, while regulatory frameworks shape operational viability windows across jurisdictions.
United States
Trauma centers and oncology services sustain demand for leukoreduced components across hospital networks. FDA pathogen-reduction mandates accelerate INTERCEPT-treated platelet adoption in transfusion protocols. The Dallas-Fort Worth metro anchors high-volume plasma collection center density, with automated processing platforms displacing legacy centrifugation.
Germany
Leukemia patient access to hematopoietic stem-cell transplants depends on unrelated donor registry expansion. The EU Tissue and Cells Directive harmonizes traceability standards across member-state borders. Bavaria's Munich-centered biobanking cluster validates non-DMSO cryoprotectants ahead of REACH authorization deadlines.
Japan
Expectant families drive private cord-blood storage demand through streamlined commercial licensing pathways. PMDA biologics framework revisions reduce approval timelines for cellular therapy products. Tokyo's academic medical centers integrate GMP-compliant biobanking infrastructure with CAR-T manufacturing scale-up.
Netherlands
Nonprofit government-backed operational structures ensure supply security for hospital transfusion services. EU traceability mandates concentrate documentation burdens on high-volume operators. Amsterdam-Leiden corridor facilities specialize in controlled-rate freezing protocols for long-term tissue viability.
India
Underdeveloped bone-marrow registries create white-space potential for public-private partnership models. The country's national pharmaceutical regulator enforces biologics handling standards for emerging collection centers. Maharashtra's Mumbai-Pune corridor links urban collection infrastructure to transplant program demand.
Blood and Organ Bank Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized cryopreservation services and automated cold-chain monitoring. The supplier base stratifies across integrated hospital-service networks, community collection centers, and government-backed nonprofit structures. Three archetypes dominate: vertically integrated plasma-to-fractionation operators, hospital-aligned transfusion service providers, and research-focused biobank specialists. Competitive positioning hinges on group purchasing organization contract capture and ISO 20387 certification timelines.
Among nonprofit operators, American National Red Cross and NHS Blood and Transplant exemplify government-contracted supply security models, while CSL Plasma occupies a position within the commercial plasma collection tier. These entities represent divergent capital structures—chartered humanitarian missions versus shareholder-return frameworks—each anchoring distinct procurement relationships with hospital end users.
| Leading Market Players |
|---|
| American National Red Cross |
| New York Blood Center |
| NHS Blood and Transplant |
| CSL Plasma |
| Vitalant |
| Sanquin |
| New England Organ Bank |
| Australian Red Cross Lifeblood |
| Canadian Blood Services |
| Others |
Supply Flow & Price Mechanics
Government-backed nonprofit operators anchor supply security across European hospital networks while compressing margin expansion for commercial plasma collectors competing on fractionation contracts. This ownership split between chartered humanitarian missions and shareholder-return frameworks creates divergent pricing discipline, with nonprofit cost-recovery models undercutting commercial bids for hospital service agreements while commercial operators capture premium pricing in private cord-blood storage and specialized cryopreservation services.
Pricing Analysis
Warranty and viability-guarantee bundling separates premium-tier cryopreservation contracts from transactional blood component procurement, with stem-cell banks offering decade-long storage assurances commanding price multiples over per-unit red-cell concentrates. Price differentiation rests on ISO 20387 certification status and cold-chain documentation granularity, with accredited facilities capturing hospital biobank contracts at standard-tier rates while uncertified regional banks compete on economy pricing for research samples. Cost compression in community blood center operations is intensifying because consolidated procurement through group purchasing organizations concentrates contract awards among three to five national suppliers. Independent hospital networks exhibit highest price sensitivity in routine transfusion component procurement, while academic medical centers demonstrate lowest sensitivity in cellular therapy-grade biobanking infrastructure.
Supply Chain Analysis
Direct-to-hospital distribution channels handle high-volume blood component demand through integrated service agreements, while specialized logistics providers manage cryopreserved stem-cell transport under vapor-phase nitrogen parameters. Geographic supply concentration centers on the United States, Germany, and the Netherlands for plasma collection and fractionation infrastructure, with Japan emerging for cord-blood processing technology. Raw material dependencies include cryopreservation media formulations, automated component separation equipment, and pathogen-reduction reagent kits. Single-source vulnerability in dimethyl sulfoxide alternatives creates input risk for European stem-cell banks facing REACH authorization deadlines. Distribution runs through hospital group purchasing organizations in North America and government-contracted supply security models in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-heavy operators as EU traceability mandates and FDA pathogen-reduction requirements force undercapitalized regional banks into acquisition or exit.
For Market Incumbents: Lock in hospital system contracts through multi-year service agreements that bundle routine transfusion components with specialized cellular therapy logistics, defending against emerging automated cold-chain monitoring specialists. Pursue backward integration into cryopreservation media formulation to reduce dependency on the three specialty chemical suppliers currently controlling input costs. Prioritize ISO 20387 certification acceleration to capture research institution procurement growth fastest. For New Entrants and Emerging Players: Underserved mid-tier Indian transplant centers present white-space potential for public-private partnership models linking urban collection infrastructure to bone-marrow registry expansion. Private cord-blood storage demand among expectant families in Japan offers penetrable entry through PMDA-streamlined licensing pathways. Lead with perioperative autologous blood salvage technology convergence to capture cardiac and orthopedic service line procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor cryobiologist-scarce stem-cell banks in Germany facing REACH compliance cost spikes and aging practitioner retirement waves. Long-term viability across the analysis window hinges on cellular therapy manufacturing integration, with GMP-compliant biobanking infrastructure commanding sustained premium multiples. Monitor FDA donor-deferral policy shifts as inflection indicators for plasma collection volume availability.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen-Reduction Technology Adoption | INTERCEPT-treated platelet mandates reshape hospital transfusion protocols and supplier certification requirements. |
| Non-DMSO Cryoprotectant Validation | European stem-cell banks accelerate reformulation investments ahead of REACH authorization deadlines. |
| Automated Cold-Chain Monitoring Deployment | Sensor-network capital costs compress temperature-excursion rates below legacy manual logging thresholds. |
| ISO 20387 Certification Acceleration | Multi-year accreditation timelines delay revenue for new facilities lacking qualified auditor access. |
| Cellular Therapy Manufacturing Integration | CAR-T scale-up demands GMP-compliant biobanking infrastructure co-located with academic medical centers. |
Methodological Framework
Document review covered FDA blood and biologics regulations, EU Tissue and Cells Directive implementation guidelines, and Health Canada biologics framework documents, complemented by interviews with blood bank operations directors, hospital transfusion service chiefs, cryobiology laboratory managers, and group purchasing organization contract specialists. Secondary validation drew from hospital procurement databases, GPO contract award filings, and national donor registry statistical reports. Bottom-up facility capacity estimates and top-down national health expenditure allocations were triangulated against primary interview data.
Segment-level outputs across product type, application, end user, and technology dimensions were generated through projection horizon modeling, with country-specific regulatory adoption curves and cold-chain infrastructure investment flows as key inputs. CAGRs were derived from fitted growth curves anchored to historical procurement volume trajectories and policy implementation timelines.
Revisions become necessary when pathogen-reduction technology adoption rates, donor-deferral policy expansions, or cryopreservation media authorization delays materialize outside modeled parameters. Forecasts reflect base-case assumptions regarding regulatory harmonization progress and fractionation capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Nursing Products Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Medical Products Market