
 Digital Comparators Market | 2026-2036
Digital Comparators Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Comparators Market Outlook
Discrete logic integration is fragmenting across CMOS, BiCMOS, and bipolar process nodes as foundries optimize for power-speed tradeoffs in comparator design. STMicroelectronics leverages its European fab network to sustain supply of automotive-grade precision comparators. Analog Devices anchors North American demand through specialized signal conditioning portfolios. Renesas Electronics Corporation dominates Japanese industrial automation channels with voltage comparator lineups optimized for factory floor environments.
Digital comparators are electronic circuits that evaluate two analog input voltages and output a binary logic state based on which input exceeds the other, typically operating with propagation delays below 50 nanoseconds and input offset voltages measured in microvolts for precision variants. Their primary purpose centers on analog-to-digital interface functions including zero-crossing detection, threshold monitoring, and waveform shaping in mixed-signal systems. Precision comparators command margin concentration in medical instrumentation and test equipment where offset stability determines measurement fidelity. Voltage comparators lead volume in automotive battery management and motor control architectures. High-speed variants in telecommunications infrastructure are capturing fastest expansion as 5G baseband processing demands sub-nanosecond decision windows.
FDA device classification rules in the United States shape comparator specifications for patient-connected diagnostic equipment through electromagnetic compatibility and isolation requirements. ECHA REACH restrictions on lead-bearing solder materials in Europe are forcing migration to RoHS-compliant comparator packages with modified termination metallurgies. China's GB standards for industrial control equipment, administered by SAMR, mandate surge immunity thresholds that filter comparator suppliers without certified test reports. Stakeholders must monitor how dual carbon goals across East Asian manufacturing hubs recalibrate foundry energy sourcing and comparator wafer cost structures.
Market Dynamics
Precision voltage comparator procurement from Taiwan and South Korean semiconductor foundries is tightening supply availability for European and North American OEMs, forcing dual-sourcing strategies and qualification of secondary wafer sources.
Growth Catalysts
- EU Chips Act capital redirection:European comparator manufacturing capacity is expanding through targeted subsidies, reducing import dependency for automotive and industrial automation customers.
- 5G baseband processing architectures:Telecommunications infrastructure deployment is pulling sub-nanosecond decision window comparators into high-volume production.
- Shenzhen-Shanghai-Suzhou industrial corridor:China's factory automation upgrade cycle is generating concentrated demand for voltage comparators in motor control and battery management systems.
Market Restraints
- Advanced node wafer cost volatility:Precision comparator fabrication on sub-40nm processes faces input cost pressure from specialty substrate and photomask pricing.
- East Asian foundry concentration risk:Over 70% of high-speed comparator wafer supply originates from Taiwan and South Korea, creating single-point vulnerability.
- RoHS termination metallurgy migration:ECHA REACH restrictions on lead-bearing solder materials are forcing package redesigns that extend qualification timelines.
Strategic Opportunities
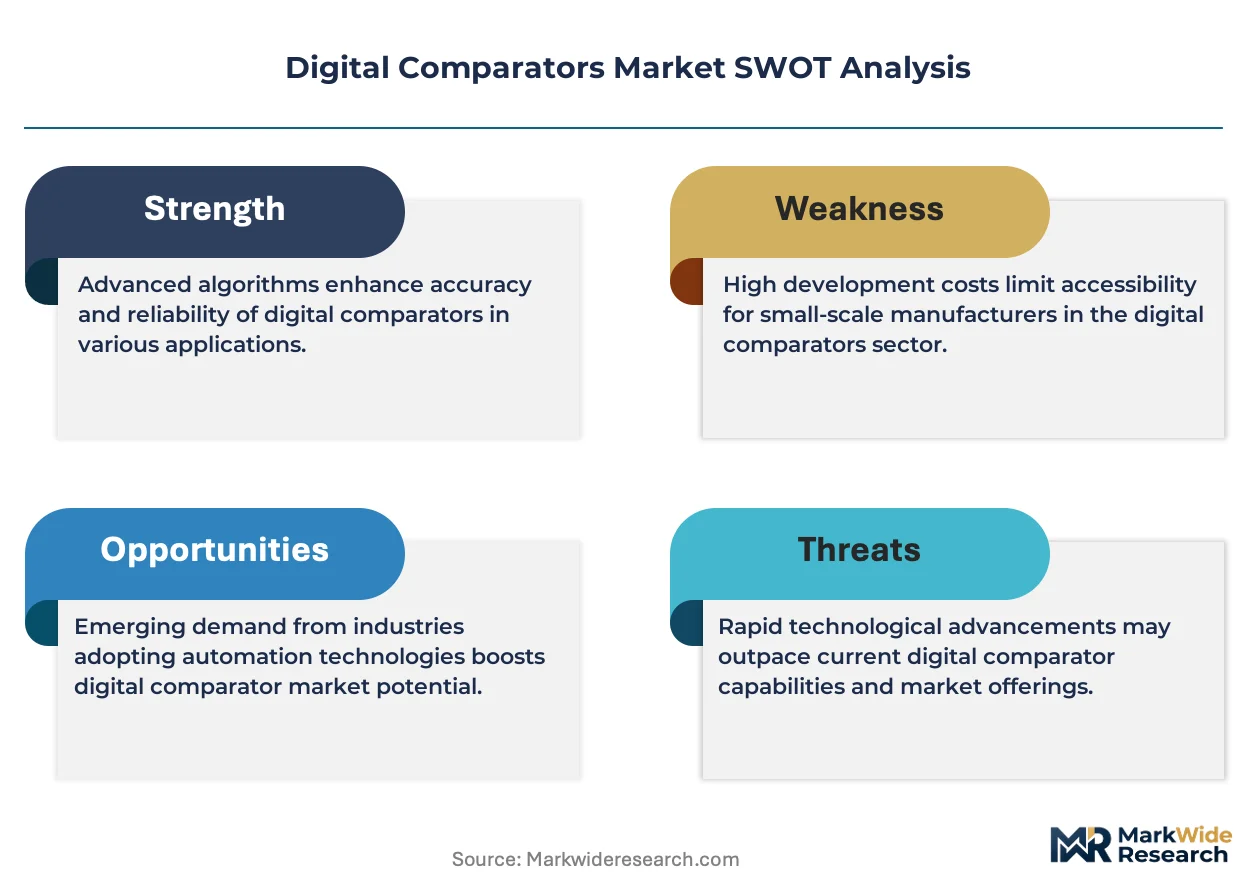
- Medical instrumentation certification gap:FDA electromagnetic compatibility requirements for patient-connected diagnostic equipment are filtering out uncertified suppliers, creating margin expansion for qualified vendors.
- Automotive battery management integration:Voltage comparator modules are converging with isolation amplifiers and ADCs in single-package solutions for electric vehicle architectures.
- Direct procurement from European fabs:STMicroelectronics and emerging European foundries are establishing bypass channels to industrial OEMs previously dependent on Asian distributors.
Industry Challenges
- Mixed-signal design talent scarcity:Comparator architecture expertise combining analog precision with digital interface requirements commands premium compensation and extended hiring cycles.
- Dual carbon goal compliance costs:SAMR-administered energy sourcing requirements for Chinese foundries are recalibrating wafer cost structures and delivery commitments.
- Legacy system integration friction:Factory floor retrofit projects in Japan and Germany face signal conditioning incompatibility between new precision comparators and existing PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Comparators Market |
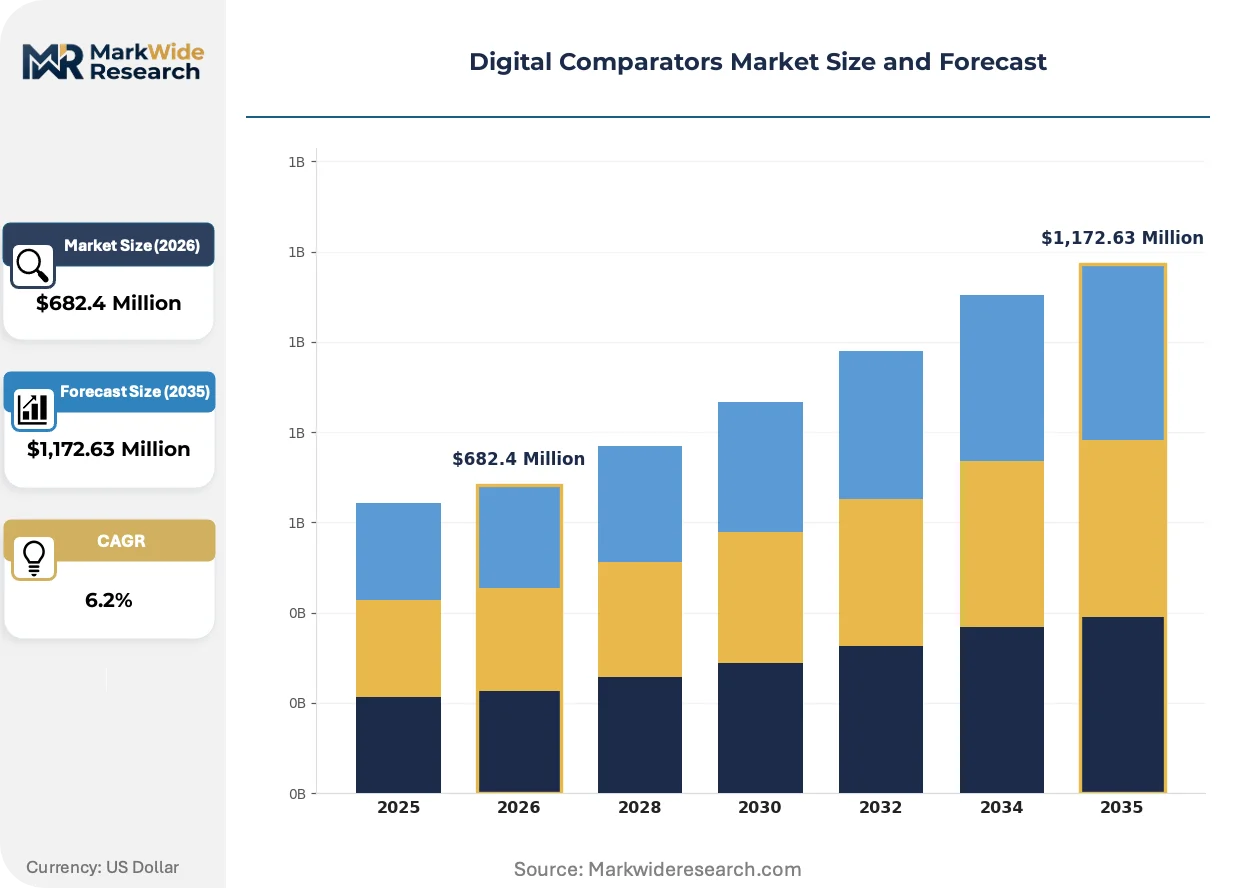
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,172.63 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Comparators, Precision Comparators, Voltage Comparators, High-Speed Comparators End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Technology: CMOS, Bipolar, BiCMOS, Low-Voltage Application: Signal Conditioning, Voltage Level Detection, Signal Processing, Data Conversion |
| Companies Covered | Frenco GmbH, Japan Radio Co Ltd, STMicroelectronics, Panasonic Corporation, Renesas Electronics Corporation, Mahr Inc, Nisshinbo Micro Device Inc, Analog Devices Inc, MetLogix Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Comparators Market Strategic Shifts
Comparator design is fragmenting across process nodes as foundries optimize power-speed tradeoffs, while regulatory pressure on materials and electromagnetic compatibility is reshaping qualification requirements.
BiCMOS comparator architectures are migrating from legacy bipolar-dominated designs in precision instrumentation applications. Medical device manufacturers in Switzerland and Germany are accelerating adoption to achieve microvolt offset stability with reduced quiescent current. This migration from pure bipolar processes is compressing the performance gap between precision and power-efficient variants.
REACH restrictions on lead-bearing solder materials in Europe are forcing package termination metallurgy redesigns. Comparator suppliers must requalify RoHS-compliant offerings through modified plating chemistries and alloy compositions. Medical instrumentation and aerospace segments in France and Germany are experiencing the longest recertification delays.
Automotive OEMs are consolidating comparator procurement through tier-one module suppliers rather than direct semiconductor sourcing. Battery management system integrators in South Korea and Germany are capturing value-add through bundled voltage monitoring solutions. This concentration is most visible in electric vehicle platforms where functional safety certification requirements favor established subsystem vendors.
Digital Comparators Market Segmentation
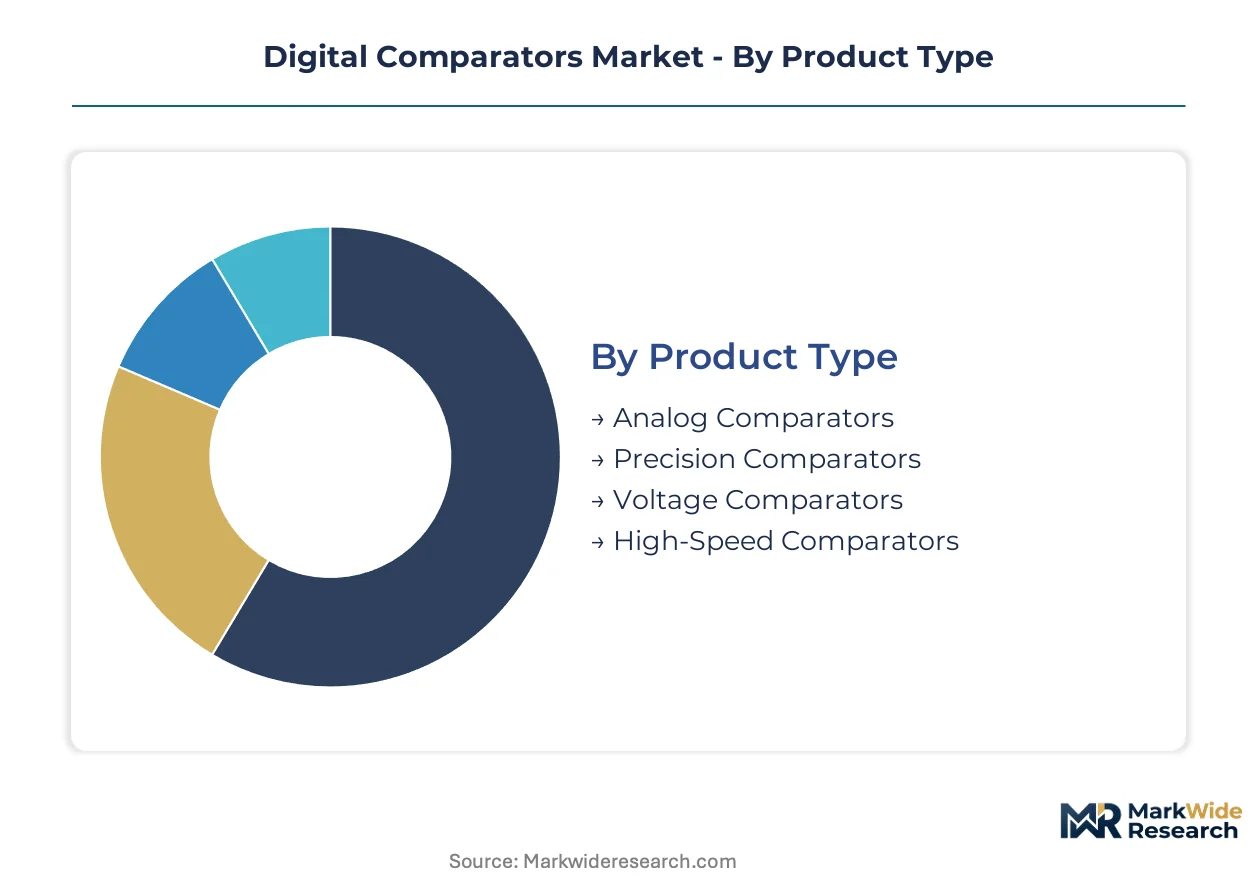
Digital comparator architectures fragment across process technologies, voltage domains, and response speed requirements. Procurement patterns diverge sharply between precision instrumentation demanding microvolt stability and automotive volume applications prioritizing cost-optimized threshold detection.
Product Type:
Use-case spectrum spans medical calibration benches requiring offset stability through telecommunications infrastructure demanding sub-nanosecond propagation delays.
- Precision Comparators:These devices achieve input offset voltages measured in single-digit microvolts with temperature drift below 5µV/°C. Medical instrumentation manufacturers in Switzerland and Germany concentrate procurement here for patient-connected diagnostic equipment where measurement fidelity determines regulatory clearance.
- Voltage Comparators:Standard variants dominate automotive battery management and motor control architectures with propagation delays of 50-200 nanoseconds. China's Shenzhen-Shanghai-Suzhou industrial corridor generates concentrated demand as factory automation upgrade cycles accelerate.
- Analog Comparators:General-purpose designs serve cost-sensitive consumer electronics and basic industrial signaling.
- High-Speed Comparators:Sub-nanosecond decision windows address 5G baseband processing and optical communication front-ends.
Established volume favors voltage comparators; emerging adoption favors high-speed variants.
End User:
Customer procurement maturity separates safety-critical automotive qualification from high-volume consumer electronics spot purchasing.
- Automotive:Battery management system integrators in South Korea and Germany bundle voltage monitoring with isolation amplifiers and ADCs in single-package solutions. Functional safety certification requirements under ISO 26262 favor established subsystem vendors over direct semiconductor sourcing.
- Industrial Automation:Renesas Electronics channels dominate Japanese factory floor environments with comparator lineups optimized for PLC integration and motor drive protection. Legacy system retrofit projects in Germany face signal conditioning incompatibility with new precision architectures.
- Consumer Electronics:Smartphone and wearable OEMs drive CMOS comparator volumes with aggressive cost targets.
- Telecommunications:5G infrastructure deployment pulls specialized high-speed variants into carrier-grade equipment.
Procurement concentration sits with automotive; margin expansion favors industrial automation.
Technology:
Process node selection trades quiescent current against bandwidth and offset performance across foundry offerings.
- BiCMOS:Hybrid architectures merge bipolar input stages with CMOS output drivers. Medical device manufacturers accelerate adoption to achieve microvolt offset stability with reduced power consumption compared to legacy bipolar-only designs.
- CMOS:Dominates portable and battery-powered applications through nanoampere quiescent currents. Taiwan and South Korean foundries optimize these processes for consumer electronics scale.
- Bipolar:Retains foothold in precision instrumentation requiring lowest voltage noise.
- Low-Voltage:Sub-1.8V operation addresses IoT endpoint and energy harvesting applications.
BiCMOS gains share fastest in precision segments; CMOS maintains cost leadership in high volume.
Application:
Functional requirements determine comparator specification hierarchy from simple threshold crossing to complex mixed-signal conditioning.
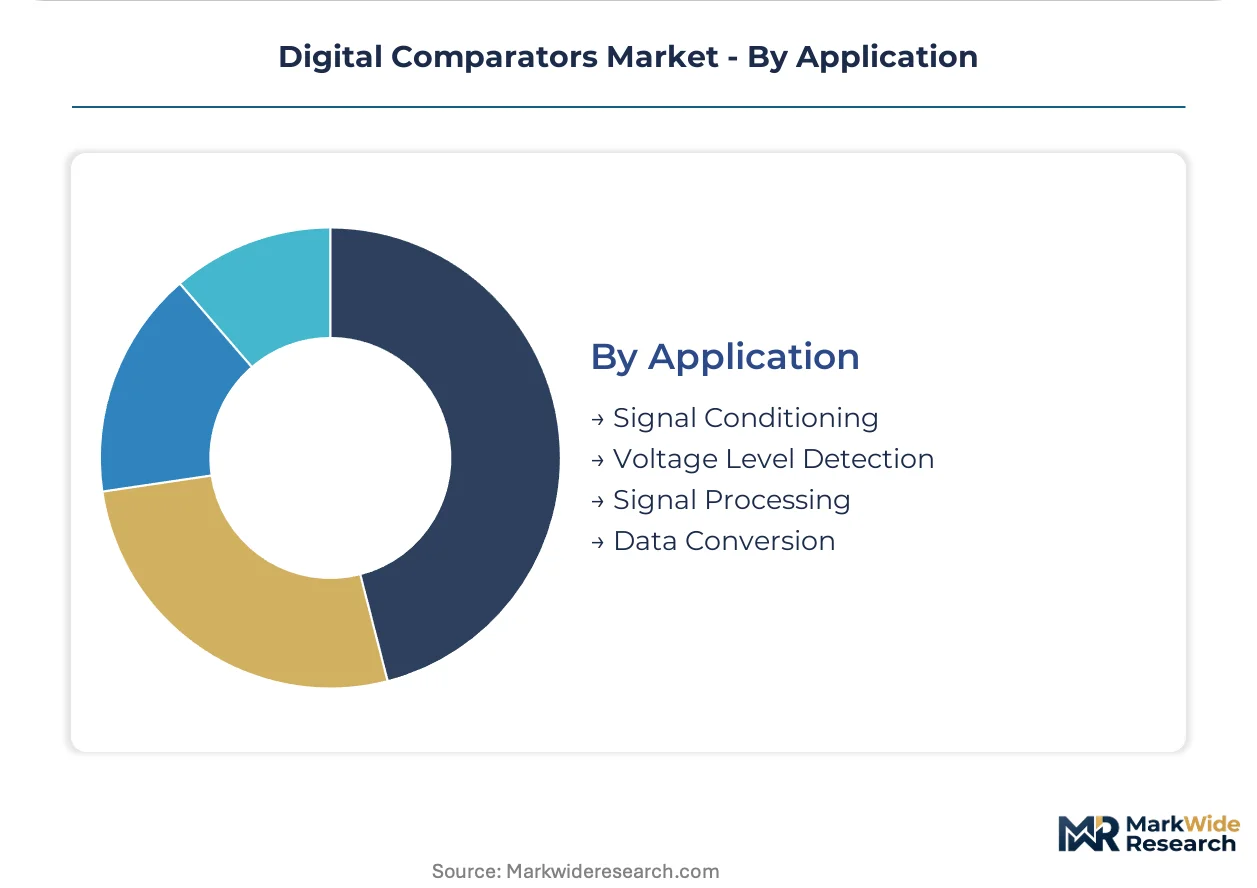
- Signal Conditioning:Analog Devices anchors North American demand through specialized portfolios integrating comparators with amplifiers and references. Sensor interface applications in aerospace and defense require extended temperature range qualification.
- Data Conversion:Comparator performance bounds ADC effective resolution and conversion speed. Successive-approximation and flash architectures depend on settling time and metastability characteristics.
- Voltage Level Detection:Power management ICs incorporate comparators for undervoltage lockout and sequencing functions.
- Signal Processing:Zero-crossing detection and waveform shaping support motor control and power factor correction.
Signal conditioning commands premium pricing; data conversion drives technology roadmap investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive battery management system integrators in South Korea and Germany concentrate procurement power. Precision instrumentation buyers in Switzerland and Germany drive medical-grade comparator specifications. Industrial automation OEMs across China's eastern seaboard generate sustained volume demand.
China
Shenzhen-Shanghai-Suzhou industrial corridor drives voltage comparator consumption for motor control and battery management systems. SAMR-administered GB standards mandate surge immunity thresholds that filter supplier qualification. Suzhou-based factory automation integrators are expanding comparator inventories to support electric vehicle component testing lines.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria consolidate procurement through tier-one battery management suppliers. ECHA REACH restrictions on lead-bearing solder materials force RoHS-compliant package redesigns with extended recertification timelines. Munich-Stuttgart industrial corridor hosts subsystem vendors bundling comparators with isolation amplifiers for electric vehicle platforms.
South Korea
Semiconductor foundries in Gyeonggi Province expand precision voltage comparator fabrication for advanced node testing equipment. MFDS medical device regulations shape electromagnetic compatibility requirements for diagnostic equipment exports. Seoul-Incheon manufacturing belt concentrates battery management system integrators capturing value-add through bundled voltage monitoring solutions.
United States
FDA device classification rules govern comparator specifications for patient-connected diagnostic equipment through electromagnetic compatibility and isolation mandates. Analog Devices anchors North American demand through specialized signal conditioning portfolios integrating precision comparators. Greater Boston medical instrumentation cluster drives microvolt offset stability requirements for measurement fidelity.
Japan
Renesas Electronics channels dominate factory floor environments with comparator lineups optimized for PLC integration and motor drive protection. METI industrial standards shape procurement specifications for legacy system retrofit projects. Nagoya-Osaka manufacturing belt faces signal conditioning incompatibility friction between new precision architectures and existing industrial control systems.
Digital Comparators Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base stratifies between scale-driven diversified semiconductor houses and focused precision instrumentation suppliers. Three archetypes dominate: European automotive-grade specialists, Asian industrial automation channel captains, and North American signal conditioning integrators. Competitive moves center on foundry capacity reservations and functional safety certification stacking under ISO 26262.
Among diversified semiconductor manufacturers, STMicroelectronics leverages its European fab network to sustain automotive-grade precision comparator supply. Renesas Electronics Corporation occupies the industrial automation channel captain position across Japanese factory floor environments. Analog Devices anchors North American positioning through specialized signal conditioning portfolios that integrate comparators with amplifiers and voltage references.
| Leading Market Players |
|---|
| Frenco GmbH |
| Japan Radio Co Ltd |
| STMicroelectronics |
| Panasonic Corporation |
| Renesas Electronics Corporation |
| Mahr Inc |
| Nisshinbo Micro Device Inc |
| Analog Devices Inc |
| MetLogix Inc |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Shenzhen freight corridors carry precision comparator wafers from Taiwan foundries to mainland China assembly facilities, with logistics cost volatility amplifying margin compression for European and North American OEMs while enabling aggressive pricing from integrated Asian suppliers serving the Shenzhen-Shanghai-Suzhou industrial corridor.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement between automotive OEMs and European foundries. Three-tier pricing structure across automotive-grade precision, industrial standard, and consumer economy levels separates ISO 26262-certified variants from basic threshold detectors. Pricing pressure stems from advanced node wafer cost volatility as sub-40nm photomask expenses escalate. Consumer electronics buyers exhibit highest price sensitivity; medical instrumentation buyers accept premium positioning for FDA-cleared electromagnetic compatibility.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan, South Korea, and Japan before precision lithography and bipolar or BiCMOS processing. Specialty photomasks and advanced packaging substrates constitute critical dependencies alongside pure silicon. Single-source vulnerability concentrates in Taiwan foundry capacity exceeding seventy percent of high-speed comparator supply. Distribution runs through tier-one battery management system integrators in South Korea and Germany rather than direct semiconductor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Comparators Market constitutes a high-growth disruption as 5G baseband processing architectures pull sub-nanosecond decision window devices into carrier-grade volume production, while EU Chips Act subsidies recalibrate European manufacturing economics.
For Market Incumbents: Build certification moats around ISO 26262 functional safety and FDA electromagnetic compatibility for patient-connected equipment. Secure foundry capacity reservations at STMicroelectronics European fabs before EU Chips Act allocation deadlines. Defend against emerging BiCMOS specialists by accelerating pure bipolar process deprecation in precision instrumentation segments. For New Entrants and Emerging Players: Establish a beachhead in medical instrumentation certification gaps where FDA electromagnetic compatibility requirements filter uncertified suppliers. Target Swiss and German diagnostic equipment manufacturers seeking microvolt offset stability with reduced quiescent current. Pursue direct procurement relationships with Suzhou-based factory automation integrators expanding electric vehicle component testing lines. For Investors and Strategic Acquirers: European automotive-grade precision comparator specialists with captive fab access represent the most defensible acquisition archetype. Long-term viability hinges on dual-sourcing qualification completion before East Asian foundry concentration risk materializes. Monitor EU Chips Act subsidy disbursement velocity as inflection indicator for European manufacturing capacity competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | STMicroelectronics European fab allocations reduce import dependency for automotive OEMs. |
| Functional Safety Certification | ISO 26262 stacking enables battery management system integration in electric vehicles. |
| BiCMOS Process Migration | Medical device manufacturers in Switzerland achieve microvolt stability with lower power. |
| RoHS Package Redesign | ECHA REACH compliance extends recertification timelines for aerospace segments in Germany. |
| Direct OEM Procurement Channel | Bypass of Asian distributors captures margin from European industrial automation customers. |
Study Parameters
A spread of perspectives from comparator design engineers at foundries, procurement leads at automotive battery management system integrators, regulatory affairs specialists at medical device manufacturers, and distribution channel managers converged on the working assumptions. Primary interviews combined with secondary validation from SEC semiconductor filings, ECHA REACH regulatory databases, SAMR GB standard publications, and foundry capacity disclosure reports. Bottom-up wafer shipment estimates and top-down end-use demand aggregation provided triangulation.
Demand-supply balance modeling across product type, technology node, end-use industry, and regional regulatory cluster dimensions structured the analytical framework throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by foundry capacity expansion announcements and OEM procurement contract visibility. 5G infrastructure deployment schedules and EU Chips Act subsidy allocation timelines served as comparator-specific forecast inputs.
Stress conditions across Taiwan foundry geopolitical disruption, advanced node wafer cost escalation, and ECHA REACH enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about BiCMOS migration velocity and automotive battery management integration timing. Cross-checking against IHS Markit semiconductor production data and OECD trade flow statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
One-Box Testers Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Battery Testing Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
North America Electronic Test and Measurement Market