
 Optical Critical Dimension (OCD) Measurements System Market | 2026-2036
Optical Critical Dimension (OCD) Measurements System Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Critical Dimension (OCD) Measurements System Market Insights
REACH compliance is realigning the cost-of-entry calculus for European semiconductor equipment suppliers. KLA Corporation leverages its installed base of scatterometry platforms to sustain service revenue across leading-edge fabs. Applied Materials Inc. anchors its OCD portfolio through backward integration into source hardware and algorithm development. Nova Ltd. differentiates via specialized thin-film measurement modules for advanced packaging nodes.
Optical Critical Dimension measurement systems employ polarized broadband reflectometry and spectroscopic ellipsometry to resolve sub-nanometer feature dimensions on patterned semiconductor wafers, operating at wavelengths from deep ultraviolet through near-infrared to capture critical linewidth, sidewall angle, and profile height data essential for process control in lithography and etch modules. Stand-alone systems dominate capital expenditure budgets at leading-edge fabs, while integrated systems embedded within cluster tools are gaining share as throughput requirements tighten. Software solutions represent the fastest-expanding margin pool as machine-learning-driven recipe optimization reduces engineering cycle times. Scatterometry leads technology adoption for inline monitoring, though spectroscopy is displacing legacy methods in compound semiconductor applications.
The EU AI Act and MDR frameworks impose algorithmic transparency and medical-device-grade calibration standards that reshape product development priorities for European-bound equipment. FDA oversight of diagnostic semiconductor manufacturing and EPA reporting on fluorinated greenhouse gas emissions from etch processes further constrain system design flexibility. Stakeholders must monitor how CSRD disclosure rules and evolving ISO 17025 metrology accreditation reshape procurement criteria across foundry and research-institution end users.
Market Dynamics
EUV lithography node shrinkage below 3nm is compressing process control tolerances, forcing fabs to deploy scatterometry platforms for inline linewidth monitoring at sub-nanometer resolution. Taiwan's Hsinchu Science Park cluster concentrates procurement authority as foundries consolidate metrology vendor relationships.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European-bound equipment suppliers must embed interpretable machine-learning models into recipe optimization software, creating upgrade cycles across installed bases.
- Compound semiconductor packaging expansion:Spectroscopic ellipsometry is penetrating GaN-on-SiC and InP process lines as legacy electrical probe methods fail on insulating substrates.
- CSRD disclosure requirements:Metrology traceability documentation now feeds directly into corporate sustainability reporting, elevating ISO 17025-accredited systems in procurement scoring.
Market Restraints
- Deep ultraviolet source hardware concentration:Laser and broadband lamp supply chains cluster in German and Japanese component vendors, exposing fabs to single-source fragility.
- Fluorinated greenhouse gas reporting:EPA mandatory disclosure of etch-process emissions adds compliance overhead to integrated OCD cluster tool deployments.
- Atomic force microscopy substitution:AFM platforms capture niche applications requiring direct sidewall contact, capping scatterometry addressable share in research institutions.
Strategic Opportunities
- India PLI scheme fab incentives:Domestic semiconductor manufacturing subsidies are attracting first-mover OCD vendors to establish calibration service hubs near Gujarat and Tamil Nadu greenfield sites.
- Spectroscopic ellipsometry-X-ray fluorescence convergence:Hybrid platforms combining thin-film thickness with elemental composition analysis unlock battery electrode and photovoltaic cell inspection verticals.
- Software unbundling from hardware:Machine-learning recipe optimization modules are migrating to standalone SaaS licenses, decoupling revenue from capital expenditure cycles.
Industry Challenges
- Electromagnetic simulation talent scarcity:Rigorous coupled-wave analysis expertise for scatterometry model development concentrates in legacy optics hubs, constraining vendor R&D scaling.
- Legacy fleet integration complexity:Pre-2018 stand-alone systems lack API compatibility with modern fab-wide MES architectures, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Critical Dimension (OCD) Measurements System Market |
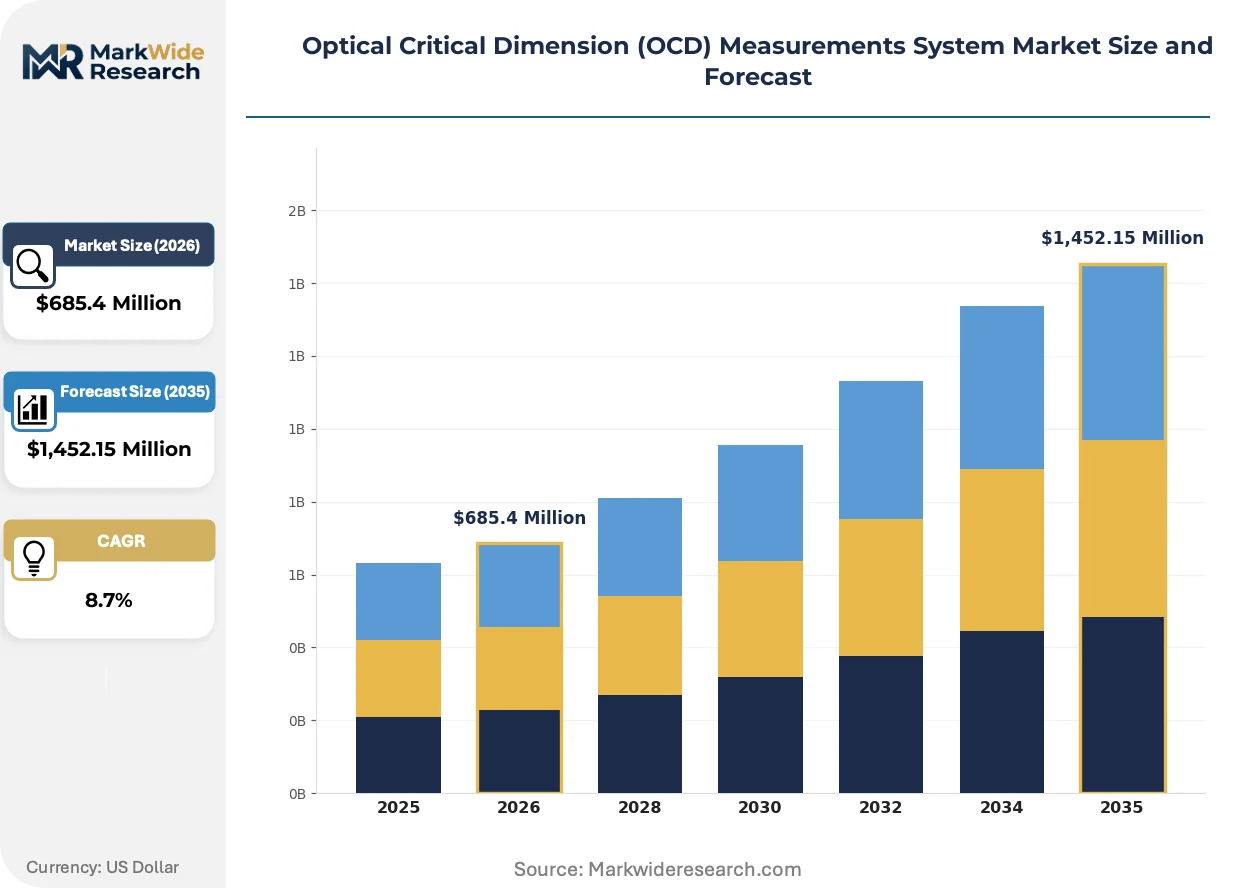
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Alone Systems, Integrated Systems, Software Solutions, Accessories Technology: Reflective Techniques, Diffractive Techniques, Scatterometry, Spectroscopy End User: Semiconductor Manufacturers, Research Institutions, Foundries, Electronics Companies Application: Wafer Inspection, Process Control, Defect Analysis, Thin Film Measurements |
| Companies Covered | Applied Materials Inc., Hitachi High-Tech Corporation, KLA Corporation, SCREEN Holdings Co. Ltd., Nikon Corporation, Onto Innovation, ASML Holding N.V., ZEISS Group, Nova Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Critical Dimension (OCD) Measurements System Market Trends and Innovations
Machine-learning inference at the measurement point is collapsing recipe optimization cycles, compressing the gap between raw spectral acquisition and actionable process adjustment. This shift restructures how fabs staff metrology engineering functions.
Polarized broadband reflectometry is absorbing computational lithography feedback loops, embedding inverse problem solvers directly on scatterometry controllers. Leading-edge foundries in Taiwan and South Korea are deploying these platforms for real-time etch depth correction. The technology is absorbing engineering headcount previously dedicated to offline model refinement, reallocating talent toward defect review automation.
REACH substance restrictions on optical coating precursors are forcing German and French suppliers to reformulate anti-reflective stack chemistries. ECHA authorization timelines now gate qualification schedules for new DUV objective assemblies. European equipment vendors are responding by accelerating in-house thin-film deposition capabilities to insulate against supply interruption.
Foundry procurement teams are consolidating metrology vendor panels from five-plus suppliers to two preferred partners per technology category. Taiwan Semiconductor Manufacturing Company and Samsung Foundry are piloting outcome-based calibration service contracts that tie payment to measurement uncertainty performance rather than uptime metrics. This model is compressing pricing transparency and shifting technical risk onto equipment suppliers.
Optical Critical Dimension (OCD) Measurements System Market Segmentation
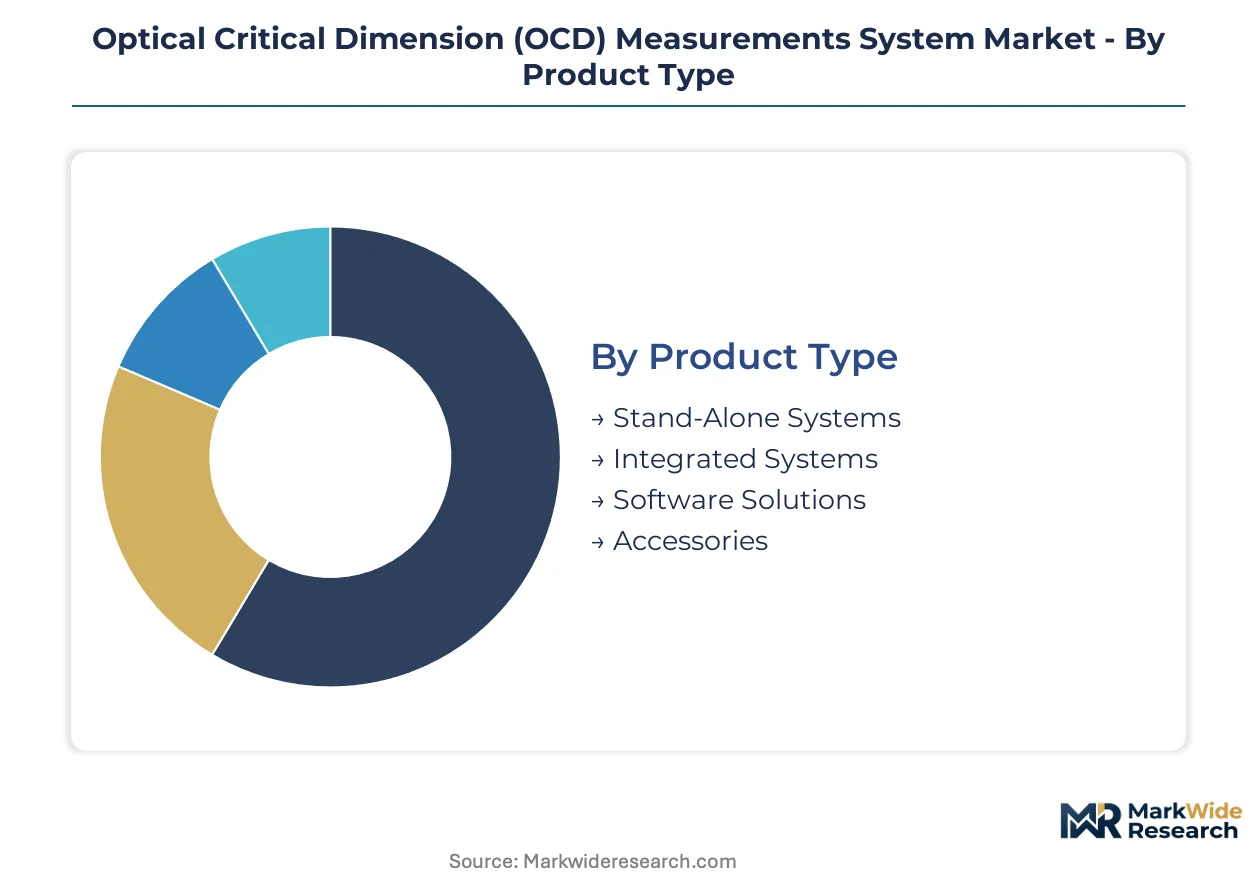
Segmentation in the OCD measurements system market reveals how capital allocation priorities diverge between leading-edge production and research environments. Equipment buyers sort offerings by integration depth, measurement physics, and the balance between throughput and resolution that their process nodes demand.
Product Type:
Upgrade and replacement cycles vary dramatically across product configurations, with stand-alone systems facing longer depreciation schedules than software modules that refresh annually.
- Stand-Alone Systems:Self-contained platforms housing complete optical benches, motion stages, and computational backends for high-precision linewidth metrology. Procurement concentrates at Taiwan Semiconductor Manufacturing Company and Samsung Foundry facilities in Hsinchu and Pyeongtaek as EUV node transitions force scatterometry refreshes every 3-4 years.
- Integrated Systems:Embedded modules within lithography and etch cluster tools, sharing vacuum interfaces and wafer handling robotics with process equipment. Demand clusters at Intel's Oregon and Arizona fabs where throughput-optimized inline monitoring reduces wafer queue times.
- Software Solutions:Machine-learning recipe optimization and spectral analysis packages licensed independently from hardware.
- Accessories:Objective lenses, calibration wafers, and source replacement components sustaining installed base performance.
Volume placements concentrate in Stand-Alone Systems; the faster expansion belongs to Software Solutions.
Technology:
Cost tier separation between techniques widens as compound semiconductor applications demand multi-physics measurement platforms.
- Scatterometry:Polarized broadband reflectometry capturing periodic grating signatures through rigorous coupled-wave analysis, delivering sub-nanometer linewidth resolution at production throughputs. Adoption concentrates at Samsung Foundry and Taiwan Semiconductor Manufacturing Company for 3nm gate-all-around process control where optical speed outweighs AFM precision.
- Spectroscopy:Spectroscopic ellipsometry measuring amplitude and phase changes across wavelength sweeps to extract thin-film thickness and optical constants. Demand is climbing fastest at GaN-on-SiC power device manufacturers where insulating substrates defeat electrical probe methods.
- Reflective Techniques:Normal-incidence reflectometry for rapid film thickness monitoring in high-volume DRAM production.
- Diffractive Techniques:Specialized angular-resolved scatterometry for 3D NAND staircase profile characterization.
Scatterometry captures the dominant share of new capital expenditure; spectroscopy is climbing the fastest as compound semiconductor packaging expands.
End User:
Customer type determines pricing tolerance and service contract structure, with foundries extracting performance-based terms unavailable to research buyers.
- Foundries:Pure-play and integrated semiconductor manufacturers operating at leading-edge nodes, consolidating vendor panels to two preferred metrology partners per technology category. Taiwan's Hsinchu Science Park cluster concentrates procurement authority as these buyers pilot outcome-based calibration contracts.
- Semiconductor Manufacturers:IDM operations with captive fab networks, typically negotiating enterprise-wide service agreements spanning multiple sites.
- Research Institutions:Universities and national laboratories prioritizing measurement flexibility over throughput, accepting slower recipe development cycles.
- Electronics Companies:Fabless design houses and OSATs accessing OCD capability through foundry partnerships or limited in-house packaging metrology.
Foundries drive the majority of annual procurement value; research institutions are expanding most quickly as EU and US semiconductor research initiatives fund new metrology infrastructure.
Application:
Application focus shapes sensor configuration and software module bundling, with process control commanding premium pricing over offline defect review.
- Process Control:Inline linewidth and profile monitoring feeding real-time feedback to lithography scanners and etch chambers, requiring sub-second measurement cycles and direct MES integration. Deployment concentrates at Samsung Foundry and Taiwan Semiconductor Manufacturing Company where EUV dose correction depends on scatterometry throughput.
- Wafer Inspection:Sampling-based critical dimension uniformity mapping across production lots, balancing statistical confidence against measurement cost.
- Thin Film Measurements:Thickness and optical property characterization for gate dielectrics, interconnect barriers, and advanced packaging redistribution layers.
- Defect Analysis:Offline review of excursion wafers combining OCD profile data with SEM imaging for root-cause determination.
Process Control commands the largest equipment budget allocation; Thin Film Measurements is gaining share fastest as 3D packaging architectures multiply film stack complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority for optical critical dimension measurement systems concentrates in East Asian foundry clusters, with secondary demand emerging from European equipment suppliers and North American research institutions responding to federal semiconductor initiatives.
Taiwan
Taiwan Semiconductor Manufacturing Company and Samsung Foundry drive scatterometry platform refreshes every 3-4 years as EUV nodes shrink below 3nm. The country's national development council prioritizes domestic metrology supply chain resilience through its semiconductor advancement program. Hsinchu Science Park anchors global procurement volume, with foundries piloting outcome-based calibration contracts that tie vendor payment to measurement uncertainty performance.
South Korea
Samsung Foundry and SK Hynix deploy polarized broadband reflectometry for real-time etch depth correction in gate-all-around process flows. METI-aligned standards cooperation with Japanese suppliers smooths DUV source hardware qualification. Pyeongtaek's semiconductor cluster concentrates capital expenditure authority, with leading-edge fabs absorbing engineering headcount previously dedicated to offline model refinement.
United States
Intel's Oregon and Arizona fabs drive integrated OCD system demand for throughput-optimized inline monitoring, while National Institute of Standards and Technology programs fund university metrology infrastructure. CHIPS and Science Act disbursements accelerate domestic foundry construction, elevating procurement timelines for stand-alone scatterometry platforms. Greater Phoenix and Hillsboro metropolitan areas concentrate IDM capital deployment as captive fab networks expand.
Germany
ZEISS and Trumpf anchor deep ultraviolet source hardware supply chains, exposing the European market to single-source fragility for critical optical components. REACH substance restrictions on anti-reflective coating precursors force reformulation of DUV objective assemblies, with ECHA authorization timelines gating new product qualifications. Dresden's Silicon Saxony cluster concentrates applied research demand as Fraunhofer institutes expand compound semiconductor packaging metrology programs.
Japan
Hitachi High-Tech and Nikon Corporation sustain domestic market presence through backward integration into source hardware and algorithm development. METI's semiconductor equipment subsidy programs support next-generation scatterometry R&D for sub-2nm node characterization. Yokohama and Kyoto metropolitan areas concentrate vendor engineering talent, with legacy optics hubs constraining rapid R&D scaling for rigorous coupled-wave analysis expertise.
Optical Critical Dimension (OCD) Measurements System Market Competitive Landscape
US and Japanese producers anchor one tier; Dutch and German specialists hold positions in lithography-integrated and optical component supply chains. The vendor base concentrates around three strategic archetypes: diversified semiconductor equipment conglomerates with captive metrology portfolios, pure-play optical measurement specialists, and lithography system integrators embedding OCD modules. Consolidation pressure intensifies as foundries narrow vendor panels from five-plus suppliers to two preferred partners per technology category. Geographic expansion and strategic partnerships represent the dominant competitive moves, with India PLI scheme incentives attracting calibration service hub establishment.
Within the diversified equipment tier, Applied Materials Inc. and KLA Corporation exemplify scale-driven positioning through installed base leverage and service revenue capture. Nova Ltd. occupies a specialist position emphasizing thin-film measurement modules for advanced packaging applications. Among lithography-integrated players, ASML Holding N.V. and ZEISS Group represent the optical component and system integration archetype, with the latter anchoring DUV objective supply chains. These three company groupings illustrate how competitive positioning fragments across technology integration depth rather than geographic origin alone.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| Hitachi High-Tech Corporation |
| KLA Corporation |
| SCREEN Holdings Co. Ltd. |
| Nikon Corporation |
| Onto Innovation |
| ASML Holding N.V. |
| ZEISS Group |
| Nova Ltd. |
| Others |
Pricing and Supply Chain Analysis
EUV node shrinkage below 3nm is simultaneously compressing equipment margins and concentrating procurement leverage among Taiwan's Hsinchu Science Park foundries. This dual pressure reshapes how vendors structure hardware-software bundles and source critical optical subsystems.
Pricing Analysis
Volume placements concentrate in stand-alone scatterometry platforms where foundries extract outcome-based terms, while software solutions capture expanding margins through SaaS-tiered licensing for machine-learning recipe optimization. Price differentiation hinges on ISO 17025 accreditation tier and the depth of after-sales calibration service bundling. Pricing pressure stems from vendor panel consolidation as TSMC and Samsung narrow preferred supplier lists to two partners per technology category. Research institutions exhibit highest price sensitivity due to grant-funded capital cycles, whereas leading-edge foundries prioritize measurement uncertainty performance over unit cost.
Supply Chain Analysis
Deep ultraviolet source hardware rests on German laser specialists and Japanese broadband lamp manufacturers, creating single-source vulnerability for critical optical components. German and Japanese suppliers anchor objective lens and illumination system production, while Taiwanese foundries concentrate downstream demand. Supply chain risk crystallizes around REACH substance restrictions on anti-reflective coating precursors, which gate ECHA authorization timelines for new DUV objective assemblies. Distribution runs through direct vendor-foundry relationships with embedded field service engineers, bypassing traditional equipment distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as electromagnetic simulation talent scarcity and rising compliance overhead squeeze mid-tier vendors without captive optical component supply.
For Market Incumbents: Anchor service revenue through outcome-based calibration contracts that tie payment to measurement uncertainty performance rather than uptime metrics. Deepen backward integration into source hardware to insulate against German and Japanese component supply fragility, while embedding interpretable machine-learning models to satisfy EU AI Act algorithmic transparency mandates. For New Entrants and Emerging Players: Cloud-based recipe optimization platforms offer the most penetrable entry vector, decoupling revenue from capital expenditure cycles and targeting research institutions expanding under US and EU semiconductor research initiatives. Focus initial deployment on spectroscopic ellipsometry modules for GaN-on-SiC power device manufacturers where legacy electrical probe methods fail. For Investors and Strategic Acquirers: Re-rating potential sits with specialized thin-film measurement module developers given compound semiconductor packaging expansion and 3D NAND staircase profile characterization demand. Long-term viability favors vendors with ISO 17025-accredited installed bases and software unbundling capability. Watch for India PLI scheme disbursement timing as a signal for calibration service hub establishment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DUV Source Hardware | ZEISS and Trumpf concentration creates vulnerability for vendors lacking captive optical component supply. |
| Machine-Learning Recipe Optimization SaaS | EU AI Act mandates accelerate upgrade cycles across installed scatterometry bases. |
| Calibration Service Hub Geographic Expansion | India PLI scheme incentives attract first-mover establishment near Gujarat greenfield sites. |
| Hybrid Spectroscopic Ellipsometry-XRF Platform Development | Battery electrode and photovoltaic inspection verticals unlock beyond-semiconductor demand. |
| Outcome-Based Service Contract Piloting | TSMC and Samsung procurement teams pilot payment tied to measurement uncertainty performance. |
Research Methodology
Document review covered SEC 10-K filings, METI equipment subsidy disclosures, and ECHA authorization timelines, complemented by interviews with fab metrology engineering directors, semiconductor equipment procurement leads, and optical component R&D heads. Secondary validation drew from Taiwan's national development council semiconductor advancement program reports, Fraunhofer institute compound semiconductor packaging studies, and CHIPS Act disbursement tracking. Bottom-up unit placement estimates triangulated against top-down foundry capital expenditure disclosures.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through structured modeling of equipment refresh cycles and software attach rates. CAGRs were derived from regression analysis of historical node transition timelines correlated with scatterometry platform replacement frequencies. Industry-specific inputs included EUV lithography roadmap milestones, REACH substance restriction phase-in schedules, and foundry vendor panel consolidation patterns.
The model holds under continued EUV node shrinkage and stable REACH authorization timelines; deviation in German-Japanese source hardware supply or abrupt ECHA restriction expansion would shift equipment availability and pricing assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Global Reflux Testing Products Market