

E-Axle and Inverter Efficiency and Reliability Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
E-Axle and Inverter Efficiency and Reliability Test Platforms Market Insights
Commercial vehicle electrification is expanding faster than passenger car applications, pulling test platform procurement toward heavy-duty cycle validation. AVL List GmbH dominates powertrain test cell integration across European truck OEMs. HORIBA sustains its position through geographic breadth in Asian automotive corridors. Siemens leverages digital twin architectures to anchor software-intensive validation workflows.
E-axle and inverter efficiency and reliability test platforms comprise dynamometer systems, thermal cycling chambers, and power electronics load simulators that subject integrated motor-inverter units to torque ripple, efficiency mapping, and accelerated life protocols. These systems verify that silicon carbide inverter switching losses and e-axle gear mesh efficiencies meet OEM durability thresholds before production release. Hardware-in-the-Loop configurations lead current installations because they compress development cycles by embedding physical controllers within virtual drivetrain environments. Combined Test Systems represent the fastest-growing product category as OEMs consolidate inverter and e-axle validation into single-cell architectures to reduce capital footprint and thermal conditioning redundancy.
The EPA, EU Green Deal, and China's MIIT each enforce distinct efficiency benchmarking and emissions accountability frameworks that shape test platform specification requirements. NHTSA safety protocols and ISO 26262 functional safety standards further mandate traceable reliability documentation across validation workflows. Stakeholders must monitor how regulatory divergence between North American, European, and Chinese efficiency certification protocols influences test platform configurability and software localization investments.
Market Dynamics
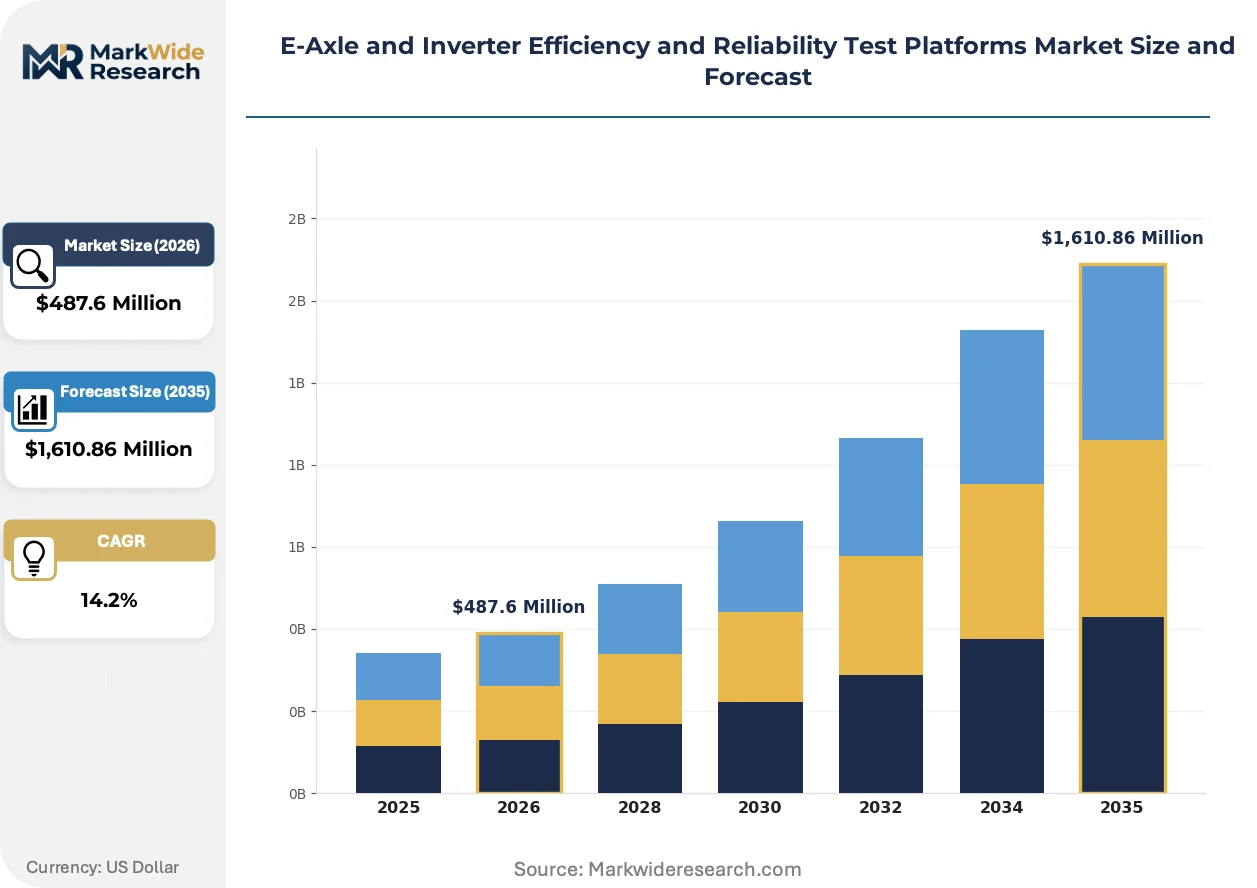
The convergence of silicon carbide inverter adoption and heavy-duty commercial vehicle electrification is compressing validation timelines and forcing test platform architectures toward higher power density and integrated thermal management.
Growth Catalysts
- EPA Heavy-Duty Greenhouse Gas Standards:Phase 3 mandates require OEMs to document powertrain efficiency across real-world duty cycles, expanding procurement of dynamometer-based validation cells.
- Silicon carbide semiconductors:Wider bandgap switching frequencies demand upgraded thermal cycling protocols that legacy IGBT test benches cannot replicate.
- German engineering clusters:Dense concentrations of Tier-1 suppliers around Stuttgart and Munich sustain concentrated demand for combined e-axle and inverter test systems.
Market Restraints
- Copper and rare-earth magnet volatility:Motor-inverter unit production costs fluctuate with dysprosium and terbium prices, deterring capital commitments to validation infrastructure.
- Single-source dependency for high-speed dynamometers:European and Japanese suppliers control precision torque measurement subassemblies, creating procurement bottlenecks.
- ISO 26262 functional safety certification:Traceability requirements extend validation documentation timelines by 8-14 months for new platform installations.
Strategic Opportunities
- India PLI scheme for automotive:Domestic e-axle manufacturing incentives create untapped demand for localized test platform deployment and service networks.
- Battery-electric bus retrofit programs:Municipal fleet operators in Brazil and Mexico require validation equipment for remanufactured powertrains.
- Hardware-in-the-Loop convergence with cloud-based data lakes:Real-time efficiency mapping across distributed test cells enables predictive maintenance subscription models.
Industry Challenges
- Power electronics firmware integration:Embedded control algorithms for SiC gate drivers require specialized validation engineers that OEM test departments lack.
- Multi-physics simulation alignment:Thermal-electromagnetic-mechanical co-simulation accuracy gaps force physical prototype iterations that digital twins promised to eliminate.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Axle and Inverter Efficiency and Reliability Test Platforms Market Trends and Innovations
Test platform architecture is pivoting from discrete inverter and e-axle validation toward unified cells that compress capital deployment and thermal conditioning redundancy. This structural shift reshapes supplier R&D priorities and buyer specification templates simultaneously.
Silicon carbide MOSFET-based inverter test benches are integrating high-frequency switching loss measurement with real-time thermal impedance tracking. Tier-1 powertrain suppliers in Germany and Japan are adopting these configurations within 18-month procurement cycles. The technology is integrating electromagnetic interference validation directly into efficiency mapping protocols, eliminating separate EMC chamber bookings.
The EU Green Deal's carbon border adjustment mechanism is forcing non-European OEMs to document lifecycle emissions from test energy consumption. Industrial consequence: test cell operators must now meter and report grid electricity carbon intensity alongside powertrain efficiency metrics. Heavy-duty commercial vehicle programs face the steepest compliance burden, driving demand for regenerative dynamometer systems that return test energy to facility grids.
Buyer specification processes now prioritize outcome-based validation service contracts over capital equipment purchases. Fleet operators and startup OEMs in Southeast Asia are displacing traditional equipment financing with per-test-hour pricing models. South Korean automotive groups lead this transition, outsourcing entire validation programs to test service bureaus equipped with multi-client shared infrastructure.
E-Axle and Inverter Efficiency and Reliability Test Platforms Market Segmentation
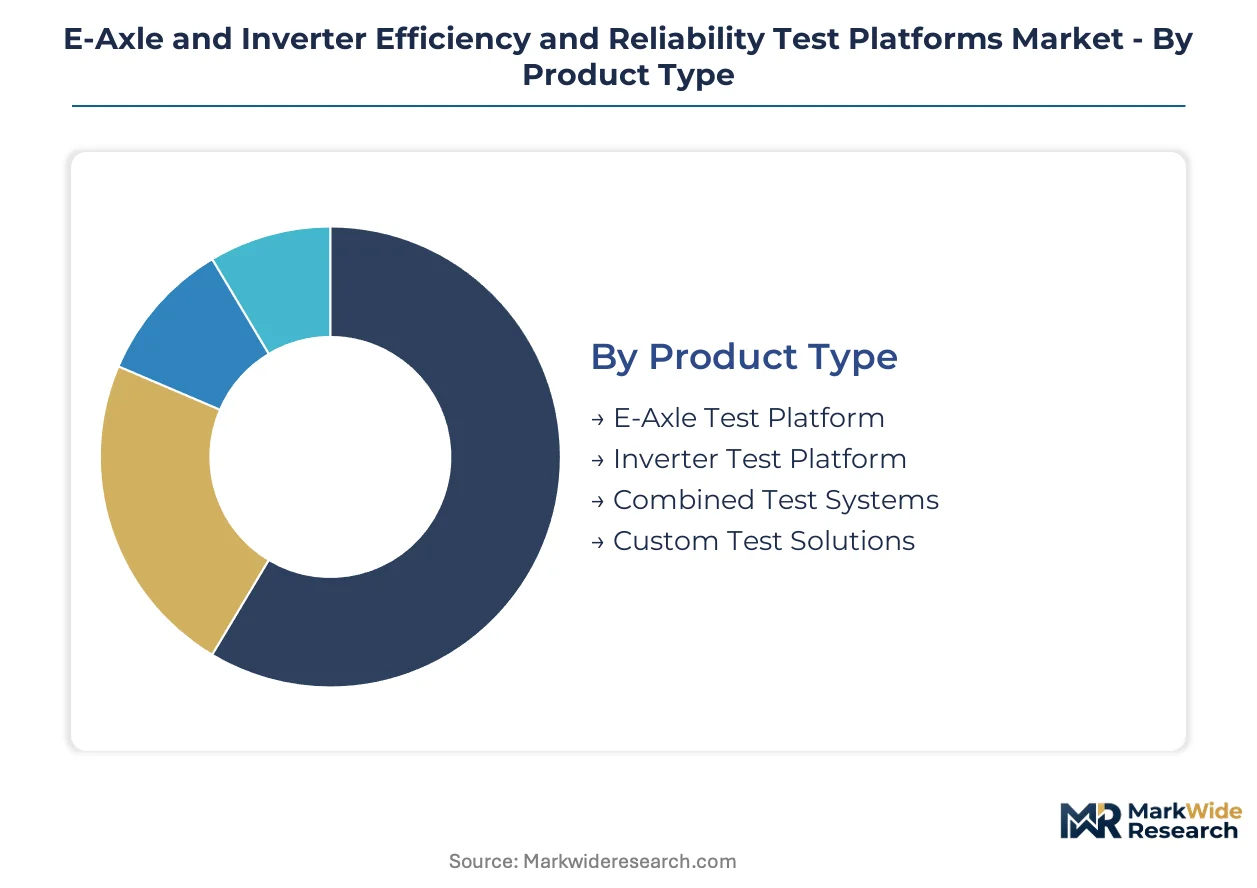
Test platform segmentation reflects divergent integration strategies across the electrification value chain. Procurement patterns split between standalone validation cells for discrete components and unified architectures that compress capital deployment.
Product Type:
Integration depth varies sharply: standalone platforms serve discrete validation workflows while combined systems eliminate redundant thermal conditioning infrastructure.
- Combined Test Systems:Unified cells consolidate e-axle dynamometry with inverter power cycling in single thermal envelopes. German OEM engineering clusters around Stuttgart specify these configurations to reduce facility footprint and synchronize validation timelines for integrated motor-inverter units.
- E-Axle Test Platform:Dedicated dynamometer cells subject gear mesh assemblies to torque ripple characterization and efficiency mapping across full load-speed envelopes. Demand concentrates with heavy-duty commercial vehicle programs where axle load ratings exceed passenger car thresholds by 4-6x.
- Inverter Test Platform:Power electronics load simulators verify silicon carbide switching losses and thermal impedance for discrete inverter modules.
- Custom Test Solutions:Bespoke architectures address proprietary motor-inverter interfaces or non-standard voltage bus configurations.
E-Axle Test Platforms lead volumes today; Combined Test Systems are gaining share fastest.
Technology:
Cost tiers separate capital-intensive physical test cells from software-centric validation layers that reduce hardware dependency.
- Hardware-in-the-Loop:Physical controllers embed within virtual drivetrain environments, compressing development cycles by enabling fault injection without mechanical prototype risk. AVL List GmbH and HORIBA dominate European installations of these configurations for commercial vehicle powertrain validation.
- Real-Time Simulation:Sub-millisecond latency execution of motor-inverter co-simulation enables closed-loop efficiency optimization during controller calibration. South Korean automotive groups outsource entire validation programs to service bureaus equipped with multi-client shared infrastructure based on this technology.
- Software-in-the-Loop:Pure virtual validation of control algorithms precedes hardware commitment.
- Automated Diagnostic Tools:Self-configuring test sequences reduce operator intervention for repetitive reliability protocols.
- Power Electronics Simulation:Circuit-level switching loss prediction supports inverter topology selection.
Hardware-in-the-Loop leads volumes today; Real-Time Simulation is climbing the fastest.
Application:
Customer type stratification separates high-volume automotive procurement from specialized industrial and aerospace requirements.
- Commercial Vehicles:Heavy-duty cycle validation demands extended thermal soak protocols and regenerative braking energy recovery measurement. EPA Phase 3 greenhouse gas standards mandate documented efficiency across real-world duty cycles, expanding procurement of dynamometer-based validation cells for truck and bus powertrains.
- Electric Vehicles:Passenger car programs prioritize compact e-axle packaging validation and NVH characterization for mass-market deployment.
- Off-Road Machinery:Mining and construction equipment requires dust-ingress testing alongside powertrain efficiency verification.
- Industrial Equipment:Material handling and stationary power applications specify lower rotational speed envelopes.
- Aerospace Components:Aviation-grade reliability documentation under DO-178C and DO-254 drives specialized test traceability.
Electric Vehicles lead volumes today; Commercial Vehicles show the steepest expansion trajectory.
End User:
Supply concentration among precision dynamometer subassembly vendors shapes procurement bottlenecks across end user categories.
- Tier-1 Suppliers:Powertrain integrators require flexible test cells capable of serving multiple OEM programs simultaneously. Dense concentrations around Munich and Stuttgart sustain concentrated demand for combined e-axle and inverter test systems with rapid reconfiguration capabilities.
- OEM Engineering Teams:Captive validation departments prioritize traceable documentation for regulatory submission.
- Testing Laboratories:Independent facilities serve startup OEMs and fleet operators with per-test-hour pricing models.
- Research Institutes:Academic and government labs focus on pre-competitive efficiency benchmarking and standard development.
- Quality Assurance Departments:Production-line validation requires high-throughput screening with reduced test duration.
OEM Engineering Teams lead volumes today; Testing Laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting test platform procurement toward jurisdictions where efficiency certification costs and timeline risks diverge most sharply. Manufacturers now site validation infrastructure where EPA, EU Green Deal, or MIIT compliance burdens align with local subsidy regimes.
Germany
Stuttgart and Munich engineering clusters sustain Europe's densest concentration of combined e-axle and inverter test systems. KBA enforcement of EU Green Deal efficiency documentation drives Tier-1 suppliers toward regenerative dynamometer configurations. Bavarian test facilities now meter grid carbon intensity alongside powertrain metrics to satisfy emerging carbon border adjustment protocols.
United States
EPA Phase 3 heavy-duty greenhouse gas standards are expanding dynamometer cell procurement across Michigan and Ohio automotive corridors. Commercial vehicle electrification programs in these states require documented efficiency across real-world duty cycles. Detroit-area engineering teams prioritize Hardware-in-the-Loop configurations that compress development timelines for silicon carbide inverter validation.
China
MIIT efficiency benchmarking frameworks and dual carbon goals are accelerating test platform deployment in Shanghai and Guangzhou manufacturing hubs. Domestic e-axle producers require localized validation infrastructure to avoid certification delays for export-bound powertrains. Yangtze River Delta clusters now specify combined thermal cycling and efficiency mapping cells that legacy IGBT benches cannot replicate.
Japan
METI technology roadmaps for wide bandgap semiconductors are reshaping inverter test specifications in Nagoya and Tokyo industrial zones. Precision torque measurement subassembly procurement bottlenecks from domestic suppliers constrain platform deployment timelines. Chubu region automotive groups outsource validation programs to service bureaus equipped with multi-client shared infrastructure.
India
PLI scheme incentives for domestic e-axle manufacturing are creating untapped demand for localized test platform deployment in Maharashtra and Tamil Nadu. BIS efficiency standards for commercial vehicle electrification remain in draft, prompting OEMs to pre-position validation capacity ahead of regulatory finalization. Chennai automotive corridors see concentrated procurement of combined test systems from European suppliers establishing service networks.
E-Axle and Inverter Efficiency and Reliability Test Platforms Market Competitive Landscape
Strategic partnerships dominate the current landscape as test platform suppliers anchor software-intensive validation workflows through digital twin alliances. The vendor base concentrates among precision dynamometer integrators and power electronics simulation specialists, with mid-tier players occupying modular subsystem niches. Three archetypes prevail: full-stack test cell integrators, Hardware-in-the-Loop software platforms, and specialized thermal cycling chamber fabricators. M&A activity and technology licensing agreements represent the dominant competitive vectors as incumbents acquire SiC gate driver firmware capabilities.
Within the full-stack integrator tier, AVL List GmbH and HORIBA exemplify European engineering-centric positioning, while Siemens occupies a position bridging industrial automation with automotive validation. These anchors represent distinct geographic and technological archetypes: Graz-based GmbH structures dominate powertrain test cell integration, Japanese precision instrument groups sustain Asian corridor penetration, and German industrial conglomerates leverage digital twin architectures to anchor software-intensive workflows.
| Leading Market Players |
|---|
| AVL List GmbH |
| HORIBA |
| dSPACE |
| NI |
| ATESTEO |
| Schenck RoTec |
| IPG Automotive |
| Siemens |
| Intertek |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer costs cascade through test platform pricing tiers, with Japanese and German precision subassembly suppliers commanding premium positioning for high-speed dynamometer torque measurement systems while Indian and Chinese integrators compete on thermal cycling chamber volume.
Pricing Analysis
Distributor margins for European precision dynamometer subassemblies compress final pricing by 15-20 points before reaching OEM engineering teams. Three-tier pricing structure across premium certified, standard validated, and economy unbundled levels separates Tier-1 suppliers seeking ISO 26262 traceability from municipal fleet operators prioritizing per-test-hour outsourcing. Pricing pressure stems from rare-earth magnet volatility in motor-inverter units, which deters capital commitments and pushes buyers toward leasing models. Startup OEMs in Southeast Asia exhibit highest price sensitivity, while German automotive groups absorb premiums for combined test system integration.
Supply Chain Analysis
Refurbishment flows for dynamometer cells concentrate in Stuttgart and Munich service hubs, extending asset lifecycles for Tier-1 suppliers managing multi-OEM programs. Geographic supply concentration centers on Germany, Japan, and China for precision torque measurement subassemblies, power electronics load simulators, and thermal cycling chamber fabricators. Raw material dependencies include copper windings, rare-earth magnets, and silicon carbide substrates. Single-source vulnerability for high-speed dynamometer subassemblies creates procurement bottlenecks when Japanese suppliers face capacity constraints. Distribution runs through direct OEM relationships for full-stack integrators and regional service bureaus for modular subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as commercial vehicle electrification mandates from EPA Phase 3 and EU Green Deal force continuous validation infrastructure refresh cycles across heavy-duty powertrain programs.
For Market Incumbents: Deploy digital twin software licensing to anchor recurring revenue streams against hardware commoditization pressure from emerging Asian test cell integrators. Deepen backward integration into SiC gate driver firmware capabilities through targeted technology licensing agreements. Fortify Stuttgart and Munich service networks to capture Tier-1 supplier consolidation of inverter and e-axle validation into single-cell architectures. For New Entrants and Emerging Players: Launch via cloud-based Hardware-in-the-Loop subscription models targeting Southeast Asian startup OEMs displaced from capital equipment financing. Penetrate India's Maharashtra and Tamil Nadu corridors ahead of BIS efficiency standard finalization, offering localized thermal cycling and efficiency mapping cells. Anchor go-to-market through per-test-hour pricing partnerships with municipal fleet operators in Brazil and Mexico pursuing battery-electric bus retrofit programs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier modular subsystem vendors lack SiC switching loss measurement IP and face margin compression from full-stack integrators. Long-term viability favors platforms with embedded predictive maintenance subscriptions tied to real-time efficiency mapping across distributed test cells. Target acquisition archetype: European precision dynamometer specialists with captive torque measurement subassembly technology. Monitor India PLI scheme disbursement velocity and EPA Phase 3 enforcement timeline as inflection signals for validation infrastructure deployment cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens anchors software-intensive validation workflows through virtual drivetrain environment licensing. |
| Backward Integration into SiC Firmware | Test cell integrators acquire gate driver control algorithm capabilities to reduce OEM engineering dependency. |
| Geographic Manufacturing Footprint Expansion | European suppliers establish Chennai service networks to capture India PLI scheme e-axle manufacturing incentives. |
| Hardware-in-the-Loop Convergence with Cloud Data Lakes | Real-time efficiency mapping enables predictive maintenance subscription models across distributed test cells. |
| Regenerative Dynamometer System Deployment | EU Green Deal carbon border adjustment mechanisms force test facilities to meter and report grid electricity carbon intensity. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket service heads; secondary validation through SEC filings, vehicle production databases, and IHS Markit registration data; and technical specification reviews — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates for combined test systems, e-axle platforms, and inverter validation cells.
Historical shipment patterns for dynamometer cells and power electronics load simulators were cross-referenced against panel input from test service bureau operators and thermal cycling chamber fabricators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product integration depth, technology layer, vehicle class, propulsion architecture, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle compression for silicon carbide inverter validation protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT efficiency benchmarking acceleration or rare-earth magnet supply disruption scenarios. Practitioners should monitor EPA Phase 3 enforcement stringency and EU Green Deal carbon border adjustment implementation timelines for early signals of validation infrastructure procurement cadence shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.