
 Blockchain Payments Software Market | 2026-2036
Blockchain Payments Software Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Payments Software Market Insights
Market Context
Modular wallet-and-gateway bundling is consolidating buyer procurement decisions across enterprise segments. Circle leverages its regulated stablecoin infrastructure to anchor compliance-first positioning in institutional corridors. Ripple competes through pre-funded liquidity networks that reduce correspondent banking friction for cross-border settlements. JPMorgan Chase Onyx dominates wholesale payment tokenization via its blockchain-based repo and intraday settlement rails.
Technical Definition and Segments
Blockchain payments software comprises cryptographic transaction protocols, distributed ledger nodes, and consensus-driven settlement engines that enable peer-to-peer value transfer without intermediary reconciliation, typically processing throughput between thousands and tens of thousands of transactions per second depending on layer-one architecture. Payment gateways and smart contracts capture expanding margin pools as enterprises automate programmable settlement logic, while wallet solutions sustain baseline demand from retail and merchant onboarding. Cloud deployment configurations lead volume adoption among mid-market retailers seeking elastic infrastructure, though hybrid architectures gain traction among financial institutions managing sensitive key custody on-premises while routing transactions through public chain validators.
Regulatory Frame
The EU's MiCA framework, the US SEC and CFTC oversight of payment tokens, and Singapore's Monetary Authority licensing regime collectively shape product roadmaps, capital reserve requirements, and market access conditions for blockchain payment providers. Compliance with these overlapping standards forces software vendors to embed real-time transaction monitoring, geographic access controls, and audit-grade reporting into core architecture. Stakeholders must monitor how divergent stablecoin reserve rules across jurisdictions fragment liquidity pools and determine whether to architect single-tenant compliance stacks or pursue modular regional deployments.
Market Dynamics
Cross-border settlement latency is compressing as financial institutions abandon correspondent banking rails for distributed ledger infrastructure, forcing software vendors to embed real-time compliance monitoring into core transaction protocols.
Growth Catalysts
- MiCA Reserve Standards:The EU's uniform stablecoin reserve requirements eliminate jurisdictional arbitrage for payment token issuers, accelerating institutional deployment across European banking corridors.
- Merchant Onboarding Automation:Smart contract-based KYC pipelines reduce onboarding friction for retail payment gateways, expanding addressable merchant bases in high-velocity commerce verticals.
- Singapore Licensing Regime:The Monetary Authority of Singapore's digital payment token framework attracts infrastructure providers seeking regulatory clarity, concentrating APAC hub development in the city-state.
Market Restraints
- Validator Concentration Risk:Layer-one consensus relies on a limited set of staking providers, creating single-point-of-failure exposure for settlement finality guarantees.
- Energy Input Volatility:Proof-of-work validation remains economically sensitive to electricity price fluctuations, constraining margin stability for mining-dependent payment networks.
- Interoperability Friction:Absent universal messaging standards, liquidity fragments across isolated blockchain ecosystems, forcing costly bridge infrastructure investments.
Strategic Opportunities
- Programmable Settlement Convergence:Smart contract oracles integrating real-world payment triggers with IoT sensor data unlock automated supply chain finance applications.
- India UPI-Blockchain Bridges:The country's real-time retail payment network presents white-space potential for rupee-denominated stablecoin settlement layers.
- Carbon-Attributed Transaction Fees:Environmental disclosure mandates under EU CSRD create demand for emissions-tracked payment routing as a differentiated service tier.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge proof engineering and secure multi-party computation expertise remains concentrated among a limited pool of specialists, inflating R&D compensation costs.
- Legacy Core Integration:Mainframe banking systems require expensive middleware abstraction layers to interface with blockchain settlement rails, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Payments Software Market |
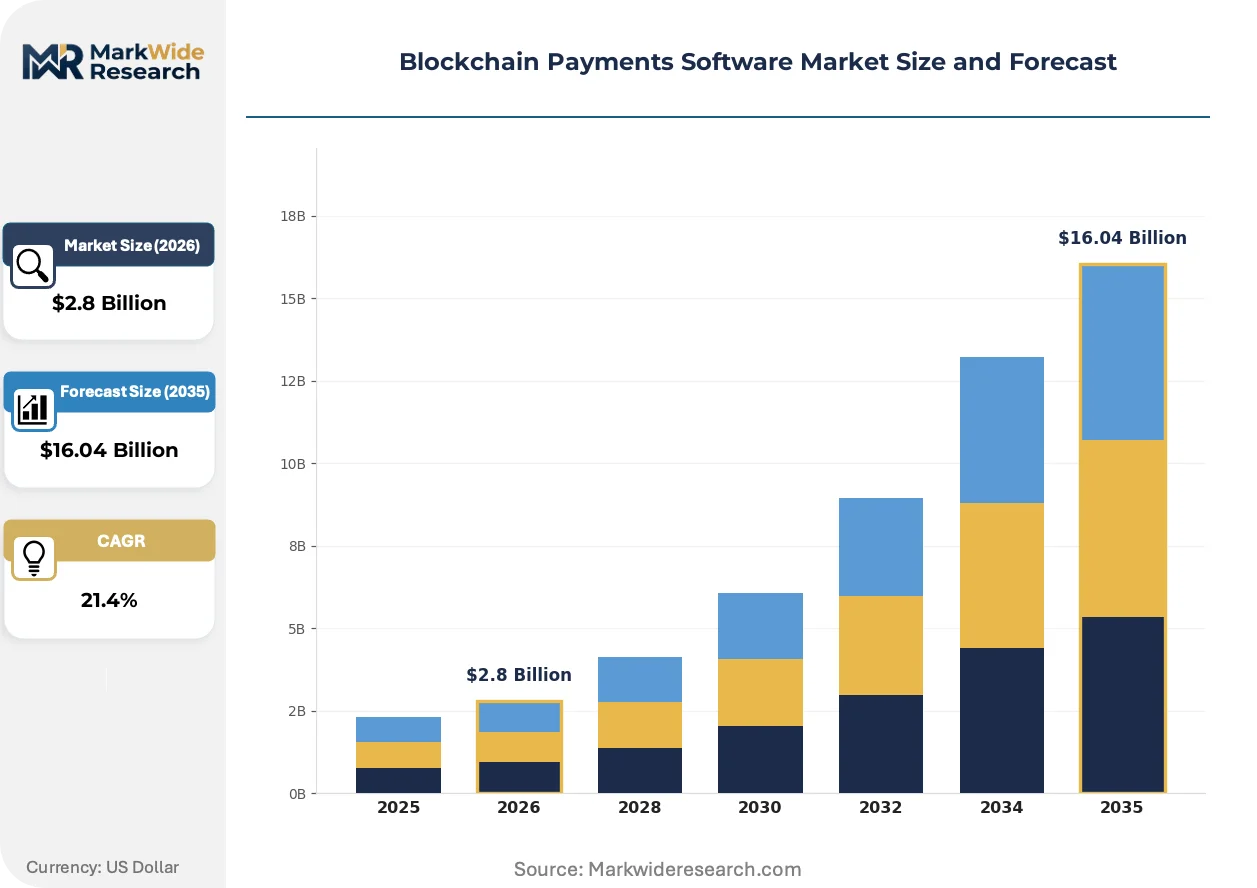
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Wallets, Payment Gateways, Smart Contracts, Remittance Services Deployment: Cloud, On-Premises, Hybrid, Multi-Chain End User: Retailers, Financial Institutions, E-Commerce Platforms, Service Providers Technology: Cryptography, Distributed Ledger, Consensus Mechanism, Tokenization |
| Companies Covered | BVNK, Circle, Ripple, BitPay, Coinbase, Mastercard Blockchain, Stellar, Veem, JPMorgan Chase Onyx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Payments Software Market Trends and Innovations
Payment infrastructure is converging around programmable money primitives that embed compliance logic directly into transaction execution, eliminating post-hoc reconciliation and enabling atomic settlement finality.
Account abstraction standards are unifying wallet interfaces across Ethereum-compatible chains, enabling gasless transaction sponsorship and social recovery mechanisms. Retail payment platforms are adopting these standards to reduce user friction in onboarding flows. This unification is compressing the technical barrier between custodial and self-custodial payment experiences, forcing gateway providers to differentiate on compliance services rather than key management.
REACH chemical substance tracking mandates in Europe are extending to payment hardware supply chains, requiring blockchain-based provenance documentation for point-of-sale devices containing conflict minerals. Industrial consequences include mandatory supplier audit trails and embedded carbon footprint disclosures. Payment terminal manufacturers serving EU markets are responding by integrating distributed ledger traceability modules into procurement systems.
Enterprise treasury departments are consolidating vendor relationships around bundled wallet-gateway-compliance stacks, displacing point-solution procurement. Financial institutions with complex multi-currency operations are driving this consolidation, seeking unified SLA accountability. This pattern is most visible in Singapore and Switzerland, where regulatory clarity has enabled integrated platform licensing.
Blockchain Payments Software Market Segmentation
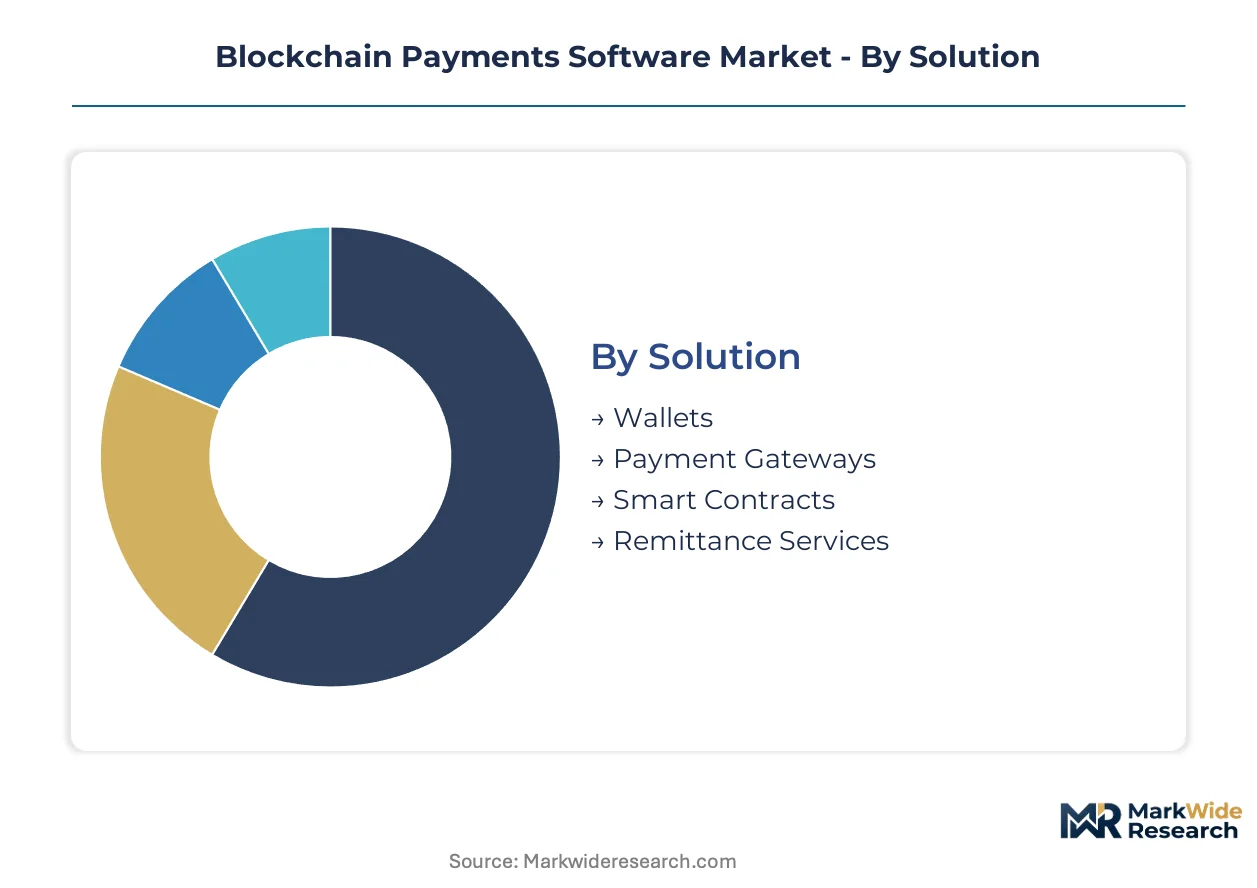
Payment software segmentation reveals how infrastructure choices map to operational complexity. Procurement patterns diverge sharply between embedded compliance stacks and standalone gateway deployments.
Solution:
Integration depth varies from embedded wallet modules to standalone settlement engines requiring custom middleware.
- Payment Gateways:These protocols route transactions between fiat and blockchain rails, embedding real-time KYC checks at the API layer. Demand clusters among Southeast Asian e-commerce platforms automating cross-border merchant payouts under Singapore's licensing regime.
- Wallets:Cryptographic key management interfaces span custodial enterprise vaults and self-custodial mobile applications. Financial institutions in Switzerland favor multi-signature institutional wallets with hardware security module integration for treasury operations.
- Smart Contracts:Programmable settlement logic automates escrow, streaming payments, and conditional releases.
- Remittance Services:Cross-border value transfer applications leverage stablecoin corridors to bypass correspondent banking delays.
Volume placements concentrate in Payment Gateways; the faster expansion belongs to Smart Contracts.
Deployment:
Cost tier separation distinguishes elastic consumption models from capital-intensive infrastructure ownership.
- Cloud:Elastic compute configurations enable mid-market retailers to scale transaction throughput without hardware procurement. German payment processors favor cloud deployments to satisfy EU data residency requirements under GDPR while minimizing upfront capital expenditure.
- Hybrid:Split architectures route sensitive key custody through on-premises hardware while pushing transaction validation to public chain nodes. Japanese banks deploy hybrid models to maintain METI-compliant audit trails for wholesale settlement operations.
- On-Premises:Dedicated infrastructure serves institutions with strict data sovereignty mandates or classified transaction processing requirements.
- Multi-Chain:Orchestration layers abstract interoperability across Ethereum, Solana, and permissioned enterprise ledgers.
Cloud configurations dominate current procurement volumes; Hybrid architectures are climbing the fastest as regulatory clarity emerges.
End User:
Application complexity escalates from consumer-facing checkout optimization to institutional treasury automation.
- Financial Institutions:Wholesale banking departments deploy blockchain rails for intraday repo settlement and cross-border correspondent alternatives. JPMorgan's Onyx platform exemplifies how tier-one banks tokenize traditional assets on permissioned infrastructure.
- E-Commerce Platforms:Marketplace operators integrate crypto checkout options to reduce chargeback exposure and access underbanked customer segments. Latin American platforms drive adoption to circumvent volatile local currency settlements.
- Retailers:Point-of-sale and online merchants seek reduced interchange fees through direct blockchain payment acceptance.
- Service Providers:Payroll, invoicing, and B2B payment platforms embed settlement infrastructure as a competitive differentiator.
Financial Institutions anchor current infrastructure investment; E-Commerce Platforms are gaining share fastest through API-first integration models.
Technology:
Maturity gradients separate proven cryptographic primitives from emerging consensus innovations still proving production reliability.
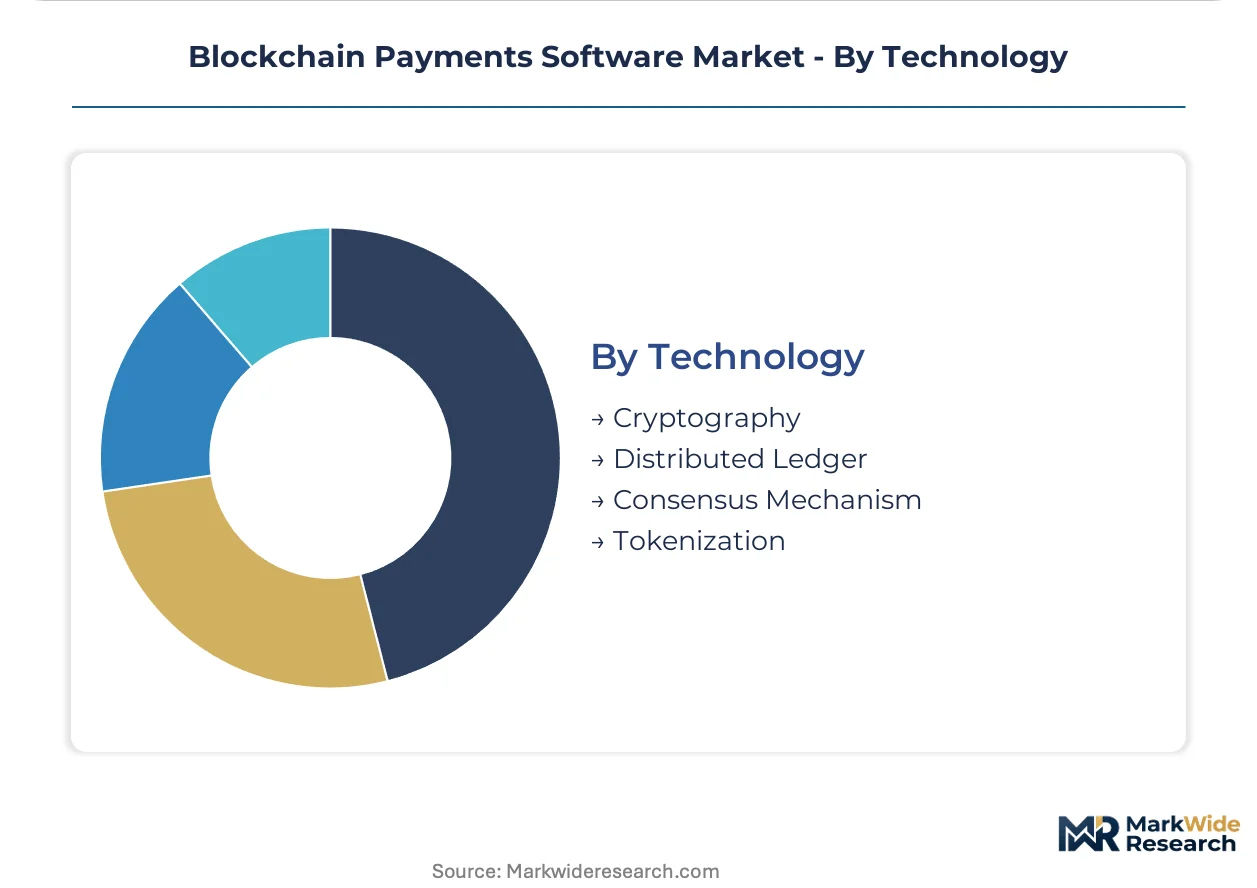
- Distributed Ledger:Immutable record-keeping architectures span public permissionless networks and private consortium chains. Singapore's licensed digital payment token providers predominantly build on distributed ledger foundations to satisfy Monetary Authority audit requirements.
- Tokenization:Asset representation standards convert real-world value into programmable digital instruments. Swiss banks leverage tokenization for fractionalized precious metal custody and automated dividend distribution.
- Cryptography:Zero-knowledge proofs, multi-party computation, and post-quantum algorithms secure transaction confidentiality and signature integrity.
- Consensus Mechanism:Proof-of-stake, Byzantine fault tolerance, and delegated validation protocols determine settlement finality guarantees and energy consumption profiles.
Distributed Ledger foundations support the majority of production deployments; Tokenization layers show the steepest expansion trajectory as real-world asset migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Singapore while institutional adoption spreads through European banking corridors and Asian financial hubs. Production of blockchain payment infrastructure clusters around regulatory clarity rather than raw market size.
United States
Institutional treasury departments at JPMorgan Chase and regional banks drive wholesale payment tokenization demand. The SEC and CFTC maintain overlapping oversight of payment tokens, forcing vendors to architect dual-compliance stacks. New York and San Francisco host the densest concentration of wallet and gateway engineering talent.
Singapore
Licensed digital payment token providers anchor APAC hub development through the Monetary Authority's regulatory framework. The MAS licensing regime mandates reserve backing and audit-grade reporting for stablecoin issuers. Marina Bay and the central business district cluster infrastructure providers seeking regional headquarters status.
Germany
Mid-market retailers adopt cloud-deployed gateways to satisfy GDPR data residency requirements while minimizing capital expenditure. The EU's MiCA framework eliminates jurisdictional arbitrage for payment token issuers operating across European banking corridors. Frankfurt's wholesale banking ecosystem drives demand for intraday settlement automation.
Switzerland
Private banks and wealth managers deploy multi-signature institutional wallets for treasury operations and fractionalized asset custody. Swiss FINMA guidelines provide regulatory certainty for tokenized securities settlement. Zurich and Geneva concentrate custody infrastructure providers serving cross-border private banking clients.
Japan
Wholesale banking departments at Mitsubishi UFJ and Sumitomo Mitsui deploy hybrid architectures to maintain METI-compliant audit trails. The Financial Services Agency mandates registration for virtual currency exchange operators. Tokyo's financial district anchors production of permissioned ledger solutions for corporate bond settlement.
Blockchain Payments Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the blockchain payments software landscape. Tier-one banks and card networks anchor the consolidated upper tier through captive infrastructure investments, while venture-backed specialists fragment the mid-market with point solutions. Three archetypes dominate: regulated stablecoin issuers with compliance-first positioning, pre-funded liquidity network operators, and wholesale payment tokenization platforms serving institutional corridors. Competitive intensity manifests through strategic partnerships with commercial banks and geographic licensing races in Singapore and Switzerland.
Among regulated infrastructure providers, Circle exemplifies the compliance-anchored archetype through its dollar-denominated stablecoin reserves. Ripple occupies a position within the liquidity network tier, while JPMorgan Chase Onyx anchors the wholesale banking segment. These three entities represent divergent strategic bets on whether payment finality derives from regulatory licensing, pre-funded correspondent relationships, or permissioned ledger deployment.
| Leading Market Players |
|---|
| BVNK |
| Circle |
| Ripple |
| BitPay |
| Coinbase |
| Mastercard Blockchain |
| Stellar |
| Veem |
| JPMorgan Chase Onyx |
| Others |
Pricing and Supply Chain Analysis
Validator node hardware procurement costs cascade through three-tier pricing structures across premium, standard, and economy levels, with Singapore-licensed infrastructure providers absorbing premium tiers while cloud-deployed mid-market gateways compete on standard-economy differentiation.
Pricing Analysis
Margin tightening in enterprise gateway tiers reflects embedded compliance module costs under MiCA and MAS licensing requirements. Three-tier pricing structure across premium, standard, and economy levels separates hardware security module-integrated deployments from API-only configurations. Price differentiation hinges on certification grade (MAS license tier, EU e-money authorization) and geographic delivery cost (data residency zone). Financial institutions show lowest price sensitivity; mid-market retailers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced semiconductor fabrication of hardware security modules and specialized cryptographic processors. Supply concentrates in the United States for consensus algorithm IP and zero-knowledge proof engineering talent, with Germany anchoring GDPR-compliant cloud infrastructure. Raw material dependencies span silicon wafers, rare earth elements for HSM components, and renewable energy credits for carbon-attributed transaction routing. Tariff exposure on cross-border hardware shipments creates structural risk. Distribution runs through direct enterprise sales for institutional tiers and API marketplace integrations for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blockchain payments software market functions as a cost-of-compliance story where MiCA reserve standards and MAS licensing regimes erect barrier-to-entry moats that favor capitalized incumbents with regulatory infrastructure already deployed.
For Market Incumbents: Hedge against validator concentration risk by diversifying staking provider relationships across multiple geographic jurisdictions. Deepen backward integration into hardware security module manufacturing to secure supply continuity for institutional wallet deployments. Channel control through exclusive partnerships with tier-one banks in Switzerland and Singapore reinforces positioning against emerging liquidity network competitors. For New Entrants and Emerging Players: Begin with India UPI-blockchain bridge infrastructure as the most penetrable white-space target, where rupee-denominated stablecoin settlement layers remain underdeveloped. Target carbon-attributed transaction fee services for EU corporates facing CSRD disclosure mandates. API-first integration models with Latin American e-commerce platforms offer the clearest go-to-market angle. For Investors and Strategic Acquirers: MAS license application volume acceleration is the leading indicator that regulatory clarity is concentrating APAC hub development and compressing returns for late entrants. Long-term viability favors vertically integrated platform plays with captive compliance stacks over point-solution gateway providers. Acquisition target archetype: hybrid deployment specialists with METI-compliant audit trail capabilities. The signal to watch is stablecoin issuer reserve audit frequency tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory License Acquisition | MAS and FINMA authorizations unlock institutional treasury corridors in APAC and private banking. |
| Smart Contract Oracle Integration | IoT sensor data feeds automate supply chain finance triggers for enterprise clients. |
| Hybrid Deployment Scale-Up | Split architectures satisfy METI audit trails while leveraging public chain validation economics. |
| Carbon-Attributed Fee Tier Launch | EU CSRD compliance creates differentiated service positioning for emissions-tracked routing. |
| Multi-Chain Orchestration Buildout | Abstraction layers across Ethereum, Solana, and permissioned ledgers reduce bridge infrastructure friction. |
Research Methodology
Independent corroboration across primary interviews with blockchain infrastructure CTOs, digital payment token compliance officers, central bank sandbox program managers, and enterprise treasury platform engineers underwrites the qualitative findings. Secondary validation draws from SEC disclosure filings for publicly traded stablecoin issuers, MAS licensing registries, EU MiCA implementation guidance documents, and Singapore fintech regulatory circulars. Bottom-up segment sizing and top-down macro validation anchor the quantitative framework.
Rate-of-change decomposition separates volume growth drivers from value capture mechanisms across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and regional regulatory cluster. CAGRs derive from logistic adoption curve fitting against institutional onboarding velocity and merchant gateway penetration rates. Forecast inputs incorporate MiCA implementation timelines and MAS license approval throughput as regulatory pacing variables.
Regulatory enforcement divergence, stablecoin reserve audit failure events, and layer-one consensus disruption are the dominant revision risks that could compress or extend adoption trajectories. Forecasts reflect documented assumptions about licensing regime stability and interoperability standard convergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
QR Codes Payment Market
Payments
Italy Gift Cards Market
Payments
Digital Remittance Service Market
Payments
United States POS Terminals Market
Payments
In-Vehicle Payment System Market
Payments
Global Mobile Payment Technology Market
Payments
Kenya Mobile Money Market
Payments
GCC Mobile Payment Market
Payments
India Payment Gateway Market
Payments
Europe Payment Gateways Market
Payments
3D Secure Payment Authentication Market
Payments
Global Payments As a Service Market
Payments
Mobile Money Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Credit Card Issuance Services Market
Payments
Global Virtual Payment (POS) Terminals Market