
 UK Virtual Cards Market | 2026-2036
UK Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
UK Virtual Cards Market Analytics
Physical plastic substitution by tokenized digital credentials is restructuring issuance economics across UK banking. Revolut leverages its multi-currency infrastructure to sustain virtual card volumes across European corridors. Monzo anchors consumer adoption through real-time spending controls and merchant-locking features. Starling Bank competes aggressively on SME banking bundles that integrate virtual cards with accounting software APIs.
UK virtual cards are digitally generated payment instruments bearing single-use or limited-use PANs, CVVs, and expiry credentials delivered through mobile applications or API endpoints, designed to isolate transaction risk and enable programmatic spend governance. The technology dimension shows API Solutions commanding the deepest integration with corporate ERP systems, while Mobile Payments leads consumer-facing deployment through NFC-enabled device provisioning. Within end user type, Corporates and Small Businesses represent the fastest-expanding demand pools as finance teams replace traditional purchasing cards with department-level virtual budgets.
The Financial Conduct Authority shapes product standards through PSD2 compliance mandates and consumer duty requirements, while the Payment Systems Regulator enforces access and competition rules across issuance networks. HM Treasury's digital pound consultation and the Competition and Markets Authority's ongoing Open Banking enforcement are tightening interoperability expectations for virtual card infrastructure. Stakeholders must monitor how regulatory pressure on account-to-account payments reshapes virtual card value propositions relative to direct bank transfer alternatives.
Market Dynamics
Open Banking mandates from the Competition and Markets Authority are dismantling incumbent payment rails and forcing banks to expose APIs for third-party virtual card issuance, fundamentally altering competitive economics across UK financial services.
Growth Catalysts
- PSD2 Compliance Mandates:Regulatory pressure from the Financial Conduct Authority compels traditional banks to open payment initiation interfaces, accelerating API-native virtual card deployment for corporate treasury departments.
- SME Banking Bundles:Small businesses in London, Manchester, and Birmingham demand integrated expense management tools, pulling virtual card adoption into accounting software workflows.
- Tokenized Digital Credentials:Single-use PAN technology isolates transaction fraud exposure, driving finance teams to replace physical purchasing cards with programmable virtual alternatives.
Market Restraints
- Account-to-Account Payment Substitution:HM Treasury's digital pound consultation and Faster Payments infrastructure improvements threaten virtual card interchange revenue models with direct bank transfer alternatives.
- Issuer Concentration Risk:Mastercard and Visa network dominance in UK BIN sponsorship creates dependency on two payment schemes for virtual card program scalability.
- API Integration Costs:Corporate ERP system connectivity requires substantial technical investment, slowing mid-market adoption relative to enterprise deployment.
Strategic Opportunities
- Consumer Duty Requirements:The Financial Conduct Authority's enhanced conduct standards create competitive openings for virtual card providers offering transparent spend controls and real-time merchant blocking.
- Department-Level Virtual Budgets:Corporate finance teams are segmenting purchasing authority into granular, API-driven spending envelopes with automated policy enforcement.
- NFC-Enabled Device Provisioning:Mobile wallet integration is overtaking physical card replacement cycles, embedding virtual credentials directly into smartphone payment architectures.
Industry Challenges
- Legacy Core Banking Modernization:Traditional institutions struggle to decouple card management systems from decades-old mainframe infrastructure, delaying real-time virtual card issuance capabilities.
- Payment Systems Regulator Access Rules:Compliance with network participation and competition enforcement demands continuous operational adaptation from emerging fintech issuers.
- Interoperability Standardization:Fragmented API specifications across Open Banking implementation entities complicate multi-bank virtual card program deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Virtual Cards Market |
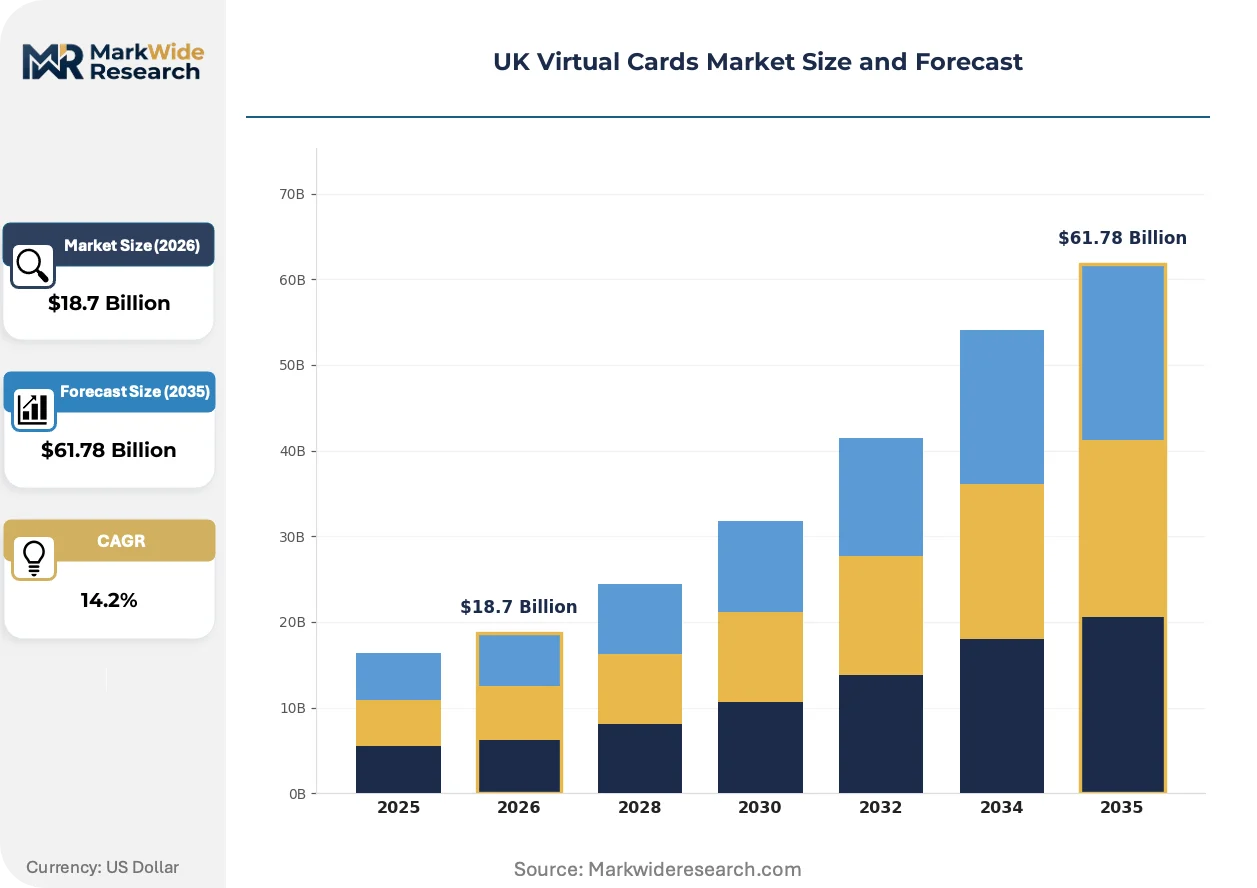
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: One-time Use, Recurring Payments, Subscription Services, Online Shopping End User Type: Consumers, Small Businesses, E-commerce Platforms, Corporates Technology: Mobile Payments, eWallet Integration, API Solutions, Cloud-Based Security Feature: Fraud Detection, Encryption, Multi-Factor Authentication, Tokenization |
| Companies Covered | Revolut, Monzo, Starling Bank, Barclaycard Payments, HSBC UK, Skrill, Monese, Wise, Stripe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Virtual Cards Market Evolving Landscape
Programmable payment infrastructure is collapsing the distinction between payment instrument and financial control system, embedding governance rules directly into transaction credentials rather than layering them atop legacy card products.
API-driven virtual card generation is overtaking batch-issued physical credentials in corporate procurement workflows. Finance teams at e-commerce platforms and marketplace operators are adopting real-time card creation for supplier payments, compressing onboarding cycles from weeks to seconds. This shift is enabling just-in-time liquidity deployment and granular spend attribution previously impossible under static card programs.
The Payment Systems Regulator's access and competition enforcement is tightening interoperability expectations for virtual card infrastructure across UK issuance networks. Incumbent schemes must now accommodate alternative routing and transparent fee structures, reshaping program economics for fintech challengers. SME-focused providers are responding by unbundling virtual cards from broader banking relationships, selling credential-as-a-service to accounting platforms.
Procurement departments are abandoning centralized purchasing card programs in favor of distributed, department-owned virtual budgets with embedded policy engines. This behavioral pivot replaces monthly reconciliation cycles with real-time spend visibility and automatic expense categorization. Corporate treasury functions in London and Birmingham financial services clusters are most advanced in this transition, pressuring mid-market finance teams to match their control sophistication.
UK Virtual Cards Market Segmentation
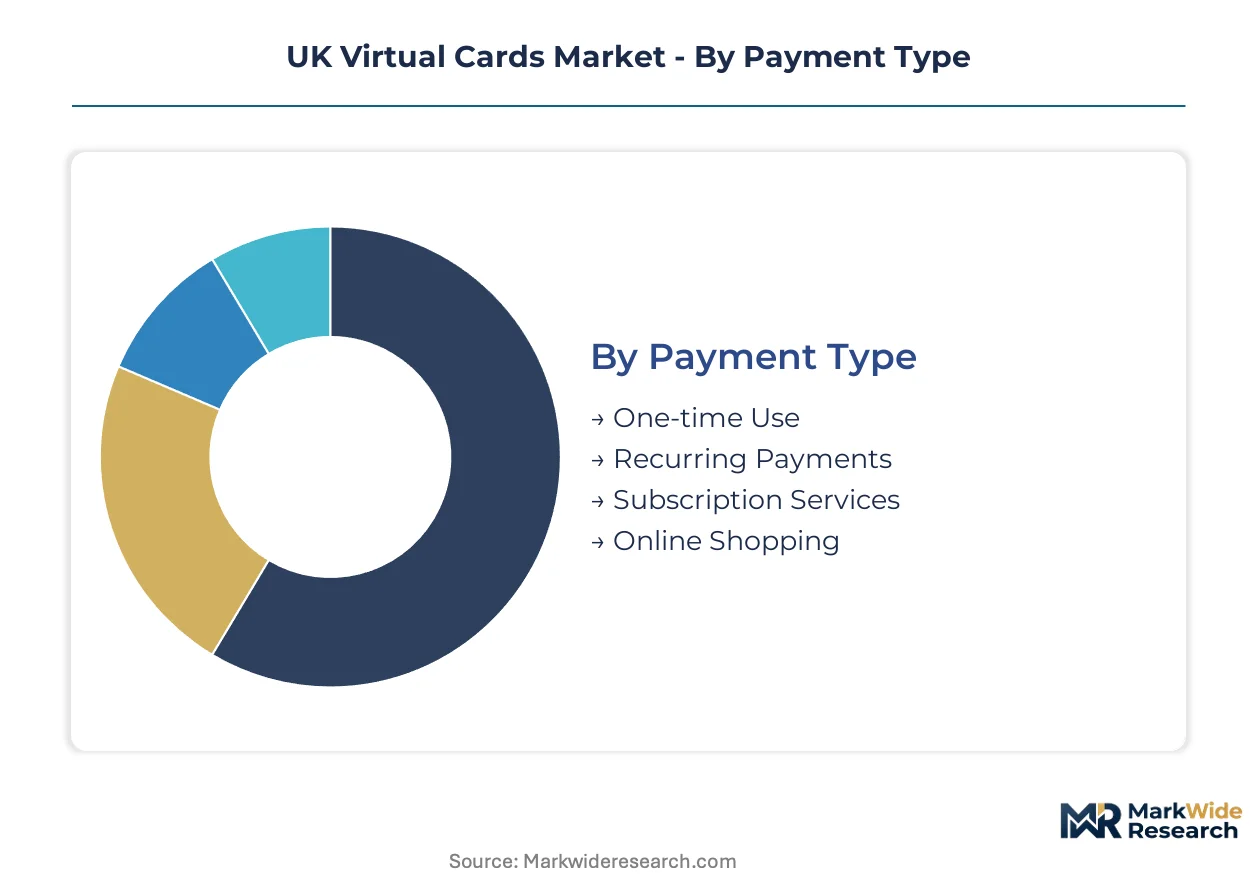
Virtual card architecture fragments across payment behavior, organizational scale, technical infrastructure, and risk management priorities. Each dimension shapes procurement decisions, integration requirements, and vendor selection criteria for UK issuers and their corporate clients.
Payment Type:
Transaction frequency and merchant relationship duration separate buyers into distinct risk and operational profiles.
- One-time Use:Single-transaction credentials with automatically expiring PANs eliminate residual fraud exposure after purchase completion. E-commerce platforms in London deploy these for high-value supplier onboarding where recurring relationships remain unproven.
- Recurring Payments:Persistent virtual credentials with merchant-locked routing enable automated settlement cycles without exposing primary account details. Utility and SaaS procurement teams across Birmingham favor these for predictable operational expenditures.
- Subscription Services:Time-bounded credentials with spend ceilings contain vendor lock-in risks.
- Online Shopping:Consumer-facing credentials optimized for checkout velocity and mobile wallet compatibility.
Recurring Payments leads volumes today; One-time Use is gaining share fastest.
End User Type:
Organizational complexity determines control granularity and API integration depth requirements.
- Corporates:Treasury departments demand ERP-native virtual card provisioning with real-time spend policy enforcement. Manchester financial services clusters lead deployment of department-level virtual budgets with automated GL coding.
- Small Businesses:Founder-led finance teams prioritize accounting software integration over standalone banking relationships. Xero and QuickBooks connectivity drives vendor selection across London, Manchester, and Birmingham SME corridors.
- Consumers:Individual users seek merchant-blocking and real-time notifications.
- E-commerce Platforms:Marketplace operators require mass credential issuance for seller payout automation.
Small Businesses leads volumes today; Corporates is expanding most quickly.
Technology:
Deployment architecture separates buyers by technical maturity and legacy system constraints.
- API Solutions:RESTful endpoints enabling programmatic card generation, spend rule configuration, and real-time transaction streaming. Corporate treasuries in London integrate these directly into SAP and Oracle workflows.
- Mobile Payments:NFC-enabled credential provisioning through smartphone wallets dominates consumer-facing deployment. Device-centric authentication reduces fraud rates for in-person and remote transactions alike.
- eWallet Integration:Embedded credentials within third-party financial applications.
- Cloud-Based:Browser-accessible management portals for mid-market teams lacking dedicated IT resources.
Mobile Payments leads volumes today; API Solutions is climbing the fastest.
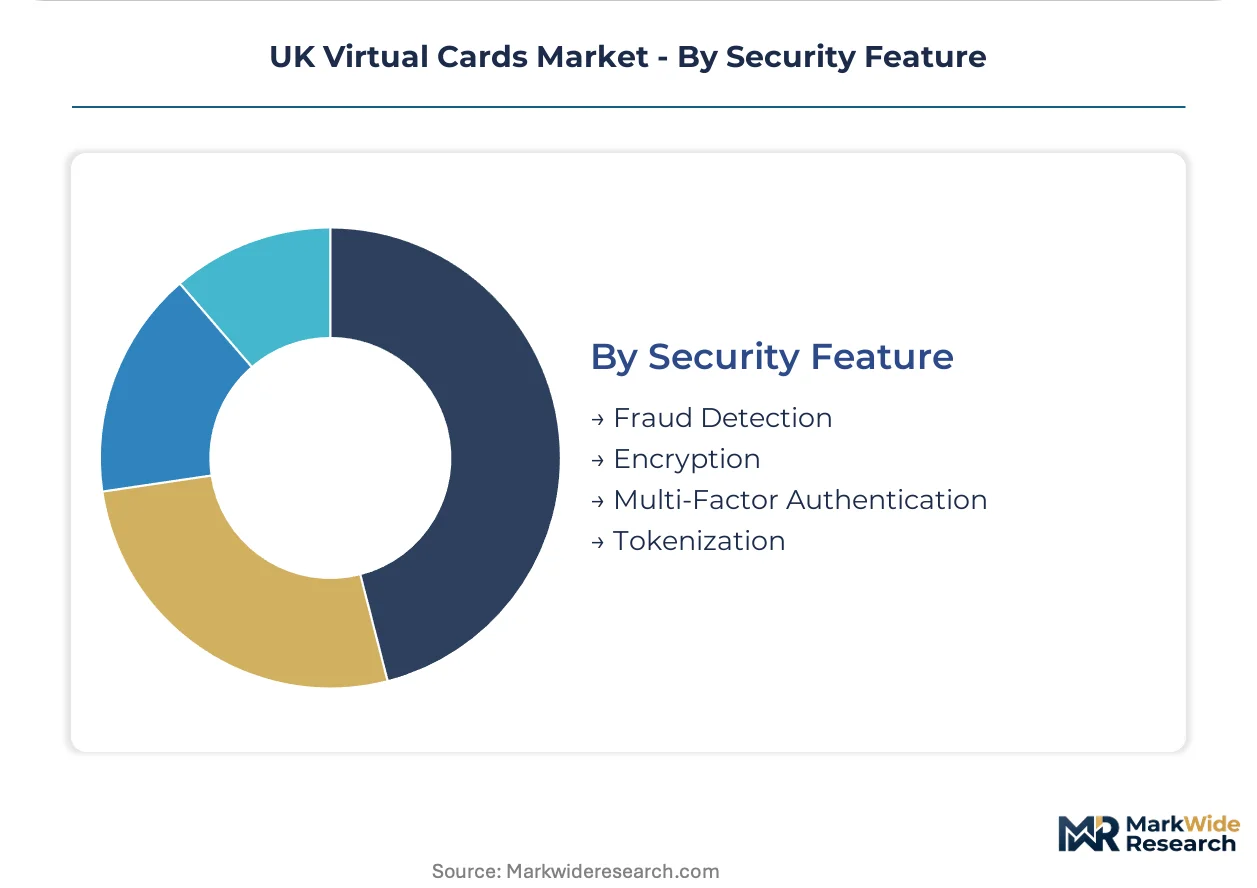
Security Feature:
Risk tolerance and regulatory exposure shape investment priority across authentication layers.
- Tokenization:PAN substitution with cryptographically generated tokens isolates breach impact to single transactions. PSD2 compliance mandates from the Financial Conduct Authority accelerate deployment across UK issuance programs.
- Fraud Detection:Machine learning models analyzing transaction velocity, geolocation, and merchant category patterns. Real-time scoring enables instant authorization decisions without cardholder friction.
- Encryption:End-to-end credential protection in transit and at rest.
- Multi-Factor Authentication:Biometric and device-binding verification for high-value transactions.
Tokenization leads volumes today; Fraud Detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors UK virtual card deployment through its concentration of fintech headquarters and corporate treasury functions. The Financial Conduct Authority's PSD2 enforcement and Open Banking mandates from the Competition and Markets Authority are reshaping issuance economics across England, Scotland, Wales, and Northern Ireland.
England
Manchester and Birmingham SME corridors drive accounting software integration demand, pulling virtual cards into Xero and QuickBooks workflows. The Payment Systems Regulator's access rules tighten interoperability expectations for issuance networks. Corporate finance teams in London's financial services cluster lead adoption of department-level virtual budgets with automated policy enforcement.
Scotland
Edinburgh's banking heritage supports fintech challenger growth alongside established institution modernization. The Financial Conduct Authority's consumer duty requirements create competitive openings for transparent spend control products. Glasgow's emerging tech sector concentrates API-native virtual card development for corporate procurement workflows.
Wales
Cardiff's financial services expansion attracts virtual card providers targeting mid-market treasury departments. HM Treasury's digital pound consultation influences regional bank strategies for payment credential alternatives. The South Wales corridor shows accelerating SME adoption of mobile-first expense management tools.
Northern Ireland
Belfast's regulatory technology sector develops compliance infrastructure for virtual card program scalability. The Competition and Markets Authority's ongoing Open Banking enforcement affects cross-border issuance economics with the Republic of Ireland. Local fintech incubators concentrate on NFC-enabled credential provisioning for consumer wallets.
UK Virtual Cards Market Competitive Landscape
Global majors compete with regional champions across API infrastructure and mobile wallet integration. The UK virtual cards sector shows tiered concentration: digital-native challengers with banking licenses, established card networks pivoting to virtual issuance, and specialist payment processors. Three archetypes dominate: full-stack neobanks, legacy bank virtual card divisions, and embedded finance infrastructure providers. Competitive moves center on accounting software API partnerships and BIN sponsorship network diversification.
Among London-based neobanks, Revolut, Monzo, and Starling Bank exemplify the challenger archetype through multi-currency infrastructure, real-time spending controls, and SME banking bundles respectively. These digital-native institutions occupy positions defined by their core capabilities: Revolut anchors European corridor coverage, Monzo sits within consumer merchant-locking specialization, and Starling represents integrated accounting connectivity. Their collective presence pressures legacy institutions to accelerate core banking modernization for virtual card parity.
| Leading Market Players |
|---|
| Revolut |
| Monzo |
| Starling Bank |
| Barclaycard Payments |
| HSBC UK |
| Skrill |
| Monese |
| Wise |
| Stripe |
| Others |
Value Network & Pricing Analysis
API-native issuance tiers diverge sharply from legacy BIN sponsorship arrangements, creating a bifurcation where programmatic virtual card providers command premium pricing through embedded ERP integration while traditional issuers compete on commoditized interchange economics. This divergence reshapes supplier selection, with fintech challengers sourcing cloud infrastructure and tokenization services from specialized vendors while incumbent banks remain tethered to decades-old core banking maintenance contracts.
Pricing Analysis
Input-cost pass-through from BIN sponsorship fees and network interchange assessments shapes virtual card program economics, with Mastercard and Visa scheme charges representing the dominant cost component. Three-tier pricing structure across premium API integration, standard SaaS dashboards, and economy mobile-only provisioning separates enterprise treasury clients from mid-market accounting software bundles. Pricing pressure stems from account-to-account payment alternatives and Faster Payments infrastructure improvements threatening interchange-dependent revenue models. SME segments exhibit highest price sensitivity, driving unbundling of virtual cards from broader banking relationships.
Supply Chain Analysis
Single-source vulnerability sits with Mastercard and Visa network dominance for UK BIN sponsorship, creating dependency concentration for program scalability. Cloud infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform data centers across Ireland, Germany, and the Netherlands. Tokenization services rest on specialized cryptography providers and HSM manufacturers. Supply chain risk centers on regulatory restriction from Payment Systems Regulator access rule enforcement. Distribution runs through direct API sales to corporate treasuries, accounting software marketplace integrations, and mobile application stores for consumer provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Virtual Cards Market functions as a stable compounder, with Open Banking regulatory mandates ensuring sustained API infrastructure investment across financial services. Programmable payment credential demand from corporate treasury departments provides recurring revenue visibility.
For Market Incumbents: Anticipate fintech challenger encroachment into SME banking bundles by accelerating core banking modernization for real-time virtual card issuance. Defensive consolidation through API partnership acquisitions with accounting software platforms protects distribution control. Vertical integration into tokenization infrastructure reduces third-party cryptography dependency.
For New Entrants and Emerging Players: Capture mid-market corporate procurement workflows where ERP integration complexity has slowed incumbent adoption. White-space concentration exists in department-level virtual budgets with automated policy enforcement for Birmingham and Manchester financial services clusters. Go-to-market leverage through Xero and QuickBooks marketplace positioning accelerates customer acquisition velocity.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIN sponsorship concentration limits program economics for sub-scale issuers. Long-term viability favors API-native infrastructure providers with direct ERP connectivity and multi-network routing capabilities. Acquisition target archetypes include embedded finance infrastructure specialists and accounting software-integrated virtual card platforms. Signal to watch is Payment Systems Regulator enforcement action on alternative routing mandates as inflection indicator for competitive parity.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Development | Direct SAP and Oracle integration captures corporate treasury procurement workflows in London financial services clusters. |
| Accounting Software Marketplace Integration | Xero and QuickBooks embedding pulls virtual card adoption into SME expense management automation across Manchester and Birmingham. |
| Multi-Network BIN Sponsorship Diversification | Reduced Mastercard and Visa dependency strengthens program economics against Payment Systems Regulator access enforcement. |
| Real-Time Tokenization Infrastructure Investment | In-house cryptography capabilities lower third-party HSM costs and accelerate PSD2 compliance for Financial Conduct Authority mandates. |
| Department-Level Virtual Budget Product Launch | Granular spend envelope provisioning with automated GL coding addresses corporate finance team demand in Birmingham financial services corridors. |
Research Methodology
Direct dialogue with virtual card product managers, corporate treasury directors, accounting software integration specialists, and Payment Systems Regulator policy officers grounded the qualitative foundation. Secondary validation drew from Financial Conduct Authority PSD2 compliance filings, Competition and Markets Authority Open Banking enforcement updates, HM Treasury digital pound consultation documents, and BIN sponsorship network disclosure data. Bottom-up segment sizing triangulated against top-down payment volume estimates from Faster Payments infrastructure reporting.
Market size and growth trajectory outputs across the projection horizon reflect econometric modeling of API adoption curves, SME banking bundle penetration rates, and corporate procurement digitization indices. Segmentation dimensions modeled include payment type, end user organizational scale, technology deployment architecture, and security feature investment priority. CAGRs derive from regression analysis of historical virtual card issuance velocity against Open Banking API call growth and accounting software platform expansion metrics.
Regulatory enforcement intensity shifts, account-to-account payment substitution acceleration, and cloud infrastructure cost volatility are the dominant revision risks for forecast assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Spain Payment Gateway Market
Payments
Czech Republic POS Terminals Market
Payments
Global Payment Gateways Market
Payments
Vietnam Mobile Payments Market
Payments
EMV Card Market
Payments
Germany POS Terminal Market
Payments
Nigeria Mobile Money Market
Payments
Payment Instruments Market
Payments
Europe Payments Market
Payments
Egypt Mobile Payments Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Europe Accounts Payable Automation Market
Payments
Vietnam E-Wallet Market
Payments
Global Financial Cards and Payments Market
Payments
Malaysia Payments Market
Payments
Forex Prepaid Cards Market