
 Consumer Wet Wipes Market | 2026-2036
Consumer Wet Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Wet Wipes Market Analysis
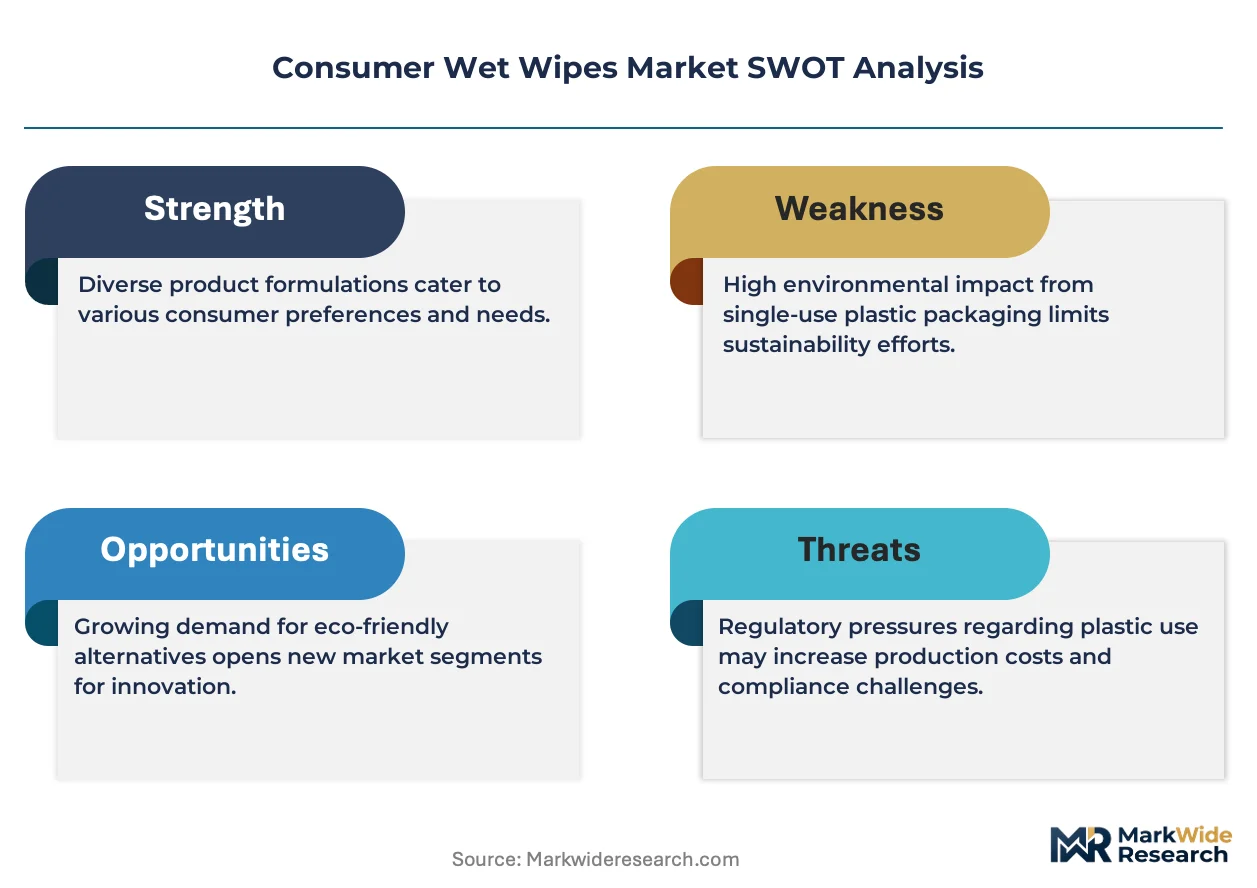
The EU Single-Use Plastics Directive is rebalancing the cost-of-entry calculus for wet wipe producers across Europe, forcing reformulation of synthetic fiber blends and raising compliance expenditures for market participants. Procter & Gamble leverages its massive R&D infrastructure to develop flushable and biodegradable substrates ahead of regulatory deadlines. Kimberly-Clark Corporation anchors North American supply through integrated non-woven manufacturing and dominant retail shelf presence. S.C. Johnson & Son differentiates via concentrated brand equity in household cleaning wipes and controlled distribution through club and mass channels.
Consumer wet wipes are pre-moistened disposable cloths, typically comprising spunlace non-woven fabrics saturated with aqueous solutions containing surfactants, preservatives, and functional additives, manufactured through hydroentanglement or thermal bonding processes for single-use hygiene and surface cleaning applications. Baby wipes occupy the largest volume share within product type segmentation, sustained by recurring purchase cycles among caregivers, while personal care wipes represent the fastest-expanding margin pool as grooming and cosmetic removal applications proliferate. Non-woven fabric dominates material segmentation due to cost-engineered scalability, though bamboo substrates attract premium positioning as brands respond to plastic-free purchasing preferences.
The EPA regulates disinfectant claims on household wipes in the United States, requiring substantiated efficacy labeling that shapes product development timelines and market access protocols. ECHA enforces REACH compliance for chemical constituents in European formulations, while FDA oversight applies to wipes marketed with cosmetic or antimicrobial drug claims, creating a multi-layered compliance landscape. Stakeholders must monitor evolving biodegradability certification standards and state-level flushability legislation to anticipate where capital deployment for substrate innovation will yield defensible positioning.
Market Dynamics
The EU Single-Use Plastics Directive is forcing substrate reformulation across wet wipe manufacturing, compelling producers to abandon synthetic fiber blends and absorb compliance costs that now determine competitive viability in European markets.
Growth Catalysts
- REACH chemical compliance:ECHA enforcement of chemical constituent standards is accelerating the phase-out of petrochemical-based preservatives, creating first-mover advantage for bio-based formulation specialists.
- Flushable substrate innovation:Hydroentanglement process improvements are enabling dispersible non-woven fabrics that meet INDA/EDANA flushability guidelines without sacrificing tensile strength.
- Caregiver purchase recurrence:Parents of infants maintain weekly replenishment cycles that stabilize volume baselines and reduce demand volatility for baby wipe portfolios.
Market Restraints
- Pulp fiber cost volatility:Fluctuating viscose rayon and cotton linter prices compress margin predictability for spunlace substrate producers dependent on cellulose supply chains.
- Regulatory fragmentation:Divergent state-level flushability legislation across the United States creates compliance complexity that multiplies SKU management overhead.
- Biodegradable certification delays:Slow standardization of industrial compostability protocols under ASTM D6400 and EN 13432 extends product launch timelines.
Strategic Opportunities
- Plastic-free purchasing mandates:Retailer sustainability scorecards in Germany and France are creating shelf-access incentives for bamboo and wood-pulp substrate alternatives.
- Cosmetic removal applications:Micellar water-infused personal care wipes are capturing share from traditional liquid cleansers among urban professional demographics.
- Direct-to-subscription channels:Recurring delivery models for household cleaning wipes bypass retail slotting fees and capture lifetime value through predictable replenishment.
Industry Challenges
- Preservative efficacy validation:Demonstrating antimicrobial stability across extended shelf lives requires costly challenge testing under USP 51 protocols.
- Substrate-handling equipment retooling:Transitioning production lines from petroleum-based to plant-based non-wovens demands capital-intensive calendering and bonding modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Wet Wipes Market |
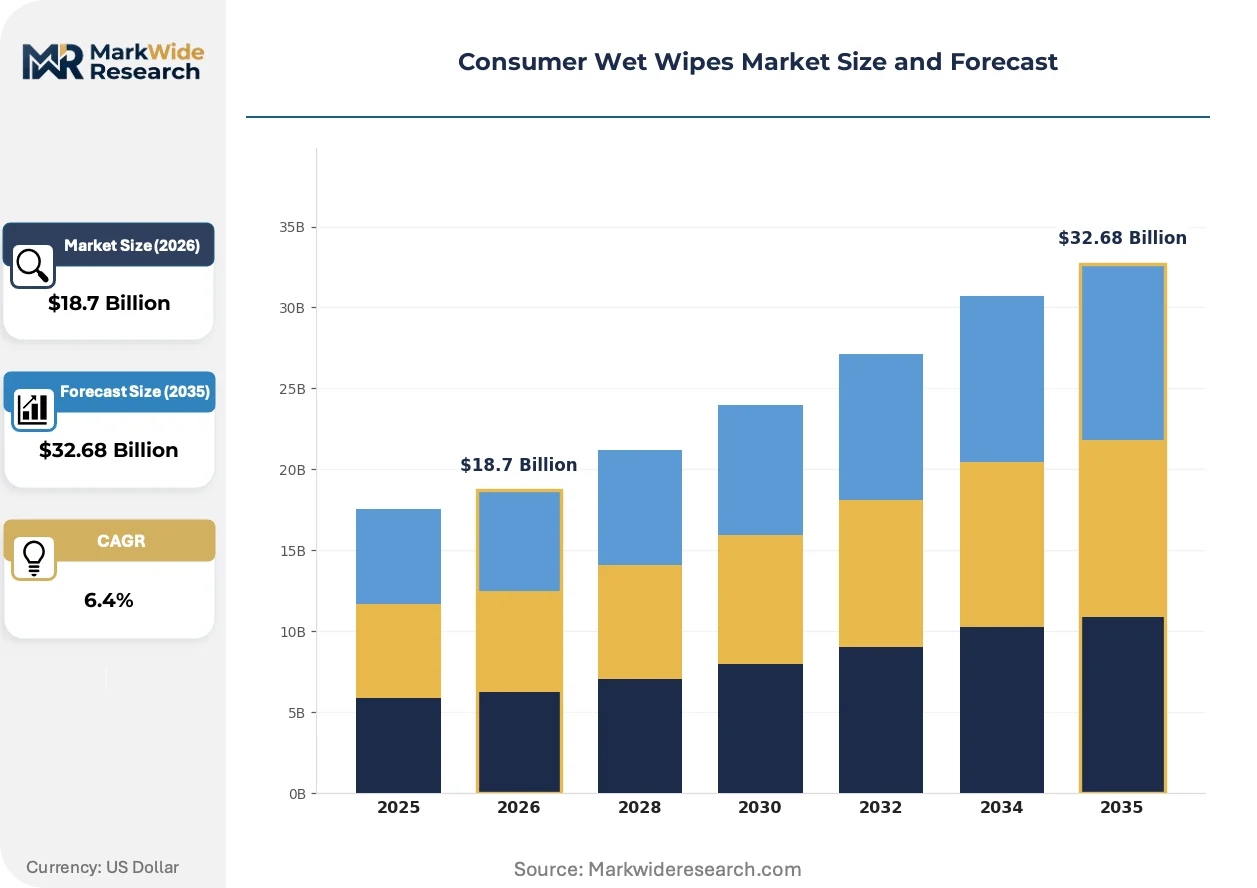
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baby Wipes, Adult Wipes, Household Wipes, Personal Care Wipes Material: Non-woven Fabric, Cotton, Viscose, Bamboo Packaging Type: Flip-top Packs, Resealable Packs, Tub Packs, Sachets End User: Consumers, Hospitals, Restaurants, Schools |
| Companies Covered | Nice-Pak Products, Clorox Company, Procter & Gamble, S.C. Johnson & Son, Diamond Wipes International, Kimberly-Clark Corporation, Rockline Industries, Unicharm Corporation, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Wet Wipes Market Emerging Trajectories
Substrate chemistry and preservation science are converging to resolve the tension between single-use convenience and environmental accountability, with manufacturers racing to certify biodegradable alternatives ahead of regulatory deadlines.
Bamboo-cellulose hybrid substrates are unifying tensile performance with compostability credentials. Premium personal care brands in France and the United Kingdom are adopting these materials at accelerated rates. This convergence is compressing the cost gap between synthetic and bio-based non-wovens, forcing mid-tier producers to reformulate or exit European distribution.
REACH Annex XVII restrictions on microplastic-containing products are mandating fiber disclosure and biodegradability testing for all wet wipes marketed in EU member states. Manufacturers must now submit technical dossiers demonstrating substrate decomposition within specified timeframes. Baby wipe and cosmetic removal segments face the steepest compliance curves as caregiver and beauty consumer scrutiny intensifies.
Subscription-based replenishment models are displacing impulse retail purchases for household cleaning wipes. Club channel and direct-to-consumer platforms in the United States are capturing volume from conventional grocery and drugstore fixtures. Urban multifamily households demonstrate the highest conversion rates to automated delivery, driven by storage constraints and routine-driven consumption patterns.
Consumer Wet Wipes Market Segmentation
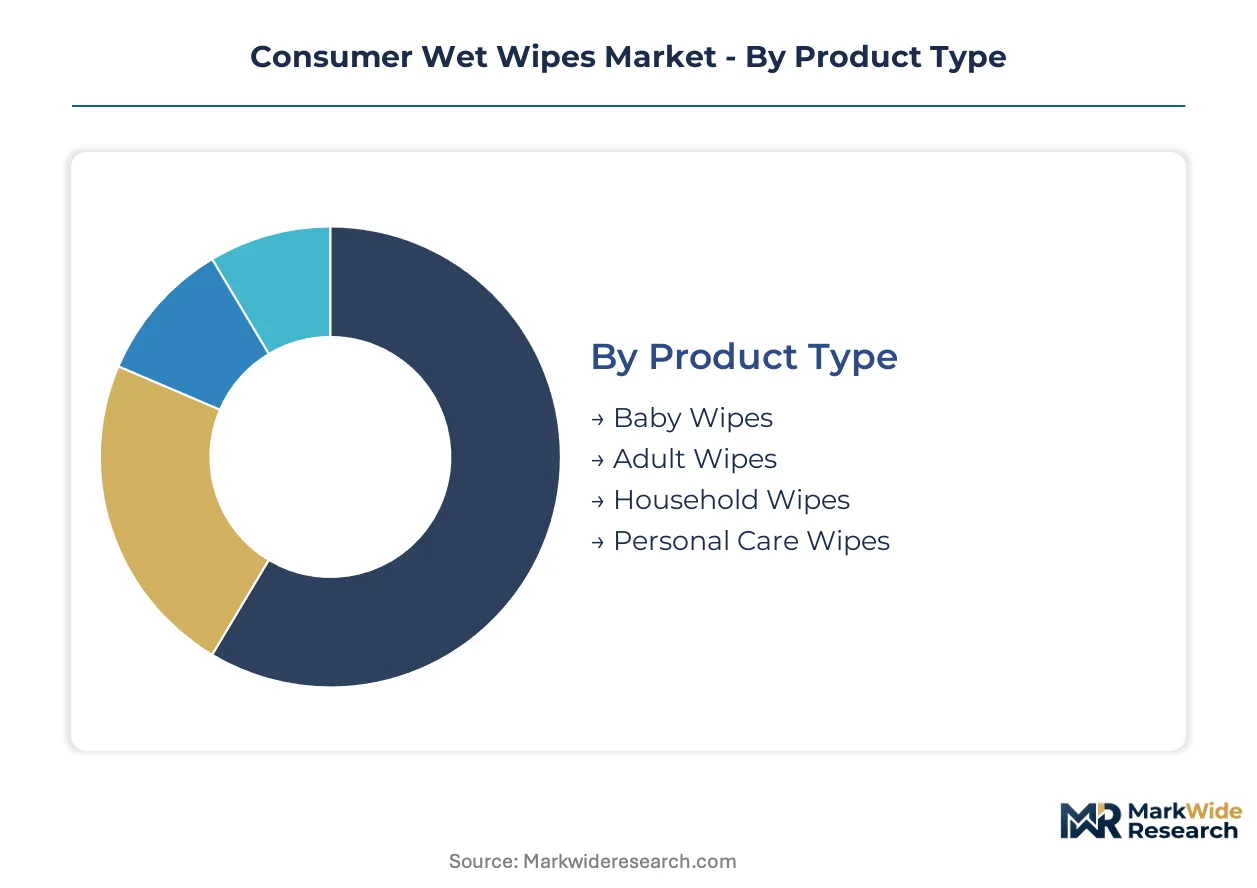
Segmentation in the consumer wet wipes market determines where capital flows for substrate innovation, which regulatory compliance burdens apply, and how pricing power concentrates across the value chain. Manufacturers align production assets to specific segment requirements rather than pursuing horizontal coverage.
Product Type:
Supply concentration clusters around formulations with the highest purchase recurrence and lowest customer acquisition costs, creating divergent margin profiles across the four product categories.
- Baby Wipes:Formulated with mild surfactants, pH-balanced aqueous solutions, and hypoallergenic preservatives for infant skin compatibility. Weekly replenishment cycles among parents of infants in the United States stabilize volume baselines and reduce demand volatility for producers with dedicated manufacturing lines.
- Personal Care Wipes:Micellar water-infused and cosmetic removal formulations targeting urban professional demographics. Demand concentrates in France and the United Kingdom where premium positioning commands shelf access through retailer sustainability scorecards.
- Adult Wipes:Larger-format substrates with enhanced tensile strength for mobility-impaired and senior care applications.
- Household Wipes:Disinfectant-saturated substrates regulated by EPA efficacy claims requirements in the United States.
Today's leader: Baby Wipes. Tomorrow's challenger: Personal Care Wipes.
Material:
Cost tier differentiation separates commodity cellulose supply chains from premium bio-based alternatives, with compliance timelines under REACH Annex XVII driving accelerated migration toward certified substrates.
- Non-woven Fabric:Spunlace hydroentangled or thermally bonded synthetic and cellulose blends manufactured for cost-engineered scalability. Producers dependent on petroleum-based fibers face compressed margins as ECHA enforcement of microplastic restrictions forces technical dossier submissions for EU market access.
- Bamboo:Cellulose-rich grass fibers processed through viscose or lyocell methods yielding compostable credentials under ASTM D6400 and EN 13432 protocols. Premium personal care brands in Germany and France are adopting these materials at accelerated rates as plastic-free purchasing mandates reshape shelf-access negotiations.
- Cotton:Natural linter fibers prized for softness in cosmetic removal applications with higher raw material cost exposure.
- Viscose:Regenerated cellulose from wood pulp subject to viscose rayon price volatility that compresses margin predictability for spunlace substrate producers.
Non-woven Fabric anchors current volume. Bamboo captures the steepest expansion trajectory as regulatory deadlines approach.
Packaging Type:
Application context dictates format selection, with moisture retention engineering and dispensing convenience driving distinct capital equipment requirements across manufacturing facilities.
- Flip-top Packs:Rigid plastic lids with snap-seal mechanisms for single-hand dispensing in household and baby wipe applications. Club channel distribution in the United States favors this format for pallet efficiency and retail shelf velocity.
- Resealable Packs:Adhesive strip closures on flexible film substrates for personal care and travel-size segments. Urban multifamily households demonstrate highest conversion to subscription replenishment models using this lightweight format.
- Tub Packs:Rigid cylindrical containers with threaded lids for high-volume household disinfectant wipes.
- Sachets:Single-unit foil or film pouches for hospitality, airline, and promotional sampling channels.
Flip-top Packs dominate retail velocity. Resealable Packs gain fastest through direct-to-consumer channels.
End User:
Customer type determines regulatory pathway, with institutional buyers imposing specification standards that diverge sharply from consumer-driven purchasing criteria.
- Consumers:Individual purchasers selecting based on brand equity, substrate feel, and sustainability credentials. Caregiver purchase recurrence for baby wipes and routine-driven consumption patterns for household cleaning wipes create predictable replenishment economics.
- Hospitals:Healthcare facilities requiring FDA oversight for antimicrobial drug claims and USP 51 preservative efficacy validation. Challenge testing costs and substantiated efficacy labeling requirements extend product development timelines for suppliers targeting this segment.
- Restaurants:Food service operators prioritizing sanitizing efficacy and cost-per-use metrics over substrate sophistication.
- Schools:Institutional buyers with consolidated procurement contracts emphasizing volume pricing and dispenser compatibility.
Consumers generate recurring margin pools. Hospitals impose the steepest compliance barriers for market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists and non-woven engineers concentrate in Germany, the United States, and Japan, anchoring substrate innovation and regulatory compliance capabilities for wet wipe producers serving divergent market requirements.
United States
Caregiver purchase recurrence for baby wipes and routine-driven household cleaning consumption stabilize volume baselines. EPA oversight of disinfectant efficacy claims shapes product development timelines for household wipe portfolios. Manufacturing clusters in Wisconsin and Arkansas host integrated spunlace production facilities serving club channel distribution.
Germany
Retailer sustainability scorecards in Berlin and Hamburg create shelf-access incentives for bamboo and wood-pulp substrate alternatives. ECHA enforcement of REACH Annex XVII restrictions mandates fiber disclosure and biodegradability testing for all wet wipes marketed in EU member states. The Rhine-Ruhr industrial corridor hosts specialized non-woven engineering firms developing compostable substrate solutions.
France
Premium personal care wipes targeting cosmetic removal applications command strong positioning among urban professional demographics in Paris and Lyon. ANSM and CNIL oversight intersect with EU-wide ECHA requirements for chemical constituent validation. The Auvergne-Rhône-Alpes region attracts brands accelerating adoption of bamboo-cellulose hybrid materials ahead of regulatory deadlines.
United Kingdom
Micellar water-infused formulations capture share from traditional liquid cleansers in London and Manchester metropolitan markets. Post-Brexit divergence from EU REACH protocols creates parallel compliance obligations for substrate and preservative standards. The Midlands manufacturing belt retains hydroentanglement capacity serving both domestic and export demand.
Japan
Compact resealable formats dominate urban multifamily household purchasing in Tokyo and Osaka due to storage constraints. METI guidelines on plastic resource circulation accelerate substrate reformulation timelines beyond baseline regulatory requirements. The Kansai industrial region hosts precision converting equipment manufacturers supplying regional wipe producers.
Consumer Wet Wipes Market Vendor Landscape
The competitive structure tilts toward diversified consumer goods conglomerates with captive non-woven supply chains. Tiered specialization separates integrated substrate producers from brand-marketing specialists and private-label converters. Dominant competitive moves include backward integration into spunlace manufacturing and strategic partnerships with bamboo fiber suppliers to secure compostable material streams.
Within the integrated multinational tier, Procter & Gamble, Kimberly-Clark Corporation, and S.C. Johnson & Son occupy positions exemplifying divergent strategic emphases. Procter & Gamble represents the R&D-intensive archetype with infrastructure for flushable substrate development. Kimberly-Clark Corporation anchors North American supply security through in-house non-woven production. S.C. Johnson & Son exemplifies brand-equity differentiation in household cleaning applications.
| Leading Market Players |
|---|
| Nice-Pak Products |
| Clorox Company |
| Procter & Gamble |
| S.C. Johnson & Son |
| Diamond Wipes International |
| Kimberly-Clark Corporation |
| Rockline Industries |
| Unicharm Corporation |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Skilled hydroentanglement engineers in the Rhine-Ruhr corridor and Wisconsin manufacturing clusters command wage premiums that compress margin spreads between economy cellulose wipes and premium bamboo substrates. Labor-cost differentials between European and North American production facilities widen pricing-tier spreads as ECHA compliance burdens accumulate on EU-based substrate reformulation.
Pricing Analysis
Bundled subscription services for household cleaning wipes command per-unit premiums over unbundled retail purchases, while economy baby wipes compete on volume scale. Three-tier pricing structure across premium bamboo-cellulose, standard viscose blends, and economy synthetic non-wovens reflects certification grade and substrate biodegradability credentials. Pricing pressure stems from pulp fiber cost volatility as viscose rayon and cotton linter prices fluctuate. Caregivers purchasing baby wipes demonstrate lowest price sensitivity due to replenishment routine lock-in, while institutional buyers in food service exhibit highest sensitivity to cost-per-use metrics.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian bamboo fiber suppliers serving European premium personal care brands. Raw material sourcing concentrates in China for spunlace synthetic blends, the United States for wood-pulp cellulose, and Indonesia for bamboo viscose. Supply chain risk manifests as tariff exposure on Chinese non-woven imports into North American markets. Distribution runs through club channel pallet programs in the United States, mass retail in Germany and France, and direct-to-consumer subscription platforms capturing urban multifamily households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through substrate premiumization as REACH Annex XVII deadlines force mid-tier producers toward certified bamboo alternatives or exit. Cost-down drivers in hydroentanglement process efficiency offset raw material volatility for integrated manufacturers.
For Market Incumbents: Acquire bamboo fiber processing assets in Southeast Asia to secure compostable substrate streams ahead of EU regulatory deadlines. Consolidate spunlace manufacturing capacity in Wisconsin or Arkansas to anchor North American supply security against import tariff exposure. Defensive positioning requires backward integration into viscose production or exclusive partnerships with lyocell specialists to preserve margin pools as synthetic fiber bans proliferate.
For New Entrants and Emerging Players: Enter via direct-to-subscription channels for household cleaning wipes targeting urban multifamily households with storage-constrained consumption patterns. White-space concentration sits in micellar water-infused personal care wipes for cosmetic removal applications among urban professional demographics in France and the United Kingdom. Go-to-market leverage runs through retailer sustainability scorecards in Germany and France that privilege plastic-free substrate credentials for shelf access.
For Investors and Strategic Acquirers: Valuations sit cheapest among private-label converters lacking captive non-woven supply chains and facing compressed margins from REACH compliance costs. Long-term viability favors integrated producers with R&D infrastructure for flushable substrate certification and established club channel relationships. The signal to watch is acceleration in ASTM D6400 and EN 13432 certification timelines as proxy for regulatory enforcement intensity and capital deployment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Fiber Supply | Secures compostable substrate streams ahead of EU Single-Use Plastics Directive deadlines. |
| Flushable Substrate Certification Investment | Enables dispersible non-woven fabrics meeting INDA/EDANA guidelines without tensile sacrifice. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and captures lifetime value through predictable replenishment economics. |
| Retailer Sustainability Scorecard Alignment | Unlocks shelf access in German and French mass channels prioritizing plastic-free purchasing mandates. |
| Hydroentanglement Process Efficiency Program | Reduces unit conversion costs to offset viscose rayon price volatility in spunlace production. |
Methodological Framework
Direct dialogue with brand managers at consumer goods conglomerates, category buyers at club channel retailers, hydroentanglement process engineers, and supply planners at non-woven substrate producers grounded qualitative findings. Secondary validation drew from EPA disinfectant claim filings, ECHA REACH Annex XVII technical dossiers, Nielsen retail audit data, and customs records tracking viscose rayon import flows. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers across the analysis window.
Segment-level outputs across product type, material substrate, packaging format, and end-user category fed into analytical framework projections over the modeling period. CAGRs derived from regression analysis against caregiver purchase recurrence rates, regulatory compliance cost trajectories, and substrate innovation adoption curves. Forecast inputs incorporated ECHA enforcement intensity proxies, pulp fiber futures price volatility bands, and flushability certification pipeline status.
Inputs from regulatory filing databases and retail channel audit services were available through the study window; gaps in real-time bamboo fiber contract pricing introduce uncertainty bands around substrate cost assumptions. Forecasts reflect documented assumptions regarding REACH Annex XVII implementation timelines and state-level flushability legislation progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Household Cleaners Market