
 Global Carpet and Upholstery Cleaning Services Market | 2026-2036
Global Carpet and Upholstery Cleaning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carpet and Upholstery Cleaning Services Market Analysis
Commercial hospitality buyers are rotating toward scheduled maintenance contracts as pandemic-era deep-cleaning protocols become permanent operational standards. ServiceMaster Clean leverages its national franchise network to sustain recurring revenue from hotel chains and property management groups. Stanley Steemer anchors residential demand through direct-to-consumer scheduling platforms and technician training programs. Chem-Dry differentiates via carbonating cleaner technology that reduces water usage and drying times for commercial clients.
Carpet and upholstery cleaning services encompass professional removal of soil, allergens, and contaminants from textile floor coverings and furniture using hot water extraction, absorbent compounds, or low-moisture systems operating at pressures between 100 and 500 PSI and temperatures exceeding 150°F to sanitize without fiber damage. Steam cleaning dominates contract value in commercial settings where hot water extraction penetrates dense pile for regulatory-compliant sanitation. Very low moisture technology captures the fastest expansion in hospitality environments where four-hour drying windows prevent room inventory loss. Residential demand clusters around carbonating systems that minimize disruption to occupied dwellings.
EPA indoor air quality guidelines and OSHA workplace sanitation standards shape service frequency mandates for commercial and industrial facilities across the United States. REACH chemical restrictions in Europe limit formulation choices for pre-spray agents and extraction detergents, pushing operators toward enzyme-based and plant-derived alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations that threaten stain-resistant carpet treatments and could redirect cleaning chemistry investments toward PFAS-free protective coatings.
Market Dynamics
The transition from reactive spot-cleaning to predictive maintenance contracts is compressing customer acquisition costs and extending lifetime value for service providers across commercial real estate portfolios.
Growth Catalysts
- OSHA workplace sanitation mandates:Federal requirements for indoor air quality in US commercial buildings now specify quarterly deep extraction protocols for textile surfaces in high-occupancy zones.
- Very low moisture systems:Hospitality operators in Germany and Japan are adopting four-hour drying technologies to eliminate room inventory loss during peak booking periods.
- Carbonating chemistry:Plant-derived surfactant formulations reduce water consumption by sixty percent compared to traditional hot water extraction, aligning with EU Green Deal resource efficiency targets.
Market Restraints
- PFAS regulatory uncertainty:REACH restrictions on per- and polyfluoroalkyl substances threaten existing stain-resistant carpet treatments and force chemistry reformulation investments without clear compliance timelines.
- Equipment supply concentration:Commercial-grade portable extractors and truck-mounted systems depend on specialized pump manufacturers concentrated in northern Italy and southwestern Germany.
- Skilled technician scarcity:IICRC certification requirements for hot water extraction at 150°F-plus temperatures limit labor pool expansion in markets with tight unemployment.
Strategic Opportunities
- India commercial real estate:Grade-A office stock in Mumbai and Bangalore lacks established service contracts, presenting first-mover advantages for scheduled maintenance providers.
- Sensor-integrated cleaning:IoT-enabled carpet wear monitors can trigger automated service dispatch before visible soiling occurs, converging facilities management with predictive analytics.
- Brazil hospitality expansion:International hotel chains entering São Paulo and Rio de Janeiro seek EPA-aligned sanitation partners for brand-standard compliance.
Industry Challenges
- Wastewater containment compliance:EPA discharge regulations for extraction effluent containing detergents and suspended solids require capital investment in closed-loop recovery systems.
- Fragmented subcontractor networks:National brands rely on independent operator fulfillment for rural and secondary metro coverage, creating quality control and insurance liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carpet and Upholstery Cleaning Services Market |
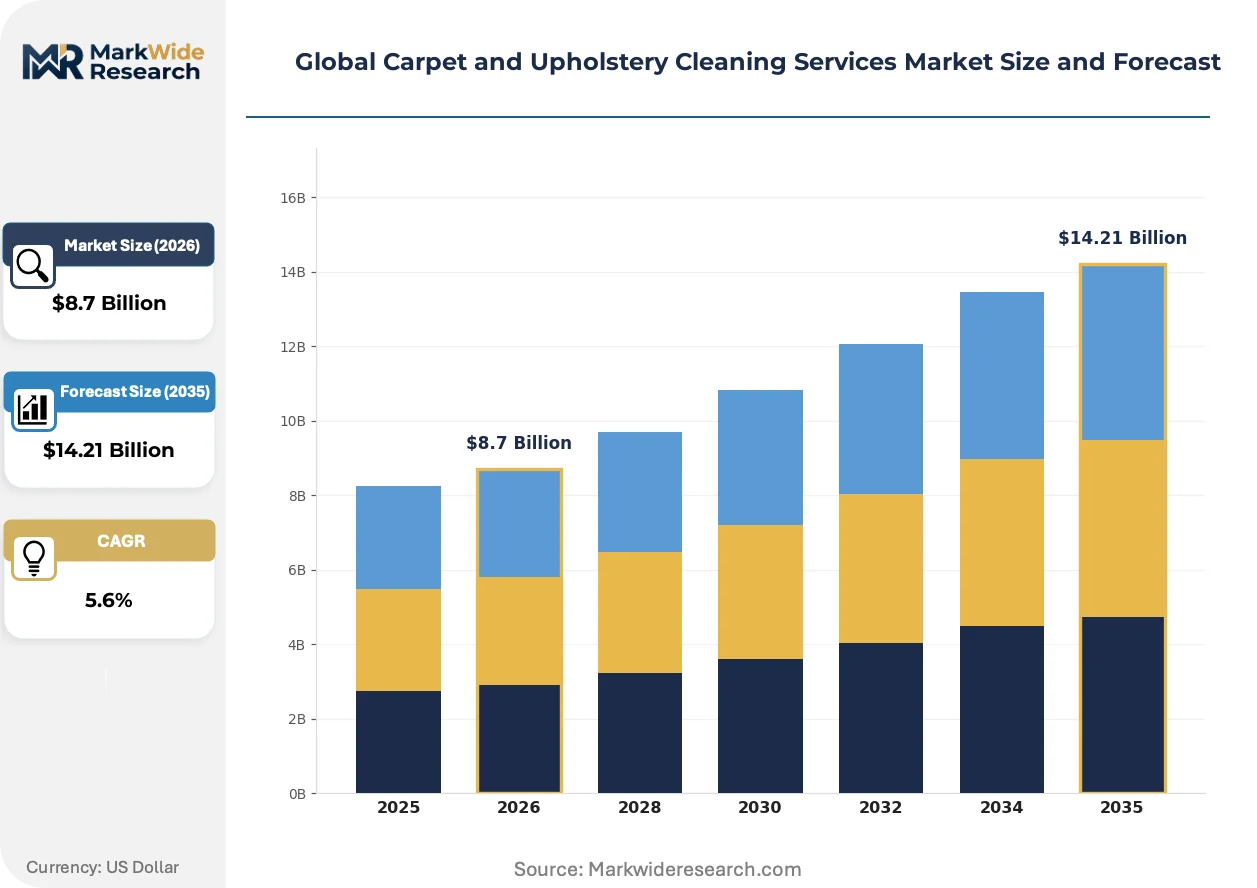
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Steam Cleaning, Dry Cleaning, Shampooing, Bonnet Cleaning End User: Residential, Commercial, Industrial, Hospitality Technology: Hot Water Extraction, Absorbent Pad, Carbonating Cleaners, VLM Application: Carpets, Rugs, Upholstery, Mattresses |
| Companies Covered | ServiceMaster Clean, Stanley Steemer, Chem-Dry, COIT, Servpro, Oxi Fresh, Rainbow International, ABM Industries Inc., Jani-King International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carpet and Upholstery Cleaning Services Market Emerging Trajectories
Equipment manufacturers and chemistry suppliers are racing to deliver portable systems that match truck-mounted performance while satisfying tightening discharge regulations and labor mobility constraints.
Encapsulation polymer technology is miniaturizing commercial cleaning operations by enabling battery-powered orbital machines to deliver crystallizing detergent performance previously requiring heated extraction rigs. Boutique hotels and co-working operators in Tokyo and Singapore are adopting these units for daytime maintenance without guest disruption. The shift is compressing capital barriers for new market entrants and fragmenting service provision toward smaller geographic territories.
REACH chemical authorization procedures are extending formulation approval timelines for enzyme-based pre-spray agents, forcing European operators to maintain dual inventory of legacy and next-generation products during transition periods. The regulatory friction most affects multi-national contract cleaners serving cross-border hospitality chains, who must harmonize service protocols across jurisdictions with divergent substance restrictions.
Facility managers are unbundling carpet maintenance from bundled janitorial contracts and issuing standalone RFPs with IICRC-certified performance specifications. Property management groups in the United States and Germany now separate textile surface care from hard-floor and restroom services, creating dedicated vendor relationships with specialized extraction providers. This procurement fragmentation is most advanced in healthcare-adjacent commercial real estate, where infection control documentation requirements exceed general cleaning contractor capabilities.
Global Carpet and Upholstery Cleaning Services Market Segmentation
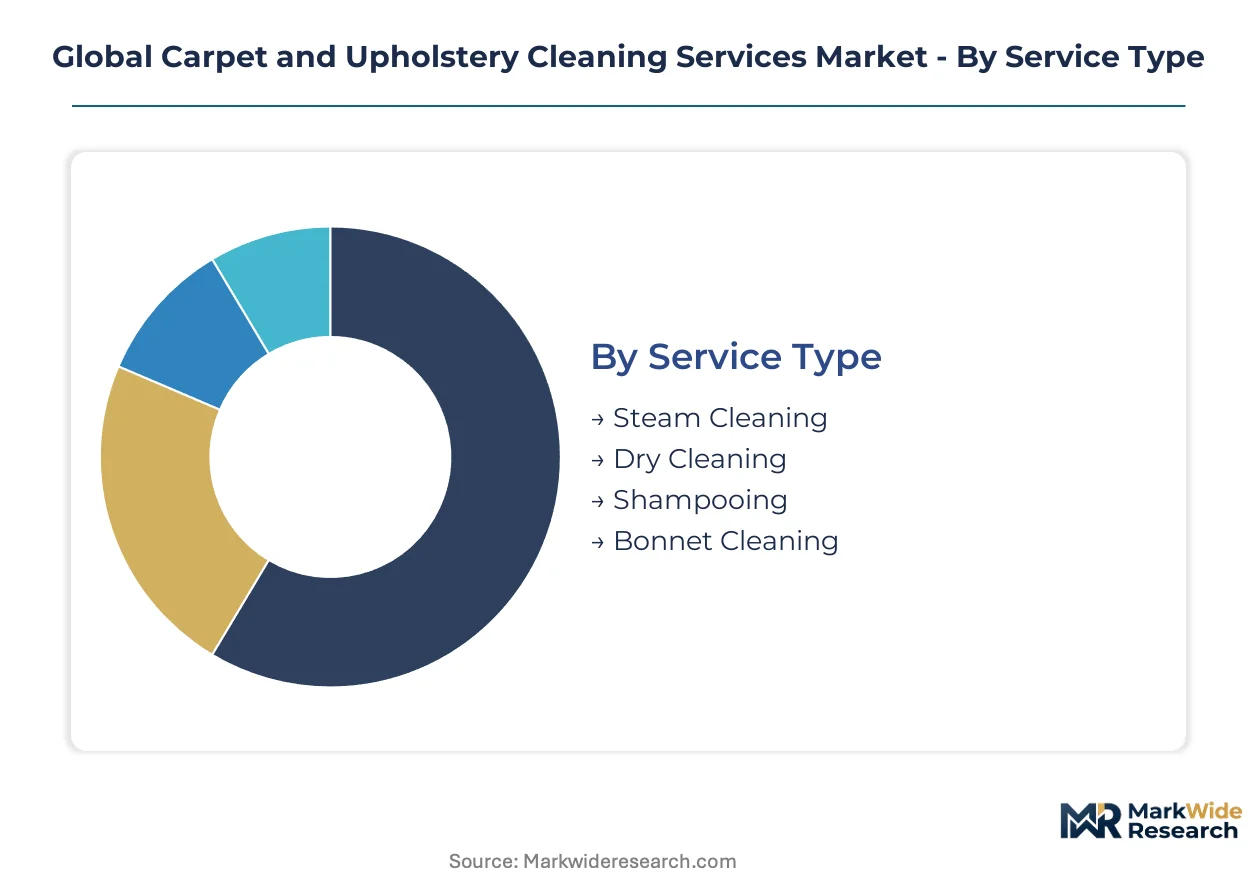
Service providers compete across divergent technical specifications, end-use requirements, and regulatory compliance thresholds. Segmentation reveals where capital intensity concentrates and where low-moisture innovations are compressing operational barriers.
Service Type:
Regulatory differentiation separates EPA-mandated deep extraction protocols from discretionary maintenance services.
- Steam Cleaning:Hot water extraction at 150°F-plus temperatures penetrates dense pile for OSHA-compliant sanitation in US commercial buildings. Federal workplace mandates specify quarterly protocols for high-occupancy zones, sustaining contract value in property management portfolios.
- Dry Cleaning:Absorbent compound systems operate without wastewater discharge, bypassing EPA effluent containment requirements that burden extraction-based competitors. Demand concentrates in European facilities where REACH chemical restrictions complicate detergent recovery.
- Shampooing:Rotary brush agitation with foam detergents persists in budget residential segments where drying times matter less than per-room cost.
- Bonnet Cleaning:Surface-level pad systems serve interim maintenance contracts in hospitality corridors between deep extraction cycles.
Established volume favors steam cleaning; emerging adoption favors dry cleaning.
End User:
Customer type determines service frequency, certification requirements, and contract structure.
- Commercial:Property management groups in the United States and Germany unbundle textile care from bundled janitorial contracts, issuing standalone RFPs with IICRC-certified performance specifications. OSHA indoor air quality mandates enforce quarterly deep extraction, creating recurring revenue anchors.
- Hospitality:Hotel operators in Tokyo and Singapore adopt encapsulation polymer systems for four-hour drying windows that prevent room inventory loss during peak booking periods. Very low moisture technology is climbing the fastest in this segment.
- Residential:Direct-to-consumer scheduling platforms drive demand for carbonating systems that minimize disruption to occupied dwellings.
- Industrial:Manufacturing facilities face EPA discharge regulations for extraction effluent containing suspended solids, requiring closed-loop recovery capital investment.
Contract value concentrates in commercial; operational innovation concentrates in hospitality.
Technology:
Water consumption and drying chemistry differentiate competitive positioning.
- Hot Water Extraction:Truck-mounted and portable systems operating at 100-500 PSI deliver regulatory-compliant sanitation for healthcare-adjacent commercial real estate. Equipment supply concentrates with specialized pump manufacturers in northern Italy and southwestern Germany.
- VLM:Very low moisture encapsulation enables battery-powered orbital machines to deliver crystallizing detergent performance without heated extraction rigs, fragmenting service provision toward smaller geographic territories.
- Carbonating Cleaners:Plant-derived surfactant formulations reduce water consumption sixty percent versus traditional extraction, aligning with EU Green Deal resource efficiency targets.
- Absorbent Pad:Bonnet systems serve interim maintenance with minimal technician training barriers.
Performance certification favors hot water extraction; capital accessibility favors VLM.
Application:
Surface material and soiling depth dictate equipment selection and chemistry formulation.
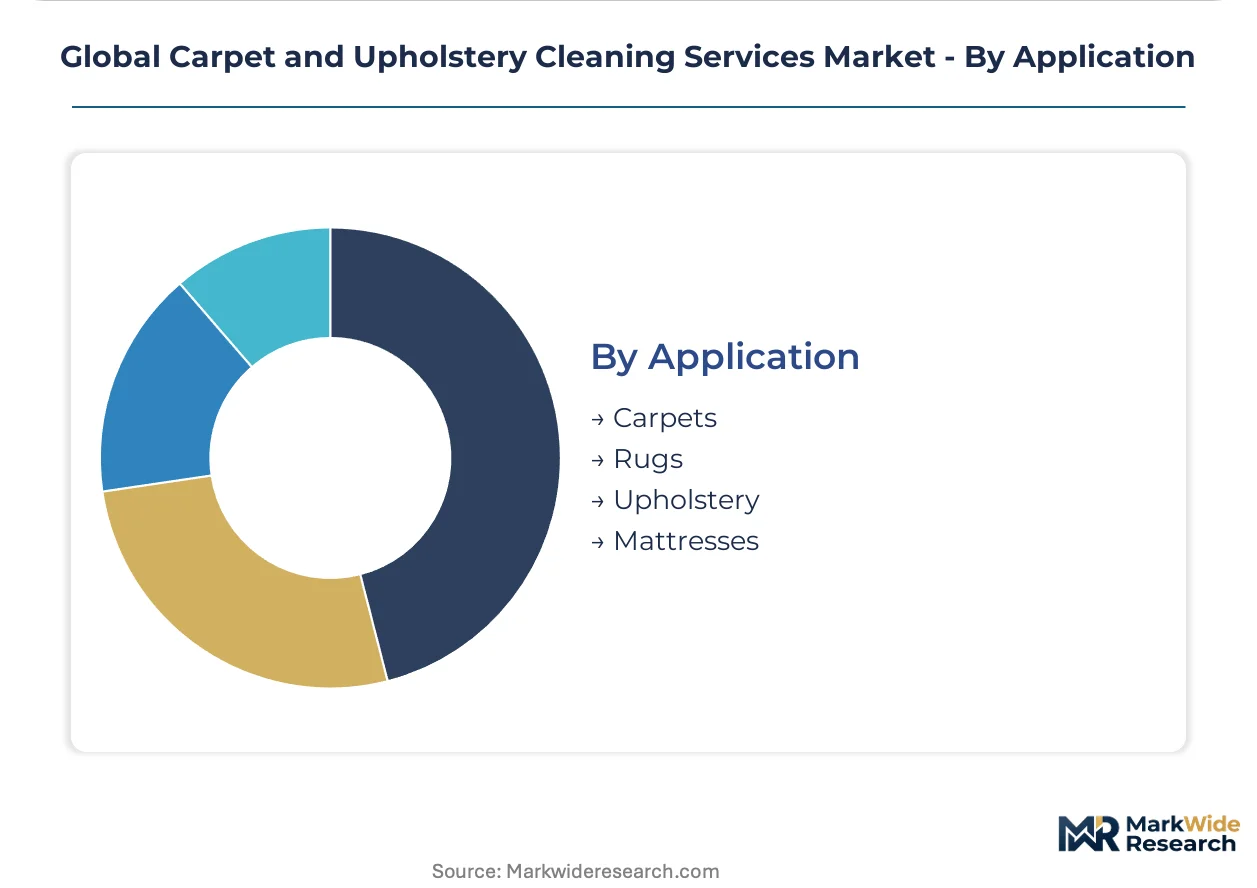
- Carpets:Dense pile in US commercial buildings requires penetrating extraction for allergen removal under EPA indoor air quality guidelines.
- Upholstery:Fabric furniture in hospitality settings demands low-moisture protocols to prevent fiber damage and extended drying.
- Rugs:Specialty wool and silk compositions in residential markets require pH-controlled cleaning agents.
- Mattresses:Healthcare-adjacent facilities in Germany specify infection control documentation exceeding general contractor capabilities.
Regulatory complexity favors carpet; margin expansion favors mattress specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American service logistics, while the Rhine-Main corridor connects German industrial demand to Benelux chemistry suppliers. Japan's Shinkansen freight network enables rapid-response hospitality contracts across the archipelago.
United States
Commercial property managers in Chicago and Dallas issue standalone textile maintenance RFPs as OSHA workplace sanitation mandates enforce quarterly deep extraction protocols. EPA indoor air quality guidelines specify high-occupancy zone treatment frequencies that sustain recurring contract value. ServiceMaster Clean leverages its national franchise network to capture hotel chain and property management group volume across these metropolitan clusters.
Germany
REACH chemical restrictions push operators toward enzyme-based pre-spray agents and plant-derived surfactants in Frankfurt and Munich commercial portfolios. The EU Green Deal resource efficiency targets accelerate carbonating cleaner adoption that reduces water consumption sixty percent versus traditional extraction. Equipment supply concentrates with specialized pump manufacturers in southwestern Germany serving truck-mounted system operators.
Japan
Hospitality operators in Tokyo and Osaka adopt four-hour drying encapsulation systems to prevent room inventory loss during peak booking periods. METI building maintenance codes sustain recurring cleaning mandates across aging commercial real estate stock. Very low moisture technology captures its fastest expansion in these hospitality corridors where inventory turnover determines profitability.
India
Grade-A office stock in Mumbai and Bangalore lacks established service contracts, presenting first-mover advantages for scheduled maintenance providers entering these markets. BIS standards for indoor environmental quality are tightening as international property investors demand compliance documentation. National brands rely on independent operator fulfillment for secondary metro coverage, creating quality control exposure in these emerging clusters.
Brazil
International hotel chains entering São Paulo and Rio de Janeiro seek sanitation partners for brand-standard compliance aligned with EPA protocols. ANVISA pharmaceutical-grade facility requirements extend to hospitality-adjacent healthcare real estate, fragmenting procurement toward specialized extraction providers. The country's national environmental regulator is drafting discharge standards that will require closed-loop recovery capital investment from extraction-based competitors.
Global Carpet and Upholstery Cleaning Services Market Vendor Landscape
Concentration sits with national franchise networks that compress customer acquisition costs through recurring commercial contracts. The vendor base spans three tiers: integrated facility management conglomerates, specialized textile cleaning franchises, and regional independent operators serving secondary metros. Two strategic archetypes dominate competitive positioning: chemistry-technology licensors that differentiate through proprietary formulations, and scale-driven service aggregators that optimize route density and technician utilization. Dominant competitive moves include strategic partnerships with property management platforms and geographic expansion through franchisee recruitment in underpenetrated metros.
Among North American service aggregators, ServiceMaster Clean and Stanley Steemer exemplify contrasting scale strategies. ServiceMaster Clean anchors commercial demand through national account relationships with hospitality chains and property management groups. Stanley Steemer occupies a position on the residential-direct vector, optimizing direct-to-consumer scheduling platforms and technician training programs. Chem-Dry represents the chemistry-licensor archetype, differentiating through carbonating cleaner technology that reduces water usage and drying times.
| Leading Market Players |
|---|
| ServiceMaster Clean |
| Stanley Steemer |
| Chem-Dry |
| COIT |
| Servpro |
| Oxi Fresh |
| Rainbow International |
| ABM Industries Inc. |
| Jani-King International Inc. |
| Others |
Supply Flow & Price Mechanics
Encapsulation polymer chemistry replacing hot water extraction equipment simultaneously shifts manufacturing gravity toward Italian and German pump specialists while compressing capital barriers for new service entrants. This substitution dynamic fragments pricing power across equipment tiers as battery-powered orbital machines democratize access to commercial-grade performance.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between national franchise networks and property management portfolios. Three-tier pricing separates IICRC-certified deep extraction protocols from interim maintenance services and emergency spot treatments. Cost compression in standard-tier hospitality contracts intensifies as VLM technology reduces labor hours per room. Small independent operators exhibit highest price sensitivity; healthcare-adjacent commercial real estate shows lowest sensitivity due to infection control documentation requirements.
Supply Chain Analysis
Italy and Germany anchor specialized pump manufacturing for truck-mounted extraction systems operating at 100-500 PSI. Commercial-grade equipment production draws from stainless steel casting foundries in northern Italy and precision machining clusters in southwestern Germany. Single-source vulnerability concentrates in high-pressure pump assemblies where two European suppliers dominate global output. Distribution runs through authorized dealer networks serving independent operators and direct procurement channels for national franchise fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA quarterly extraction mandates create a high-growth disruption as reactive spot-cleaning yields to predictive maintenance contracts. This regulatory inflection compresses customer acquisition costs while extending lifetime value for positioned providers.
For Market Incumbents: Consolidate fragmented subcontractor networks in secondary metros through selective acquisition of IICRC-certified independent operators. Lock in route density advantages by embedding sensor-integrated cleaning platforms into property management software stacks before emerging technology vendors capture facilities management convergence.
For New Entrants and Emerging Players: Anchor in Mumbai and Bangalore Grade-A office stock where scheduled maintenance contracts remain unestablished. Target hospitality-adjacent healthcare real estate in Brazil where ANVISA pharmaceutical-grade requirements fragment procurement toward specialized extraction providers. Lead with carbonating cleaner technology to differentiate on EU Green Deal alignment and water efficiency metrics.
For Investors and Strategic Acquirers: REACH chemical authorization timelines reshaping the acquisition landscape favor targets with dual inventory capabilities spanning legacy and enzyme-based formulations. Long-term viability hinges on chemistry-technology licensors with proprietary surfactant IP rather than scale-driven service aggregators facing technician scarcity constraints. Monitor PFAS regulatory clarity as the signal indicating when stain-resistant treatment reformulation investments will convert to competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Platform Development | IoT-enabled carpet wear monitors trigger automated dispatch before visible soiling occurs. |
| Franchise Network Consolidation | Selective acquisition of IICRC-certified independents secures secondary metro coverage. |
| Carbonating Chemistry Licensing | Plant-derived surfactant formulations align with EU Green Deal resource efficiency targets. |
| Closed-Loop Recovery System Deployment | EPA discharge compliance for extraction effluent requires capital investment in containment infrastructure. |
| Healthcare Specialization Certification | Infection control documentation capabilities exceed general janitorial contractor service thresholds. |
Methodological Framework
Operator-level perspectives from franchise operations directors, property management procurement leads, hospitality facilities managers, IICRC certification instructors, and chemistry formulation specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, OSHA workplace sanitation guidance documents, REACH substance restriction updates, and hospitality industry procurement RFP archives. Bottom-up service provider capacity estimates triangulated against top-down commercial real estate stock assessments.
Sensitivity analysis tested forecast outputs against variable technician certification rates, equipment capital cost trajectories, and regulatory enforcement intensity assumptions across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology platform, and application surface with geographic regulatory cluster overlays. CAGRs derived from historical contract value trajectories adjusted for mandated service frequency changes and technology substitution elasticities.
Decision-makers should treat outputs as directional under stable OSHA enforcement and REACH authorization timelines; material deviation in PFAS regulatory clarity or equipment supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in indoor air quality mandate enforcement and chemistry authorization proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Laundry Care Market