
 Dry and Wet Wipes Market | 2026-2036
Dry and Wet Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Dry and Wet Wipes Market Intelligence
The consolidation of purchasing power among large retail chains and institutional buyers like hospital networks is recalibrating supply chain negotiations. Kimberly-Clark Corporation leverages its extensive distribution network to maintain shelf space. Procter & Gamble competes on brand loyalty and product innovation in the baby wipes segment. Rockline Industries specializes in private-label manufacturing for major retailers.
Dry and wet wipes consist of a substrate, typically a nonwoven fabric, which is either sold dry or pre-moistened with a solution containing ingredients like surfactants, cleansers, or disinfectants. Their primary function is to provide convenient, single-use application for personal care, cleaning, or medical use. Baby wipes continue to represent a mature, high-volume category, while antibacterial wipes for household cleaning show significant growth. The choice of nonwoven fabric material directly influences product cost, texture, and environmental impact.
Product formulation and labeling are governed by agencies like the US FDA for wipes marketed with medical claims and the EU's ECHA under REACH for chemical safety. European regulations, including the Single-Use Plastics Directive, also mandate specific labeling for products containing plastic and push for material alternatives. Navigating the dual pressures of cost-effective manufacturing and evolving environmental regulations is the central strategic challenge for all producers.
Market Dynamics
The central tension in the wipes market is the conflict between surging demand for single-use convenience, especially in healthcare, and mounting regulatory pressure from bodies like the European Commission to mitigate plastic waste from nonwoven fabrics.
Growth Catalysts
- Elevated Hygiene Protocols:Stricter infection control standards in hospitals and clinics worldwide are increasing the institutional consumption of disinfectant and antibacterial wipes.
- Urbanization in Asia:Rapidly expanding middle-class populations in major urban centers across India and Indonesia drive demand for convenient personal hygiene products.
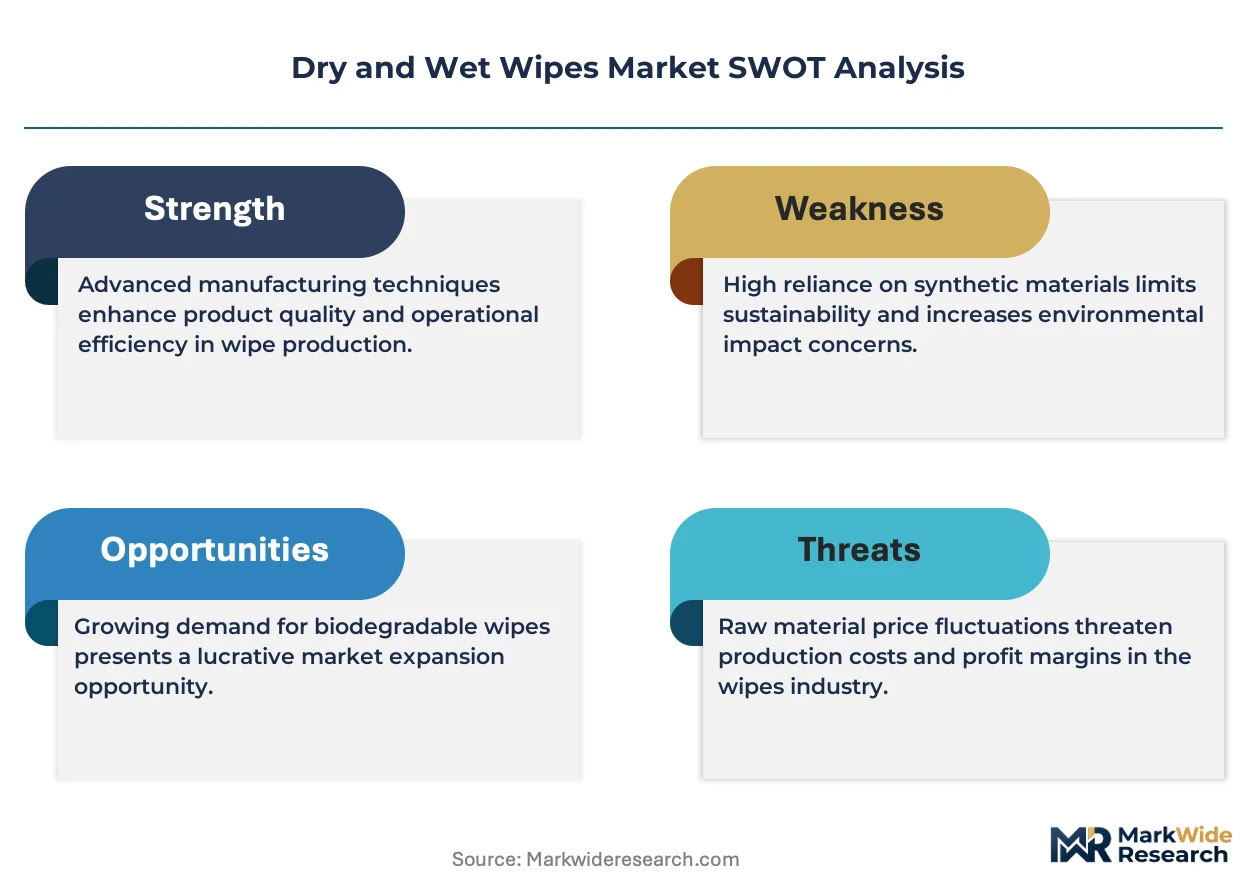
- Biodegradable Materials:Innovation in nonwoven fabrics made from lyocell, viscose, and other pulp-based fibers provides a solution to plastic-related environmental concerns.
Market Restraints
- Raw Material Volatility:Price fluctuations for key inputs like polypropylene, polyester, and wood pulp directly impact manufacturing costs and compress producer margins.
- Complex Chemical Regulations:Adherence to chemical safety frameworks like the EU's REACH requires extensive testing and documentation, adding cost and complexity to product development.
- Plastic-Focused Legislation:The EU's Single-Use Plastics Directive imposes labeling requirements and extended producer responsibility costs on many wipe products, constraining design and increasing operational expenses.
Strategic Opportunities
- Water-Activated Dry Wipes:Developing solid-state or concentrated formulas in a dry wipe format appeals to sustainability trends by reducing water transport and packaging.
- Male-Specific Grooming Segment:Targeting the underpenetrated male demographic with specialized products for facial cleansing, post-shave care, and body refreshment offers a clear growth avenue.
- Direct-to-Consumer Subscriptions:Building subscription-based models for high-volume categories like baby or cleaning wipes allows brands to bypass retail and foster customer loyalty.
Industry Challenges
- Disposal and Flushability Education:Combating consumer misinformation about which products are sewer-safe is a persistent challenge, with incorrect disposal leading to costly municipal infrastructure damage.
- Supply Chain Verification:Auditing and ensuring the authenticity of sustainability claims, such as FSC certification for wood pulp, requires significant investment in supply chain transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry and Wet Wipes Market |
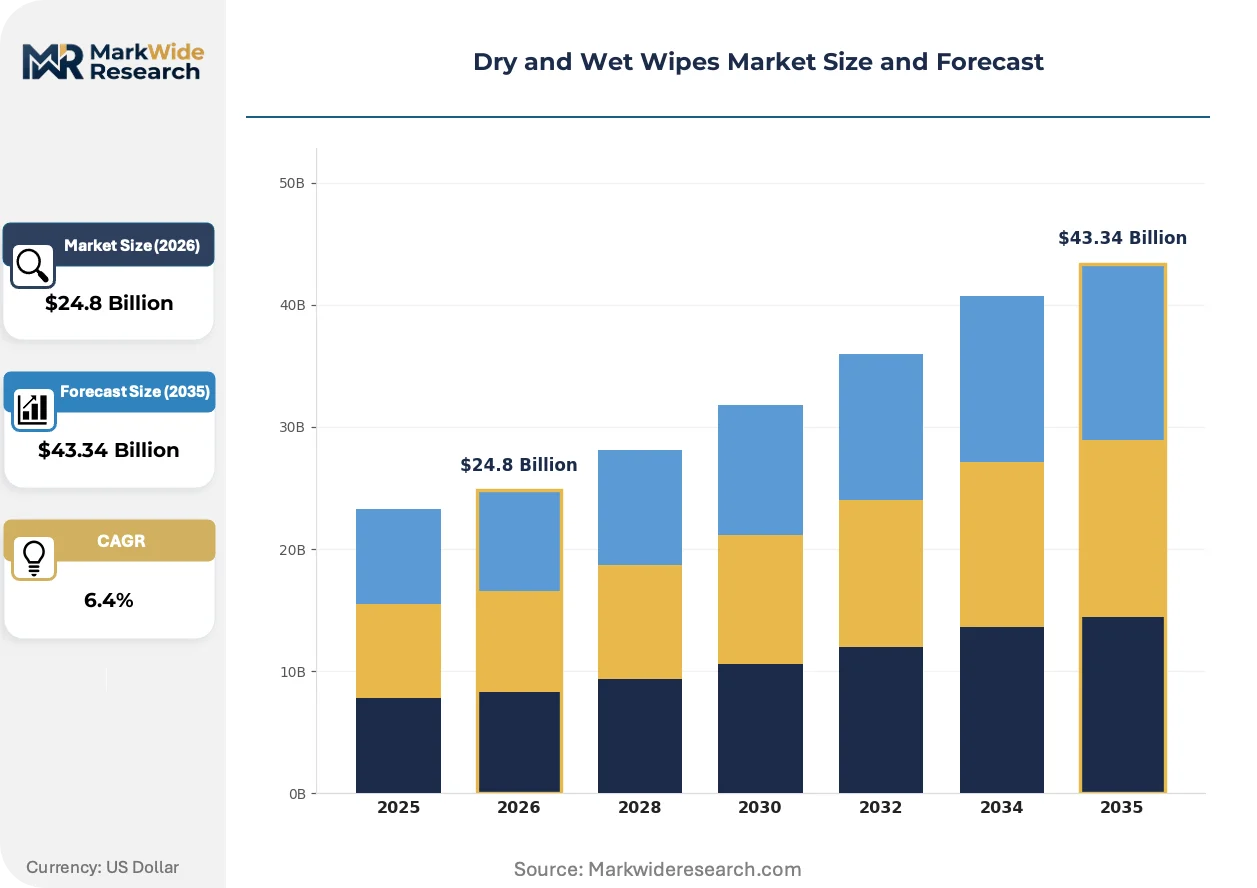
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Wipes, Reusable Wipes, Antibacterial Wipes, Baby Wipes Material: Nonwoven Fabric, Cotton, Paper, Plastic End User: Households, Healthcare Facilities, Industrial, Hospitality Application: Personal Care, Household Cleaning, Medical Use, Automotive |
| Companies Covered | Kimberly-Clark Corporation, Clorox Company, Nice-Pak Products, Inc., Albaad Massuot Yitzhak, S.C. Johnson & Son, Rockline Industries, Procter & Gamble, Zhejiang Aijian Sanitary Products Technology Co., Ltd., Diamond Wipes International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry and Wet Wipes Market Strategic Shifts & Innovations
Material science innovation is fundamentally altering product composition, driven by a dual mandate for enhanced performance and environmental compatibility. This forces a re-evaluation of substrate and formulation choices across all product categories, from personal care to industrial cleaning.
Smart-release formulations encapsulate active ingredients like moisturizers or disinfectants within the wipe substrate. Premium skincare and medicated wipe segments are the primary adopters of this controlled-release approach. This advanced delivery mechanism is converging with sensor technology, creating pathways for diagnostic wipes that provide real-time feedback on surface or skin conditions.
The European Union's Single-Use Plastics Directive imposes specific obligations on wipes containing plastic fibers. This regulation mandates conspicuous on-pack marking to inform consumers about plastic content and proper disposal. The personal care and household cleaning wipe categories sold within the EU are most impacted, accelerating investment in plastic-free alternatives like viscose and lyocell.
Consumer purchasing decisions are increasingly influenced by third-party certifications for sustainability and skin safety. This shift disadvantages uncertified private-label goods, creating an advantage for brands that achieve and market seals like FSC or ECOCERT. This behavior is most pronounced in the baby care and cosmetic wipe segments across North American and European markets.
Dry and Wet Wipes Market Segmentation
Understanding the distinct segments within the dry and wet wipes market reveals critical pathways for product development and market penetration. Each category presents unique consumer expectations, regulatory compliance challenges, and material science opportunities. Strategic market positioning hinges on tailoring product features and distribution channels to specific end-user needs.
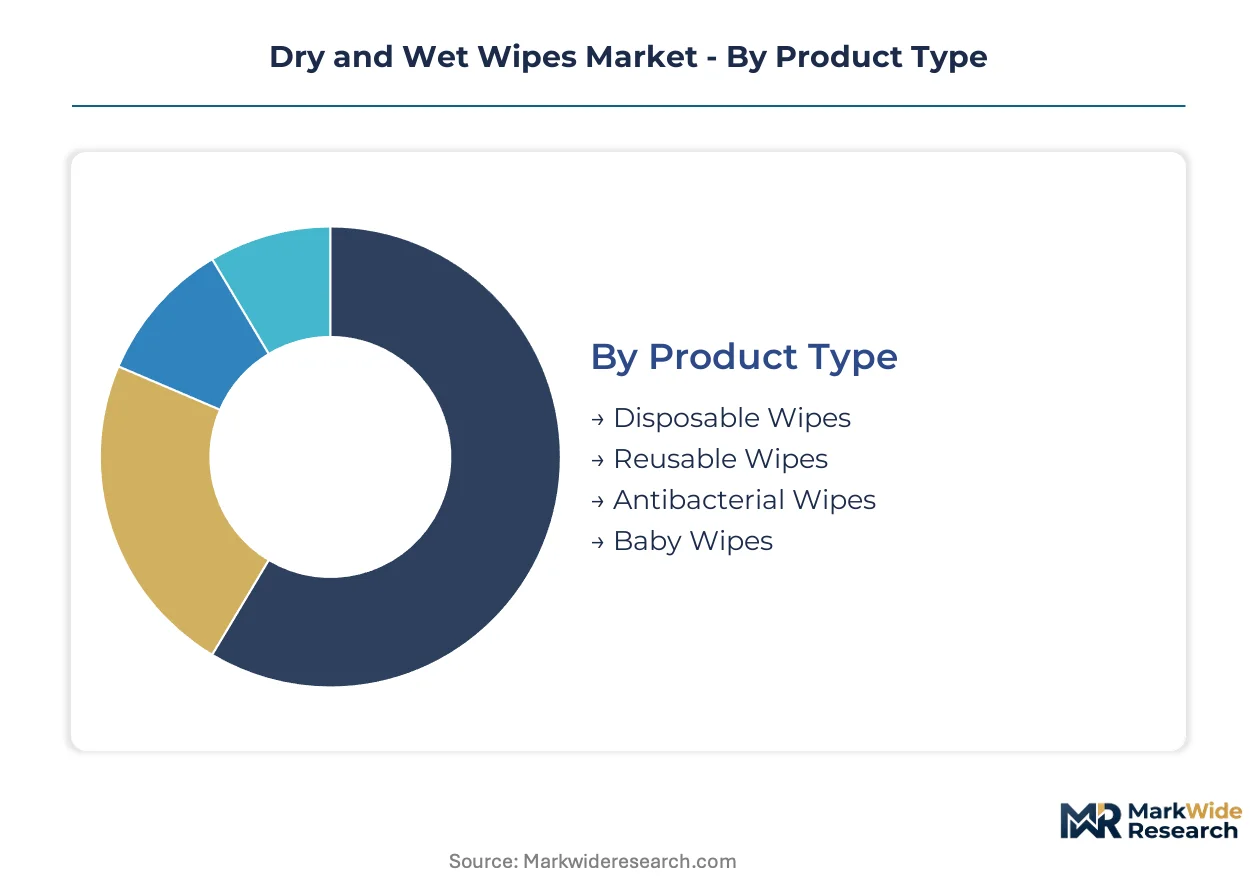
Product Type:
The product type segmentation highlights how consumers often cycle through different wipe formats based on evolving hygiene needs and convenience preferences.
- Antibacterial Wipes:These wipes are pre-moistened with disinfectants like quaternary ammonium compounds, providing efficacy against bacteria and viruses on surfaces. Demand concentrates in healthcare facilities and public spaces, driven by elevated infection control protocols and health consciousness.
- Baby Wipes:Typically soft, pre-moistened nonwoven fabrics infused with gentle cleansers and moisturizers for infant skin care. This high-volume segment sees stable demand across all major urban centers, supported by parental emphasis on convenience and hygiene.
- Disposable Wipes:Designed for single-use applications, these wipes offer maximum convenience and hygiene, particularly in public and medical settings.
- Reusable Wipes:Made from durable fabrics, these wipes are intended for multiple uses after washing, appealing to environmentally conscious consumers for household cleaning tasks.
Baby Wipes sits at the top of the volume ranking, with Antibacterial Wipes climbing the fastest.
Material:
Material choices directly influence the cost structure and performance characteristics across the dry and wet wipes product range.
- Nonwoven Fabric:Comprising entangled fibers like polyester, polypropylene, or cellulosic blends, nonwoven fabrics form the primary substrate for most wipes, offering strength and absorbency. Innovation in plastic-free nonwovens made from lyocell and viscose addresses environmental regulations across Europe.
- Cotton:A natural cellulosic fiber known for its softness, absorbency, and hypoallergenic properties, cotton is often used in premium personal care and baby wipe formulations. Demand for cotton wipes is notable in North American and European cosmetic wipe segments.
- Paper:Typically made from wood pulp, paper-based wipes offer biodegradability and cost-effectiveness, commonly found in household cleaning and some personal hygiene applications.
- Plastic:Synthetic polymers such as polypropylene and polyester provide durability and strength, though their presence in wipes faces increasing regulatory scrutiny under directives like the EU's Single-Use Plastics Directive.
Nonwoven Fabric materials dictate the base manufacturing expense, with Cotton commanding a higher price differentiation due to its natural properties.
End User:
The end-user segmentation reveals distinct purchasing behaviors and product requirements, from bulk institutional procurement to individual household consumption patterns.
- Healthcare Facilities:Hospitals, clinics, and long-term care centers require specialized disinfectant and antibacterial wipes for infection control and patient care. Stricter hygiene protocols globally ensure sustained high-volume procurement from these institutions.
- Households:Individual consumers purchase a diverse range of wipes for personal hygiene, baby care, and general household cleaning. Urbanization in India and Indonesia fuels demand for convenient single-use products in this segment.
- Industrial:This segment includes manufacturing plants, workshops, and commercial cleaning services, utilizing heavy-duty wipes for equipment maintenance, spill cleanup, and surface preparation.
- Hospitality:Hotels, restaurants, and catering services use wipes for guest amenities, surface sanitation, and quick cleanups, prioritizing convenience and hygiene standards.
Procurement patterns for Healthcare Facilities often involve long-term contracts, while Household purchases are driven by retail availability and brand loyalty.
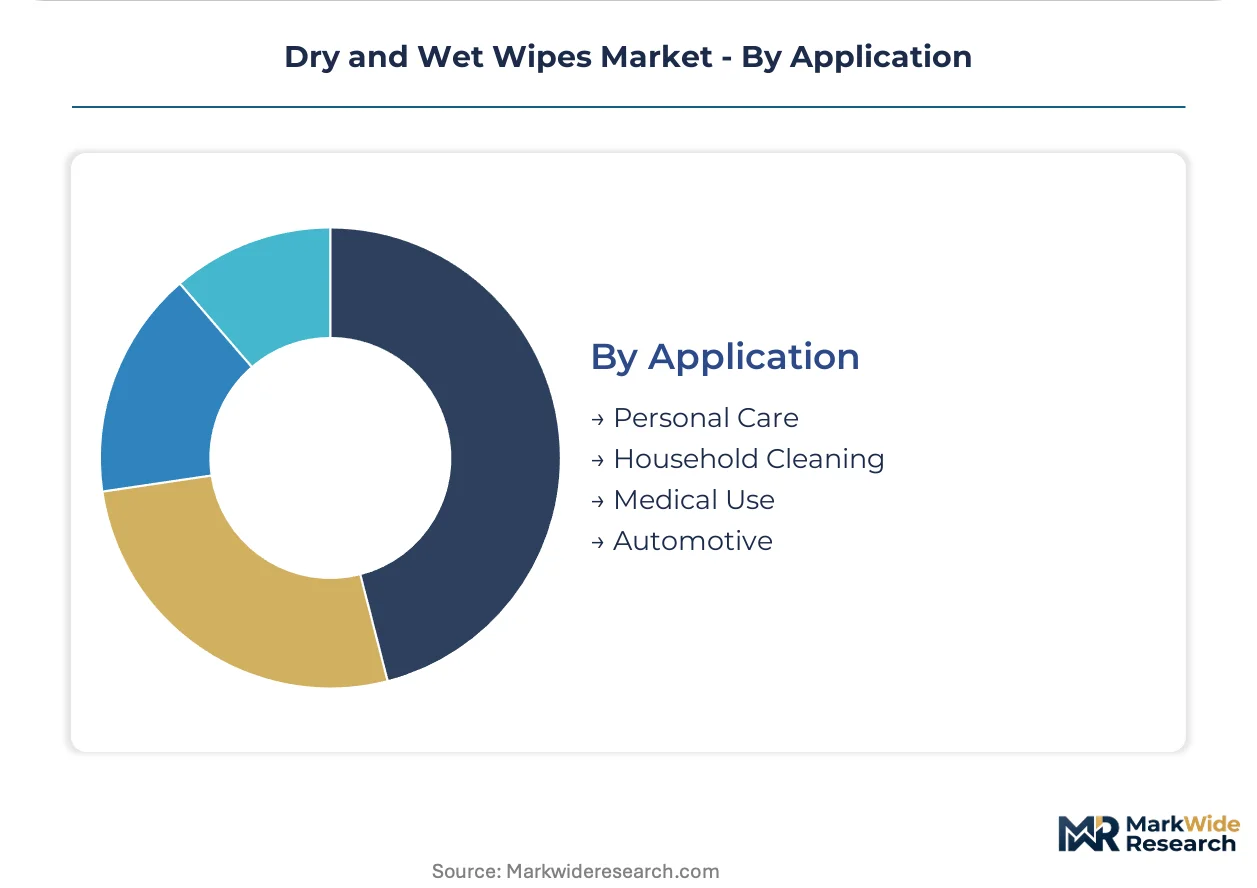
Application:
Application areas dictate specific product formulations, material characteristics, and regulatory compliance requirements for dry and wet wipes.
- Medical Use:Wipes designed for wound care, skin antisepsis, and instrument disinfection in clinical environments, often regulated by agencies like the US FDA for medical claims. Demand is surging due to heightened infection control standards.
- Personal Care:Encompasses facial cleansing wipes, makeup removers, feminine hygiene wipes, and adult body wipes, emphasizing skin compatibility and gentle formulations. This category demonstrates significant innovation in smart-release and biodegradable substrates.
- Household Cleaning:Wipes for surface disinfection, dusting, and general cleaning tasks within residential settings, balancing efficacy with cost-effectiveness.
- Automotive:Specialty wipes for interior and exterior car cleaning, polishing, and detailing, requiring specific formulations for various surfaces without leaving residue.
The Personal Care segment generates the largest volume, while Medical Use applications face the most stringent environmental impact assessments due to disposal protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's burgeoning middle class drives significant demand for personal hygiene wipes, while the United States focuses on specialized medical and household cleaning applications. European Union regulations push for sustainable material innovation, influencing product development across the continent. Southeast Asian markets, particularly Indonesia, exhibit robust growth for convenient personal care products.
United States
Healthcare facilities increase institutional consumption of disinfectant wipes, and personal care segments show steady growth. The US FDA regulates wipes with medical claims, ensuring product safety and efficacy standards. California's innovation hubs see development of premium skincare and diagnostic wipes, leveraging advanced material science.
Germany
Strict hygiene protocols in German healthcare facilities elevate demand for antibacterial wipes, alongside a strong market for eco-friendly household cleaning solutions. The EU's Single-Use Plastics Directive and ECHA's REACH framework significantly influence product formulation and labeling for wipes sold in Germany. The Rhine-Ruhr region's chemical industry supports nonwoven fabric innovation, focusing on biodegradable alternatives like viscose and lyocell.
India
Rapid urbanization and rising disposable incomes in India fuel demand for convenient personal hygiene products, especially baby wipes and facial cleansing wipes. The Bureau of Indian Standards (BIS) establishes quality and safety norms for consumer goods, including wet wipes. Major urban centers like Mumbai and Delhi witness high consumption volumes, with local manufacturers expanding production capacities.
Indonesia
A large, youthful population and increasing health consciousness in Indonesia drive the consumption of baby wipes and personal care wipes. National health agencies regulate product safety and ingredient labeling for wipes distributed across the Indonesian archipelago. Jakarta and Surabaya serve as key distribution and manufacturing hubs, catering to the country's expanding consumer base.
China
China's vast consumer market shows strong demand for both baby wipes and household cleaning wipes, driven by convenience and hygiene trends. China's NMPA oversees the safety and efficacy of personal care and medical wipes, while GB standards define product quality. The Yangtze River Delta region hosts significant manufacturing capabilities and distribution networks for wipe products, serving domestic and export markets.
Dry and Wet Wipes Market Key Industry Players
North American producers anchor one tier of the dry and wet wipes market; European specialists hold significant positions in sustainable product development. The market exhibits a tiered structure, with global conglomerates competing on scale and brand recognition, while regional manufacturers focus on niche applications. Private-label specialists cater to retail demand, emphasizing cost-effective production. Three strategic archetypes emerge: integrated giants, specialized innovators, and private-label manufacturers. Portfolio diversification into new material science and strategic partnerships for distribution are dominant competitive moves.
Among the global integrated giants, Kimberly-Clark Corporation and Procter & Gamble exemplify extensive distribution networks and strong brand loyalty, particularly in the baby wipes segment. Kimberly-Clark Corporation leverages its established presence to maintain shelf space across diverse retail channels. Procter & Gamble, a US-based consumer goods corporation, consistently drives product innovation, especially for personal care wipes. Rockline Industries, another US-headquartered entity, occupies a significant position as a specialized private-label manufacturer, serving major retailers with tailored wipe solutions. These companies collectively demonstrate the market's reliance on both proprietary brands and efficient private-label supply.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Clorox Company |
| Nice-Pak Products, Inc. |
| Albaad Massuot Yitzhak |
| S.C. Johnson & Son |
| Rockline Industries |
| Procter & Gamble |
| Zhejiang Aijian Sanitary Products Technology Co., Ltd. |
| Diamond Wipes International Inc. |
| Others |
Cost & Logistics Intelligence
Polypropylene futures volatility cascades through the dry and wet wipes supply chain, influencing manufacturing costs and downstream pricing tiers. This market navigates material expense fluctuations while addressing diverse end-user demands across global regions.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade wipes. Pricing stratifies across premium, standard, and economy tiers, reflecting quality grade, brand premium, and certification level. Cost compression in the household segment intensifies due to raw material price volatility and increasing regulatory compliance expenses. Healthcare facilities exhibit lower price sensitivity compared to individual household consumers, prioritizing performance and efficacy over cost.
Supply Chain Analysis
Reverse logistics for single-use wipes primarily involves waste management infrastructure, with increasing pressure for compostable or recyclable waste streams. Geographic supply concentration for nonwoven fabrics centers in China, the United States, and Germany, alongside raw material dependencies on polypropylene, polyester, and wood pulp. Regulatory restrictions, such as the EU's Single-Use Plastics Directive, represent a structural supply chain risk. Distribution runs through both large retail chains for household goods and direct institutional procurement for healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, with less stringent environmental regulations outside the European Union offering manufacturing cost advantages for conventional wipe products.
For Market Incumbents: Acquire specialized nonwoven fabric technology firms focused on biodegradable materials. Invest in research and development for plastic-free substrates to mitigate evolving environmental regulations and counter emerging sustainable material entrants. Deepen vertical integration into cellulosic fiber production. Strengthen distribution channels in high-growth urban centers across India and Indonesia.
For New Entrants and Emerging Players: Begin with targeted product development for underpenetrated segments, such as male-specific grooming wipes or water-activated dry formats. Focus initial market penetration on urban areas of Southeast Asia, leveraging the rising middle-class demand for convenient personal care. Implement direct-to-consumer subscription models emphasizing sustainability certifications like FSC or ECOCERT for brand differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized innovators in plastic-free nonwoven fabrics and smart-release formulation technologies. The long-term viability of the wipes market depends on a successful transition to environmentally compatible materials and advanced delivery mechanisms. Target acquisition profiles include companies with patented biodegradable substrate technologies or established direct-to-consumer channels. Practitioners should monitor adoption rates of EU SUPD-compliant products outside Europe for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Sustainable Nonwovens | Increases supply of compliant materials, reducing reliance on conventional plastics. |
| Direct-to-Consumer Launch for Niche Wipes | Bypasses traditional retail, fostering brand loyalty and direct customer feedback. |
| Material Science R&D Investment | Develops next-generation plastic-free substrates with enhanced performance characteristics. |
| Sustainability Certification Program Enrollment | Builds consumer trust and meets evolving regulatory and purchasing requirements. |
| Distribution Channel Expansion in Emerging Markets | Captures demand from rapidly urbanizing populations with increasing disposable incomes. |
Research Approach
Multiple input streams — primary interviews, secondary market intelligence, regulatory filings — were reconciled to construct a comprehensive market view. This involved engaging R&D directors at nonwoven manufacturers, procurement managers at hospital networks, brand managers at consumer goods companies, and sustainability officers. Secondary validation drew from EU ECHA REACH databases, US FDA product registrations, national trade statistics from India and China, and corporate sustainability reports, all triangulated with bottom-up and top-down analyses.
Historical data was cross-referenced with expert panel input to project market trajectories across the analysis window. Segmentation dimensions modeled included product type (antibacterial, baby), material (nonwoven, cotton), end-user (healthcare, household), application (medical, personal care), and regional regulatory clusters. Compound annual growth rates were derived through regression analysis and validated against expert insights. Forecast inputs included raw material price forecasts, urbanization rates in Asia, and regulatory timelines for plastic reduction initiatives.
Several conditions sit outside the modeled scope, including unforeseen global pandemics or rapid shifts in consumer disposable income. Forecasts reflect assumptions regarding geopolitical trade stability and the pace of regulatory changes. Practitioners should monitor quarterly raw material price indices and new national plastic legislation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Infuser Water Bottles Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Insulated Water Bottles Market
Household Items
Paper Towel Dispenser Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Residential Air Purifiers Market
Household Items
Indoor Humidifier Market
Household Items
Toilet Brush Market
Household Items
Insulated Drinkware Market
Household Items
Crash Mat Market
Household Items
India Non-Stick Cookware Market
Household Items
Japan Digital Showers Market
Household Items
Hand Wash Station Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Smart Connected Water Purifier Market
Household Items
Porcelain Tableware Market