
 Furniture Polish Market | 2026-2036
Furniture Polish Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture Polish Market Analysis
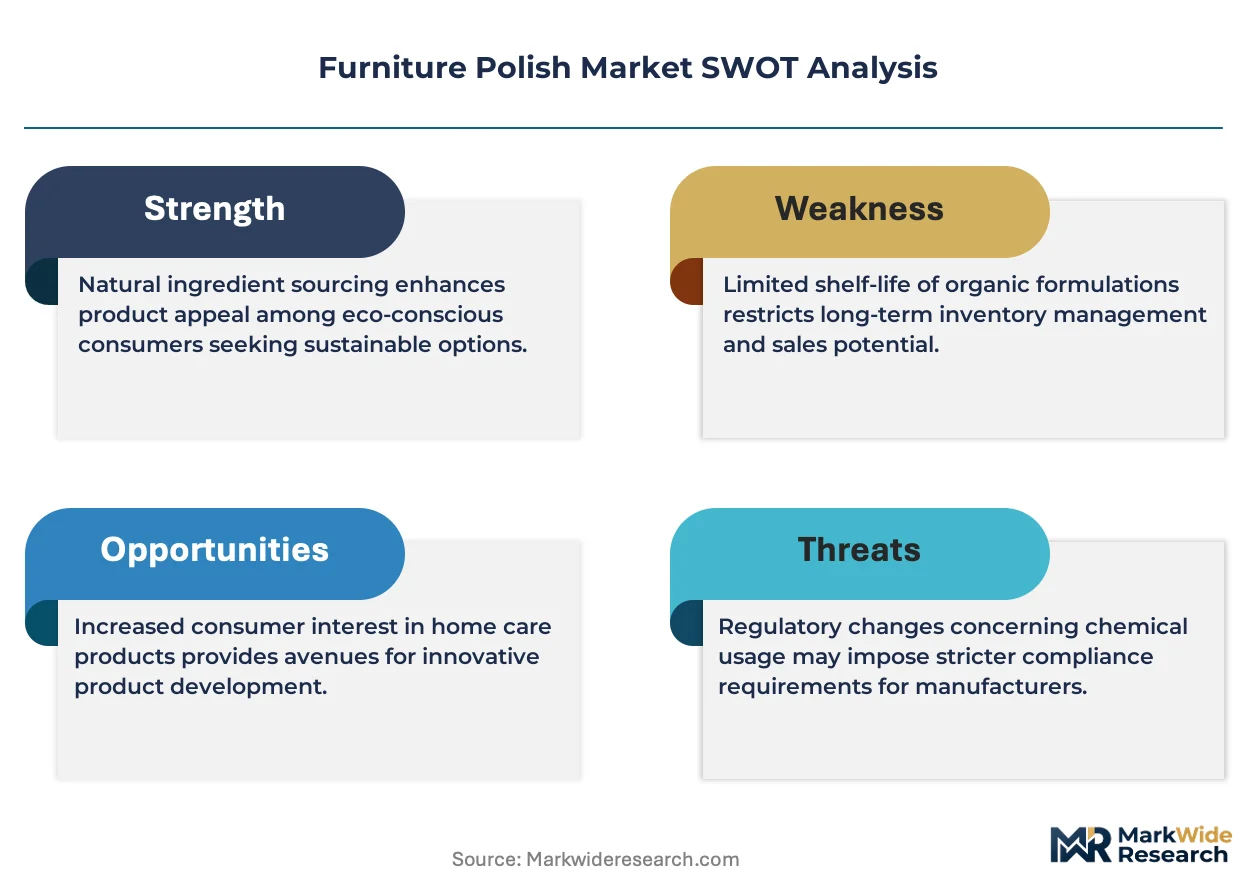
Premium silicone-free and beeswax-based formulations is bifurcating the competitive landscape into performance-grade and commodity-grade tiers. S.C. Johnson & Son, Inc. leverages its retail shelf dominance through aerosol and liquid portfolios in mass-market channels. Reckitt Benckiser Group plc anchors the European market with specialized wood care lines that meet stringent volatile organic compound limits. Bona AB differentiates through waterborne polyurethane-compatible polishes targeting professional floor care contractors.
Furniture polish comprises surface-active emulsions, natural waxes, or synthetic silicones suspended in hydrocarbon or aqueous carriers, formulated to restore luster, fill micro-abrasions, and deposit protective films on finished wood, laminate, or veneer substrates. The liquid segment sustains the largest volume share due to spray-and-wipe convenience in household and light commercial settings, though paste formats retain margin concentration among antique restoration specialists and premium furniture retailers. Natural and biodegradable formulation types are gaining fastest as regulatory pressure on petrochemical solvents intensifies and institutional buyers adopt environmental procurement criteria.
EPA regulations on volatile organic compound emissions from consumer products directly constrain solvent selection and propellant chemistry for manufacturers selling in the United States. REACH registration requirements and the EU Green Deal chemical sustainability targets are accelerating reformulation investments across European supply chains. Stakeholders must monitor evolving state-level disclosure mandates and third-party certification schemes to anticipate which formulation platforms will retain market access.
Market Dynamics
REACH and RoHS solvent thresholds are compressing formulation flexibility across European supply chains while commercial hospitality refurbishment accelerates demand for performance-grade polishes. This regulatory-demand tension is restructuring competitive tiers around compliance capability rather than scale alone.
Growth Catalysts
- Post-pandemic hospitality refurbishment:Commercial operators in Germany and France are replacing legacy wood care inventories with premium waterborne-compatible formulations.
- ECHA solvent restrictions:Tightening volatile organic compound limits under REACH Annex XVII are forcing incumbent brands to reformulate, opening shelf space for compliant entrants.
- Beeswax extraction technology:Cold-press processing advances are reducing raw material costs for natural polish categories, enabling price parity with silicone-based alternatives.
Market Restraints
- Petrochemical solvent price volatility:Hydrocarbon carrier costs fluctuate with crude oil indices, squeezing margin on traditional aerosol formulations.
- Concentrated Brazilian carnauba supply:Premium paste polish manufacturers depend on a single geography for wax feedstock, creating input vulnerability.
- Technical limitation of waterborne compatibility:Aqueous emulsions struggle to match silicone gloss durability on high-traffic commercial surfaces.
Strategic Opportunities
- Underpenetrated Scandinavian contract cleaning:Sweden and Norway lack dedicated professional-grade polish distribution, presenting first-mover channel potential.
- EU Green Deal procurement mandates:Public sector buyers must now weight environmental criteria in maintenance supply contracts, favoring biodegradable formulations.
- Subscription replenishment models:Direct-to-consumer auto-ship programs for residential wood care products are displacing supermarket impulse purchases in urban UK markets.
Industry Challenges
- Formulation chemist scarcity:Expertise in natural wax emulsion stability is concentrated among retiring specialists in Northern Italy.
- REACH registration timeline compression:New chemical entity approvals now require 18-24 month pre-market dossier preparation, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture Polish Market |
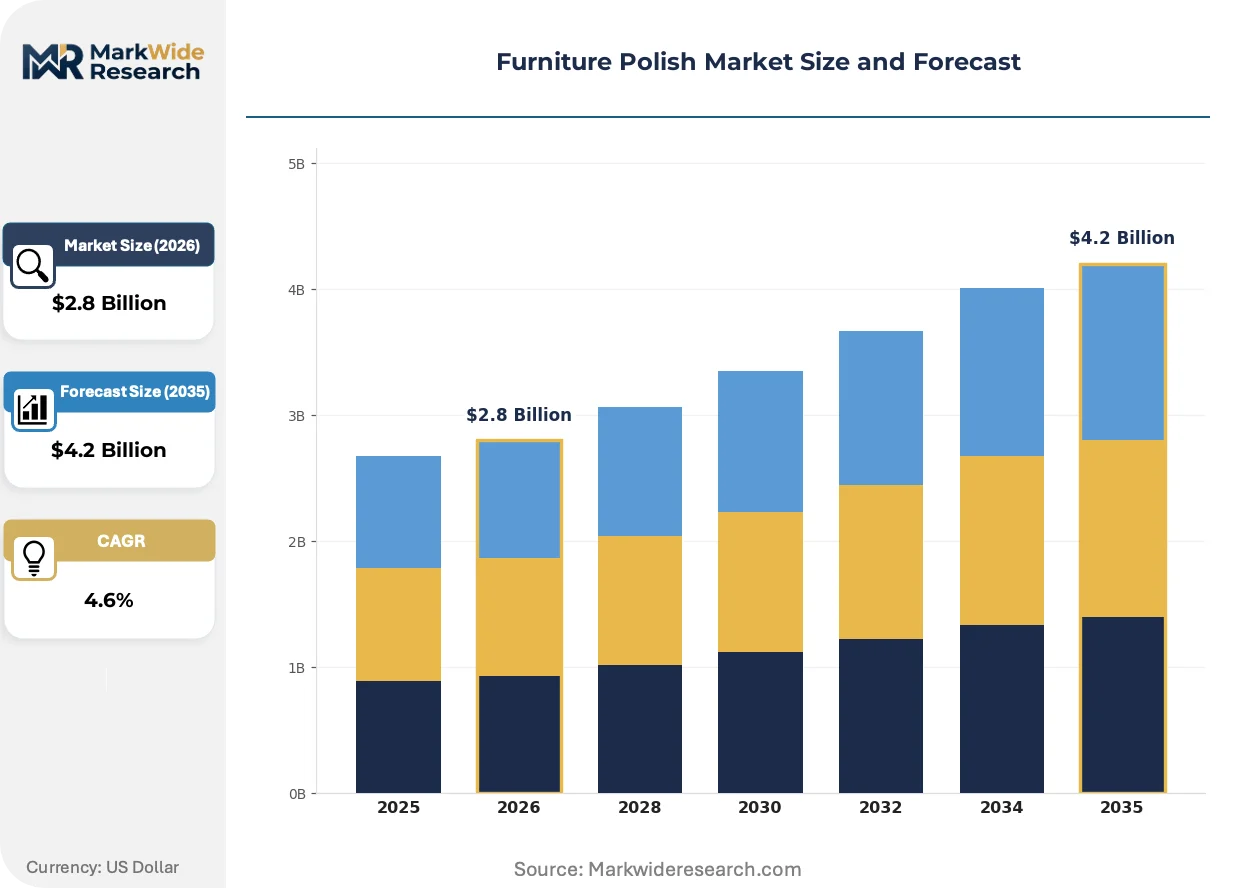
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Paste, Wipe End User: Household, Commercial, Industrial, Institutional Formulation Type: Natural, Synthetic, Biodegradable, Non-toxic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | S.C. Johnson & Son, Inc., Reckitt Benckiser Group plc, Clorox Company, Church & Dwight Co., Inc., Parker & Bailey Corporation, Weiman Products LLC, Howard Products Inc., Bona AB, Procter & Gamble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture Polish Market Emerging Trajectories
Waterborne polyurethane-compatible polish chemistry is displacing legacy silicone systems as professional floor care contractors demand finish compatibility. This technical pivot is reshaping R&D investment patterns across formulation houses.
Plant-derived emulsifier technology is fragmenting the traditional petroleum-based surfactant supply base. Boutique formulators in Provence and Tuscany are scaling cold-processed olive and citrus-derived emulsions for antique restoration specialists. These regional producers now capture margin previously held by mass-market chemical suppliers.
EPA volatile organic compound regulations for consumer products are tightening propellant chemistry requirements in the United States. Aerosol manufacturers face reformulation costs or channel exit decisions. The mass retail segment is responding with pump-spray liquid conversions and compressed air dispensing systems.
Certification-driven specification is altering procurement behavior among institutional facility managers. Third-party ecolabels such as EU Ecolabel and Nordic Swan are becoming mandatory criteria in German and Danish public tender documents. This preference shift is marginalizing uncertified commodity suppliers in contract segments.
Furniture Polish Market Segmentation
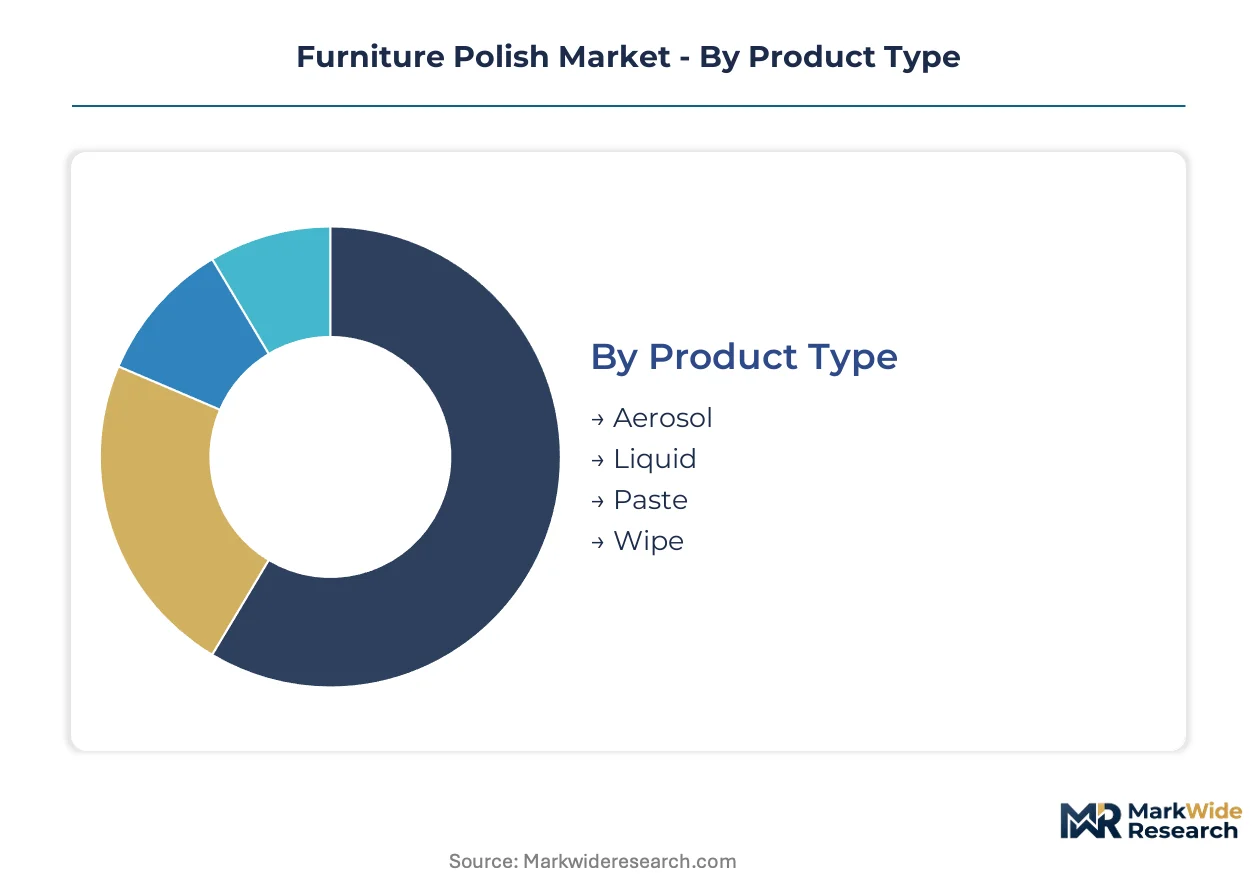
Furniture polish segmentation reveals how formulation chemistry and packaging format determine channel access and margin capture. Understanding these divides exposes where incumbent portfolios face displacement pressure from regulatory and procurement shifts.
Product Type:
Margin pools concentrate in paste formats for restoration specialists and aerosol for mass retail velocity, while liquid and wipe formats compete on convenience economics.
- Liquid:Spray-and-wipe emulsions suspended in aqueous or hydrocarbon carriers dominate household and light commercial maintenance. German residential buyers and French contract cleaners are replacing silicone-based liquids with waterborne polyurethane-compatible alternatives to meet EU Green Deal procurement criteria.
- Aerosol:Hydrocarbon-propelled silicone dispersions deliver uniform film deposition on vertical surfaces. EPA volatile organic compound regulations on consumer products are forcing US manufacturers toward compressed air dispensing or pump-spray conversions, eroding the format's traditional cost advantage.
- Paste:Concentrated wax suspensions command premium positioning among antique restoration specialists and premium furniture retailers in Northern Italy and Provence.
- Wipe:Pre-saturated substrate formats target impulse purchase channels and travel retail, sacrificing unit economics for trial conversion.
Liquid holds installed capacity. Paste is rotating up the share rankings.
End User:
Application intensity and specification rigor separate commercial operators from residential buyers, with institutional procurement introducing certification barriers that commodity suppliers cannot clear.
- Commercial:Hospitality operators, facility management contractors, and professional floor care specialists demand performance-grade formulations with documented finish compatibility. Post-pandemic refurbishment across German hotels and French restaurant chains is accelerating replacement of legacy inventories with REACH-compliant waterborne systems.
- Household:Residential buyers prioritize convenience and sensory attributes over technical specifications, though UK urban markets are shifting toward subscription replenishment models that displace supermarket impulse purchases.
- Institutional:Public sector buyers in Denmark and Germany now mandate EU Ecolabel or Nordic Swan certification in maintenance supply tenders, marginalizing uncertified entrants.
- Industrial:Manufacturing facility maintenance teams require high-throughput application on production furniture and fixtures, favoring bulk liquid formats over retail packaging.
Commercial commands specification authority. Institutional is gaining share fastest.
Formulation Type:
Raw material provenance and biodegradability credentials now determine market access in European public procurement, restructuring competitive tiers around compliance capability.
- Natural:Beeswax and carnauba-based formulations leverage cold-press extraction advances to achieve price parity with synthetic alternatives. Cold-processed olive and citrus-derived emulsions from Provence and Tuscany producers are capturing margin previously held by petroleum-based surfactant suppliers.
- Biodegradable:Plant-derived emulsifier technology meets EU Green Deal chemical sustainability targets and ECHA solvent restrictions under REACH Annex XVII. This category is expanding most quickly as institutional buyers adopt environmental procurement criteria.
- Synthetic:Silicone and petroleum-based systems retain performance advantages on high-traffic commercial surfaces but face regulatory compression on volatile organic compound thresholds.
- Non-toxic:Formulations excluding specific hazard classifications target childcare facilities and healthcare environments with strict indoor air quality protocols.
Synthetic retains volume concentration. Biodegradable is climbing the fastest.
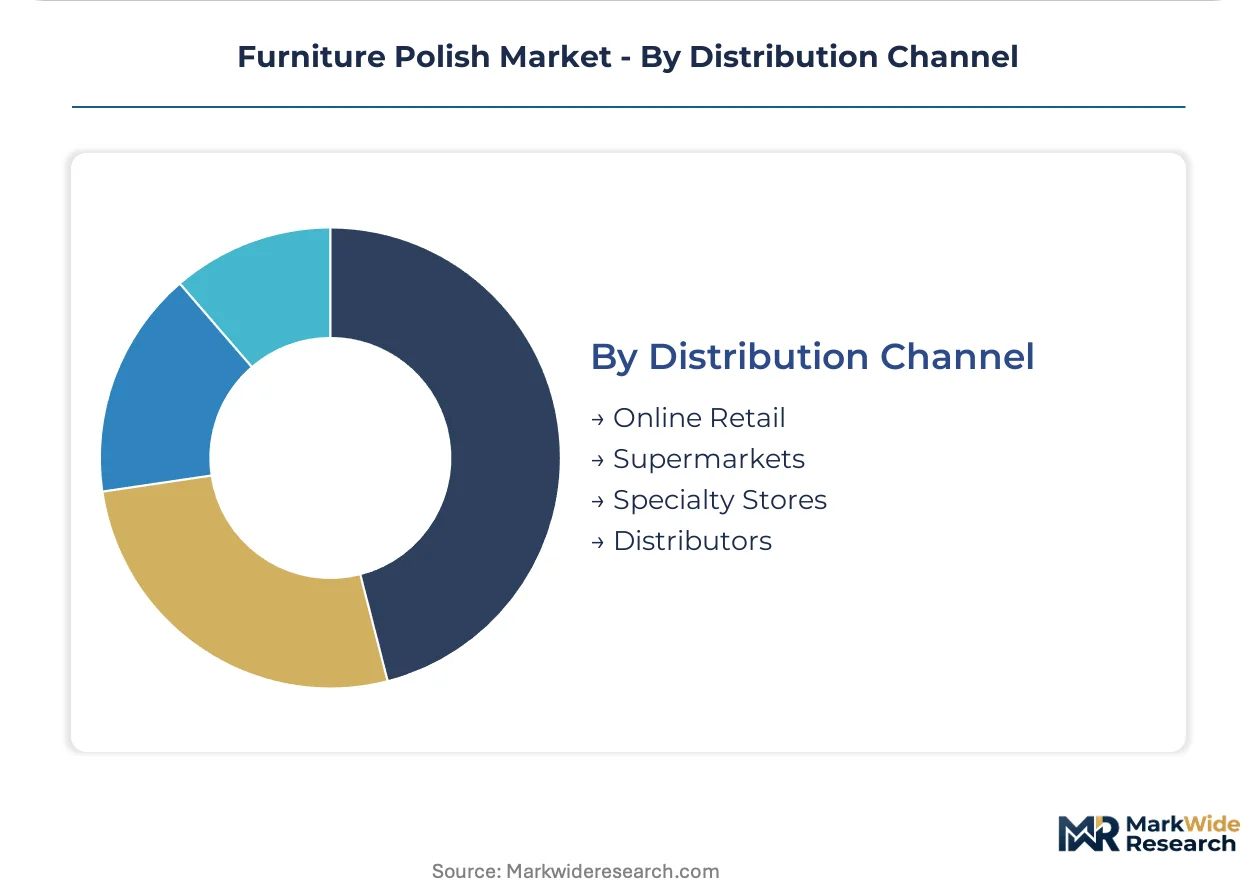
Distribution Channel:
Channel selection determines whether suppliers capture premium pricing through specification influence or compete on shelf velocity and trade terms.
- Specialty Stores:Premium furniture retailers and antique restoration suppliers in Germany and Northern Italy provide specification authority and margin protection for paste and natural wax formulations.
- Distributors:Professional-grade polish distribution to contract cleaning and facility management sectors remains underpenetrated in Sweden and Norway, presenting first-mover channel potential.
- Supermarkets:Mass retail shelf space concentrates around aerosol and liquid portfolios with established brand equity and promotional support.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment models and access to boutique formulators bypassing traditional retail gatekeepers.
Distributors hold relationship infrastructure. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in furniture polish tilt toward formulation-exporting economies with strong chemical processing infrastructure, while demand concentrates in affluent consumer markets with elevated wood care standards. Germany and the United States run structural surpluses in specialty wax chemistry, whereas emerging Asian markets remain net importers of performance-grade formulations.
Germany
Post-pandemic hospitality refurbishment across Berlin and Munich hotels is accelerating replacement of legacy silicone-based inventories with REACH-compliant waterborne systems. ECHA solvent restrictions under REACH Annex XVII are compressing permissible volatile organic compound thresholds, forcing incumbent brands into reformulation cycles. The Stuttgart-Oberhausen industrial corridor hosts concentrated specialty chemical production serving contract furniture maintenance sectors.
United States
EPA volatile organic compound regulations on consumer products are constraining propellant chemistry for aerosol manufacturers, driving pump-spray liquid conversions. Commercial facility managers in Chicago and Dallas are specifying third-party certified formulations for LEED-compliant building maintenance. The New Jersey-Pennsylvania chemical belt retains formulation capacity for hydrocarbon carrier systems despite regulatory compression.
France
Provence-based boutique formulators are scaling cold-processed olive and citrus-derived emulsions for antique restoration specialists, capturing margin previously held by petroleum-based surfactant suppliers. ANSM and CNIL oversight of consumer chemical safety is tightening disclosure requirements for fragranced household products. The Lyon-Grenoble corridor concentrates natural wax extraction technology development.
Sweden
Professional-grade polish distribution to contract cleaning sectors remains underpenetrated, presenting first-mover channel potential for REACH-compliant entrants. Nordic Swan certification is becoming mandatory in public tender documents for institutional maintenance supplies. The Stockholm-Uppsala region lacks dedicated distributor infrastructure relative to German and French market maturity.
Italy
Northern Italian antique restoration clusters in Milan and Turin sustain premium paste format demand among furniture retailers and heritage conservation specialists. Formulation chemist expertise in natural wax emulsion stability concentrates among retiring specialists in this region, creating capability scarcity. Tuscany-based producers are expanding cold-pressed beeswax extraction to achieve price parity with synthetic alternatives.
Furniture Polish Market Vendor Landscape
Concentration sits with diversified household chemical conglomerates and specialized wood care formulators rather than pure-play polish manufacturers. The vendor base spans mass-market aerosol producers, professional floor care specialists, and regional natural wax boutiques. Two strategic archetypes dominate: retail shelf dominants leveraging brand equity and distribution scale, and compliance-forward formulators capturing institutional procurement mandates. Competitive moves center on REACH registration investments for European market access and waterborne polyurethane-compatible chemistry development for professional contractor specification.
Among diversified household chemical conglomerates, S.C. Johnson & Son, Inc. and Reckitt Benckiser Group plc occupy positions representing mass-market retail archetypes with established aerosol and liquid portfolios. Bona AB exemplifies the professional-grade specialist archetype, differentiated through contractor-facing distribution and finish-compatible formulation expertise. These three companies anchor the competitive structure without exhausting strategic variation in the space.
| Leading Market Players |
|---|
| S.C. Johnson & Son, Inc. |
| Reckitt Benckiser Group plc |
| Clorox Company |
| Church & Dwight Co., Inc. |
| Parker & Bailey Corporation |
| Weiman Products LLC |
| Howard Products Inc. |
| Bona AB |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Brazilian carnauba wax processors and European paste polish manufacturers lock in multi-year supply access while anchoring raw material price visibility against petrochemical carrier volatility. These arrangements insulate premium formulation tiers from spot market swings in hydrocarbon costs driven by crude oil indices.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the furniture polish market. Price differentiation hinges on certification grade—EU Ecolabel and Nordic Swan tiers command substantial premiums over uncertified commodity formulations—and volume scale, with hospitality procurement consortia extracting favorable terms. Cost compression in aerosol formats is intensifying because EPA volatile organic compound regulations are forcing propellant chemistry conversions. Household residential buyers exhibit highest price sensitivity, while institutional facility managers prioritize compliance credentials over unit cost.
Supply Chain Analysis
Brazil and Germany anchor natural wax extraction and specialty chemical processing respectively for furniture polish feedstocks. Brazilian cold-press carnauba operations and German hydrocarbon carrier refineries supply inputs that European formulators draw from under REACH-regulated trade flows. Supply chain risk centers on concentrated Brazilian carnauba geography exposed to climate volatility and export logistics disruptions. Distribution runs through professional cleaning distributors in Germany and France, mass retail supermarkets in the United States, and emerging direct-to-consumer platforms in UK urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture polish incumbents face substitution pressure from waterborne polyurethane-compatible maintenance systems that professional floor care contractors increasingly specify over traditional silicone polishes.
For Market Incumbents: Consolidate backward integration into Brazilian carnauba sourcing and German specialty chemical production to secure feedstock access against supply concentration risks. Deepen certification investment in EU Ecolabel and Nordic Swan tiers to defend institutional procurement share from biodegradable formulation entrants. Channel control through exclusive distributor relationships in underpenetrated Scandinavian markets provides defensive moat construction. For New Entrants and Emerging Players: Subscription replenishment service gaps in UK urban residential markets offer white-space penetration where incumbent mass-market brands under-serve convenience-oriented buyers. Scandinavian contract cleaning distribution infrastructure presents lowest competitive density for REACH-compliant professional-grade entrants. Direct-to-consumer platforms enable bypass of supermarket shelf gatekeepers while capturing recurring revenue through auto-ship wood care programs. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors compliance-forward formulators with established REACH registration capabilities and waterborne chemistry R&D pipelines. Acquisition targets should demonstrate institutional procurement traction in Germany and Denmark alongside natural wax emulsion stability expertise concentrated among Northern Italian specialists. Monitor ECHA solvent restriction enforcement intensity as inflection indicator for reformulation investment cycles and compliant entrant shelf space capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Wax Sourcing | Captive Brazilian carnauba supply secures margin protection against commodity volatility and single-geography risk. |
| REACH Registration Investment | Pre-market dossier preparation enables European market access as ECHA solvent thresholds tighten under Annex XVII. |
| Waterborne Polyurethane-Compatible Formulation Development | Professional contractor specification shifts demand chemistry pivot away from legacy silicone systems. |
| Subscription Replenishment Model Launch | UK urban auto-ship programs displace supermarket impulse purchases with recurring revenue capture. |
| Nordic Swan Certification Acquisition | Danish and Swedish public tender mandates now require third-party ecolabel compliance for institutional supply contracts. |
Methodological Framework
Operator-level perspectives from facility management procurement directors, professional floor care contractors, antique restoration specialists, and specialty chemical plant managers anchored the qualitative base for this study. Primary interview findings triangulated against secondary sources including ECHA regulatory filings, EPA consumer product emission databases, customs trade flow records, and EU public procurement tender documents. Bottom-up volume estimates by formulation type and end-use segment reconciled with top-down market sizing through cross-validation against distributor shipment data and retail channel audit information.
Sensitivity analysis across crude oil price scenarios, REACH enforcement intensity variations, and hospitality refurbishment pace assumptions tested forecast robustness throughout the projection horizon. Segmentation modeling incorporated product format, end-user category, formulation chemistry, and distribution channel dimensions with geographic granularity at country level. CAGRs derived from trend extrapolation of replacement cycle dynamics, regulatory compliance investment patterns, and procurement mandate adoption curves across German, French, UK, and Scandinavian markets.
Underlying assumptions cover sustained ECHA solvent restriction enforcement, stable Brazilian carnauba export logistics, and continued EU Green Deal procurement mandate expansion, with deviation risk concentrated in petrochemical carrier price volatility and formulation chemist expertise scarcity in natural wax emulsion stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Carpet and Rug Shampoo Market