
 Personal Care Wipes Market | 2026-2036
Personal Care Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Wipes Market Intelligence
Asset-light manufacturing models that rely on contract production is reshaping competitive positioning for new market entrants. This strategy allows brands to focus on marketing without heavy capital expenditure on production lines. Kimberly-Clark Corporation leverages its massive scale and global distribution network to maintain leadership. Meanwhile, specialists like Rockline Industries dominate the contract manufacturing space, supplying numerous private-label products.
Personal care wipes are pre-moistened cloths, typically constructed from non-woven fabrics saturated with a cleansing or conditioning solution. These products are engineered for single-use application in hygiene, cosmetic removal, and sanitization. The baby wipes product type represents a mature, high-volume segment with established consumer loyalty. In contrast, flushable wipes and products utilizing biodegradable materials are gaining share, driven by consumer demand for convenience and environmental sustainability.
Regulatory oversight from bodies like the U.S. FDA, which governs antibacterial claims, and the EU's REACH regulation on chemical substances, directly influences product formulation. In China, the NMPA sets standards for cosmetic and hygiene product registration, creating market access hurdles. Navigating the complex landscape of material science innovations alongside disparate regional standards on flushability and biodegradability remains a central strategic challenge for manufacturers.
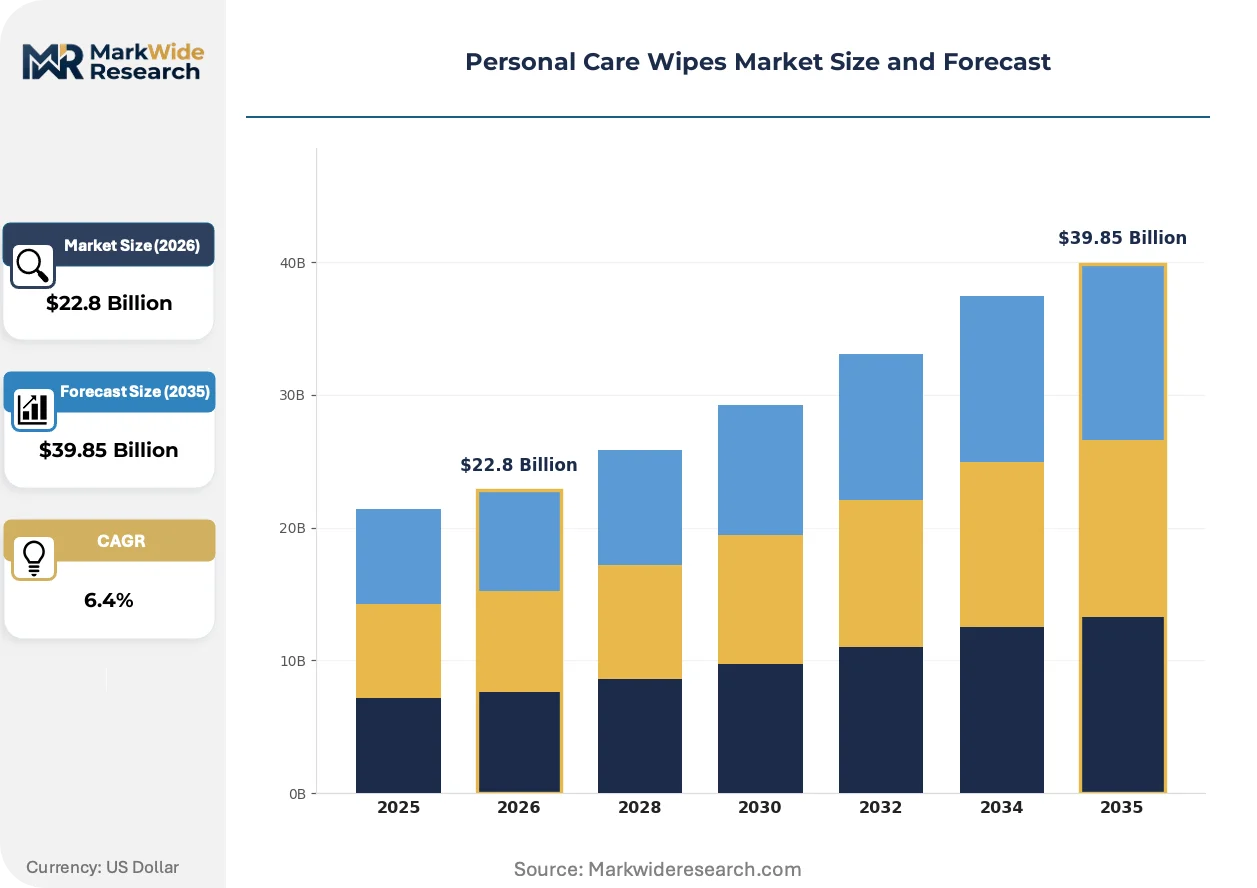
Market Dynamics
The personal care wipes market is defined by a fundamental tension between consumer demand for single-use convenience and escalating regulatory pressure against plastic waste. This dynamic, exemplified by the EU's Single-Use Plastics Directive, is forcing a rapid industry-wide pivot toward sustainable materials.
Growth Catalysts
- Sustainable Material Innovation:The development of biodegradable non-woven fabrics, such as lyocell and bamboo-based fibers, is creating new premium product tiers and meeting demand from environmentally conscious consumers in Europe and North America.
- Hygiene Awareness in Emerging Economies:Heightened focus on personal and public hygiene, especially in high-population countries like China and India, is accelerating demand for antibacterial and sanitizing wipes in household and travel applications.
- Advanced Non-Woven Technologies:Improvements in spunlace and air-laid web formation processes are yielding softer and more durable substrates, enhancing product performance and brand differentiation within the mature baby wipes segment.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of key inputs, particularly petroleum-derived polypropylene and wood pulp-based viscose, create significant margin pressure and forecasting challenges for manufacturers.
- Inconsistent Flushability Standards:A patchwork of differing regulations and testing protocols for flushable products, particularly between the United States and European nations, complicates product design, testing, and cross-border marketing.
- Threat from Reusable Alternatives:The increasing consumer adoption of reusable products, including microfiber cloths and washable cotton rounds for cosmetic removal, poses a direct substitution risk to the single-use wipes model.
Strategic Opportunities
- Geographic Expansion in Latin America:Markets such as Brazil and Mexico represent significant growth opportunities, as rising disposable incomes and greater participation of women in the workforce drive adoption of convenience-oriented hygiene products.
- Niche Application Development:Creating specialized wipes for adjacent categories like pet care, electronics cleaning, and fitness (post-workout wipes) allows brands to capture new revenue streams beyond traditional personal care.
- Male-Specific Product Lines:Formulating and marketing wipes specifically for men's grooming routines, addressing needs like facial cleansing and post-shaving care, opens an underserved consumer segment with distinct purchasing drivers.
Industry Challenges
- Complex Chemical Compliance:Adhering to stringent chemical safety regulations, including the EU's REACH framework for substances and the U.S. FDA's rules for antibacterial claims, requires extensive and costly toxicological testing.
- Capital-Intensive Material Transition:Shifting production from established polypropylene non-woven lines to ones capable of processing biodegradable materials like PLA or PHA requires substantial capital investment in new machinery and retooling.
- Greenwashing Scrutiny:Brands face a significant challenge in communicating environmental benefits without being accused of greenwashing, as unsubstantiated claims about biodegradability can lead to regulatory fines and severe reputational damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Wipes Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baby Wipes, Facial Wipes, Flushable Wipes, Antibacterial Wipes Material: Non-woven Fabric, Cotton, Biodegradable Material, Polyester End User: Household, Hospitals, Beauty Salons, Travel Industry Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Johnson & Johnson, Edgewell Personal Care, Rockline Industries, Diamond Wipes International, Nice-Pak Products, Unicharm International, La Fresh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Wipes Market Strategic Shifts & Innovations
Material science is at the center of market evolution, as the industry responds to a powerful combination of regulatory mandates and shifting consumer ethics. This pivot toward sustainability is influencing everything from raw material sourcing to product end-of-life considerations.
Advanced biodegradable non-woven fabrics, derived from renewable sources like wood pulp, bamboo, and polylactic acid (PLA), provide a functional alternative to fossil fuel-based substrates. Eco-conscious consumers and retailers in Europe are driving adoption of these materials for private-label and premium brand products. This material science shift is rendering obsolete the long-term viability of manufacturers who are solely dependent on traditional polypropylene substrates without a clear innovation pipeline.
The European Union's Single-Use Plastics Directive imposes direct costs on manufacturers through extended producer responsibility (EPR) schemes for wipes containing plastic. This regulation makes producers financially responsible for the cost of waste collection, cleanup, and consumer awareness campaigns. The baby wipes and personal hygiene categories are most impacted, compelling brands selling in the EU to accelerate reformulation efforts toward plastic-free designs.
A clear behavioral shift is the consumer demand for product transparency and "clean" formulations free from perceived irritants like parabens, phthalates, and alcohol. This is disrupting legacy product development, pushing brands to prioritize simpler ingredient lists featuring natural extracts and gentle preservatives. This trend is most visible in the North American and German markets, particularly within the sensitive skin and baby care segments.
Personal Care Wipes Market Segmentation
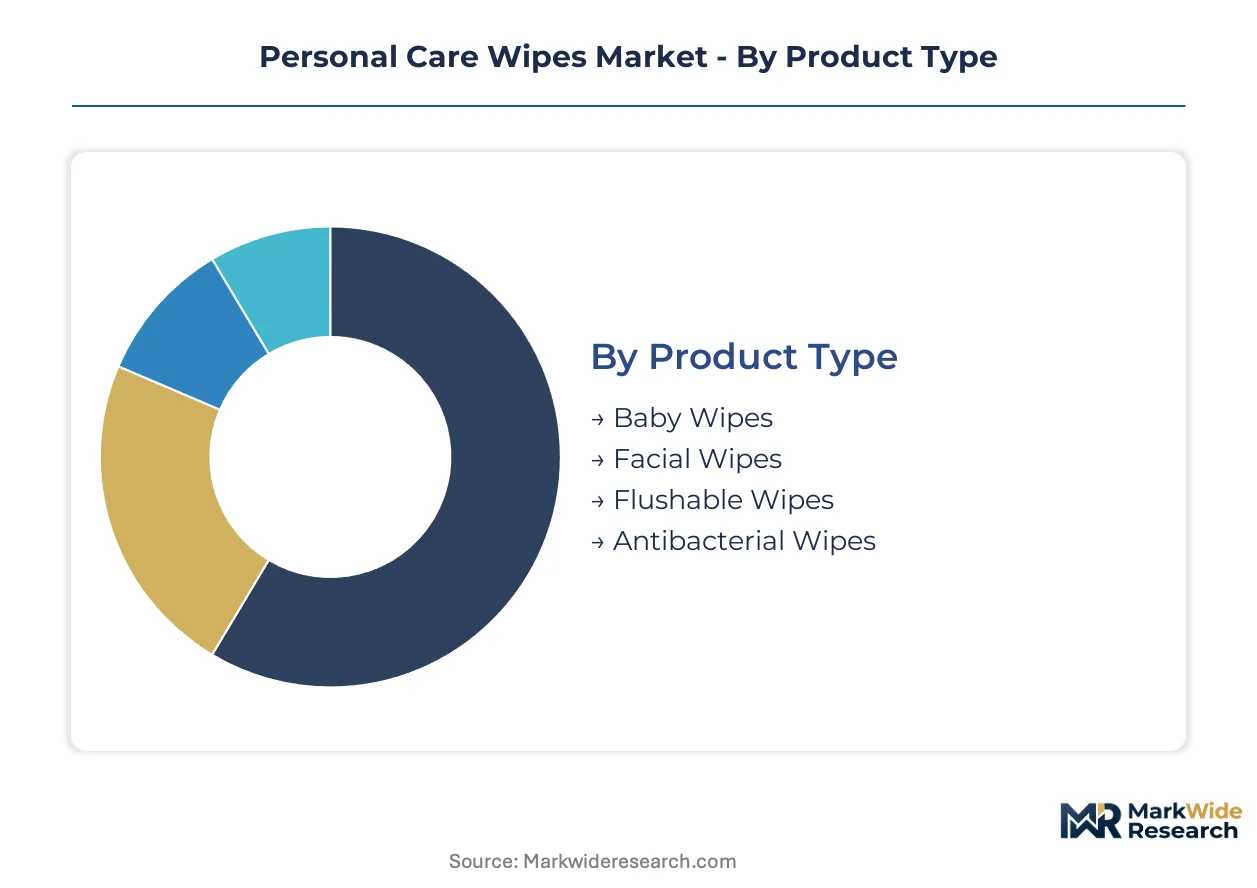
Segmentation within the personal care wipes market highlights the diverse product offerings and varied consumer preferences that define industry dynamics. Understanding these distinct segments allows manufacturers to tailor product development and marketing strategies for optimal market penetration.
Product Type:
Product type segmentation reveals varying purchase frequencies and replacement cycles among consumers.
- Baby Wipes:Pre-moistened cloths designed for infant hygiene, often containing mild cleansers and moisturizers for sensitive skin. Demand remains consistently high in households across China, driven by established consumer loyalty and daily use.
- Antibacterial Wipes:Formulated with active antimicrobial agents to reduce germs on skin or surfaces, meeting sanitization needs. Demand is rising in household and travel industry applications, particularly in India, due to heightened hygiene awareness.
- Facial Wipes:Used for cosmetic removal and facial cleansing, often infused with skincare ingredients and gentle formulations.
- Flushable Wipes:Engineered to break down in wastewater systems, gaining share due to convenience and environmental concerns.
Baby Wipes dominate the installed base. Antibacterial Wipes are where expansion concentrates.
Material:
Material composition directly influences product sustainability profiles and manufacturing investment requirements.
- Biodegradable Material:Composed of fibers like lyocell, bamboo, or polylactic acid (PLA), designed to decompose naturally after use. Consumer demand for these materials is strongest in Europe, driven by environmental consciousness and regulatory mandates.
- Non-woven Fabric:Typically made from synthetic polymers like polypropylene or natural fibers, forming a sheet through mechanical, thermal, or chemical bonding. This material type forms the bulk of traditional personal care wipe production.
- Cotton:Natural fiber offering softness and absorbency, often used in premium or sensitive skin formulations due to its gentle properties.
- Polyester:Synthetic fiber providing strength and durability, frequently blended with other materials for specific performance attributes and cost efficiency.
Biodegradable materials are gaining share most quickly as regulatory pressure against plastic waste increases.
End User:
End-user segments highlight distinct purchase motivations and usage patterns for personal care wipes.
- Household:Encompasses individual and family use for daily hygiene, baby care, and general sanitization within residential settings. Demand in this segment is driven by convenience and routine personal care needs.
- Hospitals:Utilizes specialized wipes for patient care, infection control, and surface disinfection in clinical environments. Regulatory compliance and efficacy against pathogens are paramount for these products.
- Beauty Salons:Employs facial and cosmetic removal wipes for client services and professional applications, requiring gentle and effective formulations.
- Travel Industry:Includes airlines, hotels, and cruise lines providing sanitizing and personal hygiene wipes to consumers on the go.
The Household segment accounts for the largest volume consumption. Hospitals prioritize specialized formulations for critical hygiene.
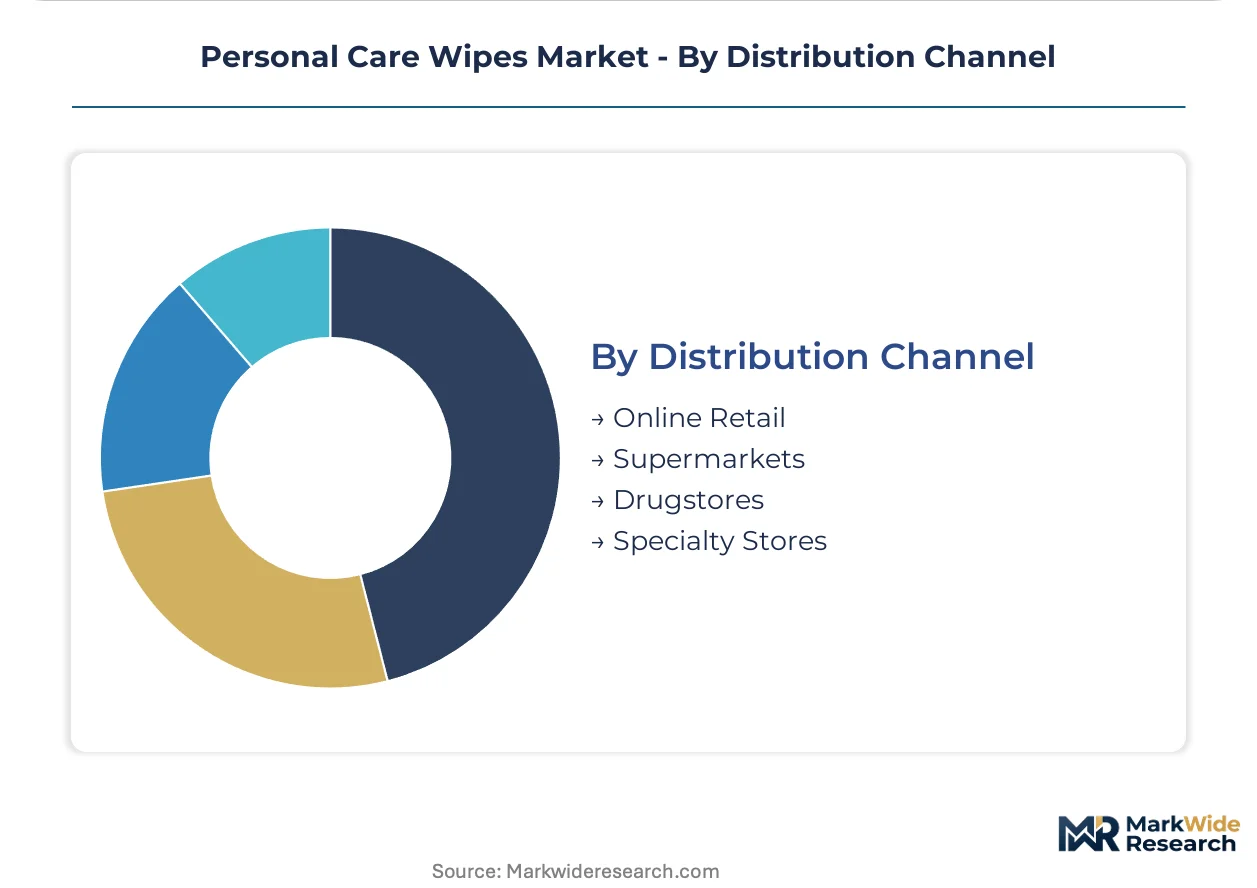
Distribution Channel:
Distribution channels define the pathways through which personal care wipes reach diverse consumer bases and professional clients.
- Supermarkets:Represents a primary channel for mass-market personal care wipes, offering broad accessibility and competitive pricing to general consumers. This channel drives significant volume for established brands.
- Online Retail:Facilitates direct-to-consumer sales and offers a wide product assortment with home delivery convenience. This channel is experiencing rapid expansion, particularly for niche and premium sustainable products.
- Drugstores:Focuses on health-oriented personal care wipes, including sensitive skin and medicinal varieties, often with pharmacist recommendations.
- Specialty Stores:Caters to niche markets such as organic, luxury, or professional-grade personal care wipe products, emphasizing unique attributes.
Supermarkets remain a foundational channel for broad market penetration. Online retail platforms are critical for reaching environmentally conscious consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between Europe and China, with European markets commanding higher prices for sustainable materials due to stringent regulations and consumer preference, while China's massive volume drives competitive pricing across conventional segments. This dynamic influences product development and market entry strategies for manufacturers targeting diverse global consumers. Companies must adapt to varied regulatory environments and consumer expectations in different geographies.
China
Consumer purchasing power and heightened hygiene awareness in China accelerate demand for antibacterial and baby wipes. The NMPA sets rigorous standards for cosmetic and hygiene product registration, creating market access hurdles. Manufacturing hubs in the Yangtze River Delta continue to expand production capacity for both domestic and export markets.
India
Heightened focus on personal and public hygiene in India drives demand for antibacterial and sanitizing wipes, particularly in household and travel applications. The BIS establishes quality standards for personal care products, influencing local formulations. Cities like Mumbai and Bengaluru are experiencing rapid growth in retail distribution for convenience-oriented hygiene solutions.
Germany
Environmentally conscious consumers in Germany demand biodegradable materials and "clean" formulations free from perceived irritants. The EU's REACH regulation on chemical substances and the Single-Use Plastics Directive directly influence product formulation and material choices. Manufacturers in Baden-Württemberg are innovating with plant-based fibers to meet stringent sustainability criteria.
United States
Demand for convenient personal care wipes remains strong across all segments, with a focus on antibacterial claims and flushable options. The U.S. FDA governs antibacterial claims, requiring specific efficacy testing and labeling for sanitizing products. Major brands based in California are investing in new non-woven technologies to improve product performance and sustainability.
Brazil
Rising disposable incomes and greater participation of women in the workforce drive adoption of convenience-oriented hygiene products in Brazil. ANVISA regulates health products, including personal care wipes, ensuring safety and quality standards. The São Paulo metropolitan area serves as a key distribution hub, facilitating market penetration across the country.
Personal Care Wipes Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials and manufacturing capabilities. The personal care wipes market exhibits a tiered structure, with global brands dominating established segments and specialized contract manufacturers supporting private-label growth. Strategic archetypes include large-scale brand owners, agile contract manufacturers, and innovative material suppliers. Geographic expansion into high-growth emerging markets and portfolio diversification into niche applications represent dominant competitive moves.
At the scale-driven end, Kimberly-Clark Corporation occupies a position as a global leader, leveraging its extensive distribution network and brand recognition across multiple product categories. Rockline Industries exemplifies the specialized contract manufacturing archetype, providing private-label solutions for numerous brands across diverse markets. Johnson & Johnson represents another established brand, focusing on sensitive skin formulations and baby care segments within the consumer health sector.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Johnson & Johnson |
| Edgewell Personal Care |
| Rockline Industries |
| Diamond Wipes International |
| Nice-Pak Products |
| Unicharm International |
| La Fresh |
| Others |
Cost & Logistics Intelligence
Under-utilized capacity in traditional polypropylene non-woven lines is driving competitive pricing for conventional wipes, while investment in sustainable materials dictates premium pricing and supplier behavior.
Pricing Analysis
Configured-to-order premium pricing for sustainable materials contrasts sharply with per-unit transactional pricing for conventional wipes. Price differentiation stems from material composition, such as biodegradable fibers, and the level of customization for specialized formulations. Pricing pressure stems from raw material price volatility, particularly for petroleum-derived polypropylene and wood pulp-based viscose. The household segment exhibits high price sensitivity, whereas hospitals prioritize efficacy and regulatory compliance over cost.
Supply Chain Analysis
Rockline Industries and Nice-Pak Products, as major contract manufacturers, hold significant capacity for personal care wipes. Geographic supply concentration includes manufacturing hubs in China's Yangtze River Delta and established non-woven production in the United States. Raw material dependencies include polypropylene, wood pulp, and newer plant-based fibers like lyocell and PLA. Commodity price volatility for key inputs represents a structural risk. Distribution runs through a dual model, leveraging supermarkets for mass-market penetration and online retail for niche and premium sustainable products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal care wipes market requires a strong substitution defense, as reusable alternatives like microfiber cloths pose a direct threat to the single-use model.
For Market Incumbents:Insulate core product lines by investing heavily in R&D for biodegradable materials, countering the direct threat from reusable alternatives and regulatory pressure from the EU Single-Use Plastics Directive. Expand manufacturing capacity for plant-based fibers in Europe to meet stringent sustainability criteria. Leverage global distribution networks to introduce premium sustainable options in markets with high environmental consciousness. Deepen vertical integration into non-woven fabric production to secure supply and control costs for advanced substrates.
For New Entrants and Emerging Players:Niche application development in pet care and male-specific grooming represents the most penetrable entry point for specialized brands. Target environmentally conscious consumers in Europe and North America with "clean" formulations free from perceived irritants. Utilize online retail platforms for direct-to-consumer sales, emphasizing product transparency and sustainable sourcing. Focus on innovative material science, such as bamboo or PLA-based fibers, to differentiate from established players.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the sustainable materials sub-segment, driven by retooling requirements for new production lines. Long-term viability hinges on adaptability to evolving regulatory landscapes, particularly concerning plastic waste and chemical compliance. Acquisition targets should include agile contract manufacturers specializing in plant-based fibers or brands with strong intellectual property in biodegradable non-wovens. Quarterly review of regulatory amendments and material input costs is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Biodegradable Materials | Manufacturers scale production of plant-based fibers to meet EU Single-Use Plastics Directive mandates. |
| Portfolio Diversification into Niche Applications | Brands capture new revenue streams by developing specialized wipes for pet care and electronics cleaning. |
| Strategic Partnership with Material Suppliers | Companies secure access to innovative lyocell and bamboo-based fibers, ensuring sustainable raw material supply. |
| Direct-to-Consumer (DTC) Channel Expansion | Brands reach environmentally conscious consumers directly, bypassing traditional retail and controlling messaging. |
| Regulatory Compliance & Certification Investment | Manufacturers gain market access and consumer trust by adhering to FDA antibacterial claims and EU REACH standards. |
Research Approach
Initial hypotheses were tested against primary input from product development executives, procurement managers, and regulatory affairs specialists, then refined through iterative analysis. This involved combining insights from deep-dive interviews with validation against secondary sources like NMPA and FDA filings, EU REACH reports, and customs data. A bottom-up approach to market sizing was triangulated with top-down validation.
Demand-supply balance models project market evolution across the analysis window, integrating volume and value outputs through a triangulated approach. Segmentation dimensions modeled include product type, material, end user, distribution channel, and regional regulatory landscape. Compound annual growth rates were derived from historical trends and projected market shifts. Raw material price forecasts and regulatory compliance costs served as key industry-specific forecast inputs.
Practitioners should monitor shifts in regional flushability standards and raw material price volatility for early signals of market revision. Forecasts reflect assumptions regarding technological advancements in sustainable materials and consumer adoption rates. Quarterly review of regulatory amendments and material input costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
False Eyelashes Market