
 Household Cleaning Products Market | 2026-2036
Household Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Household Cleaning Products Market Analysis
Buyer concentration among large-format retailers and property management groups is hardening, squeezing negotiating leverage for mid-tier suppliers. Procter & Gamble leverages its massive manufacturing scale to secure shelf dominance across North American mass retail channels. Henkel anchors its position through specialized laundry and home care formulations that command premium positioning in European drugstores. Unilever competes aggressively on sustainability credentials, using its global brand architecture to navigate tightening environmental compliance across multiple jurisdictions.
Household cleaning products encompass formulated chemical preparations designed to remove soil, stains, and microbial contaminants from domestic surfaces, typically comprising surfactants, solvents, chelating agents, and antimicrobial actives at specified pH and concentration levels. These formulations serve the primary commercial purpose of maintaining hygienic residential and light commercial environments while meeting safety standards for human contact and environmental discharge. Surface cleaners and disinfectants currently lead value generation due to persistent post-pandemic hygiene consciousness, while spray and wipe formats capture disproportionate growth as convenience-seeking residential buyers shift away from dilutable concentrates. Online retailers represent the fastest-expanding distribution channel, though supermarkets still control the majority of volume throughput and promotional visibility.
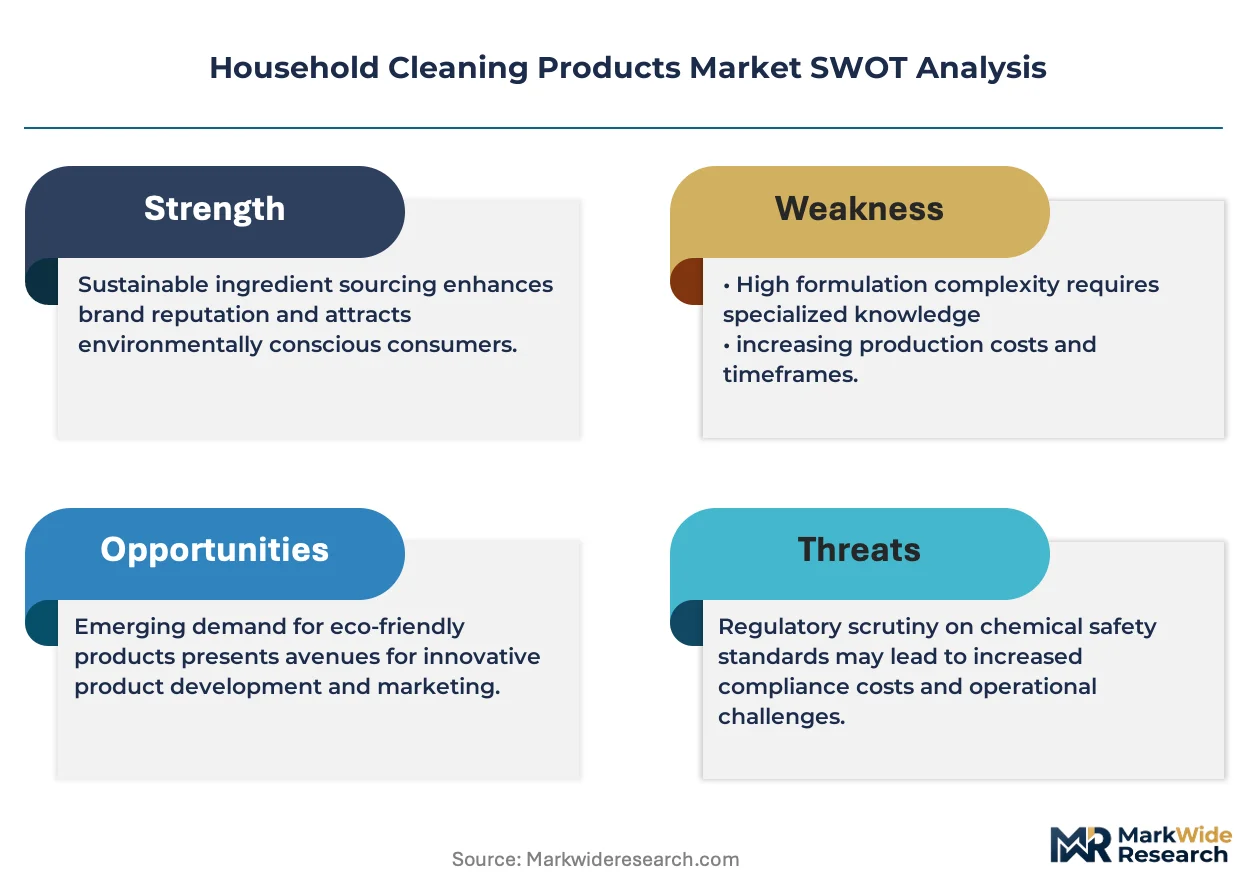
The EPA regulates antimicrobial claims and active ingredient safety through FIFRA registration requirements, while the EU REACH framework restricts specific biocides and mandates full supply chain transparency for chemical substances in cleaning formulations. The California Air Resources Board imposes additional volatile organic compound limits that effectively shape formulation decisions for products distributed across the United States. Stakeholders must monitor evolving state-level ingredient bans and biobased procurement mandates, as these fragmented regulatory trajectories will determine which product portfolios retain market access without costly reformulation cycles.
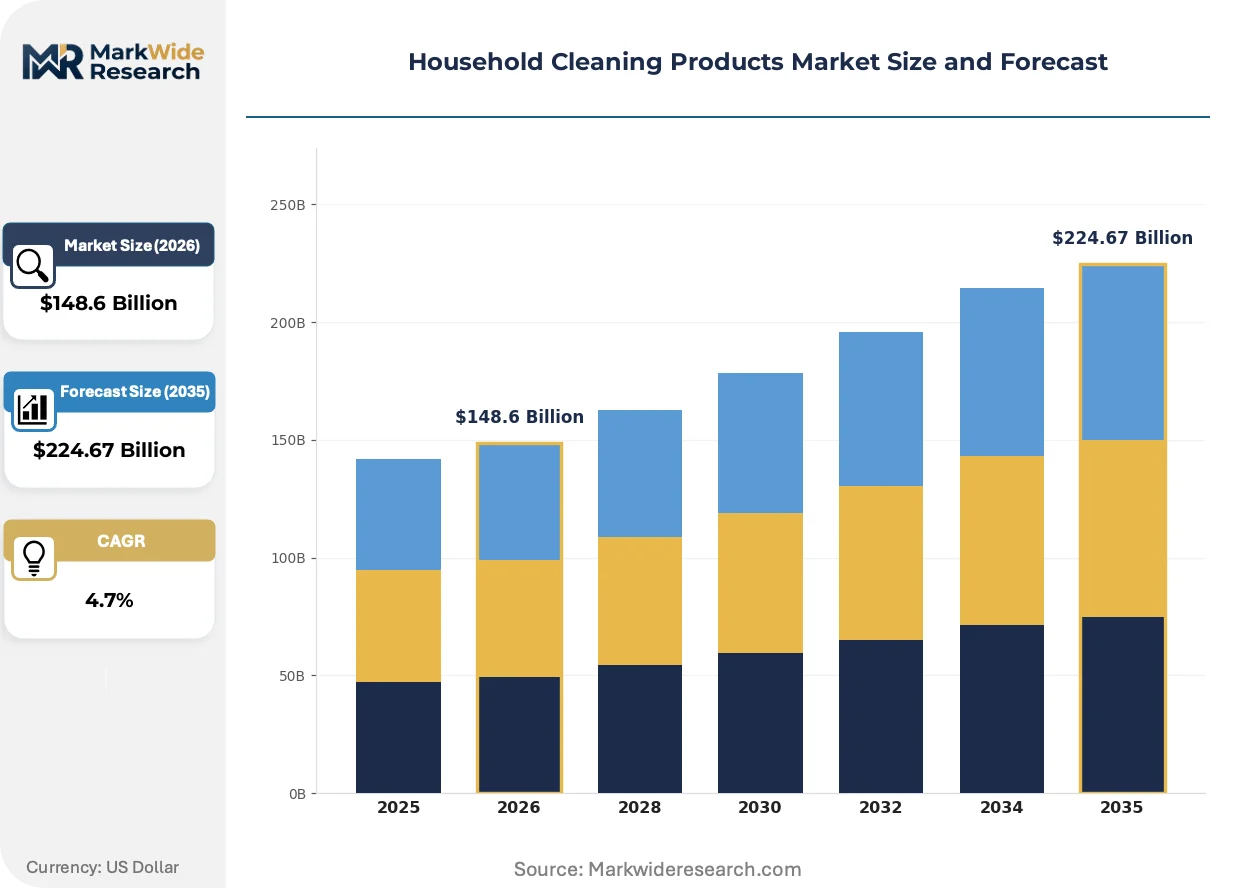
Market Dynamics
Property management groups and large-format retailers are consolidating procurement around certified green formulations, squeezing mid-tier suppliers while rewarding scale players with reformulation capabilities and regulatory compliance infrastructure.
Growth Catalysts
- EPA Safer Choice Certification:Property managers in multi-unit residential complexes now mandate this label for centralized procurement contracts, creating volume pull-through for compliant suppliers.
- Spray-and-wipe format preference:Convenience-seeking residential buyers are abandoning dilutable concentrates, driving premium pricing for ready-to-use formulations with specialized dispensing mechanisms.
- Southeast Asia urban middle-class expansion:Cities like Jakarta, Bangkok, and Ho Chi Minh City are outpacing historical Western consumption patterns for surface disinfectants and laundry additives.
Market Restraints
- Surfactant feedstock volatility:Palm oil and petrochemical derivative prices fluctuate with energy markets, compressing margins for formulators lacking backward integration into raw material supply.
- EU REACH biocide restrictions:The framework's evolving substance bans force costly reformulation cycles, particularly for antimicrobial actives in surface disinfectants.
- California Air Resources Board VOC limits:These standards effectively dictate formulation architecture for products distributed nationally, creating compliance friction for smaller regional players.
Strategic Opportunities
- Vietnam and Indonesia household penetration gaps:Modern trade expansion in secondary cities offers first-mover positioning before organized retail saturates these markets.
- Biobased procurement mandates:US federal purchasing requirements under the BioPreferred program create preferential channel access for certified suppliers.
- Enzyme-surfactant hybrid chemistry:Convergence of biotechnology with conventional formulation science enables cold-water performance claims that differentiate premium laundry segments.
Industry Challenges
- Toxicology assessment capacity scarcity:Formulators struggle to secure qualified regulatory scientists capable of navigating simultaneous EPA FIFRA, EU REACH, and state-level disclosure requirements.
- Legacy manufacturing asset retrofit costs:Converting tank-mix facilities for low-VOC, high-viscosity spray formulations demands capital outlays that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Cleaning Products Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $224.67 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Bathroom Cleaners, Floor Cleaners, Disinfectants Form: Liquid, Powder, Spray, Wipe Distribution Channel: Supermarkets, Online Retailers, Drugstores, Specialty Stores Customer Type: Residential, Commercial, Institution, Industrial |
| Companies Covered | Henkel, Colgate-Palmolive Company, Procter & Gamble, Kao Corporation, SC Johnson, Unilever, The Clorox Company, Church & Dwight, Reckitt Benckiser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Cleaning Products Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing simultaneous transformation as sustainability credentials displace price-per-liter as the primary procurement filter across institutional and residential channels.
Water-free concentrate tablets and dissolvable pods are rewriting the economics of shipping and shelf space. Major European drugstore chains are expanding private-label SKUs in this format, compressing liquid concentrate volumes while capturing margin through premium unit pricing. The technology is enabling direct-to-consumer subscription models that bypass traditional retail slotting fee structures.
The EU Ecolabel's revised criteria for cleaning products now mandate comprehensive ingredient disclosure and restricted substance lists that exceed REACH baseline requirements. Formulators serving the European market must maintain dual specification sheets, increasing documentation overhead but creating defensive moats against non-compliant imports. Laundry detergent manufacturers face the steepest compliance curves due to surfactant biodegradability testing protocols.
Centralized procurement through property management software platforms is fragmenting traditional distributor relationships. Multi-unit residential operators now issue RFPs through specialized procurement portals that automatically filter for green certification status, bypassing field sales relationships that historically governed contract allocation. This pattern is most visible in US Sun Belt markets where institutional ownership of rental housing concentrates buying power.
Household Cleaning Products Market Segmentation
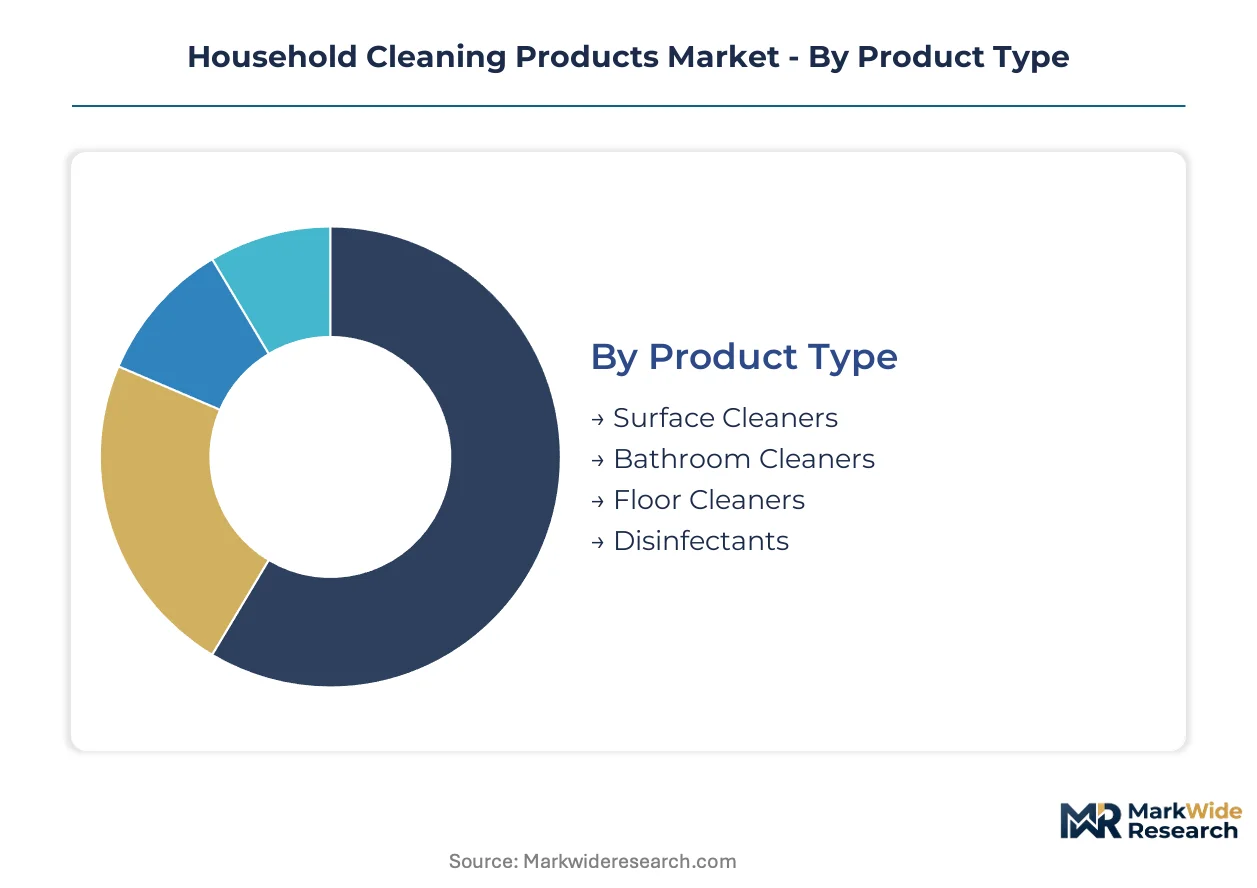
Segmentation in household cleaning products reveals how procurement power concentrates around format convenience and certification status rather than traditional brand loyalty. Buyers now filter choices through sustainability credentials and dispensing efficiency, reshaping how suppliers allocate R&D and manufacturing capacity.
Product Type:
Buyers prioritize efficacy against specific soil types and pathogen threats when selecting product categories, with post-pandemic hygiene consciousness elevating disinfectant specifications in both residential and institutional tenders.
- Surface Cleaners:Formulations combine surfactant blends with pH-adjusted solvents for multi-material compatibility. Demand concentrates in multi-unit residential complexes where property managers mandate EPA Safer Choice certification for centralized procurement contracts.
- Disinfectants:These preparations incorporate quaternary ammonium compounds or hydrogen peroxide at registered concentrations for antimicrobial claims. Institutional buyers in healthcare and education sectors drive volume through recurring sanitation protocols.
- Bathroom Cleaners:Acidic formulations target mineral deposits and soap scum on ceramic and chrome surfaces.
- Floor Cleaners:pH-neutral solutions protect sealed wood and vinyl substrates while removing particulate soil.
Volume sits with surface cleaners; growth tilts toward disinfectants.
Form:
Format selection hinges on water access, storage constraints, and time-to-task efficiency, with convenience-seeking residential buyers abandoning dilutable concentrates for ready-to-use alternatives.
- Spray:Pressurized dispensers deliver fine-mist application for vertical and overhead surfaces. Southeast Asian urban households in Jakarta and Bangkok favor this format for compact storage in high-density apartments.
- Wipe:Pre-saturated nonwoven substrates eliminate mixing and measurement steps. Travel and workplace segments sustain premium pricing for portable single-use packs.
- Liquid:Concentrated and ready-to-dilute variants dominate institutional bulk purchasing.
- Powder:Low-moisture formulations persist in manual scrubbing applications and emerging markets with irregular water supply.
Spray formats command shelf visibility; wipes are expanding most quickly through subscription direct-to-consumer channels.
Distribution Channel:
Channel selection reflects buyer urgency, basket size, and certification verification needs, with green procurement mandates rewriting traditional distributor relationships.
- Supermarkets:Mass retail chains control promotional visibility and impulse purchase volume. Shelf dominance here requires slotting fee capacity that rewards scale players with reformulation infrastructure.
- Online Retailers:E-commerce platforms capture subscription replenishment and specialty formulation searches. This channel climbs fastest as water-free concentrate tablets enable lightweight shipping economics.
- Drugstores:European chains anchor premium positioning for specialized laundry and home care formulations.
- Specialty Stores:Independent retailers serve professional cleaning contractors and eco-conscious niches.
Supermarkets retain transaction volume; online retailers gain share fastest in urban middle-class segments.
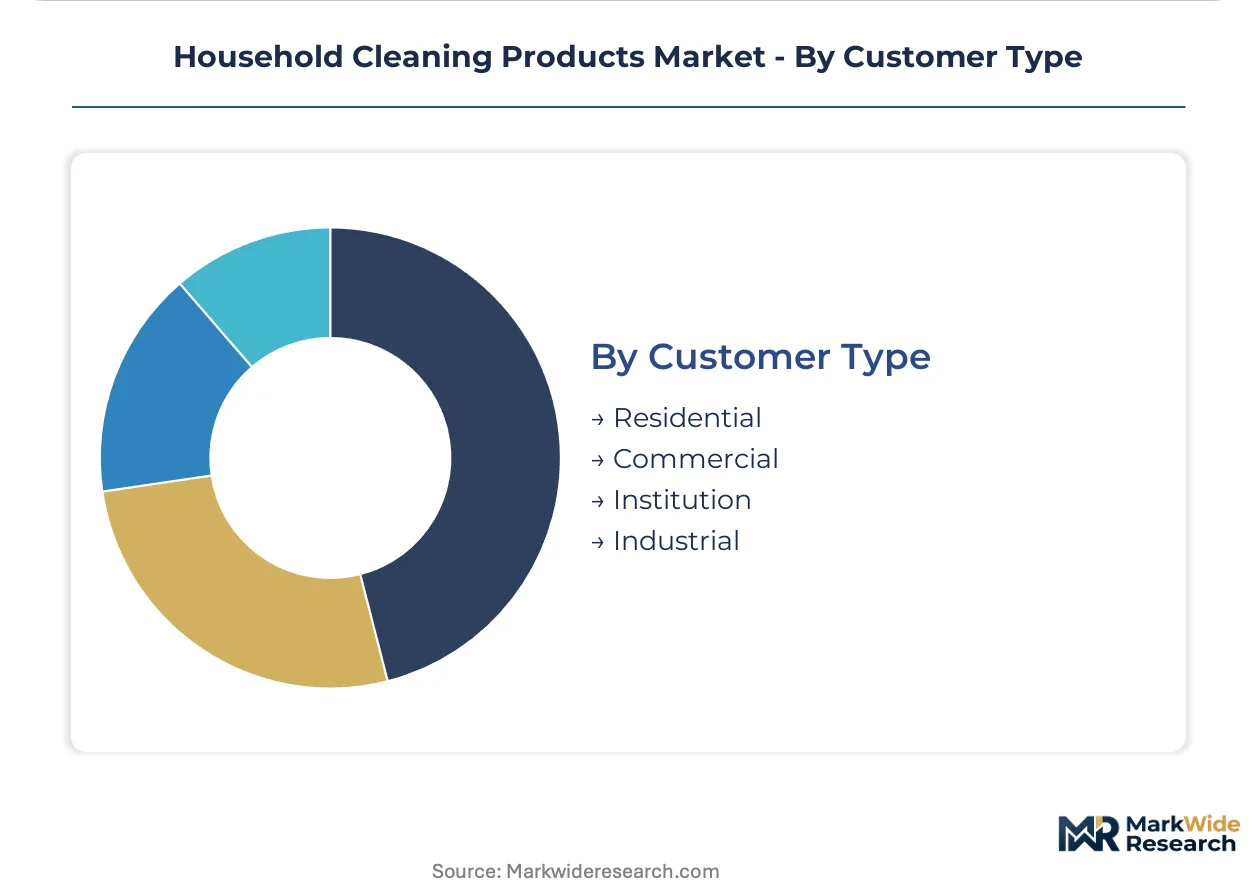
Customer Type:
End-use segmentation tracks regulatory exposure and procurement centralization, with institutional buyers imposing specification standards that cascade to residential formulations.
- Residential:Individual households select through retail shelves and digital platforms. Convenience and scent profiles dominate purchase decisions here.
- Commercial:Property management groups consolidate procurement through software platforms that filter for green certification status. US Sun Belt rental housing operators exemplify this concentrated buying power.
- Institution:Healthcare and education facilities require documented compliance with EPA FIFRA and state-level disclosure mandates.
- Industrial:Food processing and manufacturing sites demand heavy-duty degreasers with occupational safety documentation.
Commercial buyers concentrate contract value; residential segments sustain the steepest expansion trajectory through emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property management software platforms now filter procurement through green certification status, concentrating contract value in the United States, Germany, Japan, Vietnam, and Brazil where regulatory infrastructure and urban density create divergent competitive conditions.
United States
Multi-unit residential operators in the Sun Belt drive centralized procurement through specialized portals that mandate EPA Safer Choice certification. The California Air Resources Board imposes volatile organic compound limits that reshape national formulation architecture. Dallas-Fort Worth rental housing concentrations exemplify how institutional ownership concentrates buying power around compliant suppliers.
Germany
European drugstore chains anchor premium positioning for specialized laundry formulations with strict biodegradability requirements. The EU Ecolabel's revised cleaning product criteria mandate comprehensive ingredient disclosure beyond REACH baseline standards. The Rhine-Ruhr industrial corridor hosts concentrated formulation R&D facilities serving continental private-label expansion.
Japan
Compact spray formats dominate Tokyo and Osaka apartment households where storage constraints favor convenience packaging. METI guidelines on chemical substance management influence regional disclosure standards. The Kanto region's dense urban corridors sustain premium pricing for ready-to-use surface preparations with specialized dispensing mechanisms.
Vietnam
Ho Chi Minh City and Jakarta households outpace historical Western consumption patterns for surface disinfectants as modern trade expands. The country's national chemical regulator tightens import documentation for antimicrobial actives. Secondary cities in the Mekong Delta offer first-mover positioning before organized retail saturates these penetration gaps.
Brazil
São Paulo's urban middle-class sustains volume demand for laundry additives and multi-surface cleaners through supermarket chains. ANVISA registration requirements for sanitizing claims create compliance friction for non-compliant imports. The Southeast industrial belt concentrates manufacturing assets serving Mercosur distribution networks.
Household Cleaning Products Market Vendor Landscape
North American producers anchor one tier; European specialists hold formulation premium positioning; Asian manufacturers capture emerging market volume through adapted format strategies. The structure concentrates around scale players with backward integration into surfactant supply and regulatory compliance infrastructure. Three archetypes dominate: diversified consumer goods conglomerates with shelf dominance capacity, specialized home care formulators with regional certification expertise, and private-label manufacturers serving retailer consolidation. Competitive moves center on M&A for green chemistry capabilities and strategic partnerships with property management software platforms.
Among diversified consumer goods conglomerates, Procter & Gamble, Unilever, and Henkel exemplify the tier where manufacturing scale secures mass retail shelf dominance and reformulation agility navigates tightening environmental compliance. These entities occupy positions where global brand architecture supports multi-jurisdiction certification maintenance, representing the consolidation endpoint as procurement centralization squeezes mid-tier suppliers lacking comparable infrastructure investment capacity.
| Leading Market Players |
|---|
| Henkel |
| Colgate-Palmolive Company |
| Procter & Gamble |
| Kao Corporation |
| SC Johnson |
| Unilever |
| The Clorox Company |
| Church & Dwight |
| Reckitt Benckiser Group |
| Others |
Supply Flow & Price Mechanics
EPA Safer Choice certification gates both qualified supply and premium-tier pricing access, as property management groups in Dallas-Fort Worth and comparable Sun Belt markets mandate this label for centralized procurement contracts. Formulators lacking compliant chemistry infrastructure face exclusion from the fastest-expanding institutional channel while certified suppliers capture pricing power through limited competition.
Pricing Analysis
Volume concentrates in economy-tier liquid concentrates sold through supermarket chains, while margins accrue to premium spray-and-wipe formats with specialized dispensing mechanisms. Price differentiation rests on EPA Safer Choice certification status and backward integration into surfactant supply, with certified formulations commanding shelf positioning that uncertified competitors cannot match. Cost compression in economy tiers is intensifying because palm oil and petrochemical derivative volatility squeezes formulators lacking captive raw material sources. Residential buyers in Southeast Asian urban markets exhibit highest price sensitivity, whereas US commercial property managers prioritize compliance over per-unit cost.
Supply Chain Analysis
US BioPreferred program domestic-content mandates are reshaping sourcing decisions for suppliers seeking federal procurement access. Manufacturing concentrates in the United States, Germany, and China, with the Rhine-Ruhr corridor hosting concentrated formulation R&D and the US Gulf Coast anchoring surfactant production. Raw material dependencies center on palm oil derivatives, petroleum-based solvents, and quaternary ammonium compounds. Single-source vulnerability in Southeast Asian palm supply creates exposure to El Niño-driven harvest disruptions. Distribution runs through supermarket chains for volume, with online platforms capturing fastest expansion through water-free concentrate tablet economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household cleaning products sector is undergoing a technology-transition phase as water-free concentrate tablets and dissolvable pods displace legacy liquid formulations. This shift rewrites shipping economics and enables direct-to-consumer subscription models that bypass traditional retail slotting structures.
For Market Incumbents: Extend certification maintenance capabilities across multiple jurisdictions to defend against mid-tier suppliers squeezed by simultaneous EPA FIFRA, EU REACH, and California Air Resources Board compliance burdens. Deepen backward integration into surfactant supply to buffer margin pressure from palm oil and petrochemical volatility. Prioritize manufacturing asset retrofit for high-viscosity spray formulation capacity before legacy tank-mix facilities become stranded. For New Entrants and Emerging Players: EU Ecolabel's revised cleaning product criteria in Europe opens a window for specialized laundry formulations with comprehensive ingredient disclosure that exceeds REACH baseline requirements. Target secondary cities in Vietnam's Mekong Delta before organized retail saturates penetration gaps. Pursue direct-to-consumer subscription models leveraging water-free concentrate tablet lightweight shipping economics. For Investors and Strategic Acquirers: Property management software platform RFPs filtering for green certification status is the leading indicator that contract value will concentrate among compliant suppliers with regulatory infrastructure already deployed. The five-to-ten year viability window favors acquisition targets with dual EPA Safer Choice and EU Ecolabel certification capabilities plus existing relationships with institutional rental housing operators. Monitor toxicology assessment capacity scarcity as a signal of which formulators can sustain multi-jurisdiction compliance without bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Acquisition | EPA Safer Choice certification infrastructure transfers immediately to acquirer's portfolio. |
| Backward Integration into Surfactants | Palm oil and petrochemical supply control buffers margin compression from energy volatility. |
| Spray Format Manufacturing Retrofit | High-viscosity production capacity captures convenience-seeking residential buyer migration. |
| Property Management Platform Partnership | Direct RFP access bypasses field sales relationships that historically governed contract allocation. |
| Southeast Asia Distribution Buildout | Ho Chi Minh City and Jakarta modern trade expansion enables first-mover positioning. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across plant managers at formulation facilities, procurement leads at multi-unit residential operators, category buyers at European drugstore chains, and technical R&D directors specializing in enzyme-surfactant hybrid chemistry. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure consistency across volume and value estimates.
Granularity-level modeling deployed product type, form, distribution channel, and customer type as core segmentation dimensions, with additional disaggregation by certification status tier and regional regulatory cluster. CAGRs were derived through trend extrapolation calibrated to historical consumption elasticity and forward-looking procurement mandate trajectories across the analysis window. Forecast inputs incorporated surfactant feedstock price volatility indices and property management software platform adoption curves.
The model assumes a particular technology adoption path for water-free concentrate tablets; alternative pathways for dissolvable pod chemistry would alter the outlook for shipping economics and subscription channel penetration. Forecasts reflect assumptions around EPA Safer Choice program continuity, EU REACH substance ban evolution, and Southeast Asian urban middle-class expansion velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Bathroom Mirror Wiper Market