
 Household Wipes Market | 2026-2036
Household Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Household Wipes Market Analysis
Premium antimicrobial specifications are redrawing competitive boundaries in household wipes. Procter & Gamble leverages proprietary fiber technology to sustain shelf visibility in mass retail. S. C. Johnson & Son anchors its position through concentrated R&D spending on botanical actives. Kimberly-Clark dominates institutional channels with specialized dispensing systems.
Household wipes are non-woven substrate products impregnated with cleaning, disinfecting, or conditioning solutions, typically manufactured through hydroentanglement or thermal bonding of synthetic or cellulosic fibers to achieve specified tensile strength and liquid retention. They serve residential and commercial sanitation needs where convenience, pathogen reduction, and surface compatibility converge. Disinfectant wipes command the largest revenue pool due to health-protocol persistence post-pandemic, while biodegradable material grades represent the fastest structural expansion as procurement policies across hospitality and educational institutions prioritize plastic reduction. Non-woven fabric substrates retain manufacturing scale advantages, though cotton and paper alternatives carve margin in certified organic channels.
The EPA regulates antimicrobial claims through FIFRA-mandated registration, compelling reformulation cycles for active ingredient changes. ECHA's REACH restrictions on quaternary ammonium compounds and the EU Green Deal's single-use plastic directives reshape export-bound product architectures. China's SAMR enforces GB standards for disposable hygiene products, affecting cross-border supply qualifications. Stakeholders must monitor divergence between regional chemical approval lists and packaging compliance timelines to avoid stranded inventory or access barriers.
Market Dynamics
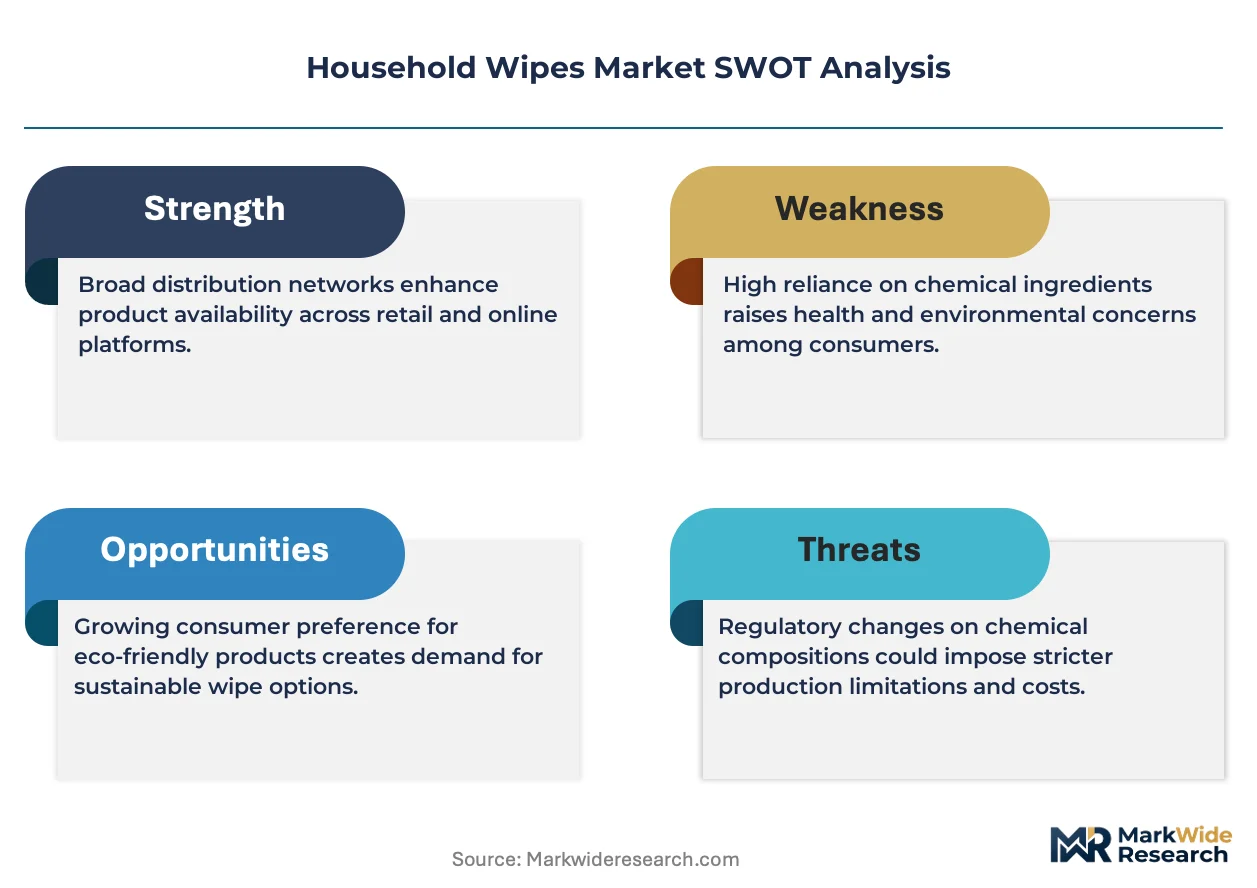
Plastic-phaseout mandates across OECD jurisdictions are forcing substrate reformulation cycles faster than manufacturing retooling timelines, compressing margin structures for producers locked into polyester supply chains.
Growth Catalysts
- EPA Safer Choice certification:Federal procurement preferences for labeled products drive institutional volume commitments in US school districts and municipal facilities.
- Cellulosic fiber hydroentanglement:Advanced bonding processes enable cotton-linen blends to match synthetic tensile performance at competitive unit economics.
- Urban sanitation density:Apartment household concentration in Shanghai, Mumbai, and São Paulo creates concentrated demand nodes for single-use convenience formats.
Market Restraints
- Viscose staple fiber price volatility:Dissolving pulp input costs fluctuate with textile sector demand cycles, squeezing converter margins unpredictably.
- Quaternary ammonium compound restrictions:ECHA REACH authorization timelines delay new antimicrobial claim approvals, freezing product pipeline releases.
- Reusable microfiber substitution:Machine-washable alternatives capture cost-conscious household segments in Northern European markets.
Strategic Opportunities
- Rural India distribution gaps:Kirana store networks remain underserved by organized wet-wipe supply, offering first-mover consolidation potential.
- EU Green Deal packaging mandates:Recycled-content thresholds create certified-product premiums in hospitality procurement tenders.
- Subscription replenishment models:Direct-to-home auto-delivery platforms bypass retail slotting fee structures for premium botanical formulations.
Industry Challenges
- Biodegradability certification timelines:TÜV OK Compost and BPI validation protocols extend launch schedules by 8-14 months.
- Legacy converting equipment retrofit costs:Thermal bonding lines require seven-figure capital outlays to process plant-based fiber inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Wipes Market |
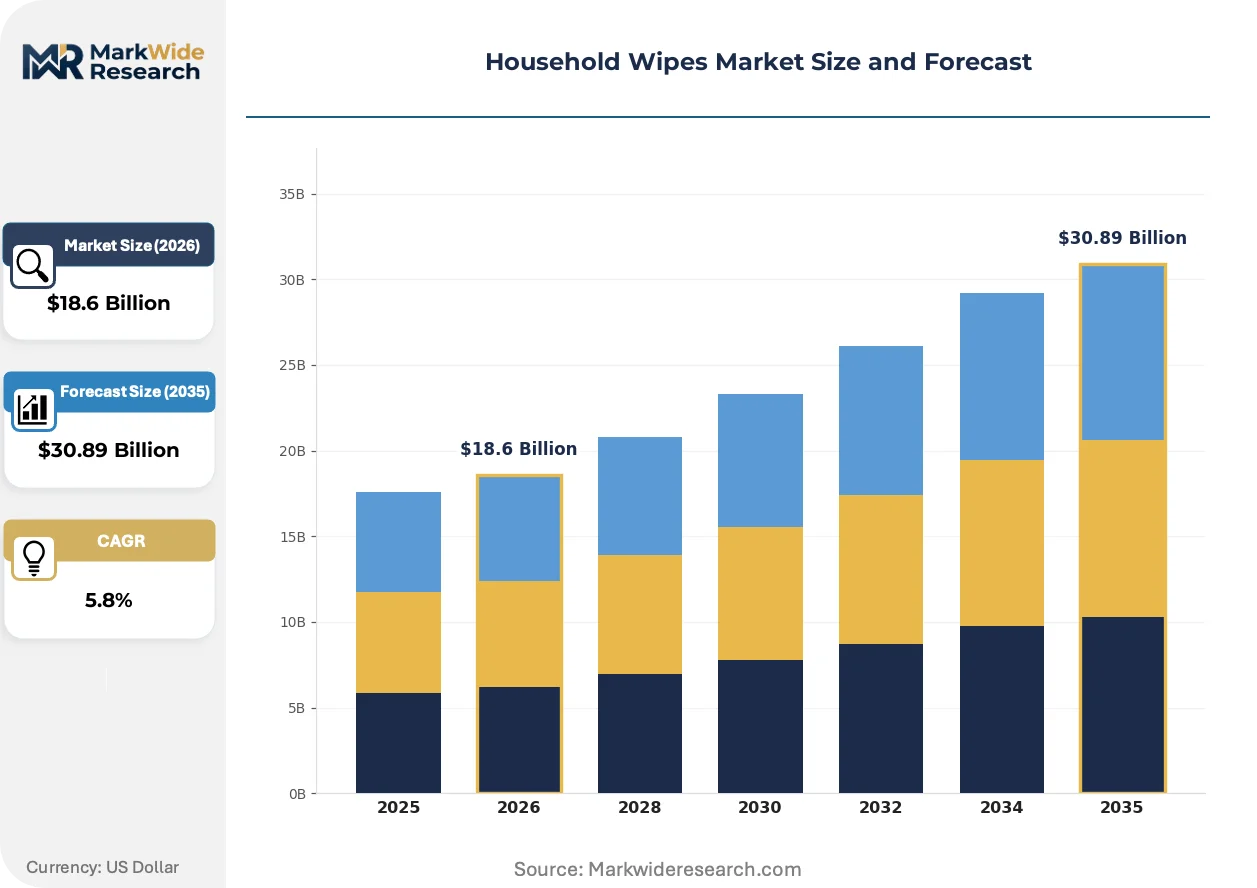
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectant Wipes, All-Purpose Wipes, Glass Wipes, Baby Wipes Material: Non-Woven Fabric, Cotton, Paper, Biodegradable Packaging Type: Plastic Tub, Resealable Pack, Single-Use Pouch, Bulk Container End User: Households, Hospitality, Healthcare, Educational Institutions |
| Companies Covered | Procter & Gamble, S. C. Johnson & Son, The Clorox Company, Reckitt Benckiser Group plc, Nice-Pak Products, Inc., Kimberly-Clark Corporation, 3M Company, Colgate-Palmolive Company, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Wipes Market Emerging Trajectories
Active ingredient disclosure requirements and substrate traceability demands are rewiring competitive advantage toward supply chain transparency rather than formulation secrecy alone.
Polylactic acid spunlace nonwovens are decomposing industrial composting standards as the reference benchmark for biodegradability claims. Quick-service restaurant chains in California and Washington State specify PLA substrates in sanitation supply contracts. This shift is decomposing incumbent petroleum-based fiber market positions by 2030.
REACH microplastic restrictions compel reformulation of polyester-based substrates for export-bound European shipments. Manufacturers must demonstrate fiber fragmentation below 5mm thresholds under standardized test protocols. Wipes destined for German and French retail channels now require polymer-type labeling and disposal pathway instructions.
Ingredient transparency scanning via mobile applications is altering supermarket aisle behavior. Millennial and Gen-Z purchasers in US coastal metros verify EWG ratings and EPA registration numbers before basket placement. This verification habit compresses trial rates for unverified private-label entrants in mass-market retail channels.
Household Wipes Market Segmentation
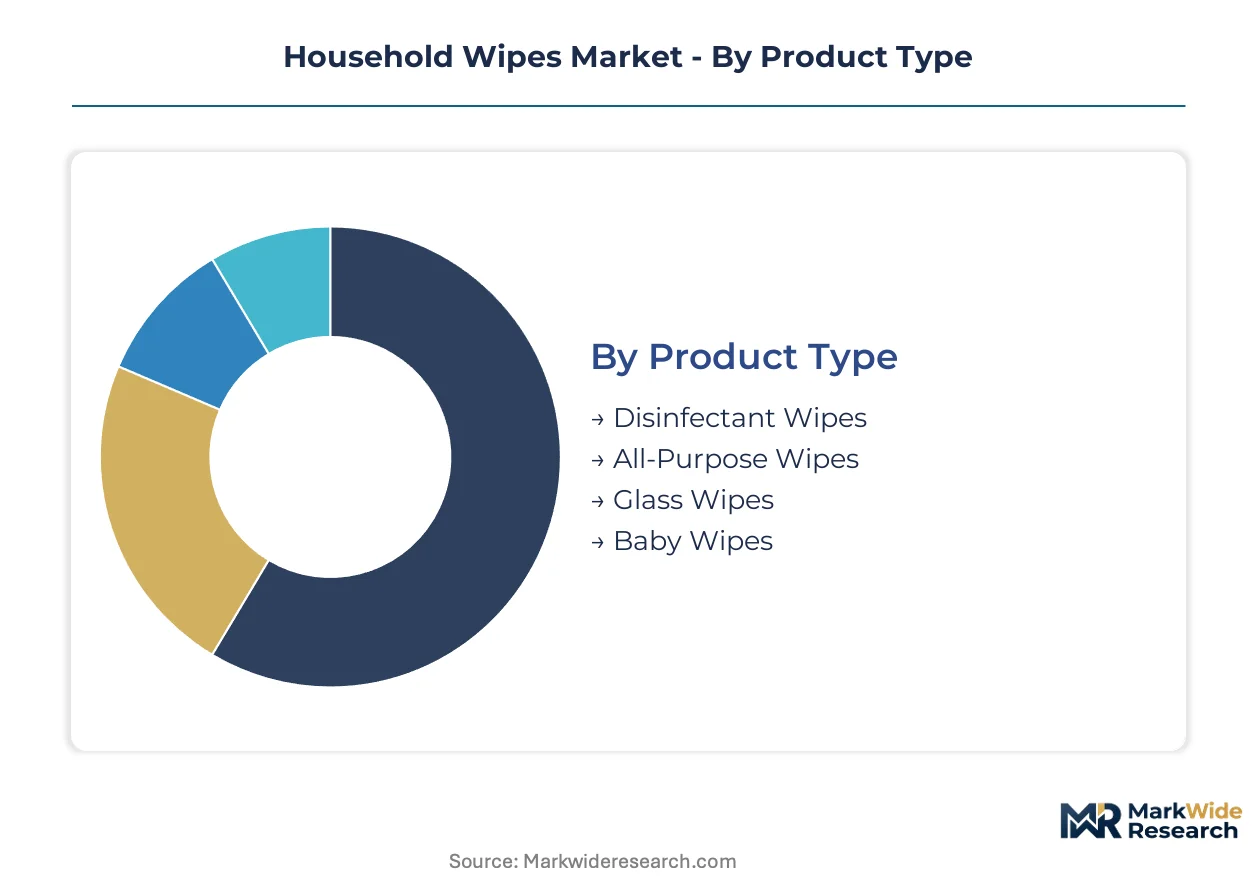
Household wipes segmentation reveals how formulation chemistry, substrate engineering, and packaging format each command distinct margin architectures. Procurement policies across institutional channels are rewiring volume concentration away from traditional retail dominance toward certified sustainable supply chains.
Product Type:
Margin pools concentrate in formulations carrying antimicrobial registration, where regulatory compliance creates defendable pricing power against commodity alternatives.
- Disinfectant Wipes:Impregnated with quaternary ammonium compounds or hydrogen peroxide solutions at EPA-registered concentrations, these substrates deliver pathogen reduction claims for healthcare and foodservice protocols. Demand clusters in US school districts and German hospital procurement tenders where Safer Choice and EU Green Deal compliance filter supplier pools.
- All-Purpose Wipes:General surfactant formulations balance grease cutting with surface compatibility across countertops, appliances, and sealed flooring. Volume concentrates in Chinese urban households and Brazilian apartment complexes where convenience premiums outweigh reusable alternatives.
- Glass Wipes:Ammonia-free solutions with streak-resistant polymers target automotive and residential window cleaning segments.
- Baby Wipes:pH-balanced formulations with aloe and chamomile extracts serve infant care routines with dermatological sensitivity requirements.
Disinfectant wipes hold installed capacity. All-purpose wipes are rotating up the share rankings.
Material:
Cost tier separation runs deepest between petroleum-derived synthetics and certified compostable alternatives, with procurement premiums widening in European hospitality channels.
- Non-Woven Fabric:Polyester or polypropylene spunlace substrates dominate manufacturing scale through hydroentanglement bonding, delivering tensile strength above 30N/5cm for wet mechanical durability. US mass retail and Chinese e-commerce platforms anchor volume concentration despite mounting plastic-phaseout pressure.
- Biodegradable:Polylactic acid and wood-pulp spunlace materials achieve TÜV OK Compost certification for industrial decomposition within 180 days. German quick-service restaurant chains and French hotel groups specify these substrates in mandatory sustainability tenders, capturing procurement premiums unavailable to conventional fiber suppliers.
- Cotton:Carded natural fibers serve certified organic retail channels with dermatological positioning.
- Paper:Cellulosic wet-strength substrates occupy economy-tier price positioning in emerging market distribution.
Non-woven fabric holds installed capacity. Biodegradable is climbing the fastest.
Packaging Type:
Application context dictates format selection, with institutional bulk formats commanding lower per-unit costs and residential convenience formats sustaining retail margin.
- Resealable Pack:Laminated film pouches with adhesive strip closures balance moisture retention against shelf footprint for household pantry storage. US suburban households and Japanese apartment dwellers drive replenishment frequency through subscription auto-delivery platforms.
- Plastic Tub:Rigid polypropylene containers with hinged lids enable one-handed dispensing for kitchen and bathroom countertop placement. Chinese hypermarket chains and Indian modern trade formats anchor volume through prominent shelf positioning.
- Single-Use Pouch:Individual sachet packaging serves airline, hospitality, and foodservice amenity applications.
- Bulk Container:Refill canisters and institutional dispensers reduce per-wipe cost for educational and healthcare facilities.
Plastic tub holds installed capacity. Resealable pack is gaining share fastest.
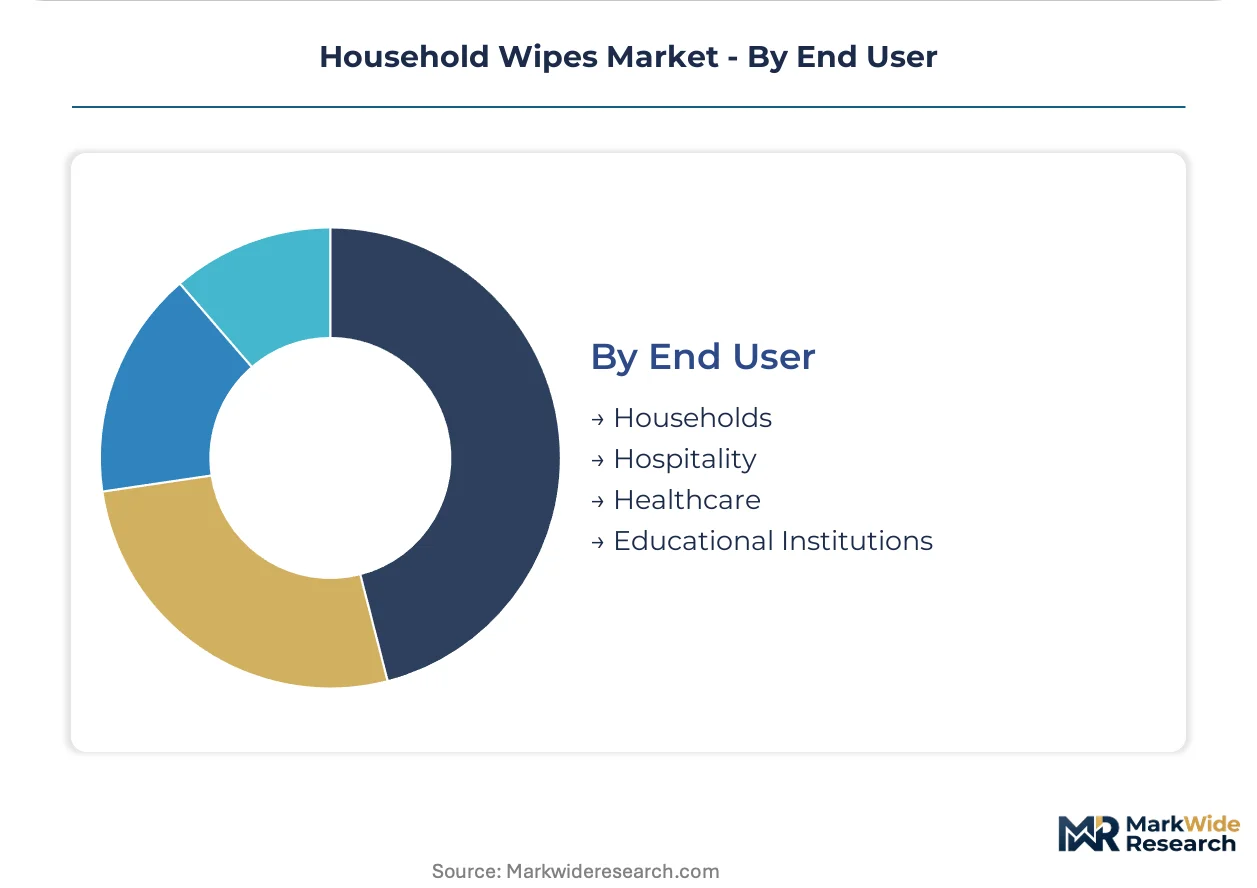
End User:
Customer type segmentation separates price-sensitive household procurement from institutional tender processes where compliance documentation and volume commitments reshape competitive access.
- Households:Individual consumers purchase through supermarket, drugstore, and e-commerce channels with preference for convenience formats and botanical ingredient positioning. Mumbai, São Paulo, and Jakarta apartment concentrations create dense demand nodes for single-use wipe adoption.
- Hospitality:Hotels, restaurants, and catering operations specify EPA-registered or EU-compliant formulations with documented safety data sheets for staff handling protocols. California and Washington State plastic bans are accelerating substrate specification shifts in this segment.
- Healthcare:Hospitals and clinics require disinfectant wipes with validated kill claims against healthcare-associated pathogens.
- Educational Institutions:K-12 schools and universities combine procurement volume with federal preference programs like EPA Safer Choice in US municipal contracting.
Households hold installed capacity. Hospitality is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States, China, and Germany, with each jurisdiction imposing distinct chemical registration and packaging mandates that fragment export qualification requirements. Urban sanitation density and federal procurement programs reshape volume concentration across metropolitan corridors. Regulatory divergence between EPA, SAMR, and ECHA compliance timelines creates inventory stranding risks for cross-border suppliers.
United States
School district procurement and municipal facility contracts concentrate demand in EPA Safer Choice-certified formulations. The EPA's FIFRA-mandated antimicrobial registration compels reformulation cycles for active ingredient changes. Chicago and Los Angeles metropolitan areas anchor institutional volume through federal preference program compliance.
China
Apartment household density in Shanghai and Shenzhen drives single-use convenience format adoption. SAMR enforces GB standards for disposable hygiene products, affecting cross-border supply qualifications. Yangtze River Delta manufacturing clusters process cellulosic fiber hydroentanglement for domestic and export markets.
Germany
Quick-service restaurant chains and hotel groups specify TÜV OK Compost-certified substrates in mandatory sustainability tenders. ECHA REACH restrictions on quaternary ammonium compounds delay new antimicrobial claim approvals. North Rhine-Westphalia industrial zones convert thermal bonding lines for plant-based fiber inputs.
India
Kirana store networks in rural districts remain underserved by organized wet-wipe supply, offering first-mover consolidation potential. BIS certification requirements for imported hygiene products create entry barriers for unqualified suppliers. Mumbai and Delhi-NCR apartment concentrations generate dense demand nodes for convenience formats.
Brazil
São Paulo apartment density and sanitation standard tightening drive adoption of single-use convenience formats. ANVISA regulates antimicrobial claims through pharmaceutical-grade registration pathways. Southeast industrial corridors develop converting capacity for regional supply chain localization.
Household Wipes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary fiber developers commanding premium positioning while scale converters capture mass-market volume. The market structures around three tiers: multinational consumer goods conglomerates with regulatory compliance infrastructure, specialized non-woven converters with substrate engineering capabilities, and private-label assemblers competing on slotting fee minimization. Dominant competitive moves include backward integration into fiber supply and strategic partnerships with hospitality procurement consortia.
Among consumer goods conglomerates, Procter & Gamble, S. C. Johnson & Son, and Kimberly-Clark occupy positions that exemplify divergent strategic archetypes. Procter & Gamble represents technology-driven premium positioning through proprietary fiber development. S. C. Johnson & Son anchors botanical-active formulation specialization. Kimberly-Clark sits within institutional channel dominance through dispensing system integration. These three entities collectively illustrate how regulatory compliance infrastructure and manufacturing scale create defendable market access across divergent customer segments.
| Leading Market Players |
|---|
| Procter & Gamble |
| S. C. Johnson & Son |
| The Clorox Company |
| Reckitt Benckiser Group plc |
| Nice-Pak Products, Inc. |
| Kimberly-Clark Corporation |
| 3M Company |
| Colgate-Palmolive Company |
| Unilever PLC |
| Others |
Supply Flow & Price Mechanics
Cellulosic fiber substitution for petroleum-based synthetics simultaneously concentrates supply geography in Yangtze River Delta manufacturing clusters and compresses pricing power for polyester-dependent converters. This input transition rewires cost structures across substrate tiers while regulatory compliance timelines create temporary margin premiums for certified alternatives.
Pricing Analysis
EPA Safer Choice certification dictates the pricing tier structure by filtering institutional procurement pools toward registered formulations commanding defendable premiums. Three-tier pricing structure across premium, standard, and economy levels separates botanical-active disinfectants from commodity surfactant blends and generic private-label alternatives. Pricing pressure stems from viscose staple fiber cost volatility as dissolving pulp demand cycles squeeze converter margins unpredictably. Mass-market households exhibit highest price sensitivity while hospitality procurement committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
Dissolving pulp supply concentration in Southeast Asian plantation networks underwrites cellulosic fiber availability for hydroentanglement lines. Manufacturing capacity clusters in China, Germany, and the United States with each jurisdiction imposing distinct chemical registration mandates. Raw material dependencies span petroleum-derived polyester, wood-pulp dissolving pulp, and polylactic acid resin feedstocks. Single-source vulnerability runs through quaternary ammonium compound suppliers facing ECHA REACH authorization delays. Distribution runs through mass retail chains, e-commerce platforms, and institutional procurement consortia with divergent compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household wipes market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive advantages through EPA antimicrobial registration timelines and biodegradability certification protocols that freeze out unqualified competitors.
For Market Incumbents: Compound regulatory compliance infrastructure into channel lock-in by accelerating TÜV OK Compost certification pipelines before EU Green Deal packaging mandates tighten. Defend shelf positioning through backward integration into cellulosic fiber hydroentanglement capacity in Yangtze River Delta clusters. Capacity addition in Germany's North Rhine-Westphalia industrial zones captures hospitality procurement premiums as polyester substitution accelerates.
For New Entrants and Emerging Players: Differentiate on substrate traceability transparency via mobile-verified supply chain disclosure that millennial and Gen-Z purchasers in US coastal metros demand before basket placement. Target rural India kirana store networks where organized wet-wipe supply remains underpenetrated. Launch through direct-to-home subscription auto-delivery platforms that bypass retail slotting fee structures for premium botanical formulations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized non-woven converters with substrate engineering capabilities over private-label assemblers competing on slotting fee minimization. Long-term viability across the projection horizon rests on capturing procurement premiums in European hospitality channels where sustainability tenders widen cost-tier separation. Monitor ECHA REACH microplastic restriction enforcement timelines as the inflection indicator for polyester-based substrate obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradability Certification Acceleration | TÜV OK Compost validation secures access to EU Green Deal-mandated hospitality procurement tenders. |
| Cellulosic Fiber Backward Integration | Captive dissolving pulp supply insulates margin structures from textile sector demand cycle volatility. |
| Direct-to-Consumer Platform Launch | Subscription auto-delivery bypasses mass retail slotting fees for premium botanical formulations. |
| Institutional Dispensing System Integration | Kimberly-Clark-style specialized hardware locks educational and healthcare facilities into replenishment contracts. |
| Rural Distribution Network Expansion | Kirana store consolidation in underserved Indian districts captures first-mover volume before organized retail penetration. |
Methodological Framework
Desk research of customs trade records, EPA antimicrobial registration databases, and EU ECHA REACH authorization filings preceded structured interviews with non-woven converter plant managers, hospitality procurement directors, retail category buyers, and regulatory affairs specialists at consumer goods conglomerates. Primary fieldwork with substrate engineers and distribution channel partners combined with secondary validation against Nielsen retail audit data and SEC 10-K filings. Bottom-up volume modeling across product type, material grade, and end-use segments triangulated against top-down market sizing.
Variance decomposition across the analysis window isolates volume drivers from price-mix effects in segment-level forecasts. Segmentation dimensions modeled include formulation chemistry tier, substrate material certification status, packaging format convenience index, and regional regulatory cluster. CAGRs were derived through regression-based trajectory fitting against historical adoption curves and policy implementation timelines. Industry-specific inputs incorporate EPA Safer Choice program enrollment rates and ECHA quaternary ammonium compound restriction phase-in schedules.
The analysis sits within stated boundaries; outcomes outside current EPA, ECHA, and SAMR regulatory trajectories would require recalibration. Forecasts reflect assumptions regarding plastic-phaseout mandate adherence and cellulosic fiber scale-up timelines that remain vulnerable to dissolving pulp supply disruptions or trade policy shifts. Practitioners should keep alternative scenarios live as biodegradability certification protocol adoption rates and hospitality procurement tender specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market