
 Global All Purpose Cleanser Market | 2026-2036
Global All Purpose Cleanser Market Size, Share, and Industry Trends Forecast 2026-2036
Global All Purpose Cleanser Market Analysis
Aftermarket service revenue from concentrated refill systems is fragmenting across brand-owned subscription platforms and third-party bulk dispensers. Procter & Gamble leverages direct-to-consumer refill pouches to sustain recurring revenue streams. Unilever anchors its market position through concentrated formats that reduce plastic intensity per cleaning cycle. SC Johnson competes via plant-derived ingredient portfolios that command premium shelf placement in European retail.
All purpose cleansers are aqueous or solvent-based formulations containing surfactants, chelating agents, and pH adjusters designed to remove soils from multiple hard surfaces without substrate damage; they typically achieve effective cleaning at dilutions between 1:32 and 1:128 depending on soil load. Liquid formulations dominate volume shipments due to compatibility with spray triggers and mop buckets, while wipe formats capture margin in healthcare and aviation maintenance where convenience commands price premiums. Spray applications lead household adoption, though industrial segments favor bulk liquid deliveries to automated dilution systems.
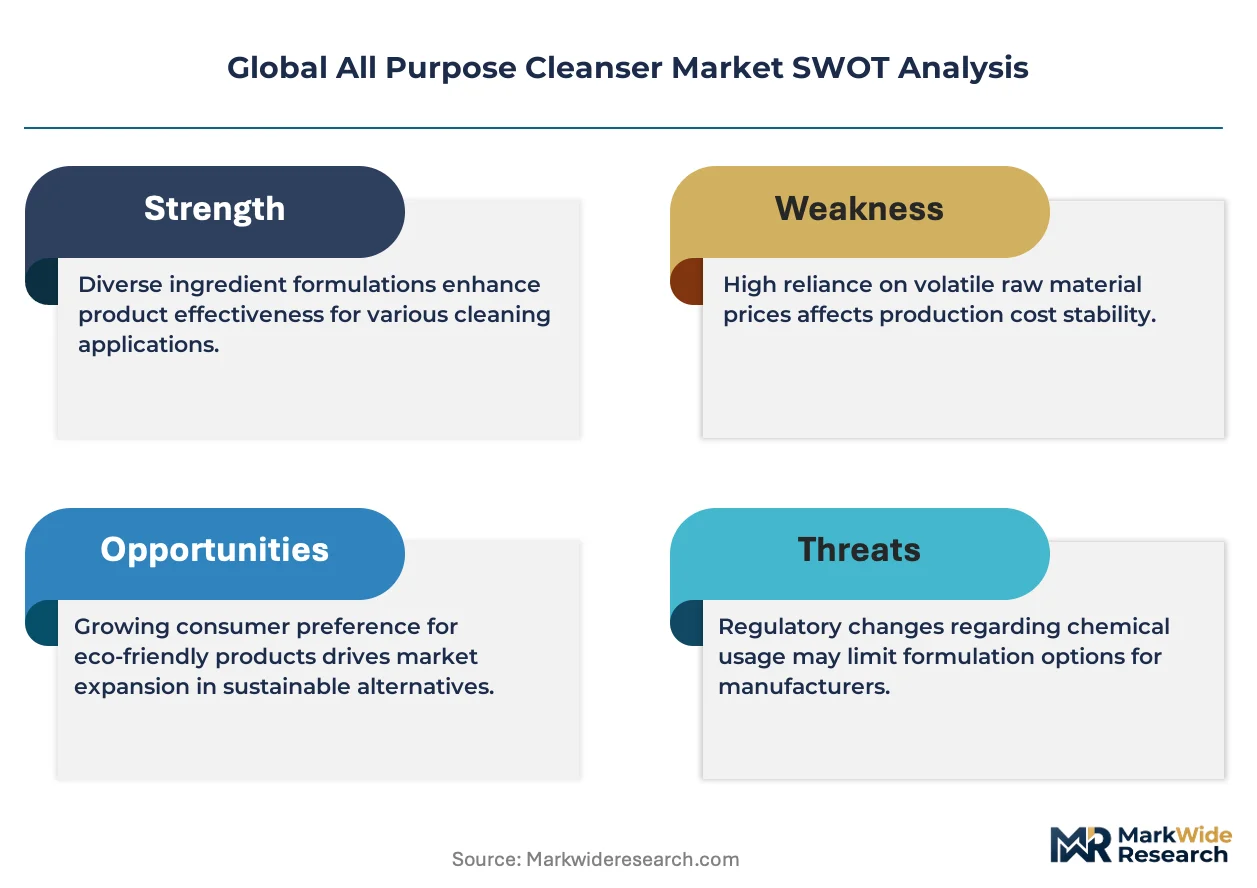
The EPA Safer Choice program and REACH restrictions in Europe compel reformulation away from alkylphenol ethoxylates and volatile organic compounds, raising compliance costs for suppliers serving multiple jurisdictions. China's GB standards for surface cleaners and the EU F-Gas Regulation on propellant gases further constrain aerosol-based product architectures. Stakeholders must monitor divergence between regional chemical hazard classifications when designing unified global product platforms.
Market Dynamics
The EPA Safer Choice program and REACH restrictions in Europe are forcing simultaneous reformulation across multiple jurisdictions, fragmenting product architectures and raising compliance costs for suppliers attempting unified global platforms.
Growth Catalysts
- Hospitality sector concentration:Hotels and foodservice operators in the United States are adopting concentrated formulations to reduce storage footprint and shipping costs per cleaning cycle.
- REACH chemical restrictions:The European regulation's phase-out of alkylphenol ethoxylates is accelerating investment in bio-based surfactant alternatives that command premium positioning.
- Automated dilution systems:Industrial facilities in Germany are installing closed-loop dispensing equipment that locks in bulk concentrate purchasing contracts.
Market Restraints
- Feedstock volatility:Palm-derived surfactants and petrochemical solvents face price instability tied to agricultural yields and crude oil fluctuations.
- Propellant constraints:The EU F-Gas Regulation restricts hydrofluorocarbon use in aerosol formats, compressing viable product architectures in European retail.
- Technical performance gaps:Plant-derived chelating agents in premium formulations often underperform synthetic alternatives on mineral scale removal.
Strategic Opportunities
- Subscription refill platforms:Direct-to-consumer concentrated pouch delivery is creating recurring revenue streams outside traditional retail channels.
- Aviation maintenance wipes:Pre-moistened formats for aircraft interior cleaning capture margin through convenience premiums in MRO facilities.
- China GB standard alignment:Reformulation to meet national surface cleaner standards opens access to provincial procurement tenders.
Industry Challenges
- Formulation chemist scarcity:Expertise in green chemistry and multi-jurisdictional regulatory compliance concentrates among a limited talent pool.
- Certification timeline compression:EPA Safer Choice and ECHA substance evaluation cycles are lengthening, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global All Purpose Cleanser Market |
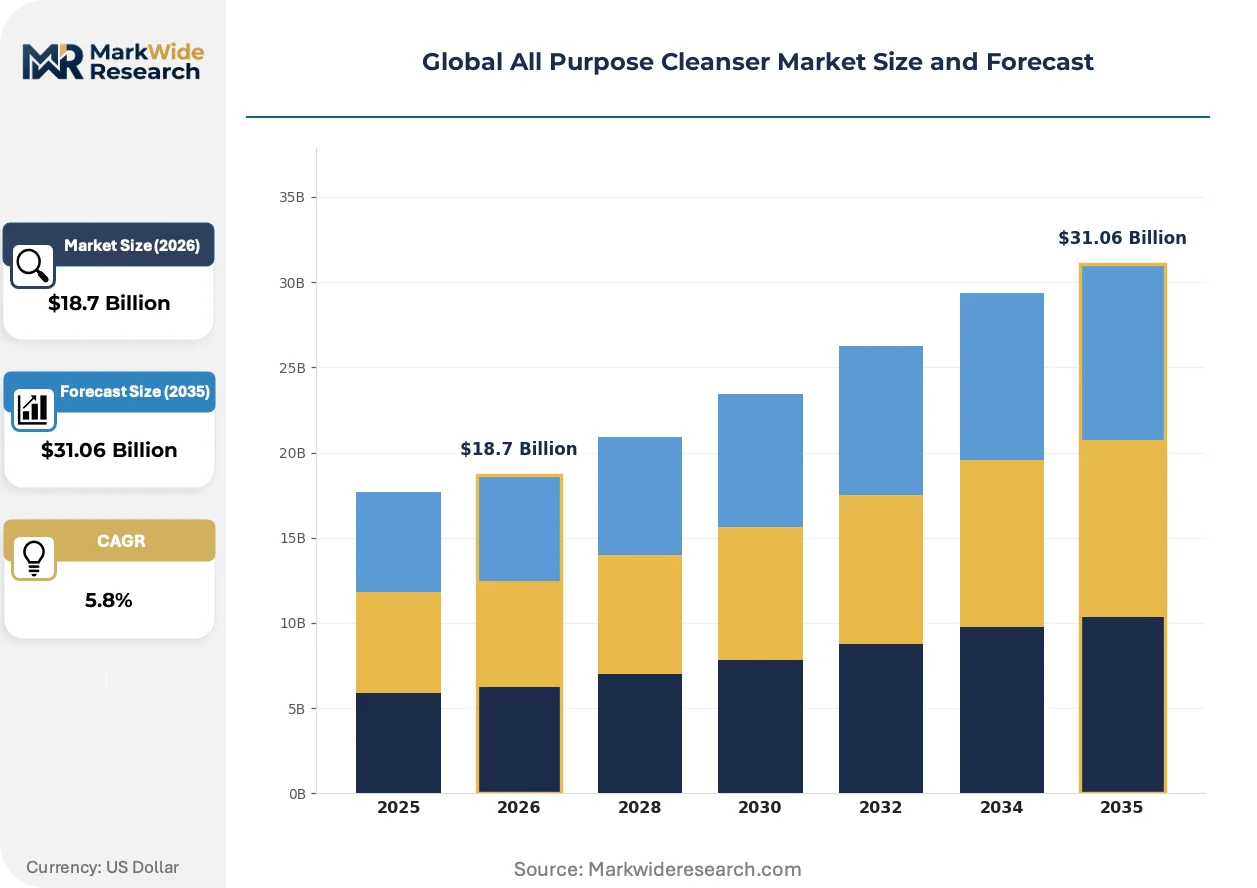
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Spray, Wipe, Gel Application: Household, Commercial, Industrial, Automotive Packaging Type: Bottle, Box, Canister, Refill Pouch Distribution Channel: Online, Supermarket, Convenience Store, Wholesale |
| Companies Covered | Procter & Gamble, Unilever, SC Johnson, Reckitt Benckiser, The Clorox Company, Henkel, Colgate-Palmolive, Ecolab, Seventh Generation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global All Purpose Cleanser Market Emerging Trajectories
Formulation science is converging with packaging engineering and digital dispensing to reshape how concentrates reach end-users. Three distinct vectors are altering competitive positioning.
Enzyme-surfactant co-formulations are hybridizing cleaning performance across pH ranges that previously required separate alkaline and acidic products. Healthcare facilities in the United States are piloting these dual-function concentrates to reduce SKU complexity in environmental services. The technology is compressing the addressable market for specialized floor and bathroom cleaners by delivering equivalent efficacy from unified inventory.
REACH authorization requirements for fragrance allergens are forcing disclosure and reformulation of scented variants sold in European retail. Manufacturers serving Germany and France are stripping limonene and linalool from mass-market SKUs to avoid labeling thresholds. The policy shift is accelerating demand for fragrance-free and hypoallergenic positioning in professional channels.
Foodservice operators are consolidating purchasing through group procurement organizations that specify concentrate-only contracts with dilution verification. Distributors in the United States are responding with private-label concentrate programs bundled with dispensing equipment leases. The behavior shift is most visible in quick-service restaurant chains where standardization across franchise locations overrides brand loyalty.
Global All Purpose Cleanser Market Segmentation
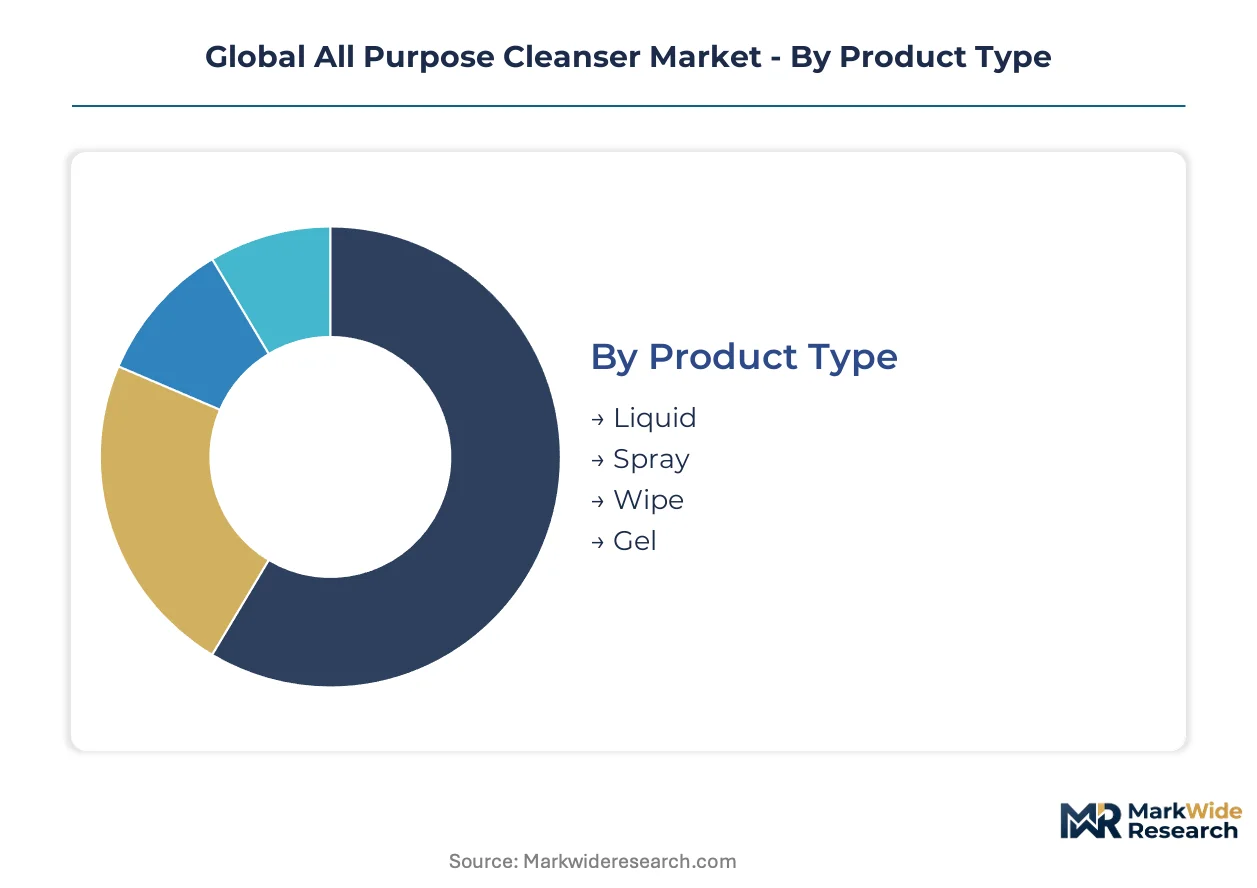
Product architecture in the all purpose cleanser market fragments across formulation physics, use intensity, and procurement economics. Understanding where volume concentrates versus where margin accumulates exposes where reformulation investments and channel partnerships deliver returns.
Product Type:
Cost tier differentiation separates commodity bulk liquids from convenience-premium formats where packaging engineering commands price multiples.
- Liquid:Aqueous or solvent-based concentrates containing surfactant-chelator blends achieve effective dilution ratios between 1:32 and 1:128. Foodservice operators in the United States specify bulk liquid deliveries to automated dilution systems that lock in concentrate purchasing contracts and reduce per-cycle plastic intensity.
- Spray:Trigger-dispensed formulations incorporate propellant-free pump mechanisms to circumvent EU F-Gas Regulation constraints on hydrofluorocarbon aerosols. German retail channels favor spray formats for household adoption where convenience commands modest premiums over manual dilution.
- Wipe:Pre-moistened substrates saturated with surfactant solutions capture margin in healthcare and aviation maintenance through labor-time savings.
- Gel:Viscous cling-formulations extend contact time on vertical surfaces for specialized industrial degreasing applications.
Liquid commands the established base. The steepest expansion runs through wipe formats in professional maintenance channels.
Application:
Customer type intensity determines formulation specification, with commercial and industrial users driving concentrate adoption while households prioritize convenience.
- Commercial:Hotels and foodservice operators adopt concentrated formulations to compress storage footprint and shipping costs per cleaning cycle. Group procurement organizations in the United States now specify concentrate-only contracts with dilution verification requirements, overriding brand loyalty in quick-service restaurant chains.
- Industrial:Automated dilution systems in German manufacturing facilities require closed-loop dispensing equipment that anchors bulk concentrate purchasing. Enzyme-surfactant co-formulations are piloting across these installations to reduce SKU complexity by hybridizing performance across previously separate alkaline and acidic pH ranges.
- Household:Spray applications dominate residential adoption where trigger-dispensed convenience outweighs per-ounce economics.
- Automotive:Specialized formulations address interior surface compatibility requirements in vehicle detailing and MRO facilities.
Commercial applications command the established base. The steepest expansion runs through industrial segments installing automated dispensing infrastructure.
Packaging Type:
Supply concentration in refill systems is fragmenting across brand-owned subscription platforms and third-party bulk dispensers.
- Bottle:Conventional polyethylene terephthalate containers remain standard for retail shelf presence and spray-trigger compatibility.
- Refill Pouch:Flexible concentrate delivery systems reduce plastic intensity per cleaning cycle by 70-80% versus ready-to-use bottles. Direct-to-consumer subscription platforms are creating recurring revenue streams outside traditional retail channels.
- Canister:Rigid packaging for wet wipe formats supports moisture retention and dispensing convenience in healthcare settings.
- Box:Corrugated containment for bulk liquid concentrates in commercial and industrial procurement.
Bottle packaging commands the established base. The steepest expansion runs through refill pouch systems in subscription and foodservice channels.
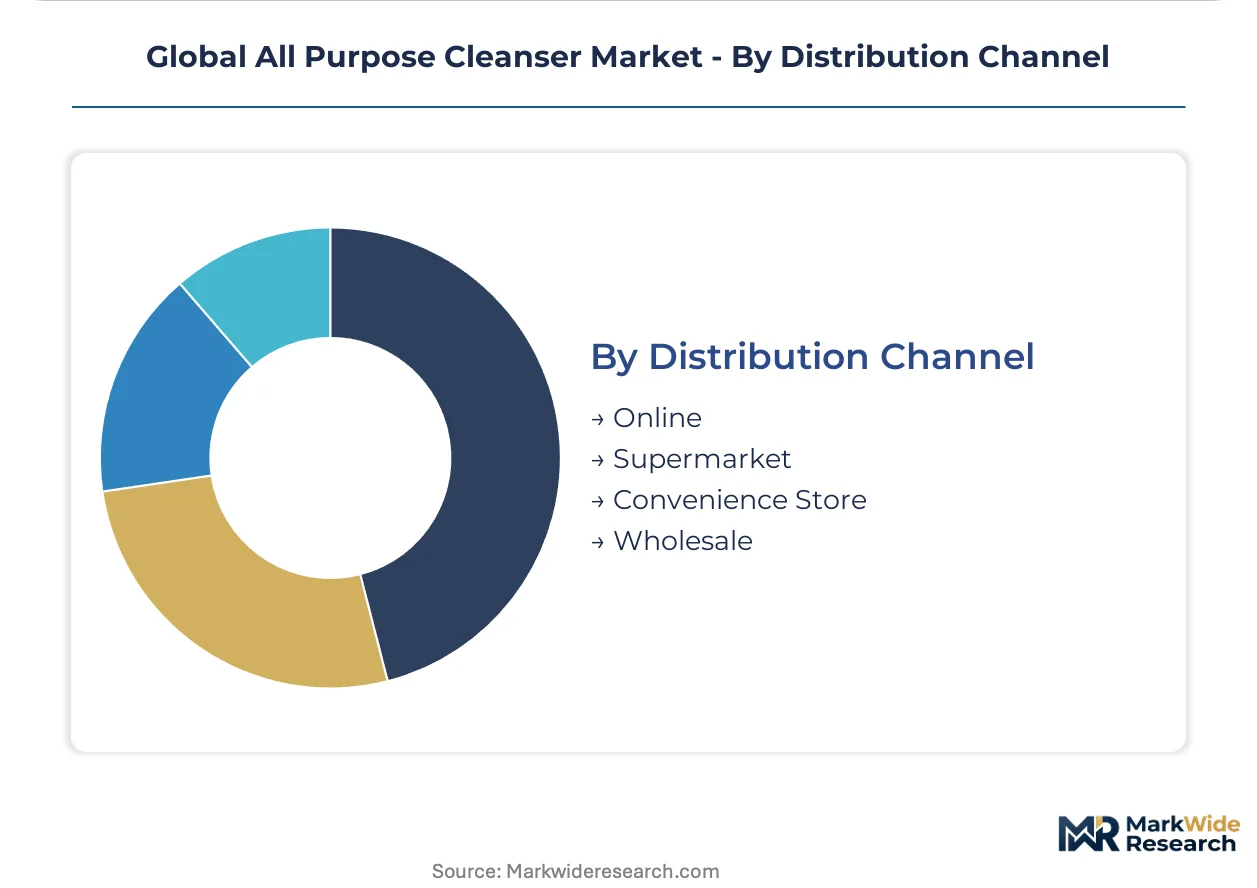
Distribution Channel:
Margin structure varies sharply by channel control, with wholesale and online capturing volume while supermarkets extract listing fees.
- Wholesale:Distributors bundle private-label concentrate programs with dispensing equipment leases to foodservice operators. This channel captures bulk procurement consolidation through group purchasing organizations.
- Online:Brand-owned subscription platforms and third-party marketplaces enable direct-to-consumer refill pouch delivery. The EPA Safer Choice certification provides digital shelf differentiation.
- Supermarket:Mass retail commands premium shelf placement fees and drives fragrance-variant proliferation before REACH allergen restrictions forced reformulation.
- Convenience Store:Impulse-oriented small-format retail for emergency and travel-size purchases.
Supermarket channels command the established base. The steepest expansion runs through online subscription platforms and wholesale bundled equipment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity as regulatory compliance and automation justify premium concentrate spending, while price-sensitive procurement in China and India favors bulk commodity formulations with minimal certification overhead.
United States
Foodservice operators and hospitality chains drive concentrate adoption through group purchasing organizations that mandate dilution verification systems. The EPA Safer Choice program shapes procurement specifications for federal and institutional contracts. Industrial clusters in the Midwest and Southeast anchor automated dispensing equipment installations that lock in bulk concentrate supply agreements.
Germany
Manufacturing facilities and commercial cleaning contractors prioritize closed-loop dispensing infrastructure to reduce per-cycle plastic intensity and storage footprint. REACH restrictions on alkylphenol ethoxylates and fragrance allergens accelerate reformulation investment in bio-based surfactants. The Rhine-Ruhr industrial corridor concentrates demand for enzyme-surfactant co-formulations that hybridize alkaline and acidic cleaning performance.
China
Provincial procurement tenders and foodservice chain expansion drive volume demand for surface cleaners meeting GB national standards. The Ministry of Ecology and Environment enforces dual carbon goals that constrain solvent-based formulation architectures. Manufacturing agglomeration in the Yangtze River Delta and Pearl River Delta supports private-label concentrate production for domestic and export markets.
India
Urban household penetration and quick-service restaurant chain growth expand addressable volume for spray and liquid formats. The Bureau of Indian Standards maintains voluntary specifications for surface cleaners that influence organized retail procurement. Metropolitan clusters in Maharashtra and Karnataka concentrate demand for convenience-oriented formats in modern trade channels.
Brazil
Foodservice sector formalization and hospitality investment sustain demand for professional-grade concentrates with dilution control features. ANVISA regulates antimicrobial claims and ingredient safety for surface cleaning products. São Paulo and Rio de Janeiro anchor distribution infrastructure serving institutional buyers with consolidated procurement patterns.
Global All Purpose Cleanser Market Vendor Landscape
Capability concentration sits with specialty formulators possessing green chemistry expertise and multi-jurisdictional regulatory navigation; scale advantage sits with diversified consumer goods conglomerates commanding retail shelf access and manufacturing throughput. The market structure splits between premium-tier players competing on certification portfolios and plant-derived positioning, and value-tier suppliers competing on cost-engineered formulations for price-sensitive channels. Two strategic archetypes dominate: subscription-enabled direct-to-consumer platforms capturing recurring revenue outside traditional retail, and equipment-integrated concentrate suppliers locking in institutional contracts through dispensing system leases. Competitive moves center on portfolio diversification into enzyme-hybrid formulations and geographic expansion through regional regulatory alignment.
Within the diversified multinational tier, Procter & Gamble and Unilever exemplify scale-driven positioning through concentrated format leadership and plastic-reduction architectures, while SC Johnson occupies a specialist position emphasizing plant-derived ingredient portfolios that command premium placement in European retail channels.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| SC Johnson |
| Reckitt Benckiser |
| The Clorox Company |
| Henkel |
| Colgate-Palmolive |
| Ecolab |
| Seventh Generation |
| Others |
Supply Flow & Price Mechanics
Palm oil and petrochemical feedstock concentration in Southeast Asia and the Middle East anchors cost structures for surfactant suppliers, concentrating margin capture with formulators who have locked in long-term offtake agreements or backward-integrated into bio-based alternatives. This upstream geography directly shapes where pricing power accumulates downstream.
Pricing Analysis
Aftermarket revenue from dispensing equipment leases and subscription refill deliveries drives lifetime value beyond initial concentrate sales. Three-tier pricing structure across premium certified, standard commercial, and economy private-label levels segments buyers by compliance burden and volume scale. Cost compression in commodity surfactant tiers is intensifying because foodservice group purchasing organizations now mandate dilution verification systems that squeeze undifferentiated suppliers. Quick-service restaurant chains exhibit the highest price sensitivity, while German manufacturing facilities and US healthcare systems show low elasticity for EPA Safer Choice-certified concentrates.
Supply Chain Analysis
Upstream palm-derived surfactants and petroleum-based solvents draw from agricultural plantations in Indonesia and Malaysia and refining complexes in Saudi Arabia and the United States. Specialty chelating agents and fragrance compounds rest on chemical manufacturing clusters in Germany and China. Single-source vulnerability runs through Indonesian palm kernel oil supply, where weather volatility and export policy shifts propagate downstream. Distribution runs through regional chemical distributors in the United States, bundled equipment-leasing programs in Germany, and direct-to-consumer subscription platforms that bypass traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from private-label concentrates bundled with dispensing equipment, as foodservice procurement organizations override brand loyalty with total-cost-of-ownership calculations.
For Market Incumbents: Entrench market position by acquiring or developing captive bio-based surfactant production to insulate margin from palm oil volatility, while embedding dilution verification software into dispensing equipment to lock out unbundled competitors. The threat of equipment-integrated private-label programs from US distributors demands preemptive channel control through exclusive lease agreements. For New Entrants and Emerging Players: Build out subscription refill platforms targeting environmentally conscious households in German urban centers, where REACH-driven fragrance allergen restrictions have stripped limonene and linalool from mass-market SKUs, creating white space for hypoallergenic positioning. Aviation maintenance wipes for MRO facilities offer a second penetrable niche where convenience premiums support newcomer margins. For Investors and Strategic Acquirers: Capital is best deployed toward specialty formulators possessing green chemistry expertise and multi-jurisdictional regulatory navigation capabilities, as these assets concentrate competitive advantage over the coming decade. Watch for inflection when EPA Safer Choice certification timelines compress or lengthen, signaling regulatory capacity constraints that will favor incumbents with established compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Surfactants | Captive supply of palm alternatives insulates margin from Indonesian export volatility. |
| Direct-to-Consumer Subscription Launch | Recurring revenue streams bypass supermarket slotting fees and REACH-driven retail fragmentation. |
| Dispensing Equipment Integration | Closed-loop systems lock in institutional contracts through dilution verification requirements. |
| EPA Safer Choice Certification Investment | Federal and institutional procurement specifications favor certified suppliers. |
| Aviation Wipe Format Expansion | MRO facility convenience premiums capture margin unavailable in commodity liquid tiers. |
Methodological Framework
Desk research of customs trade databases, chemical industry association reports, and regulatory filing repositories preceded structured interviews with formulation R&D directors, foodservice procurement managers, chemical distribution channel partners, and environmental services executives at US healthcare systems. Secondary validation drew from EPA Safer Choice certified product listings, ECHA substance evaluation timelines, and China GB standard documentation. Bottom-up volume estimates from concentrate production capacities and top-down demand segmentation were triangulated to constrain forecast variance.
Assumptions held fixed include REACH authorization timelines for fragrance allergens, EPA Safer Choice program continuity, and palm oil price volatility within historical bands; variables tested include foodservice automation adoption rates and aviation sector recovery trajectories. Segmentation dimensions spanned formulation physics, use intensity tiers, packaging format economics, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines across the projection horizon, with specific inputs from enzyme-surfactant co-formulation patent filings and automated dispensing equipment installation records.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese private-label specialists or sudden REACH scope expansions would shift outcomes. Cross-checking against customs export data for surfactant precursor chemicals is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Carpet Spot Remover Market