
 Cleaning Appliance Market | 2026-2036
Cleaning Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Appliance Market Analysis
The EU Ecodesign Regulation is realigning product development priorities across the cleaning appliance sector by mandating stricter energy efficiency thresholds and dust re-emission limits for vacuum cleaners sold in member states. Dyson leverages its cyclone technology heritage to sustain premium positioning against these efficiency benchmarks. SharkNinja competes aggressively on cordless runtime and price-accessible feature sets. Samsung Electronics anchors its portfolio through smart home ecosystem integration, connecting vacuum and mop functions to broader appliance platforms.
Cleaning appliances encompass electromechanical devices engineered to remove soil, debris, and contaminants from surfaces through suction, pressurized water, heated steam, or mechanical agitation, with motor power ratings typically spanning 200W to 2500W and filtration thresholds measured in micron capture efficiency. Their primary commercial purpose spans residential hygiene maintenance, commercial facility upkeep, and industrial contamination control across hard floors, soft furnishings, and vertical glass surfaces. Vacuum cleaners occupy the largest revenue pool given household penetration depth, while robotic systems represent the fastest-expanding technology segment as LiDAR navigation and autonomous docking mature. Cordless platforms are displacing traditional tethered designs in residential settings where maneuverability and storage constraints dominate purchase criteria.
The US EPA guides chemical discharge standards for pressure washer effluent, while the EU F-Gas Regulation constrains refrigerant-based steam generation systems, and China's GB standards govern motor efficiency and electromagnetic compatibility for domestically manufactured units. These frameworks collectively elevate compliance costs for new market entrants while rewarding incumbents with established testing and certification infrastructure. Stakeholders must monitor evolving interoperability protocols between robotic cleaners and proprietary smart home ecosystems, as platform lock-in risks fragmenting addressable demand across incompatible standards.
Market Dynamics
The EU Ecodesign Regulation is compressing product development cycles by mandating maximum annual energy consumption thresholds and dust re-emission caps for vacuum cleaners sold across member states, forcing manufacturers to redesign motor architectures and filtration systems ahead of enforcement deadlines.
Growth Catalysts
- Smart home integration:Residential buyers now expect robotic cleaners to interoperate with existing IoT platforms, creating pull for LiDAR-enabled navigation systems and autonomous docking stations.
- China's urban household formation:Tier-1 and Tier-2 cities are generating concentrated demand for cordless stick vacuums as apartment dwellers prioritize storage efficiency and maneuverability.
- EU F-Gas Regulation:Constraints on refrigerant-based steam generation systems are accelerating R&D investment in alternative heating technologies for commercial-grade cleaning equipment.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack costs for cordless platforms remain vulnerable to raw material sourcing bottlenecks concentrated in specific processing geographies.
- Technical limitation in autonomous navigation:Robotic systems still struggle with edge detection on dark surfaces and threshold climbing above 2cm, constraining addressable surface types.
- REACH compliance costs:European chemical registration requirements for polymer components in filtration systems elevate barrier-to-entry for new market participants.
Strategic Opportunities
- Underpenetrated commercial segments:Healthcare facilities and food processing plants in Germany present unmet demand for HEPA-certified autonomous cleaning systems with audit trail documentation.
- Technology convergence:Integration of computer vision with predictive maintenance algorithms enables shift from reactive to condition-based servicing models.
- Direct-to-installer channels:Bypassing traditional retail through contractor and facilities management procurement platforms captures specification influence earlier in the purchase cycle.
Industry Challenges
- Embedded software talent scarcity:Robotic navigation and machine learning competency shortages in motor control engineering constrain product roadmap velocity.
- Certification timeline compression:Simultaneous GB standards compliance for China and CE marking for Europe requires parallel testing tracks that extend time-to-market.
- Legacy fleet integration:Commercial buyers with existing tethered equipment face capex write-off decisions when evaluating cordless platform migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Appliance Market |
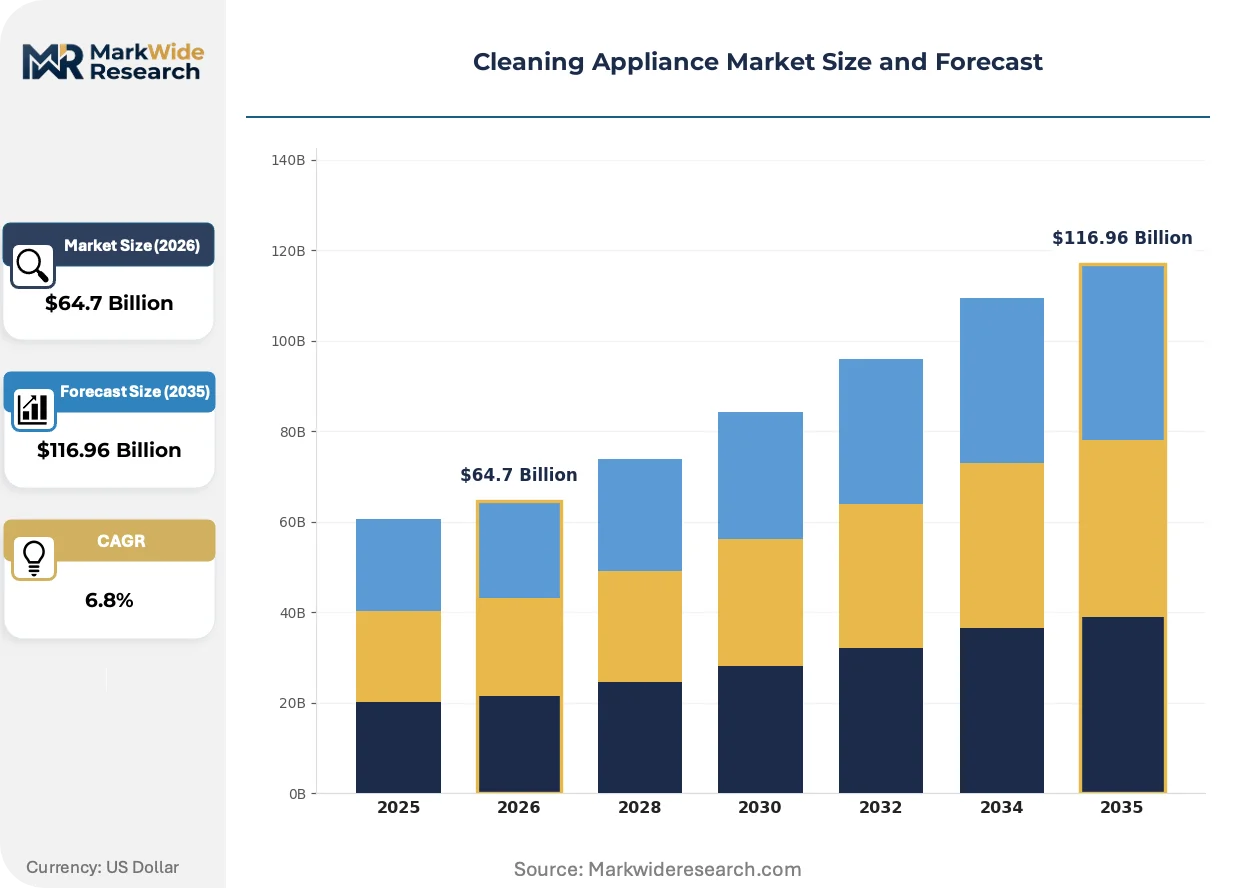
| Market Size in 2026 | $64.7 Billion |
| Market Size in 2035 | $116.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Cleaners, Pressure Washers, Steam Mops, Carpet Cleaners Technology: Robotic, Cordless, Smart, Traditional End User: Residential, Commercial, Industrial, Institutional Application: Floor Cleaning, Upholstery Care, Window Cleaning, Multi-surface |
| Companies Covered | Koninklijke Philips, Whirlpool, Samsung Electronics, LG Electronics, Electrolux, Dyson, SharkNinja, Panasonic, iRobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Appliance Market Emerging Trajectories
Product architecture is pivoting from standalone mechanical devices to software-defined cleaning systems where motor performance, navigation logic, and filtration efficiency are continuously optimizable through firmware updates and cloud-connected diagnostics.
Brushless DC motor technology is electrifying residential vacuum platforms by enabling sustained suction power above 100 air watts without thermal derating. Urban apartment dwellers in Shanghai and Shenzhen are adopting these systems at accelerating rates as rental stock modernizes. This electrification is compressing the performance gap between cordless and traditional canister designs, collapsing the premium pricing umbrella that tethered systems once commanded.
The EU Ecodesign Regulation's 2024 amendments impose mandatory repairability scoring and spare parts availability requirements for vacuum cleaners sold in member states. Manufacturers must now design motor housings and battery packs for user-replaceable access without specialized tooling. The robotic cleaner segment faces the steepest compliance burden, as sealed-unit construction common in LiDAR navigation bases conflicts with disassembly mandates, prompting redesign of docking station architectures.
Subscription-based filter and brush replacement programs are displacing traditional retail accessory sales as the dominant aftermarket revenue model. Direct-to-consumer channels and integrated smart home platforms are capturing this shift, bundling consumable replenishment with warranty extensions. This pattern is most visible in the United States, where Amazon's Dash Replenishment and proprietary manufacturer apps now handle a growing share of recurring revenue capture.
Cleaning Appliance Market Segmentation
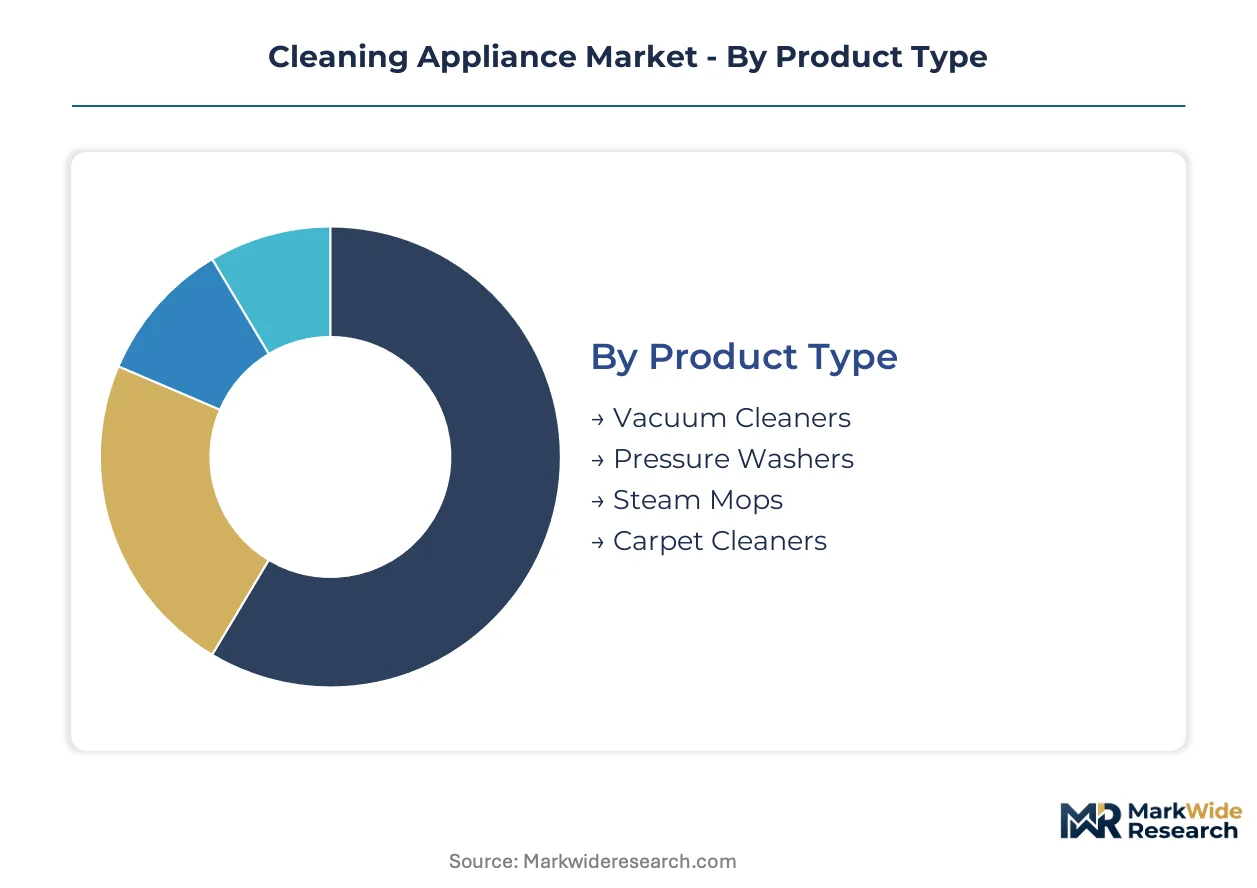
Cleaning appliance segmentation reveals divergent compliance burdens across product architectures. Certification requirements for autonomous navigation systems differ sharply from those governing high-pressure water systems or heated steam generation.
Product Type:
Vacuum cleaners face EU Ecodesign energy efficiency thresholds and dust re-emission caps. Pressure washers must satisfy US EPA effluent discharge standards. Steam mops navigate EU F-Gas constraints on refrigerant-based heating. Carpet cleaners encounter REACH chemical registration for extraction solutions.
- Vacuum Cleaners:Electromechanical suction systems spanning canister, upright, stick, and handheld architectures with motor ratings from 200W to 2500W. Demand concentrates in Chinese urban households where apartment dwellers prioritize storage efficiency and maneuverability over raw power specifications. Cordless stick variants are displacing tethered canister designs in Tier-1 cities.
- Pressure Washers:High-pressure water systems generating 1000-4000 PSI for surface cleaning and coating removal. Commercial facilities in Germany specify these for fleet maintenance and building facade upkeep, though US EPA effluent regulations constrain chemical detergent formulations and wastewater discharge protocols.
- Steam Mops:Heated vapor systems producing 120°C+ saturated steam for sanitization without chemical residues. EU F-Gas Regulation limits refrigerant-based steam generation, accelerating alternative heating technology R&D.
- Carpet Cleaners:Extraction systems combining heated solution application with vacuum recovery for deep fiber cleaning. REACH compliance elevates barrier-to-entry for polymer tank and hose components in European markets.
Leading the category by volume: Vacuum Cleaners. Growing fastest: Robotic vacuum variants within this segment.
Technology:
Technology tiers stratify by embedded software complexity and power architecture. Robotic systems demand LiDAR navigation certification and smart home interoperability testing. Cordless platforms require lithium-ion cell safety validation. Smart and traditional categories diverge on connectivity protocol compliance.
- Robotic:Autonomous navigation platforms integrating LiDAR mapping, computer vision, and autonomous docking. Healthcare facilities in Germany specify these for HEPA-certified operation with audit trail documentation, though technical limitations persist in edge detection on dark surfaces and threshold climbing above 2cm.
- Cordless:Battery-powered platforms utilizing brushless DC motors to sustain 100+ air watts without thermal derating. China's GB standards govern motor efficiency and electromagnetic compatibility for domestically manufactured units.
- Smart:IoT-connected systems enabling firmware updates, cloud diagnostics, and smart home ecosystem integration. Interoperability protocol fragmentation risks locking demand into proprietary platforms.
- Traditional:Tethered electromechanical designs without embedded software or connectivity. Commercial buyers with existing fleets face capex write-off decisions when evaluating platform migration.
Volume concentration: Cordless. Steepest expansion trajectory: Robotic systems as LiDAR navigation and autonomous docking mature.
End User:
End user categories separate by procurement authority and performance specification intensity. Residential buyers prioritize maneuverability and smart home compatibility. Commercial and institutional segments demand HEPA certification and repairability scoring. Industrial applications emphasize durability and effluent compliance.
- Residential:Individual household purchasers selecting cleaning appliances for hygiene maintenance across hard floors and soft furnishings. Urban apartment formation in Shanghai and Shenzhen drives cordless stick vacuum demand as rental stock modernizes.
- Commercial:Facilities management and contract cleaning operations serving offices, retail, and hospitality. Direct-to-installer procurement platforms capture specification influence earlier in the purchase cycle for this segment.
- Industrial:Manufacturing and logistics operations requiring contamination control and surface preparation. US EPA chemical discharge standards constrain pressure washer effluent management.
- Institutional:Healthcare, education, and government facilities with mandated sanitization protocols. EU Ecodesign repairability scoring and spare parts availability requirements affect procurement decisions.
Dominant demand source: Residential. Fastest-growing specification: Institutional HEPA-certified autonomous systems.
Application:
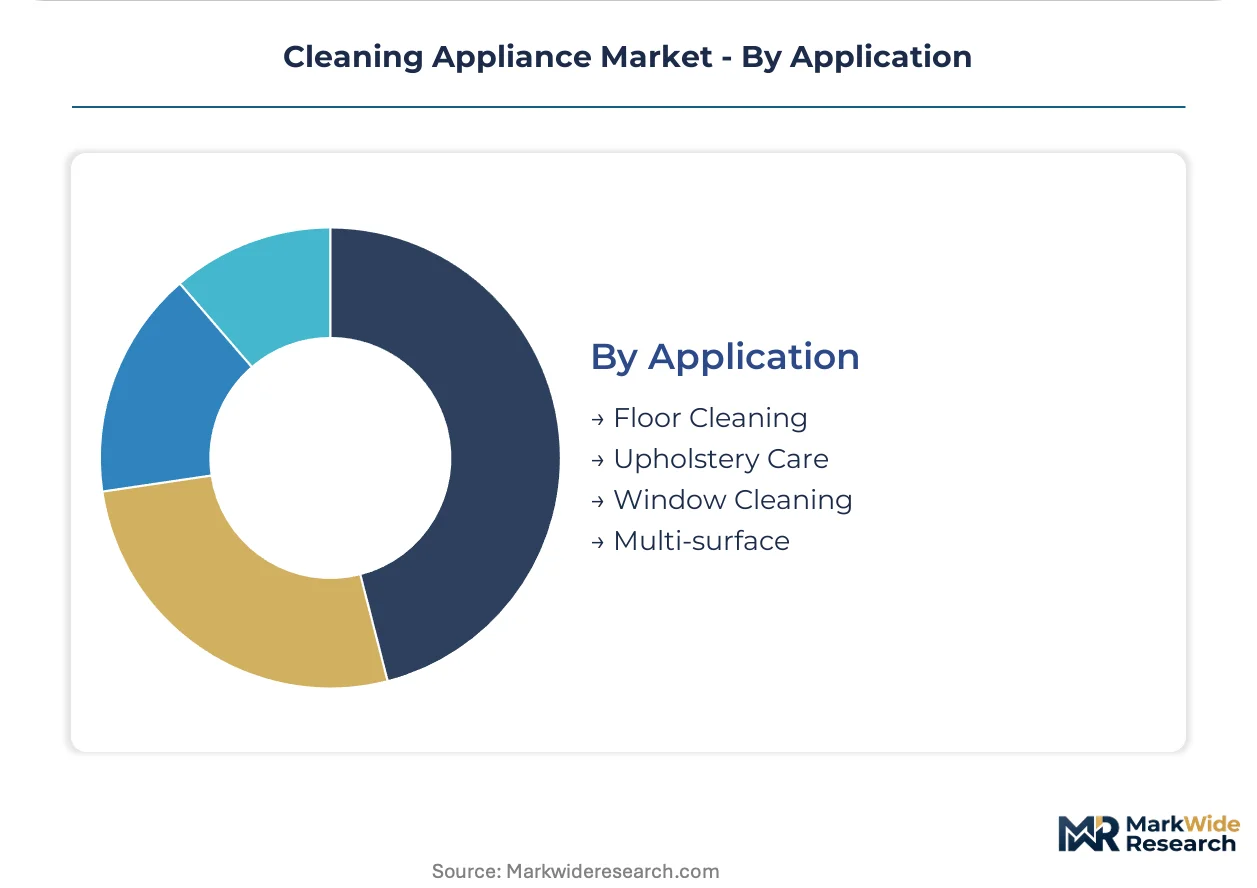
Application segmentation aligns with surface material diversity and contamination type. Floor cleaning commands the deepest household penetration. Upholstery care and window cleaning demand specialized attachments and chemical compatibility. Multi-surface flexibility drives cordless platform preference.
- Floor Cleaning:Hard surface and carpet maintenance across residential and commercial environments. Brushless DC motor electrification compresses the performance gap between cordless and traditional canister designs.
- Upholstery Care:Fabric and leather surface cleaning requiring specialized suction control and chemical extraction. Carpet cleaners and handheld vacuums serve this application with dedicated attachment sets.
- Window Cleaning:Vertical glass surface maintenance using suction-based robotic systems or manual squeegee platforms. Robotic window cleaners face distinct certification requirements for fall protection and edge detection.
- Multi-surface:Flexible platforms transitioning between hard floors, carpets, and above-floor cleaning without tool changes. Cordless stick vacuums with detachable handheld units dominate this application in space-constrained urban dwellings.
Volume leader: Floor Cleaning. Quickest share gain: Multi-surface as apartment dwellers prioritize storage efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors cordless vacuum demand as apartment modernization accelerates across China's eastern seaboard. Shenzhen's electronics corridor supplies brushless DC motor components to domestic manufacturers. These coastal manufacturing clusters concentrate both production capacity and consumption density for next-generation cleaning platforms.
United States
Residential smart home integration drives specification intensity for robotic systems with autonomous docking capabilities. The EPA guides chemical discharge standards for pressure washer effluent in commercial applications. Austin's technology corridor hosts firmware development operations for LiDAR-enabled navigation platforms serving North American distribution channels.
Germany
Healthcare facilities specify HEPA-certified autonomous cleaning systems with audit trail documentation for contamination control. The EU Ecodesign Regulation mandates repairability scoring and spare parts availability for vacuum cleaners sold across member states. Stuttgart's industrial belt concentrates engineering talent for motor architecture redesigns targeting efficiency thresholds.
China
Urban household formation in Tier-1 and Tier-2 cities expands the addressable base for cordless stick vacuums prioritizing storage efficiency. GB standards govern motor efficiency and electromagnetic compatibility for domestically manufactured units. The Yangtze River Delta manufacturing corridor produces lithium-ion battery packs for cordless platforms serving both domestic and export markets.
Japan
Residential buyers prioritize compact form factors for space-constrained urban dwellings in Tokyo and Osaka metropolitan areas. METI oversees energy efficiency labeling requirements for household appliances including vacuum cleaners. Nagoya's precision manufacturing cluster supplies brushless motor components to domestic appliance assemblers.
India
Rising disposable incomes in metropolitan centers drive adoption of automated cleaning systems among urban middle-class households. BIS certification requirements govern electrical safety and electromagnetic compatibility for imported and domestically produced units. The Delhi-NCR corridor concentrates distribution infrastructure for premium appliance brands targeting northern Indian markets.
Cleaning Appliance Market Vendor Landscape
The competitive structure tilts toward diversified electronics conglomerates with established smart home ecosystems. Market concentration remains moderate with clear tiering between premium technology specialists and mass-market volume players. Three strategic archetypes dominate: cyclone-technology heritage brands, ecosystem-integrated electronics manufacturers, and cordless-specialist challengers. Capacity expansion in brushless motor production and strategic partnerships for LiDAR navigation sourcing represent the dominant competitive moves.
Within the premium technology tier, Dyson and iRobot exemplify archetype specialization through sustained R&D intensity in suction engineering and autonomous navigation respectively. Samsung Electronics and LG Electronics anchor the ecosystem-integrated conglomerate segment, leveraging existing smart home platform infrastructure to bundle cleaning appliances with broader appliance portfolios. SharkNinja occupies a position between these tiers, competing on price-accessible feature sets while building cordless runtime capabilities. Koninklijke Philips and Electrolux represent European heritage manufacturers with established distribution footprints across multiple regional markets. Whirlpool and Panasonic complete the competitive set as diversified appliance manufacturers with geographic diversification strategies.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Whirlpool |
| Samsung Electronics |
| LG Electronics |
| Electrolux |
| Dyson |
| SharkNinja |
| Panasonic |
| iRobot |
| Others |
Supply Flow & Price Mechanics
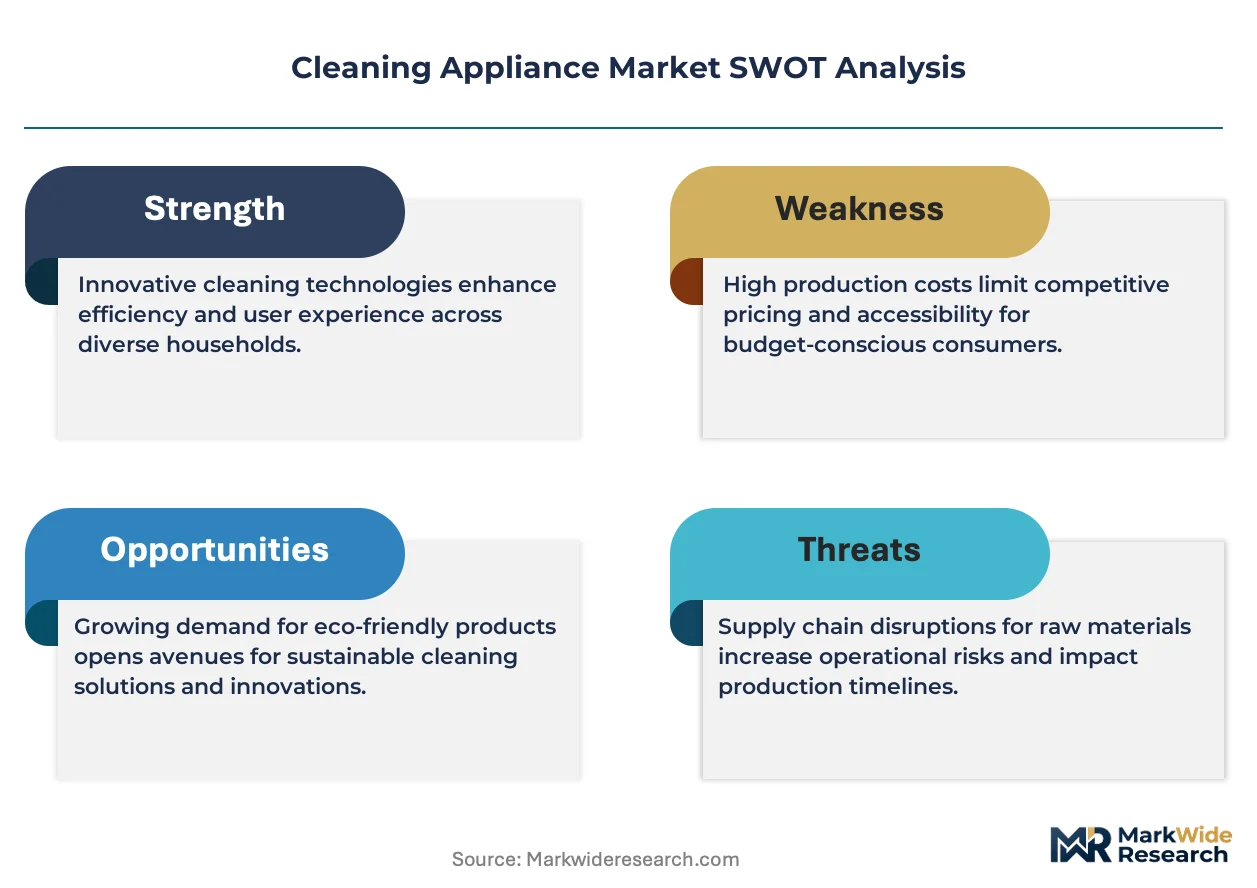
Lithium carbonate price volatility cascades through cordless vacuum supply chains, compressing margins for battery pack manufacturers while forcing tiered pricing adjustments across premium and mass-market product lines. The Yangtze River Delta's concentration of cell production amplifies this transmission mechanism into final consumer pricing.
Pricing Analysis
Runtime-per-charge metrics anchor value-based pricing for cordless stick vacuums, with manufacturers tiering offers across 40-minute, 60-minute, and 90-minute endurance thresholds. Price differentiation hinges on brushless motor wattage ratings and HEPA certification grade, with EU Ecodesign repairability scoring emerging as a new tier separator. Pricing pressure stems from Chinese domestic brands compressing entry-level cordless segments. Residential buyers in Tier-2 Chinese cities exhibit highest price sensitivity, while German healthcare procurement shows lowest.
Supply Chain Analysis
Ocean freight rate fluctuations from Shanghai to Rotterdam directly impact landed costs for finished robotic cleaners, with container availability constraints amplifying working capital requirements for inventory positioning. Manufacturing concentrates in China, Vietnam, and Mexico for final assembly, with brushless DC motors and LiDAR navigation modules drawing from South Korean and Japanese component specialists. Single-source vulnerability persists for high-nickel cathode materials. Distribution runs through Amazon's fulfillment network and big-box retail partnerships in North America, direct-to-consumer apps in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cleaning appliance sector occupies a technology-transition phase where brushless DC motor electrification systematically displaces legacy brushed-motor architectures, collapsing performance premiums that tethered canister designs once commanded.
For Market Incumbents: Extend firmware update capabilities into legacy cordless platforms to slow replacement cycles and defend installed base against robotic migration. Capture backward integration into brushless motor production in China's Yangtze Delta to secure supply continuity. The EU Ecodesign repairability mandate threatens sealed-unit robotic designs; accelerate docking station redesign ahead of enforcement.
For New Entrants and Emerging Players: Direct-to-installer procurement platforms targeting German healthcare facilities offer white-space access with specification influence upstream of traditional retail. Target HEPA-certified autonomous systems for food processing plants, where audit trail documentation requirements deter incumbent commoditization. Launch through facilities management software partnerships rather than consumer advertising.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier cordless specialists with established GB standards compliance and underutilized Vietnamese assembly capacity. Long-term viability centers on software-defined servicing revenue streams rather than hardware shipment volumes. Watch for inflection when robotic navigation patents expire and LiDAR module costs drop below threshold for mass-market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive supply of brushless DC components insulates margin from lithium-cell price swings in China's Yangtze Delta. |
| Direct-to-Installer Channel Development | Facilities management procurement platforms capture specification authority before retail commoditization in German healthcare. |
| Smart Home Ecosystem Integration | Platform lock-in through Alexa, Google Home, and proprietary apps raises switching costs for residential robotic buyers. |
| Subscription Filter Replacement Programs | Recurring revenue capture through Amazon Dash Replenishment and manufacturer apps displaces traditional retail accessory sales. |
| EU Ecodesign Repairability Compliance | User-replaceable battery and motor housing designs satisfy mandatory scoring while differentiating against sealed-unit competitors. |
Methodological Framework
Independent corroboration across appliance engineering directors, smart home platform managers, and lithium-ion procurement specialists underwrites the qualitative findings in this study. Primary fieldwork encompassed interviews with motor control firmware developers, EU regulatory affairs leads, and Chinese OEM export managers. Secondary validation drew from customs trade databases, EPA effluent discharge filings, and GB standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring.
Comparable-period analysis anchored the projection framework to historical adoption curves for cordless platform displacement of tethered designs. The model segmented across product architecture, power technology, end-user procurement authority, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to smart home penetration rates and urban household formation patterns. Forecast inputs incorporated EU Ecodesign amendment timelines and brushless motor cost experience curves.
The model holds under stable lithium carbonate supply and continued smart home platform consolidation; deviation in raw material export restrictions or interoperability protocol fragmentation would shift trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Liquid Laundry Detergent Market