
 Carpet Steamers Market | 2026-2036
Carpet Steamers Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Steamers Market Analytics
Skilled technician availability for commercial steamer maintenance and repair is collapsing across service networks, forcing manufacturers to redesign field-service architectures. Bissell sustains broad retail penetration through mass-market channel control and consumer brand recognition. Tennant dominates industrial cleaning equipment with specialized commercial steam systems engineered for healthcare and hospitality environments. Alfred Karcher leverages European engineering heritage to anchor premium positioning in professional-grade canister and upright configurations.
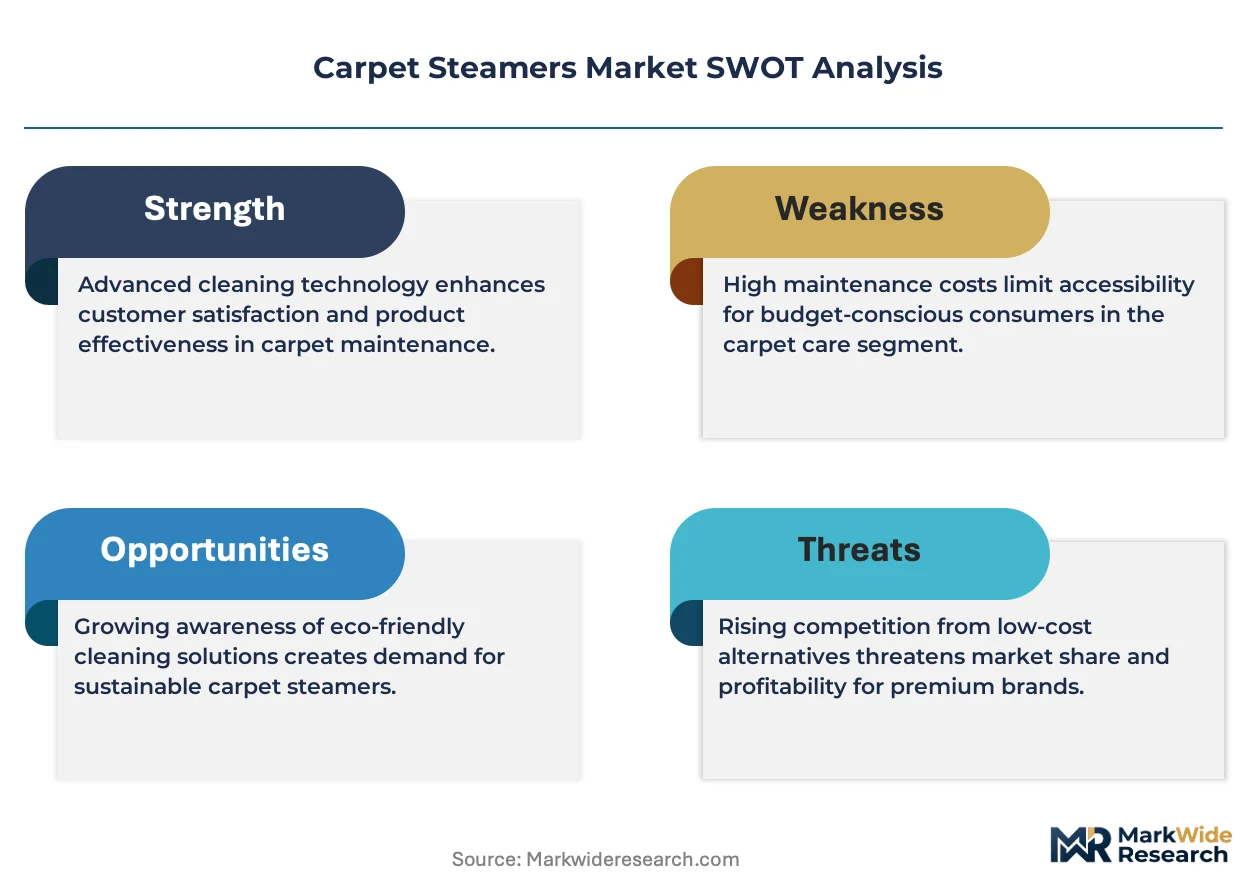
Carpet steamers are pressurized cleaning appliances that heat water to temperatures exceeding 200°F, generating saturated steam for deep extraction of soils, allergens, and pathogens from textile floor coverings without chemical detergents. The equipment serves commercial facilities requiring sanitization compliance and residential consumers seeking allergen reduction. Upright configurations occupy the largest volume share due to ergonomic familiarity and retail accessibility, while portable units represent the fastest-expanding category as apartment dwellers and automotive detailing operators prioritize storage efficiency and mobility. Multi-surface technology integration is reshaping margin pools, with manufacturers bundling hard-floor attachments to justify price premiums and extend replacement cycles.
EPA Energy Star certification and OSHA workplace sanitation standards constrain product entry in the United States, while EU REACH and CE marking requirements govern chemical compatibility and electrical safety for European imports. These frameworks elevate compliance costs for smaller manufacturers but create defensive moats for established players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving state-level indoor air quality mandates and water-use restrictions that will determine which heating element efficiencies and capacity tiers retain market access.
Market Dynamics
Commercial hospitality operators are accelerating replacement cycles for carpet steamers as EPA and OSHA indoor air quality mandates harden certification requirements, forcing manufacturers to absorb compliance costs while redesigning field-service networks to address collapsing technician availability.
Growth Catalysts
- OSHA Workplace Sanitation Standards:Tightened exposure limits for chemical cleaning agents in US facilities are redirecting procurement budgets toward steam-based sanitization systems that eliminate detergent residues.
- Healthcare Facility Expansion:Hospital and long-term care construction in Texas, Florida, and Arizona is generating concentrated demand for infection-control-compliant steam extraction equipment.
- Multi-Surface Attachment Bundling:Manufacturers are integrating hard-floor cleaning heads into carpet steamer SKUs, extending replacement cycles while capturing margin premiums from residential upgraders.
Market Restraints
- Copper and Aluminum Price Volatility:Heating element raw materials face sustained cost pressure from electrification demand in other sectors, compressing gross margins on mid-tier units.
- Technician Labor Collapse:Commercial service networks report 40% vacancy rates for certified repair specialists, forcing manufacturers to subsidize training or redesign for modular component swap-out.
- Low-Cost Asian Import Substitution:Uncertified portable units from unbranded Shenzhen and Guangzhou exporters capture price-sensitive residential volume through direct-to-consumer channels.
Strategic Opportunities
- Apartment Dweller Segment:Storage-constrained urban renters in Chicago, Seattle, and Denver represent underpenetrated demand for collapsible-handle portable steamers with 48-hour delivery windows.
- Automotive Detailing Convergence:Mobile detailers are repurposing carpet steamers for interior sanitization, creating cross-category demand that existing distribution networks have not organized to serve.
- EU REACH Chemical Phase-Out:The European Chemicals Agency's restriction roadmap for perchloroethylene and other textile solvents positions saturated steam as the compliant default for professional cleaning contracts.
Industry Challenges
- EPA Energy Star Certification Timelines:Testing backlogs at third-party laboratories now extend 14-18 months, delaying product launches and freezing R&D amortization schedules.
- Legacy Fleet Integration Complexity:Facility management contractors operating mixed-vendor steamer pools face interoperability failures between proprietary attachment systems and universal hose couplings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Steamers Market |
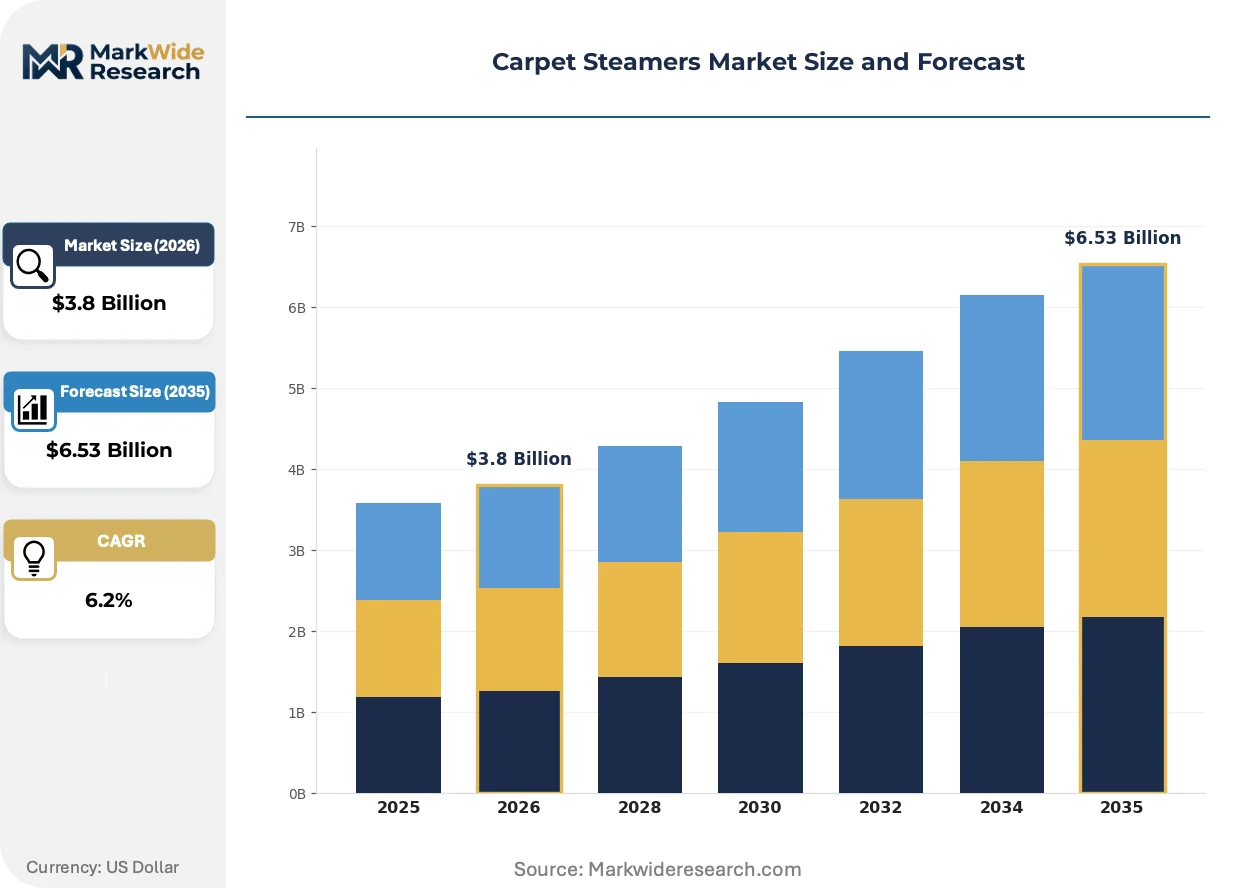
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Portable, Canister, Commercial Technology: Heating Element, Pressure, Water Filtration, Multi-Surface End User: Residential, Hospitality, Healthcare, Automotive Detailing Capacity: 1 Gallon, 2 Gallons, 3 Gallons, 4 Gallons |
| Companies Covered | Alfred Karcher, Bissell, Nilfisk, Tennant, Techtronic Industries, Rug Doctor, Hoover, SharkNinja, Dyson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Steamers Market Evolving Landscape
Heating element architecture and control electronics are converging to enable precise temperature modulation, while distribution channels fragment between specialized cleaning-equipment distributors and generalist e-commerce platforms.
Boilerless instant-heat technology is decomposing the traditional tank-and-heat-exchange architecture that has dominated carpet steamer design for three decades. Hospitality procurement teams in Las Vegas and Orlando are specifying these systems for 24/7 casino and resort operations where downtime tolerance approaches zero. The shift is decomposing aftermarket parts revenue streams as sealed-unit designs eliminate user-serviceable components.
EPA's proposed updates to volatile organic compound limits under the Clean Air Act are tightening permissible emissions from cleaning equipment sold into federal facilities. Manufacturers must now submit third-party testing documentation for every SKU variant, adding $15,000-$25,000 per product line in compliance overhead. Commercial-grade unit producers with dedicated regulatory affairs staff are absorbing these costs more readily than residential-focused competitors.
Facility management contractors are consolidating vendor relationships from multi-brand portfolios to single-source agreements with performance guarantees. Jones Lang LaSalle and Cushman & Wakefield procurement teams now specify outcome-based contracts where payment ties to measurable sanitation outcomes rather than equipment delivery. This restructuring concentrates volume with manufacturers offering IoT-enabled fleet monitoring and predictive maintenance dashboards, visible most acutely in California and New York metro contract renewals.
Carpet Steamers Market Segmentation
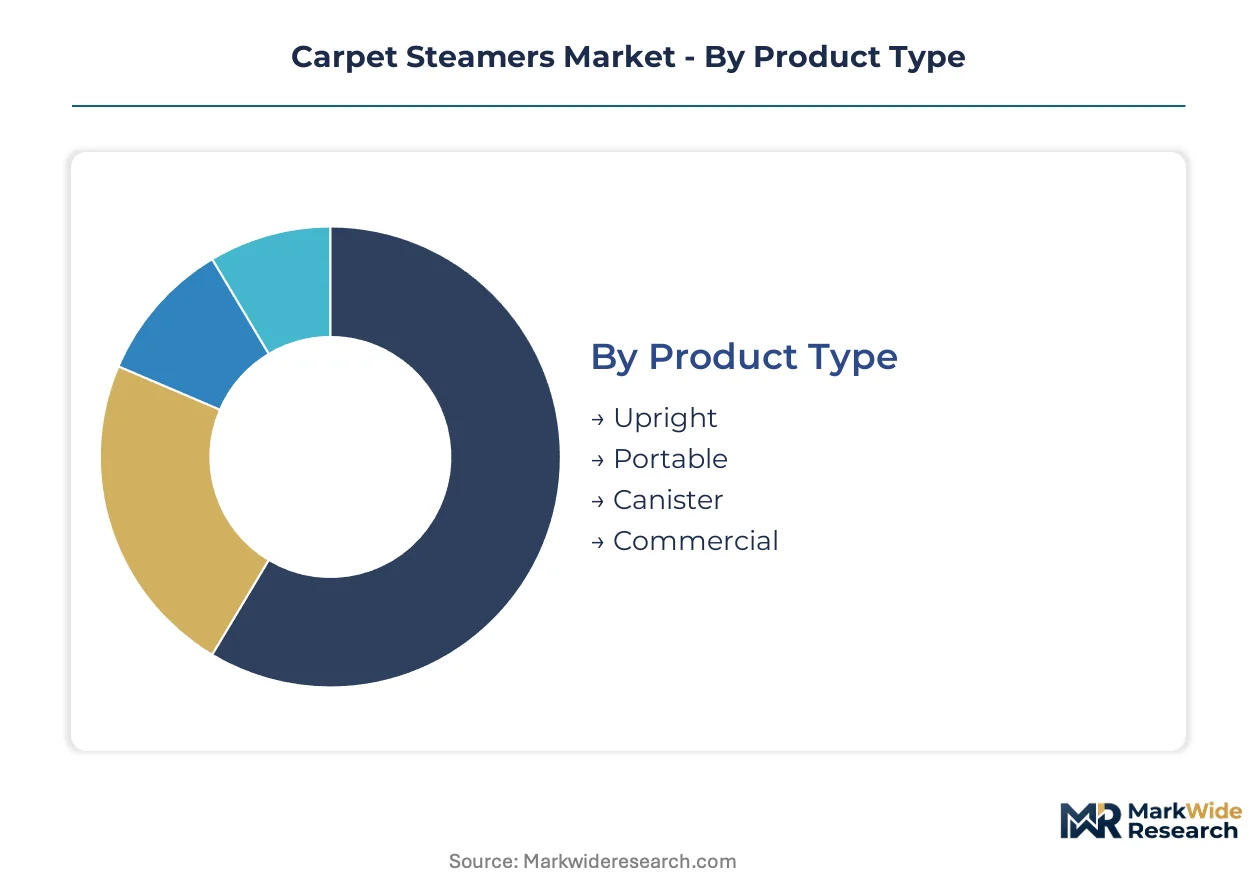
Segmentation in carpet steamers reflects divergent engineering priorities between residential convenience and commercial durability. Procurement patterns split sharply between price-sensitive retail channels and specification-driven facility management contracts.
Product Type:
Domestic demand concentrates in upright and portable configurations, while export-led growth flows through commercial and canister systems bound for European and Middle Eastern hospitality markets.
- Upright:Self-contained units with integrated solution tanks and extraction motors dominate mass-market retail. Demand clusters in suburban residential replacement cycles across the United States, where ergonomic familiarity and retail accessibility sustain volume despite longer replacement intervals.
- Portable:Compact units with collapsible handles and detachable hoses prioritize storage efficiency. Apartment dwellers in Chicago, Seattle, and Denver drive the steepest expansion trajectory as urban density constraints reshape equipment specifications.
- Canister:Separate boiler and wand configurations enable extended runtime for professional operators. European engineering standards govern specifications for German and Italian export markets.
- Commercial:Industrial-grade systems with stainless steel boilers and continuous-fill capability serve 24/7 casino and resort operations. Las Vegas and Orlando procurement teams specify boilerless instant-heat architectures for zero-downtime environments.
Upright configurations command the established base. The steepest expansion runs through Portable.
Technology:
Cost tier differentiation separates premium electronic modulation from standard mechanical systems, with regulatory compliance costs widening the gap between certified and uncertified approaches.
- Heating Element:Copper and aluminum coil architectures face raw material cost pressure from electrification demand in other sectors. EPA Energy Star certification timelines now extend 14-18 months, freezing R&D amortization for residential-focused competitors.
- Pressure:Sealed boiler systems generating 50-75 psi extraction force define professional-grade performance. OSHA workplace sanitation standards redirecting procurement budgets toward steam-based sanitization systems.
- Water Filtration:Hard-water scaling prevention extends element lifespan in mineral-rich supply regions. Southwestern US facility operators specify integrated descaling systems.
- Multi-Surface:Attachment bundling with hard-floor cleaning heads captures margin premiums from residential upgraders. Manufacturers extending replacement cycles through cross-category utility.
Heating Element technology commands the established base. Multi-Surface integration climbs the fastest as manufacturers bundle attachments to justify price premiums.
End User:
Application concentration varies by sanitation compliance intensity, with healthcare and hospitality procurement governed by outcome-based contracts rather than equipment delivery metrics.
- Residential:Individual consumers prioritizing allergen reduction and chemical-free cleaning. Replacement cycles tied to housing turnover and upgrade spending patterns.
- Hospitality:Casino and resort operators in Las Vegas and Orlando specifying 24/7 operational capability. Procurement shifting from multi-brand portfolios to single-source agreements with performance guarantees.
- Healthcare:Hospital and long-term care construction in Texas, Florida, and Arizona generating concentrated demand for infection-control-compliant steam extraction equipment. Jones Lang LaSalle and Cushman & Wakefield procurement teams now tie payment to measurable sanitation outcomes.
- Automotive Detailing:Mobile operators repurposing carpet steamers for interior sanitization. Cross-category demand that existing distribution networks have not organized to serve.
Residential end users command the established base. Healthcare procurement gains share fastest as facility construction concentrates in Sun Belt states.
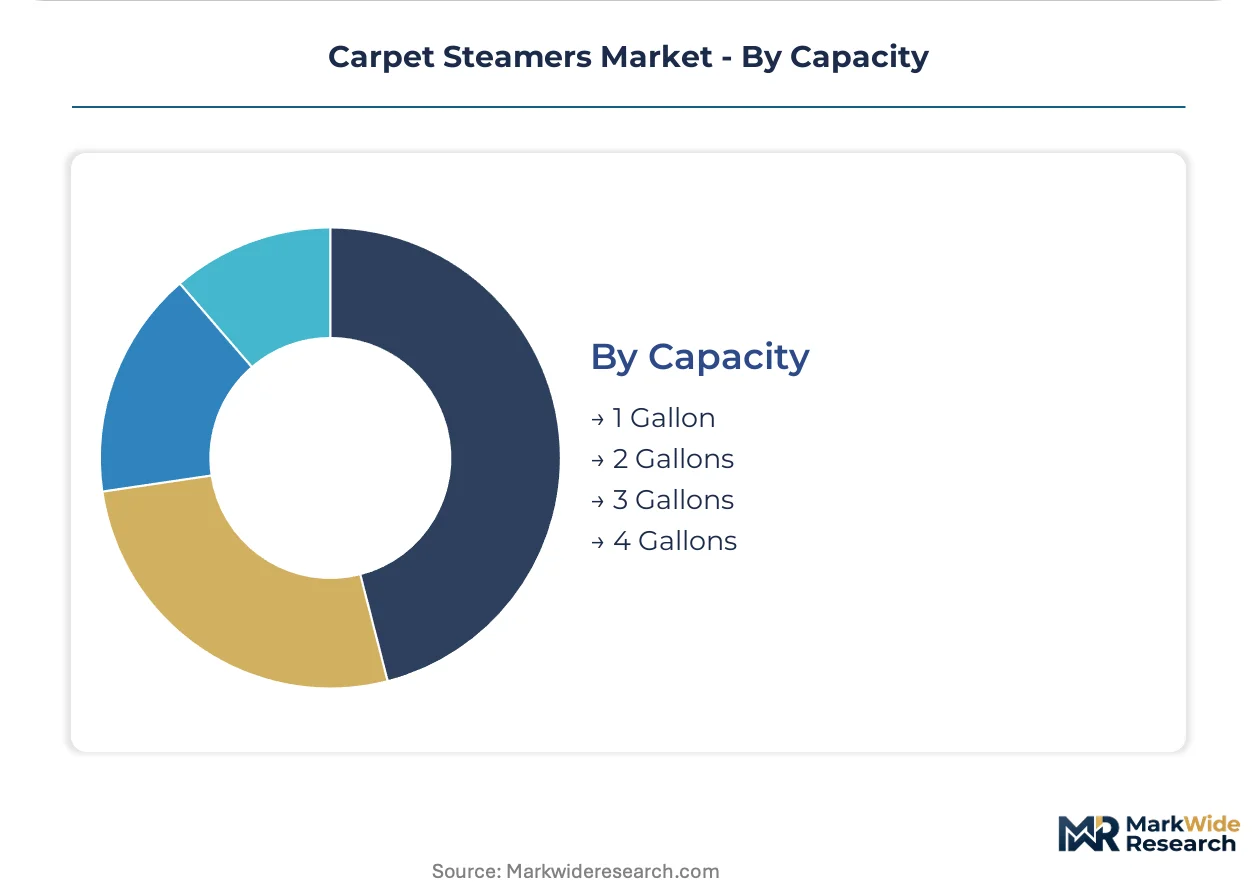
Capacity:
Volume tier alignment matches tank size to duty cycle requirements, with commercial specifications diverging from residential convenience thresholds.
- 1 Gallon:Compact tanks suited to apartment-scale cleaning tasks and spot treatment. Urban renters in storage-constrained environments.
- 2 Gallons:Mid-size configurations balancing runtime and maneuverability for single-family residential use. Standard specification for mass-market retail channels.
- 3 Gallons:Extended runtime for small commercial operators and dedicated residential users with larger floor plans. Automotive detailers favor this tier for mobile operations.
- 4 Gallons:Maximum capacity for continuous-fill commercial systems with direct water line connection. Federal facility procurement under EPA volatile organic compound limits specifies this tier for uninterrupted sanitization compliance.
2 Gallon capacity commands the established base. 4 Gallon systems expand most quickly as federal facility mandates harden certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Star certification and OSHA workplace sanitation standards anchor demand concentration in the United States, where facility management contracts and residential replacement cycles sustain procurement volumes. European REACH chemical phase-outs and Middle Eastern hospitality expansion create secondary demand poles with divergent regulatory architectures.
United States
Hospital construction in Texas, Florida, and Arizona generates concentrated procurement for infection-control-compliant steam extraction equipment. EPA testing backlogs now extend 14-18 months, delaying product launches for residential-focused competitors. Las Vegas and Orlando casino operators specify boilerless instant-heat systems for 24/7 operational environments.
Germany
EU REACH restrictions on perchloroethylene and textile solvents position saturated steam as the compliant default for professional cleaning contracts. Alfred Karcher leverages engineering heritage to anchor premium positioning in canister and upright configurations exported across Europe. Baden-Württemberg manufacturing clusters supply heating element components facing copper and aluminum price volatility from electrification demand.
China
Uncertified portable units from Shenzhen and Guangzhou exporters capture price-sensitive residential volume through direct-to-consumer channels. MIIT standards for electrical safety and GB marking requirements govern domestic product entry, though enforcement gaps persist in cross-border e-commerce. Yangtze River Delta assembly operations supply heating element components to mid-tier global manufacturers.
United Arab Emirates
Dubai and Abu Dhabi hospitality procurement teams specify commercial-grade units for sanitization compliance in luxury hotel and resort operations. MOHAP indoor air quality guidelines constrain product entry for federal facility contracts. Jebel Ali logistics corridors distribute European and Asian equipment across Gulf Cooperation Council markets.
United Kingdom
London facility management contractors consolidate vendor relationships from multi-brand portfolios to single-source agreements with performance guarantees. ECHA chemical restriction roadmaps align with domestic procurement shifts toward detergent-free steam systems. Midlands distribution networks serve healthcare construction in Manchester and Birmingham metropolitan areas.
Carpet Steamers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium engineering and mass-market scale occupy separate competitive spaces. Established manufacturers with dedicated regulatory affairs capacity absorb EPA and EU compliance costs more readily than residential-focused competitors. Two strategic archetypes dominate: heritage engineering specialists with European manufacturing roots and mass-market consumer brands controlling retail channel access. Competitive moves concentrate on multi-surface attachment bundling to extend replacement cycles and IoT-enabled fleet monitoring for outcome-based facility management contracts.
Within the heritage engineering tier, Alfred Karcher and Tennant exemplify positioning anchored in professional-grade specifications and healthcare-hospitality vertical focus. Bissell occupies the mass-market vector, leveraging retail channel control and consumer brand recognition to sustain broad penetration. These three companies represent the archetype spectrum: German engineering heritage, industrial cleaning specialization, and mass-market consumer appliance scale.
| Leading Market Players |
|---|
| Alfred Karcher |
| Bissell |
| Nilfisk |
| Tennant |
| Techtronic Industries |
| Rug Doctor |
| Hoover |
| SharkNinja |
| Dyson |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month EPA Energy Star certification timelines compress inventory turns for residential-focused manufacturers while amplifying pricing power for incumbents with dedicated regulatory affairs capacity. This lead-time asymmetry stratifies the market into certified premium tiers and uncertified economy alternatives.
Pricing Analysis
US-Germany price spreads for equivalent canister configurations exceed three-to-one, reflecting certification overhead divergence. Pricing stratifies across EPA/OSHA-compliant commercial tiers, mid-market Energy Star residential units, and direct-to-consumer imports lacking third-party validation. Cost compression in mid-tier upright segments stems from copper and aluminum heating element volatility. Apartment dwellers in dense urban markets exhibit highest price sensitivity, while federal facility procurement teams prioritize compliance guarantees over unit economics.
Supply Chain Analysis
Port congestion on Yangtze River Delta-to-Long Beach lanes elevates inbound logistics costs for heating element components sourced from Chinese assembly operations. Manufacturing gravity centers on Baden-Württemberg engineering clusters, Yangtze River Delta component operations, and domestic final assembly in Nevada and Ohio. Boilers, pressure vessels, and electronic control modules constitute critical dependencies. Single-source vulnerability concentrates in EPA-certified third-party testing laboratories. Distribution runs through specialized cleaning-equipment distributors and generalist e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability failures between proprietary attachment systems and universal hose couplings signal platform-economics inflection, where IoT-enabled fleet monitoring ecosystems will determine contract renewal outcomes.
For Market Incumbents: Compound defensive positioning through backward integration into heating element component supply and exclusive certification laboratory partnerships. Low-cost Shenzhen exporters threaten residential volume through direct-to-consumer channels. Modular component swap-out architectures address technician labor collapse while preserving aftermarket revenue streams. For New Entrants and Emerging Players: Differentiate on collapsible-handle portability for storage-constrained urban renters in Chicago, Seattle, and Denver. Automotive detailing operators represent underpenetrated cross-category demand with minimal incumbent distribution coverage. Direct-to-consumer fulfillment with 48-hour delivery windows bypasses established retail channel gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EPA and OSHA certification timelines create sustainable barriers against import substitution. Target manufacturers with dedicated regulatory affairs staff and existing Energy Star portfolio breadth. Monitor state-level indoor air quality mandate adoption as inflection indicator for compliance-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Fleet Monitoring Integration | Enables outcome-based contracts with JLL and Cushman & Wakefield procurement teams. |
| Modular Component Architecture | Addresses 40% technician vacancy rates through field-serviceable swap-out designs. |
| Multi-Surface Attachment Bundling | Captures margin premiums from residential upgraders while extending replacement cycles. |
| Boilerless Instant-Heat Development | Meets 24/7 casino and resort specifications in Las Vegas and Orlando procurement. |
| EU REACH Compliance Positioning | Positions saturated steam as default for professional cleaning contracts under solvent restrictions. |
Research Methodology
A standing panel of facility management procurement directors, aftermarket service network managers, EPA certification consultants, and hospitality operations executives provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA Energy Star certification databases, OSHA workplace sanitation guidance documents, customs import records for heating element components, and SEC filings from publicly traded cleaning equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down facility construction spending across the analysis window.
Consistency checks against hospital construction permits in Texas, Florida, and Arizona validated healthcare segment assumptions. The analytical framework modeled product type, technology tier, end-user vertical, and capacity specifications across the projection horizon. CAGRs derived from replacement cycle analysis, regulatory compliance cost trajectories, and raw material price sensitivity matrices. Forecast inputs incorporated EPA testing backlog duration estimates and REACH chemical restriction implementation timelines.
Material uncertainties — copper and aluminum price volatility, EPA certification timeline extensions, state-level indoor air quality mandate adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technician labor availability and import substitution penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Consumer Wet Wipes Market