
 Liquid Laundry Detergent Market | 2026-2036
Liquid Laundry Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Laundry Detergent Market Intelligence
Capacity expansion in China and India is narrowing the technology gap between regional producers and established multinational corporations. Procter & Gamble leverages its extensive global distribution network and brand equity to maintain leadership in premium segments. Unilever competes through a multi-tiered portfolio of brands targeting diverse consumer price points and regional preferences. Henkel differentiates its offerings with a strong focus on sustainable formulations and advanced chemical engineering for specialized applications.
Liquid laundry detergent is an aqueous cleaning solution using surfactants, enzymes, and builders to remove soil from textiles. Its primary function is to lower water's surface tension, allowing it to penetrate fabrics and suspend dirt for removal. Concentrated and pod formats are displacing conventional products due to consumer demand for convenience and reduced packaging waste. Formulations for commercial laundries in the healthcare sector require specific disinfecting properties not found in standard household products.
Product formulation is heavily influenced by chemical safety and environmental regulations. The US EPA’s Safer Choice program and the EU’s REACH directive govern the use of specific surfactants and phosphates, impacting ingredient sourcing and labeling. In China, national GB standards dictate product performance, safety, and labeling requirements. Stakeholders must now decide whether to invest in proprietary eco-friendly formulations for premium markets or scale up conventional products to capture volume in emerging economies.
Market Dynamics
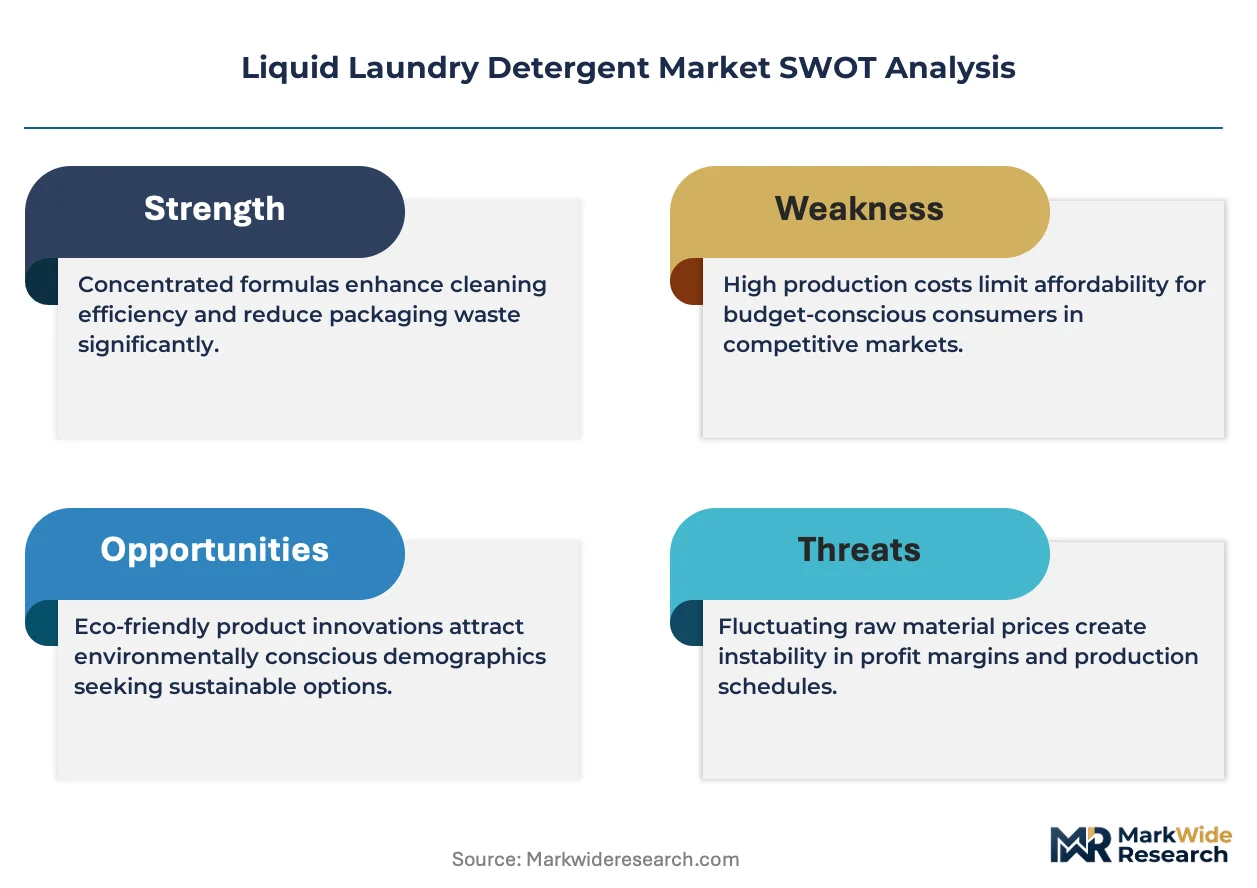
The market's central dynamic is the tension between regulatory mandates for sustainable, biodegradable formulations in developed economies and the strategic imperative to scale up production of cost-effective conventional products for high-volume, price-sensitive emerging markets.
Growth Catalysts
- Regulatory Alignment:EU REACH and US EPA Safer Choice programs accelerate R&D in biodegradable surfactants, creating a market for premium, eco-labeled products.
- Emerging Market Urbanization:Rising hygiene standards in urban India and Indonesia are driving first-time adoption of liquid formats over traditional powders and bars.
- Healthcare Sector Needs:Infection control mandates in hospitals fuel demand for specialized commercial laundry detergents with validated disinfecting properties.
Market Restraints
- Input Cost Volatility:Prices for petrochemical-derived surfactants are tied to volatile oil markets, creating margin pressure and forecast instability for producers.
- Regulatory Fragmentation:Divergent rules like the EU's REACH and China's GB standards increase compliance costs and complicate global formulation strategies.
- Substitution by Solids:Consumer demand for convenience and less plastic waste drives adoption of pods and sheets, eroding the market for bottled liquids.
Strategic Opportunities
- Specialty Formulations:Developing high-performance detergents for technical textiles like sportswear addresses an underserved niche requiring specialized care.
- Rural Market Penetration:Introducing low-cost liquid detergent sachets in rural Southeast Asia can capture volume from dominant powder formats.
- Advanced Enzyme Systems:Integrating novel enzymes with surfactants can create effective cold-water wash formulas, meeting demand for energy savings.
Industry Challenges
- Sustainable Sourcing:Securing a consistent supply of bio-based feedstocks like plant-derived oils is a major logistical challenge for mass production.
- Global Compliance Burden:Adapting packaging to comply with disparate regulations, such as the US EPA Safer Choice and EU Ecolabel, is a significant operational hurdle.
- Manufacturing Modernization:The capital investment to build or retrofit plants for concentrated formats creates a barrier for smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Laundry Detergent Market |
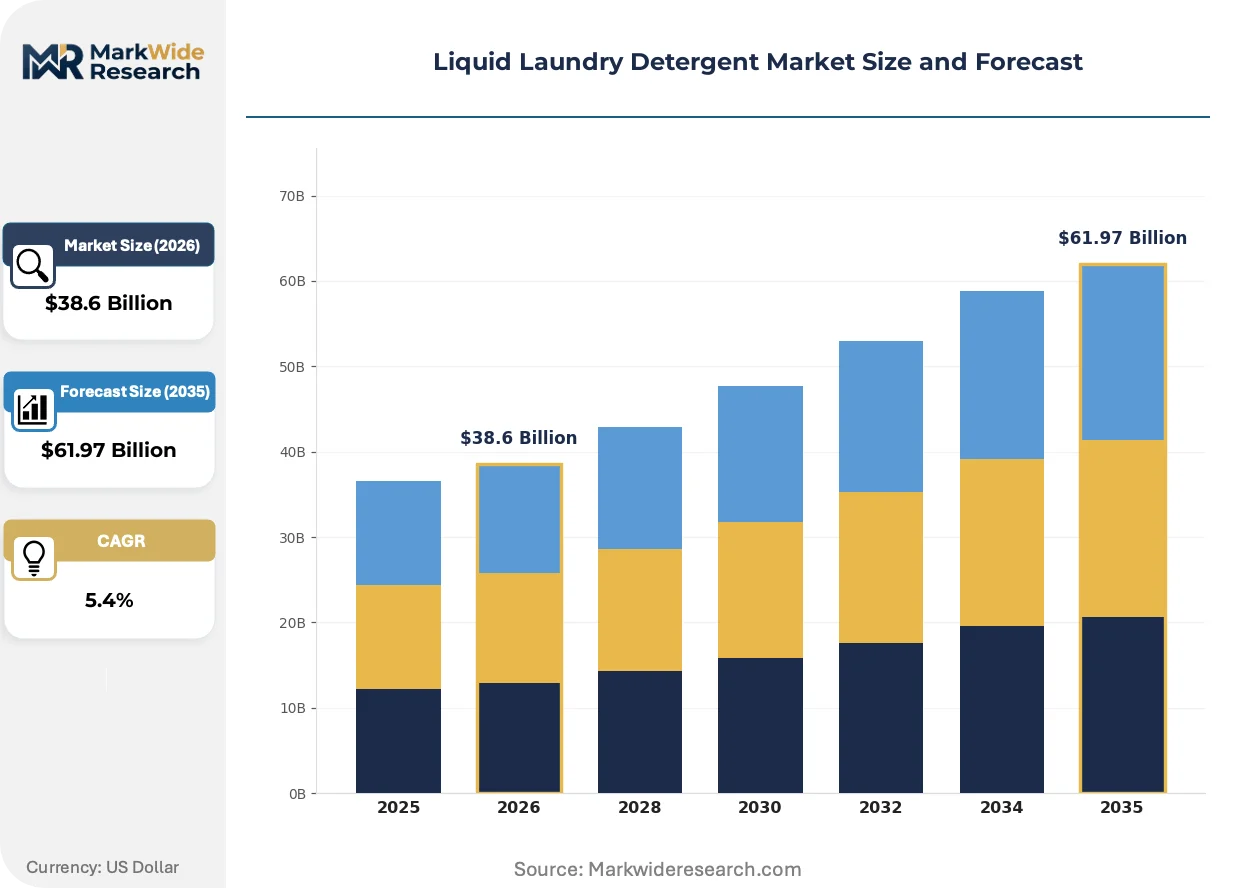
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Eco-Friendly, Concentrated, Pod Packaging Type: Bottles, Pouches, Tubs, Jugs End User: Households, Commercial Laundries, Hospitality, Healthcare Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Church & Dwight, Lion Corporation, Procter & Gamble, The Clorox Company, Reckitt, Unilever, Kao Corporation, SC Johnson, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Laundry Detergent Market Strategic Shifts & Innovations
Material science and digital technology are converging to alter product formulation and consumption models. Regulatory pressures for sustainability accelerate this shift, pushing the industry toward specialized solutions and circular economy principles that redefine value beyond simple cleaning performance.
Smart-dosing technology, integrated into connected washing machines, uses sensors to dispense the precise amount of detergent for a load. Appliance makers and premium brands are promoting this to eco-conscious consumers. This innovation is digitizing consumption, creating a path toward subscription-based auto-refill services that lock in customer loyalty.
The EU’s Ecodesign for Sustainable Products Regulation (ESPR) mandates recycled content in packaging and promotes refill systems. This directive forces manufacturers to abandon single-use virgin plastic bottles for models like refillable pouches. The household segment is most affected, with brands redesigning packaging to comply with circular economy goals in Europe.
A notable behavioral change is the rise of direct-to-consumer (DTC) subscription services for eco-friendly and specialized detergents. This channel disintermediates traditional retailers, enabling niche brands to build direct customer relationships. The model is gaining traction in North American and Western European urban markets with efficient residential delivery logistics.
Liquid Laundry Detergent Market Segmentation
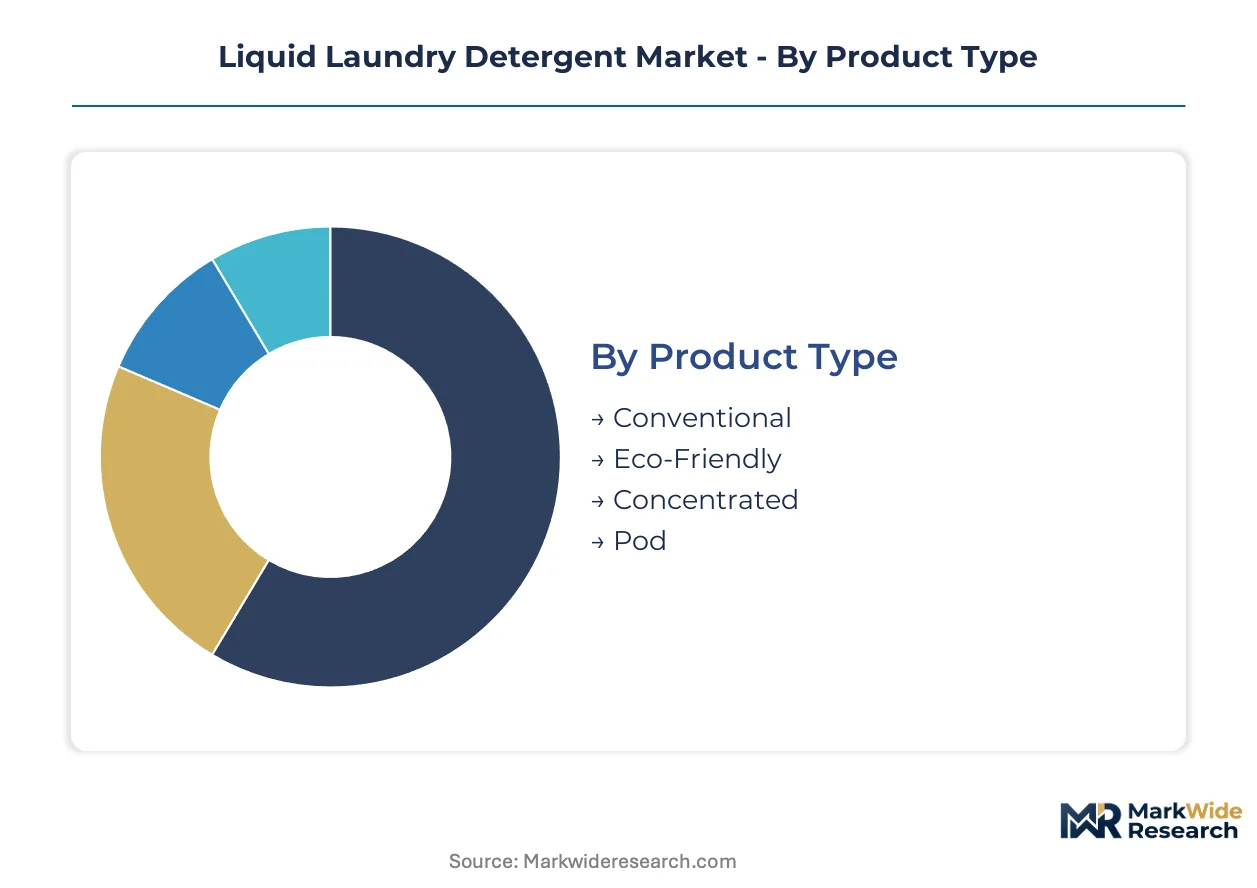
Market segmentation for liquid laundry detergents provides a granular view of consumer preferences and industry demands. Understanding these distinct segments allows manufacturers to tailor product formulations, packaging, and distribution strategies effectively. This detailed analysis highlights the diverse needs across various user groups and product formats.
Product Type:
The product type segmentation reflects varying after-sales service requirements, from simple usage instructions to specialized dispensing system support.
- Concentrated:These formulations offer higher active ingredient content, requiring smaller doses per wash cycle and reducing packaging volume. Demand is concentrating in developed economies like Germany and the United States, driven by environmental consciousness and regulatory pushes for reduced carbon footprint.
- Pod:Pre-measured, single-use detergent capsules provide ultimate convenience and eliminate spillage. Consumer demand for pods is rising in urban centers across Canada and the United Kingdom, fueled by busy lifestyles and compact living spaces.
- Conventional:Standard liquid detergents typically contain a higher water content and require larger dosing volumes per load.
- Eco-Friendly:Formulations using biodegradable surfactants and plant-derived ingredients cater to environmentally conscious consumers.
Conventional products hold the largest share; momentum sits with Pod formats.
Packaging Type:
Packaging types exhibit distinct cost tiers, influencing both production expenses and consumer affordability perceptions.
- Pouches:Flexible, lightweight packaging options often used for refills, reducing plastic waste and transportation costs. Demand for pouches is expanding in European markets like France and Italy, driven by circular economy initiatives like the EU’s Ecodesign for Sustainable Products Regulation.
- Bottles:Traditional rigid plastic containers, offering durability and ease of handling for household use. These are widely adopted across India and Indonesia, where product protection and shelf stability are primary concerns for consumers.
- Tubs:Larger, often multi-use containers typically found in commercial or bulk purchasing scenarios.
- Jugs:Similar to bottles but often with integrated handles, designed for larger volumes and easier pouring.
Bottles maintain significant market presence, while pouches are expanding most quickly.
End User:
End-user segments dictate specific application requirements for liquid laundry detergents, ranging from daily household use to stringent industrial cleaning protocols.
- Households:This segment includes all residential consumers utilizing detergents for personal laundry care. Consumption is high in populous nations such as China and Brazil, driven by rising disposable incomes and urbanization.
- Healthcare:Hospitals, clinics, and long-term care facilities require specialized detergents with disinfecting properties for infection control. Demand is particularly strong in the US and Germany due to strict hygiene regulations and patient safety standards.
- Commercial Laundries:Large-scale laundry operations serving hotels, restaurants, and other businesses.
- Hospitality:Hotels, resorts, and guesthouses use detergents for linen and uniform cleaning.
Household consumption drives overall volume, with the healthcare sector demonstrating a steepest expansion trajectory.
Distribution Channel:
Distribution channels are shaped by distinct customer purchasing behaviors and logistical preferences, catering to both individual consumers and bulk buyers.
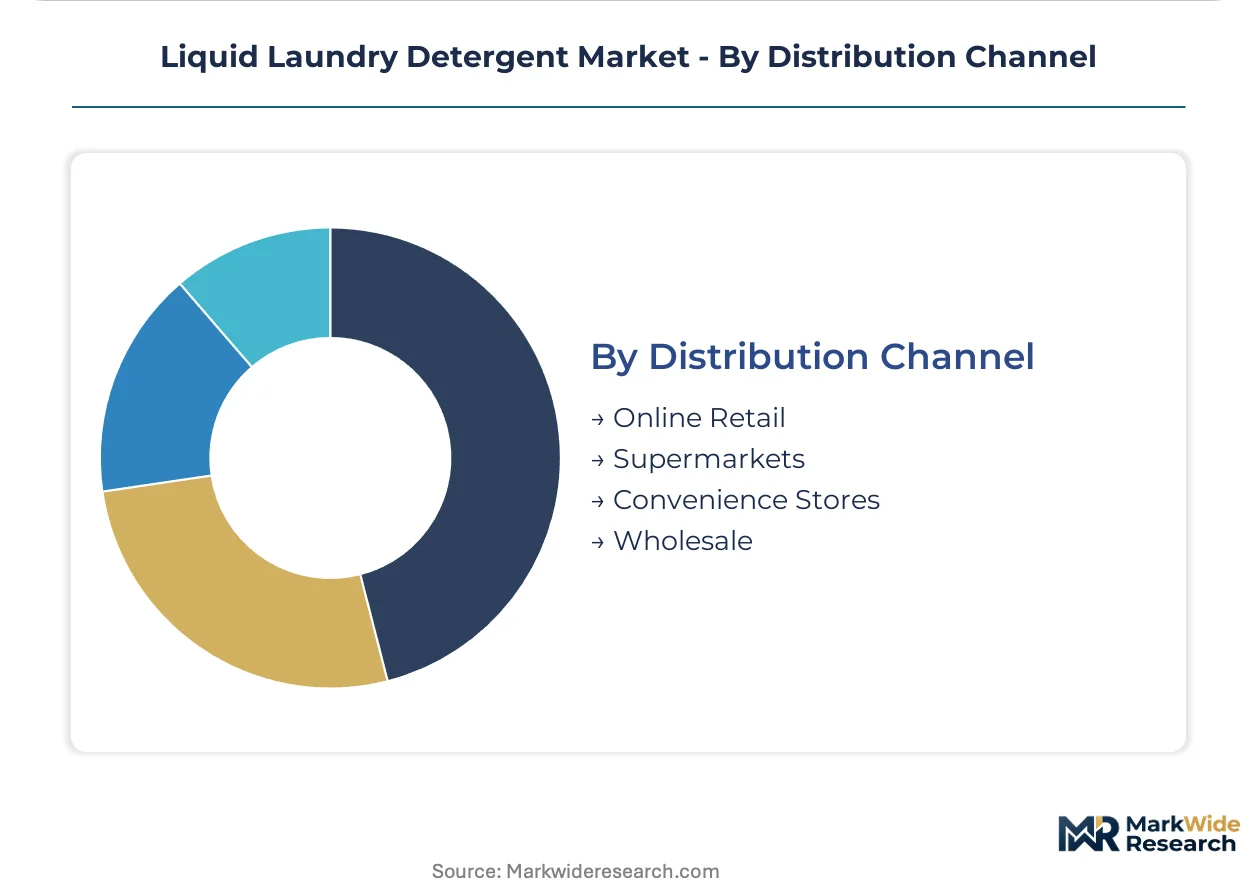
- Supermarkets:Large retail stores offering a wide variety of household products, serving as a primary channel for consumer purchases. This channel dominates in markets like the United Kingdom and Australia, providing extensive product choices and competitive pricing.
- Online Retail:E-commerce platforms and brand-specific websites offering direct delivery to consumers. This channel is gaining traction in the United States and Japan, supported by efficient logistics networks and subscription models.
- Convenience Stores:Smaller retail outlets providing quick access to essential household items, often catering to immediate needs.
- Wholesale:Bulk sales channels supplying products to commercial users, smaller retailers, or institutional buyers.
Supermarkets remain the primary channel, while online retail continues to gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global supply chain for liquid laundry detergent exhibits concentration in key manufacturing hubs. These hubs leverage access to raw materials and established distribution networks for scale. This dynamic influences product availability and pricing across diverse consumer markets.
India
Rising household hygiene standards in urban India drive first-time adoption of liquid formats over traditional powders. The Bureau of Indian Standards (BIS) dictates product quality and safety norms for domestic consumption. Production facilities in Maharashtra are scaling up to meet this expanding consumer base.
China
Rapid urbanization and a growing middle class in China stimulate demand for convenient liquid detergents. National GB standards regulate product performance, safety, and labeling requirements for all formulations. Manufacturers in the Yangtze River Delta are expanding capacity to serve both domestic and export markets.
United States
Consumer demand for convenience and eco-friendly options shapes the liquid laundry detergent market in the United States. The US EPA’s Safer Choice program promotes the use of environmentally preferred ingredients. Research and development centers in California innovate advanced enzyme systems for cold-water washing.
Germany
Strong environmental consciousness and stringent regulations define the liquid detergent landscape in Germany. The EU’s REACH directive influences ingredient sourcing and biodegradable surfactant development. Production clusters in North Rhine-Westphalia focus on specialized formulations for premium segments.
Indonesia
Urbanization and improving living standards in Indonesia are accelerating the shift from traditional bar soaps to liquid laundry detergents. The country's national standards body (SNI) ensures product quality and consumer safety. Manufacturing sites near Jakarta are increasing output to penetrate the vast domestic market.
Liquid Laundry Detergent Market Key Industry Players
Global multinational corporations and regional specialists split the liquid laundry detergent market, each pursuing distinct strategic paths. Large established players leverage extensive global distribution networks and brand equity to maintain leadership in premium segments. Smaller, agile firms focus on niche segments like eco-friendly formulations or specialized applications. Dominant competitive moves include portfolio diversification and strategic partnerships to access new technologies, alongside significant capacity expansion in emerging economies.
On the premium-tier vector, Procter & Gamble and Unilever represent global leaders with multi-tiered brand portfolios. These multinational corporations anchor significant market share through extensive product lines and strong consumer recognition across diverse geographies. Henkel exemplifies a specialist approach, focusing on sustainable formulations and advanced chemical engineering for diverse applications. These established players consistently invest in research and development to meet evolving consumer preferences and regulatory mandates. The Clorox Company, known for its household cleaning solutions, also occupies a position in this competitive landscape, often leveraging its existing brand reputation.
| Leading Market Players |
|---|
| Church & Dwight |
| Lion Corporation |
| Procter & Gamble |
| The Clorox Company |
| Reckitt |
| Unilever |
| Kao Corporation |
| SC Johnson |
| Henkel |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost fluctuations directly impact raw material procurement, influencing both supply concentration from Asian manufacturers and downstream price differentiation across consumer segments in North America.
Pricing Analysis
The US EPA’s Safer Choice program dictates the pricing tier structure for certified eco-friendly formulations, commanding a premium. Price differentiation stems from both certified quality grades and established brand equity, especially for multinational corporations like Procter & Gamble. Pricing softness reflects intense competition from conventional products in emerging economies, driven by local producers. Household consumers in price-sensitive markets like India exhibit high price sensitivity, while healthcare sector buyers prioritize performance over cost.
Supply Chain Analysis
The EU’s REACH directive, acting as a de facto regulatory control on specific chemical flows, influences ingredient sourcing and supply chain resilience. Geographic supply concentrates in manufacturing hubs across China, India, and Germany. The industry relies on petrochemical-derived surfactants and advanced enzyme systems, creating significant input dependencies. Commodity price volatility for oil-based inputs presents a primary structural risk. Distribution runs through a dual model, leveraging supermarkets for household volume and specialized wholesale channels for commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid laundry detergent market faces high-growth disruption, driven by the EU’s Ecodesign for Sustainable Products Regulation. This regulatory inflection accelerates the shift towards circular economy principles and advanced formulation technologies.
For Market Incumbents: Pre-empt market share erosion from direct-to-consumer (DTC) brands by investing in subscription-based auto-refill services. Consolidate market position through strategic acquisitions of specialized eco-friendly formulators, mitigating the threat of niche players. Leverage advanced enzyme systems R&D to differentiate premium offerings and meet evolving consumer preferences for cold-water washing. Strengthen distribution networks in emerging economies to counter regional competition. For New Entrants and Emerging Players: Specialty formulations for technical textiles like sportswear represent a highly penetrable niche, requiring advanced care solutions. Rural Southeast Asia offers white-space opportunity for low-cost liquid detergent sachets, capturing volume from traditional powder formats. A direct-to-consumer (DTC) subscription model provides an effective go-to-market angle, building direct customer relationships and loyalty. Focus on biodegradable surfactants for premium positioning in developed urban markets. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational corporations divesting non-core household product lines. The market exhibits long-term viability over the next decade, driven by sustained hygiene standards and innovation in sustainable chemistry. Acquisition targets include agile firms specializing in bio-based feedstocks or smart-dosing technology. The signal to watch is the accelerated adoption of circular packaging solutions in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This initiative captures volume in Indonesia and India, addressing rising household hygiene standards. |
| Advanced Enzyme System Development | This investment enables cold-water wash formulas, meeting US consumer demand for energy savings. |
| Biodegradable Surfactant R&D | This innovation aligns products with EU REACH regulations, opening premium market opportunities. |
| Direct-to-Consumer (DTC) Channel Launch | This strategy builds direct customer relationships for eco-friendly brands in North American urban markets. |
| Refill Pouch Packaging Redesign | This adaptation complies with the EU’s Ecodesign for Sustainable Products Regulation, reducing plastic waste. |
Research Approach
A standing panel of R&D directors, plant managers, procurement leads, and brand managers provided ongoing calibration and validation for market insights. Primary interviews with these industry stakeholders were triangulated with extensive secondary research. This included analysis of national GB standards, US EPA data, EU REACH reports, and trade association publications. Both bottom-up and top-down approaches were utilized to ensure comprehensive data integrity.
Scenario-bracketing provided a robust framework for projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, packaging type, end user, and distribution channel, alongside ingredient profile. Compound annual growth rates were derived through regression analysis, incorporating historical trends and anticipated shifts in consumer behavior. Key forecast inputs included raw material cost projections and regulatory compliance timelines.
Practitioners should monitor shifts in petrochemical prices and new regulatory mandates for early signals of market change. Forecasts inherently reflect current assumptions regarding technological adoption and consumer preferences. Material shifts in bio-based feedstock availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Fabric Care Market