
 Baby Wipes Market | 2026-2036
Baby Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Wipes Market Analysis
The boundary between premium and commodity baby wipes is hardening around ingredient transparency and substrate sourcing. Procter & Gamble leverages its North American retail dominance to sustain volume leadership through club-channel exclusives. Kimberly-Clark Corporation anchors its position via healthcare facility partnerships that demand clinical-grade formulations. Hengan International Group competes on manufacturing scale across Greater China, where local cost structures undercut imported alternatives.
Baby wipes are pre-moistened disposable cloths, typically comprising non-woven fabric substrates saturated with aqueous solutions containing cleansers, preservatives, and skin-conditioning agents, designed for infant hygiene maintenance and gentle epidermal cleansing. Wet wipes command the largest revenue share due to habitual consumer preference for convenience, though plant-based fiber materials represent the fastest-expanding category as sustainability mandates intensify across retail procurement policies. Sensitive skin wipes occupy the highest margin tier, where dermatological testing certifications justify price premiums over standard formulations.
The EPA regulates preservative biocides in U.S.-manufactured wipes under FIFRA, while the EU REACH framework restricts certain chemical additives and drives reformulation investments. India's BIS certification requirements for infant care products create compliance barriers for unqualified imports. Stakeholders must monitor evolving plastic-content thresholds, as pending regulatory expansions in major markets will determine which substrate technologies secure long-term shelf access.
Market Dynamics
The EU Single-Use Plastics Directive is forcing substrate transitions across manufacturing footprints, compressing margins for petrochemical-dependent producers while opening procurement pathways for cellulose fiber innovators. This regulatory compression cascades through formulation chemistry, packaging specifications, and retail listing requirements simultaneously.
Growth Catalysts
- REACH chemical restrictions:The EU framework bans specific preservatives and fragrance compounds, compelling manufacturers to reformulate with dermatologically certified alternatives that command shelf placement in premium retail channels.
- Healthcare facility hygiene protocols:Clinical-grade wipe specifications are expanding from hospital settings into outpatient clinics and eldercare facilities, pulling industrial-quality manufacturing standards into adjacent consumer segments.
- Urban nuclear family concentration in India:Metropolitan household structures with dual-income parents generate recurring bulk purchasing patterns that sustain subscription-channel volume commitments.
Market Restraints
- Viscose fiber cost volatility:Wood pulp input prices fluctuate with forestry harvest cycles and energy-intensive processing costs, compressing gross margins for plant-based substrate commitments.
- Preservative biocide supply concentration:EPA FIFRA-registered active ingredient manufacturers cluster in limited chemical production corridors, creating single-source vulnerability for compliant formulations.
- Flushability technical limitations:Current dispersibility testing protocols (EDANA/INDA GD4) fail to prevent municipal wastewater system blockages, restricting marketing claims and inviting liability exposure.
Strategic Opportunities
- Indian tier-2 city penetration:Hyderabad, Pune, and Ahmedabad exhibit underdeveloped modern trade infrastructure where direct-to-retail distribution partnerships can preempt multinational brand establishment.
- Compostable packaging mandates:The EU Packaging and Packaging Waste Regulation creates procurement tailwinds for bio-based film substrates that biodegrade in industrial composting facilities.
- Telemedicine-integrated dermatology:Remote pediatric skin consultations are normalizing prescription-linked wipe recommendations, converging healthcare channel credibility with home delivery logistics.
Industry Challenges
- BIS certification timeline compression:India's infant product safety mark requires 12-18 month laboratory validation cycles that delay market entry against faster-notified competitors.
- Legacy wet-laid line retrofitting:Existing nonwoven machinery requires capital-intensive modification to process natural fiber blends at commercial throughput rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Wipes Market |
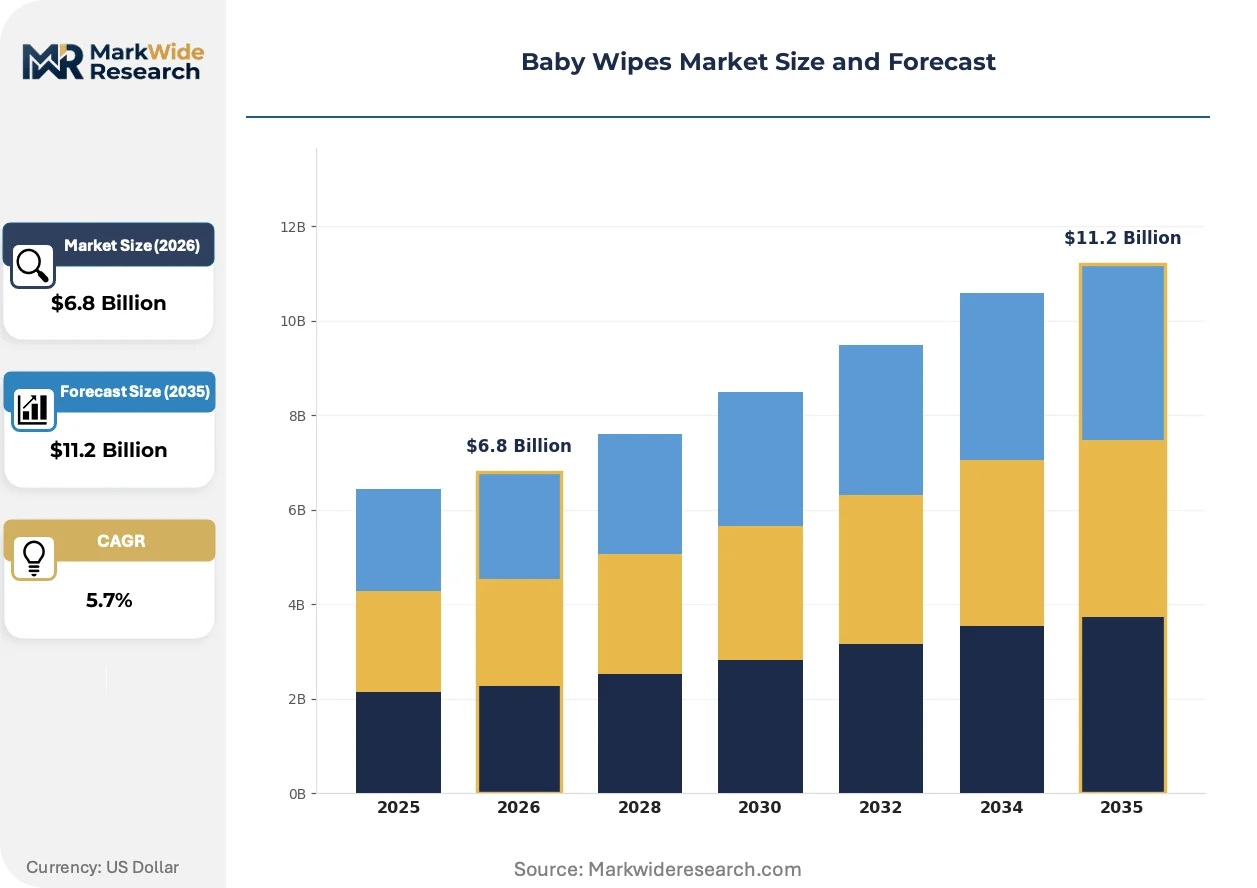
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Wipes, Dry Wipes, Antibacterial Wipes, Sensitive Skin Wipes Material: Pure Cotton, Non-Woven Fabric, Bamboo Fiber, Plant-Based Fiber Package Type: Resealable Packs, Canisters, Travel Packs, Bulk Packs End User: Parents, Caregivers, Healthcare Facilities, Childcare Centers |
| Companies Covered | Unicharm Corporation, Nice-Pak Products, Procter & Gamble, Hengan International Group, Rockline Industries, Kimberly-Clark Corporation, First Quality Enterprises, Pigeon Corporation, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Wipes Market Emerging Trajectories
Substrate chemistry and preservation systems are converging around dermatological safety verification, with manufacturing investments tracking regulatory threshold tightening rather than consumer preference polling alone.
Lyocell fiber production is integrating closed-loop solvent recovery systems that eliminate traditional viscose carbon disulfide emissions. Premium private-label buyers in German and French pharmacy channels are adopting these substrates at accelerated qualification schedules. This technology is integrating clinical-grade supply chains with mass-market retail cost structures, collapsing the historical separation between medical and consumer wipe manufacturing tiers.
EPA FIFRA registration renewal requirements for isothiazolinone preservatives are tightening concentration limits and expanding warning label mandates. Formulation houses are accelerating phenoxyethanol and organic acid alternative development to preempt supply disruption. Sensitive-skin product lines in North American markets face the steepest compliance recalibration, with several mid-tier brands withdrawing SKUs rather than absorbing reformulation costs.
Subscription commerce platforms are capturing recurring purchase commitments through auto-replenishment algorithms calibrated to household consumption telemetry. Direct-to-consumer channels in UK and US markets are displacing impulse-driven supermarket purchases, compressing brand switching opportunities and locking in twelve-month volume contracts. Urban parents with predictable delivery logistics show the highest retention rates, particularly in London, New York, and San Francisco metropolitan corridors.
Baby Wipes Market Segmentation
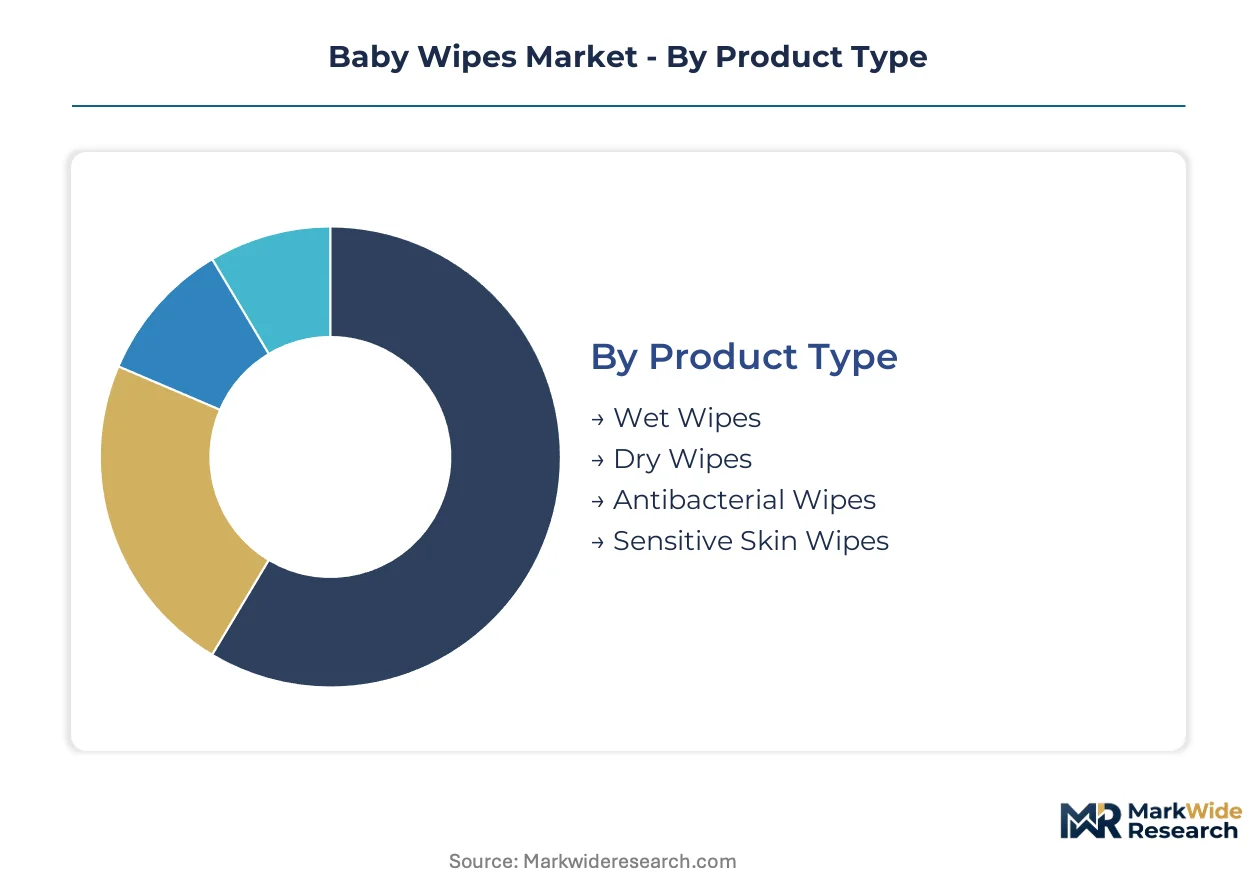
Segmentation in baby wipes determines regulatory exposure and margin architecture. Substrate chemistry and end-use specifications dictate which certification pathways manufacturers must navigate to secure shelf access across retail and institutional channels.
Product Type:
FDA cosmetic regulations govern standard formulations, while EPA FIFRA registration requirements apply to antibacterial claims. Sensitive skin variants require dermatological testing documentation for pharmacy channel placement.
- Wet Wipes:Pre-moistened cloths saturated with aqueous solutions containing cleansers and preservatives. Parents in urban India drive recurring bulk purchases through subscription platforms, though viscose fiber cost volatility compresses margins for plant-based substrate commitments.
- Sensitive Skin Wipes:Formulations exclude fragrance compounds and MIT/CMIT preservatives per REACH restrictions. Dermatological testing certifications command price premiums in North American pharmacy channels, with several mid-tier brands withdrawing SKUs rather than absorbing reformulation costs.
- Dry Wipes:Unsaturated cloths requiring separate moisture application.
- Antibacterial Wipes:EPA-registered biocide formulations for infection control protocols.
Leading the category by volume: Wet Wipes. Growing fastest: Sensitive Skin Wipes.
Material:
Raw material sourcing stratifies manufacturing cost structures and determines regulatory compliance trajectories under plastic-content thresholds.
- Non-Woven Fabric:Petrochemical-based synthetic substrates dominate legacy production lines. EU Single-Use Plastics Directive pressures transition toward cellulose alternatives, compressing margins for conventional producers while opening procurement pathways for fiber innovators.
- Plant-Based Fiber:Cellulose substrates from sustainably harvested wood pulp qualify for bio-based procurement policies. German and French pharmacy channels accelerate qualification schedules for lyocell fiber with closed-loop solvent recovery systems.
- Pure Cotton:Natural fiber requiring intensive water cultivation.
- Bamboo Fiber:Rapid-growth grass alternative with regional cultivation concentration.
Highest volume share: Non-Woven Fabric. Steepest expansion trajectory: Plant-Based Fiber.
Package Type:
Distribution channel requirements determine format specifications, with retail listing fees varying substantially by container geometry and shelf footprint.
- Resealable Packs:Adhesive closure systems maintain moisture retention through repeated opening cycles. Club-channel exclusives in North American retail sustain volume leadership through pallet-scale commitments.
- Bulk Packs:Multi-hundred count configurations serve subscription commerce platforms capturing recurring purchase commitments. Urban parents with predictable delivery logistics show highest retention rates in London, New York, and San Francisco metropolitan corridors.
- Canisters:Rigid plastic containers with dispensing lids.
- Travel Packs:Compact pocket-size formats for mobility.
Dominant by shipment volume: Bulk Packs. Expanding most quickly: Resealable Packs.
End User:
Institutional procurement specifications diverge sharply from consumer retail requirements, pulling industrial-quality manufacturing standards into adjacent segments.
- Parents:Dual-income metropolitan households generate premium product uptake with ingredient transparency demands. India's urban nuclear families in Hyderabad, Pune, and Ahmedabad sustain subscription-channel volume commitments.
- Healthcare Facilities:Clinical-grade wipe specifications require ISO 13485 manufacturing certification. Hospital partnerships expand into outpatient clinics and eldercare facilities, collapsing historical separation between medical and consumer wipe manufacturing tiers.
- Caregivers:Non-parental household members including grandparents and nannies.
- Childcare Centers:Licensed facilities with state-mandated hygiene protocols.
Largest addressable base: Parents. Fastest specification upgrade: Healthcare Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the industry's fastest-expanding demand corridor, where urban nuclear families in Maharashtra sustain subscription-channel volume commitments through predictable delivery logistics.
United States
Club-channel exclusives in North American retail sustain volume leadership through pallet-scale commitments. EPA FIFRA registration requirements for preservative biocides compress formulation flexibility. Greater Boston's healthcare corridor pulls clinical-grade manufacturing standards into adjacent consumer segments through ISO 13485-certified production networks.
Germany
Premium private-label buyers in pharmacy channels accelerate qualification schedules for lyocell fiber with closed-loop solvent recovery systems. EU REACH chemical restrictions ban specific preservatives, compelling dermatologically certified alternatives. The Eindhoven-Ruhr industrial corridor concentrates cellulose fiber innovation capacity serving bio-based procurement policies.
India
Metropolitan household structures with dual-income parents generate recurring bulk purchasing patterns. BIS certification requirements for infant care products create compliance barriers for unqualified imports. Hyderabad, Pune, and Ahmedabad exhibit underdeveloped modern trade infrastructure where direct-to-retail distribution partnerships preempt multinational brand establishment.
China
Local cost structures undercut imported alternatives across Greater China manufacturing footprints. The country's national quality regulator enforces infant product safety standards that delay market entry against faster-notified competitors. Yangtze River Delta production clusters concentrate wet-laid nonwoven capacity requiring capital-intensive retrofitting for natural fiber blends.
United Kingdom
Subscription commerce platforms capture recurring purchase commitments through auto-replenishment algorithms. The EU Single-Use Plastics Directive pressures material transitions toward plant-based substrates even post-Brexit. London metropolitan corridors show highest retention rates for urban parents with predictable delivery logistics.
Baby Wipes Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across substrate chemistry and formulation architecture. The vendor base stratifies between multinational hygiene conglomerates with captive retail distribution and regional specialists with flexible manufacturing footprints. Three archetypes dominate: scale-driven substrate manufacturers, clinical-grade certification holders, and subscription-commerce native brands. Consolidation pressure manifests through healthcare facility partnership acquisitions and direct-to-consumer channel integration.
Among Asia-Pacific-based manufacturers, Hengan International Group and Unicharm Corporation exemplify scale-driven substrate production archetypes. Procter & Gamble occupies a position representing North American retail dominance through club-channel infrastructure. Kimberly-Clark Corporation anchors the clinical-grade tier via healthcare facility partnerships demanding ISO 13485 manufacturing certification.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Nice-Pak Products |
| Procter & Gamble |
| Hengan International Group |
| Rockline Industries |
| Kimberly-Clark Corporation |
| First Quality Enterprises |
| Pigeon Corporation |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap substrate producers across the Yangtze River Delta anchor cellulose fiber supply, translating procurement loyalty into pricing discipline that resists commoditization even as viscose input costs fluctuate with forestry harvest cycles.
Pricing Analysis
Subscription-based recurring revenue anchors value capture for urban nuclear families in London, New York, and Mumbai. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically certified sensitive-skin formulations from club-channel bulk configurations. Cost compression in plant-based substrate tiers is intensifying because viscose fiber production draws from energy-intensive processing. Healthcare facility buyers show least price sensitivity due to ISO 13485 certification requirements, while tier-2 Indian metropolitan parents exhibit highest elasticity.
Supply Chain Analysis
EU Single-Use Plastics Directive domestic-content thresholds are reshaping sourcing toward cellulose fiber innovators in Germany, China, and India. Raw material dependencies center on wood pulp harvest cycles, phenoxyethanol preservative alternatives, and bio-based film substrates for compostable packaging. Single-source vulnerability clusters around EPA FIFRA-registered biocide manufacturers in limited chemical production corridors. Distribution runs through club-channel pallet-scale commitments in North America, pharmacy channel qualification schedules in Germany and France, and direct-to-retail partnerships in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as REACH chemical restrictions and BIS certification timelines force sub-scale formulators to exit rather than absorb compliance recalibration costs.
For Market Incumbents: To counter mid-tier brand withdrawals from sensitive-skin segments, deepen backward integration into lyocell fiber production with closed-loop solvent recovery systems. Secure ISO 13485 manufacturing certification to capture healthcare facility partnerships expanding into outpatient clinics and eldercare facilities.
For New Entrants and Emerging Players: Capture underdeveloped modern trade infrastructure in Hyderabad, Pune, and Ahmedabad through direct-to-retail distribution partnerships that preempt multinational brand establishment. Target subscription-commerce native positioning with auto-replenishment algorithms calibrated to household consumption telemetry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor clinical-grade certification holders in Greater China and India where national quality regulator enforcement delays market entry for unqualified imports. Five-to-ten year viability hinges on substrate chemistry transition completion. Signal to monitor: pending regulatory expansions in plastic-content thresholds determining long-term shelf access.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyocell Fiber Capacity Expansion | Closed-loop solvent recovery systems eliminate carbon disulfide emissions for EU pharmacy channel qualification. |
| Healthcare Facility Partnership | ISO 13485 certification pulls clinical-grade standards into adjacent consumer segments through hospital network expansion. |
| Direct-to-Consumer Channel Launch | Auto-replenishment algorithms lock in twelve-month volume contracts from urban parents with predictable delivery logistics. |
| Sustainability Repositioning | Plant-based fiber substrates secure procurement pathways under EU Single-Use Plastics Directive compliance mandates. |
| Regulatory Certification Investment | BIS infant product safety mark and EPA FIFRA registration preempt supply disruption from preservative biocide restrictions. |
Methodological Framework
Trade databases, regulatory filings, and retail audit data formed the secondary backbone, supplemented by primary interviews with substrate R&D directors, pharmacy channel procurement managers, infant care brand managers, and healthcare facility supply chain heads. Bottom-up and top-down triangulation validated volume estimates across wet-laid nonwoven production clusters and subscription-commerce platform transaction records.
Bottom-up modeling tracked substrate chemistry transitions, formulation architecture shifts, and channel migration patterns across the projection horizon. Segmentation dimensions included product type, material substrate, package configuration, and end-user specification tier. CAGRs derived from regression analysis against viscose fiber input cost trajectories and regulatory compliance investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction expansions, BIS certification timeline compressions, and municipal wastewater system dispersibility protocol revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Changing Station Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Sippy Cups Market
Baby Products
Stroller Rental Market
Baby Products
Baby Swing Market
Baby Products
Canada Baby Care Products Market
Baby Products
Baby Tableware Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Digital Monitor Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Kids Activity Box Market
Baby Products
Kids Training Pant Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Baby Walker Market
Baby Products
Baby Feeding Bottles Market