
 Silicone Fabrics Market | 2026-2036
Silicone Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Fabrics Market Outlook
REACH is recalibrating the cost-of-entry calculus for silicone fabric suppliers seeking European market access. 3M leverages its polymer science depth to sustain certification leadership across multiple regulatory jurisdictions. Wacker Chemie AG anchors its position through backward integration into siloxane raw materials, ensuring supply security for coated fabric output. Shin-Etsu Chemical Co., Ltd. dominates Asian production scale, while Saint-Gobain Performance Plastics competes on high-temperature performance specifications for aerospace laminates.
Silicone fabrics are textile substrates impregnated or coated with polydimethylsiloxane (PDMS) elastomers, typically achieving temperature resistance from -60°C to 250°C and hydrophobic surface properties. These materials serve critical functions in thermal insulation, chemical protection, and flexible sealing across industrial and commercial environments. Coated silicone fabrics command the largest value share due to their established use in aerospace insulation blankets and automotive gaskets, though self-adhesive formats are gaining traction in healthcare device assembly where clean-room bonding is essential. Laminated constructions carry premium positioning in protective apparel, while non-woven variants remain a niche focused on disposable medical textiles.
The EPA governs volatile organic compound emissions from silicone coating operations in the United States, pushing manufacturers toward water-based formulation investments. ECHA enforces REACH substance restrictions on siloxane environmental persistence, directly influencing R&D priorities for European suppliers. FDA biocompatibility standards for implantable and patient-contact textiles create a parallel compliance track for healthcare-focused producers. Stakeholders must weigh regulatory trajectory against material substitution risk as bio-based elastomer research advances.
Market Dynamics
REACH substance restrictions on siloxane environmental persistence are recalibrating R&D priorities across European silicone fabric supply chains, forcing reformulation investments while creating competitive separation between compliant and non-compliant producers.
Growth Catalysts
- Electric vehicle battery enclosure demand:Automotive OEMs in Germany's industrial corridor source flame-retardant silicone fabrics for thermal runaway protection, creating specification pull-through across Tier-1 supplier networks.
- FDA biocompatibility pathway expansion:Medical-grade silicone textiles gain procurement priority as US hospitals upgrade protective equipment standards for patient-contact applications.
- Water-based formulation mandates:EPA volatile organic compound emission rules push coating operations toward aqueous silicone dispersion technologies, opening retrofit demand for compliant production lines.
Market Restraints
- Siloxane raw material concentration:Backward integration into polydimethylsiloxane precursors limits viable supplier base to integrated chemical conglomerates, constraining mid-tier fabricator expansion.
- High-temperature performance ceiling:Standard PDMS elastomers degrade above 250°C, excluding silicone fabrics from next-generation aerospace propulsion insulation where ceramic matrix composites capture specification.
- REACH certification cost burden:ECHA substance evaluation fees and testing protocols impose six-figure entry costs for European market access, filtering smaller coated substrate producers.
Strategic Opportunities
- India medical textile infrastructure:CDSCO regulatory harmonization with ISO 13485 creates certification pathway for silicone fabric exporters targeting surgical drape and implantable mesh applications.
- Self-adhesive format penetration:Clean-room bonding requirements in healthcare device assembly displace mechanical fasteners, opening margin expansion for adhesive-coated silicone textile specialists.
- EU Green Deal procurement incentives:Public hospital purchasing frameworks award preference points to suppliers demonstrating bio-based elastomer research progress, rewarding early reformulation movers.
Industry Challenges
- Cross-functional polymer-textile engineering scarcity:Coated fabric production requires simultaneous mastery of siloxane chemistry and textile handling, with qualified process engineers concentrated at incumbent integrated producers.
- Multi-jurisdiction certification synchronization:Healthcare-focused suppliers must maintain parallel FDA 510(k), CE marking under MDR, and ISO 10993 biocompatibility tracks, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Fabrics Market |
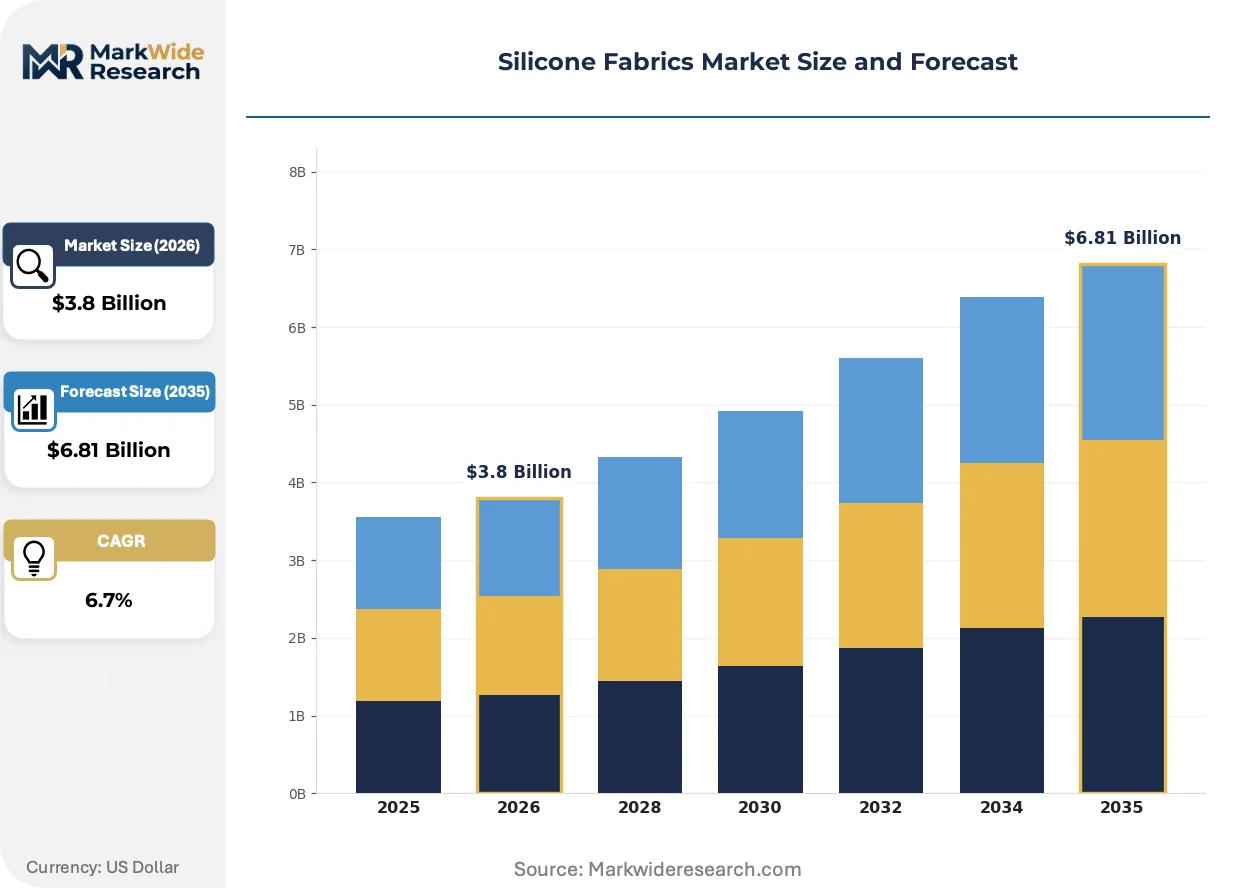
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Coated, Laminated, Non-Woven Application: Aerospace, Healthcare, Automotive, Construction End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Elkem ASA, 3M, Auburn Manufacturing, Inc., Saint-Gobain Performance Plastics, Newtex Industries, Inc., Mid-Mountain Materials Inc, Shin-Etsu Chemical Co., Ltd., Wacker Chemie AG, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Fabrics Market Strategic Shifts
Silicone fabric technology trajectories center on environmental compliance, performance specification elevation, and healthcare application expansion, with formulation chemistry and bonding architecture as the primary innovation vectors.
Nano-silica reinforced PDMS coatings are converging with aerospace laminate requirements, delivering enhanced abrasion resistance for insulation blankets exposed to turbine vibration environments. Tier-1 suppliers in France and Germany adopt these formulations under accelerated qualification timelines. The technology is converging with traditional silicone fabric specifications, compressing the performance gap between standard and premium product tiers.
ECHA enforcement of REACH Annex XVII restrictions on cyclic siloxane content is forcing reformulation of cosmetic-grade and industrial-grade silicone precursors alike. Coated fabric producers serving European medical and automotive end-uses face raw material qualification disruptions. Suppliers with captive siloxane synthesis capabilities accelerate D4/D5/D6 elimination programs ahead of 2026 enforcement windows.
Hospital procurement departments consolidate supplier panels around dual-certified vendors holding both FDA clearance and MDR conformity, displacing single-jurisdiction specialists. Group purchasing organizations in the US and centralized hospital procurement in Germany drive this concentration. The shift is most visible in surgical textile categories where silicone-coated drapes command premium positioning against polyethylene alternatives.
Silicone Fabrics Market Segmentation
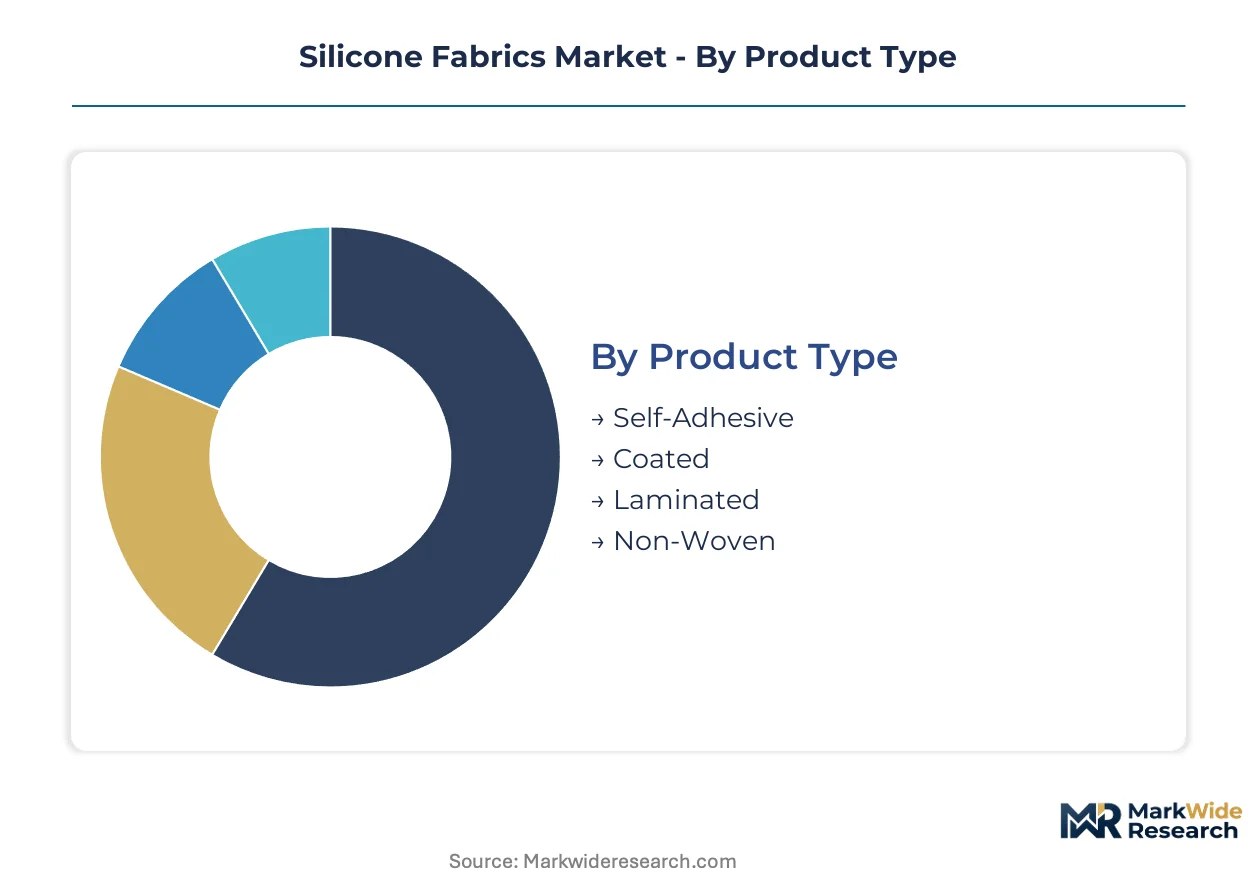
Silicone fabric procurement patterns diverge sharply across product formats and end-use specifications. Buyers prioritize thermal performance thresholds in aerospace, biocompatibility certification in healthcare, and flame-retardant ratings in automotive applications.
Product Type:
Cost tier separates commodity buyers from specification-driven procurement in this category.
- Coated:Textile substrates impregnated with polydimethylsiloxane elastomers achieve temperature resistance from -60°C to 250°C. Automotive suppliers in Germany's industrial corridor specify these for electric vehicle battery enclosure insulation, driven by thermal runaway protection mandates.
- Self-Adhesive:Pressure-sensitive silicone layers enable clean-room bonding without mechanical fasteners. Healthcare device assemblers favor this format for surgical drape and implantable mesh applications where contamination control is paramount.
- Laminated:Multi-layer constructions bond silicone films to reinforcing substrates for protective apparel.
- Non-Woven:Discontinuous fiber matrices coated with silicone serve disposable medical textile applications.
Coated fabrics lead volumes today; self-adhesive formats are gaining share fastest.
Application:
Maturity stage determines whether buyers seek established suppliers or emerging specialists.
- Aerospace:Laminated silicone fabrics insulate turbine environments and engine nacelles against extreme thermal cycling. French and German Tier-1 suppliers accelerate qualification of nano-silica reinforced coatings for vibration-exposed insulation blankets.
- Healthcare:Medical-grade silicone textiles require parallel FDA 510(k) and MDR conformity tracks. US hospital procurement upgrades and German centralized purchasing frameworks consolidate supplier panels around dual-certified vendors.
- Automotive:Flame-retardant specifications for electric vehicle battery protection dominate sourcing priorities.
- Construction:Weather sealing and membrane applications utilize standard-grade coated fabrics.
Aerospace leads volumes today; healthcare is expanding most quickly.
End User:
Volume scale dictates whether procurement emphasizes price negotiation or technical partnership.
- Manufacturers:Original equipment producers in automotive and aerospace specify silicone fabrics at the design stage, locking in multi-year supply agreements with certified coating operations.
- Distributors:Inventory-holding intermediaries serve fragmented construction and industrial maintenance demand.
- Retailers:Small-format sales target consumer protective gear and hobbyist applications.
- Consumers:Direct purchases concentrate in specialized protective apparel and DIY thermal insulation.
Manufacturers lead volumes today; distributors are climbing the fastest.
Distribution Channel:
Customer technical sophistication determines channel preference in this category.
- Direct Sales:Technical field teams engage aerospace and automotive OEMs for specification development. EPA compliance documentation and REACH certification records transfer directly between supplier and buyer engineering departments.
- Online:E-commerce platforms capture standard-grade coated fabric orders from small manufacturers and maintenance operations seeking rapid procurement turnaround.
- Wholesalers:Regional inventory positions serve construction contractors with predictable material requirements.
- Specialty Stores:Localized outlets target consumer protective equipment and hobbyist thermal insulation projects.
Direct sales lead volumes today; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone fabric production originated in German industrial chemistry during the mid-20th century, establishing the Rhine-Ruhr corridor as the foundational manufacturing cluster before Asian capacity expansion reshaped supply geography.
United States
Electric vehicle battery enclosure specifications from Detroit-area OEMs drive flame-retardant silicone fabric procurement. EPA volatile organic compound rules push coating operations toward water-based formulation investments. Ohio and Michigan host the primary automotive supplier concentration, with Tier-1 fabricators qualifying materials for thermal runaway protection systems.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg source coated fabrics for EV battery insulation, creating specification pull-through across supplier networks. ECHA REACH enforcement on cyclic siloxane content forces reformulation investments ahead of 2026 deadlines. The Rhine-Ruhr industrial corridor maintains backward-integrated siloxane synthesis capacity serving coated fabric output.
China
Domestic EV production scale in Shanghai and Guangzhou generates silicone fabric demand for battery thermal management. MIIT industrial standards for new energy vehicle safety create certification requirements for flame-retardant materials. Yangtze River Delta manufacturers expand coating capacity to serve both domestic OEMs and export markets.
Japan
Aerospace laminate specifications from Nagoya-area propulsion suppliers sustain demand for high-temperature silicone fabrics. METI industrial policy supports materials innovation for next-generation aircraft insulation. Kansai region fabricators concentrate on nano-silica reinforced formulations for turbine vibration environments.
India
CDSCO regulatory harmonization with ISO 13485 opens certification pathways for medical-grade silicone textile exporters. Surgical drape and implantable mesh applications attract procurement investment from Mumbai and Ahmedabad healthcare manufacturers. Gujarat's specialty chemicals corridor develops coating capacity targeting European and North American medical device assemblers.
Silicone Fabrics Market Competitive Environment
The competitive structure tilts toward integrated chemical conglomerates with captive siloxane supply. Three to five integrated producers control premium specification segments, while mid-tier fabricators compete on standard-grade coated fabrics for construction and industrial maintenance. Two dominant archetypes emerge: backward-integrated siloxane producers and specialized coating operations with textile handling expertise. Capacity expansion and REACH compliance certification constitute the primary competitive moves, with M&A activity concentrated among European coating specialists seeking ECHA-ready formulation portfolios.
Among integrated chemical producers, Wacker Chemie AG and Shin-Etsu Chemical Co., Ltd. exemplify the siloxane-anchored archetype with upstream control over polydimethylsiloxane precursors. Saint-Gobain Performance Plastics occupies a position within the high-performance laminate tier, representing specialization in aerospace and industrial insulation specifications. These three companies illustrate the competitive bifurcation between raw material-integrated players and application-focused fabricators.
| Leading Market Players |
|---|
| Elkem ASA |
| 3M |
| Auburn Manufacturing, Inc. |
| Saint-Gobain Performance Plastics |
| Newtex Industries, Inc. |
| Mid-Mountain Materials Inc |
| Shin-Etsu Chemical Co., Ltd. |
| Wacker Chemie AG |
| Trelleborg AB |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists in Germany's Rhine-Ruhr corridor anchor regional supply discipline, translating captive siloxane access into pricing power against fragmented Asian competitors while ECHA REACH compliance costs filter non-integrated fabricators from premium specification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified laminates from automotive-grade coated fabrics and construction-standard rolls. Price differentiation rests on certification tier — dual FDA-MDR clearance commands substantial premia over single-jurisdiction compliance — and volume scale, with OEM direct contracts compressing per-unit costs below distributor markups. Cost compression in standard-grade tiers is intensifying because Yangtze River Delta capacity expansion floods commodity segments. Healthcare manufacturers show lowest price sensitivity, prioritizing biocompatibility documentation over procurement savings.
Supply Chain Analysis
Freight cost differentials between bulk siloxane feedstock and finished coated fabric shipments favor regional production clustering over intercontinental supply chains. Manufacturing concentrates in Germany, China, and Japan, with each hub drawing from distinct precursor supply bases. Raw material dependencies center on polydimethylsiloxane monomers, textile substrates from polyester to aramid fibers, and nano-silica reinforcement additives. Single-source vulnerability runs through European siloxane supply where ECHA cyclic siloxane restrictions threaten feedstock continuity. Distribution runs through direct technical sales for aerospace and automotive OEMs, with online channels capturing standard-grade construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone fabrics market compounds steadily as electric vehicle battery thermal protection mandates create specification lock-in across automotive supply chains, generating predictable offtake visibility for qualified coating operations.
For Market Incumbents: Hedge REACH reformulation risk by accelerating D4/D5/D6 elimination programs ahead of enforcement windows while securing captive siloxane supply through backward integration or long-term precursor agreements. Ceramic matrix composite substitution in next-generation aerospace propulsion threatens high-temperature silicone laminate positioning, demanding nano-silica R&D investment to extend performance ceilings. For New Entrants and Emerging Players: Water-based silicone dispersion technologies offer entry wedge into EPA-compliant coating operations serving US automotive and healthcare demand. Target India's CDSCO-harmonized medical textile infrastructure where surgical drape and implantable mesh applications lack qualified domestic suppliers. Lead with ISO 13485 certification pathway as differentiated go-to-market anchor against incumbent generalists. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European coating specialists holding ECHA-ready formulation portfolios but lacking scale to exploit them independently. Long-term viability favors targets with demonstrated dual-jurisdiction certification maintenance and established relationships with German automotive Tier-1 networks. Watch for CDSCO regulatory harmonization completion as inflection signal for Indian medical textile export capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA cyclic siloxane elimination secures European market access against 2026 enforcement deadlines. |
| Water-Based Coating Capacity | EPA VOC compliance opens automotive and healthcare procurement channels in US Great Lakes manufacturing belt. |
| Dual Certification Investment | Parallel FDA 510(k) and MDR conformity captures hospital procurement consolidation around qualified vendors. |
| Indian Medical Textile Expansion | CDSCO harmonization with ISO 13485 creates export pathway for surgical drape and implantable mesh applications. |
| Nano-Silica R&D Partnership | Aerospace laminate qualification with French and German Tier-1 suppliers defends against ceramic composite substitution. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with coating plant managers, procurement leads at automotive and aerospace OEMs, distribution channel partners, and technical R&D directors with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up capacity and utilization estimates triangulate against top-down demand segmentation derived from end-use industry production forecasts.
Granularity-level framing models product type, application, and end-user dimensions at the country level, with coating technology and certification tier as cross-cutting analytical layers across the projection horizon. CAGRs derive from segment-level volume and value build-ups incorporating electric vehicle production trajectories, aerospace build rates, and hospital procurement upgrade cycles as industry-specific demand drivers.
The model holds under stable regulatory enforcement timelines and continued EV battery thermal protection specification adoption; deviation in REACH substance restriction acceleration or ceramic matrix composite cost reduction would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Blackout Fabric Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Agri Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Construction Textile Market
Technical Textiles
US Geotextile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Waterproof Fabrics Market