
 Road Roller Market | 2026-2036
Road Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Road Roller Market Intelligence
The balance of end-user demand from municipal corporations toward large civil contractors is shifting the market's sales cycle and service requirements. Caterpillar leverages its extensive global dealer network to support this transition with comprehensive service packages. Meanwhile, Sany Group competes aggressively on price and lead times in key emerging economies. Ammann Group differentiates through its specialization in advanced compaction technologies for niche applications like dam construction.
A road roller is a heavy construction vehicle used to compact soil, gravel, or asphalt during the construction of roads and foundations. These machines apply force through a heavy cylindrical drum, with vibratory models using frequencies up to 4,000 vpm to achieve specified material density. Tandem drum rollers dominate the road construction application due to their efficiency on large asphalt surfaces. In contrast, pneumatic tire rollers are essential for sealing and finishing applications, often supporting higher margins for manufacturers.
Engine emission mandates, including the US EPA's Tier 4 Final and Europe's Stage V regulations, directly influence powertrain design and add cost complexity. Concurrently, operator safety rules governed by bodies like OSHA in the United States and through CE marking in the EU drive the integration of features like rollover protective structures. Decisions on electrifying smaller single drum models versus developing alternative fuel solutions for heavy tandem units will define future product leadership.
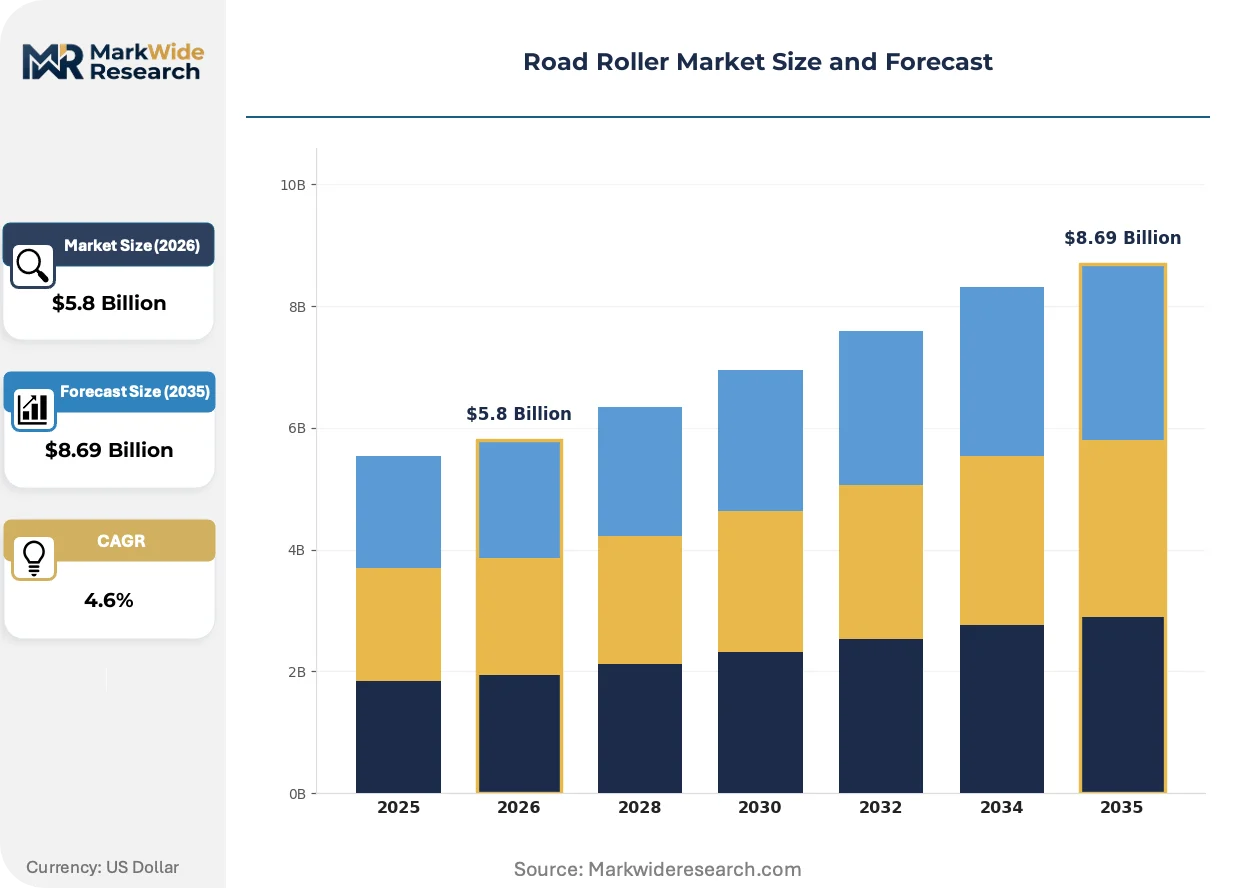
Market Dynamics
The road roller market's evolution is defined by the convergence of stringent powertrain emission mandates and the integration of intelligent compaction technologies. This dual pressure forces simultaneous R&D investment in both engine after-treatment systems and onboard digital monitoring platforms.
Growth Catalysts
- Infrastructure Programs:Large-scale public works, particularly new highway and airport projects in nations like India and Brazil, provide a consistent and large-volume demand source for new compaction equipment.
- Intelligent Compaction Specifications:An increasing number of transportation authorities now mandate the use of intelligent compaction systems for quality control on federal projects, directly pulling advanced technology into the mainstream.
- Niche Applications:Specialized construction projects, such as dam and reservoir foundations, require rollers with unique compaction capabilities, creating high-margin opportunities for manufacturers with specialized engineering expertise.
Market Restraints
- Engine Compliance Costs:Meeting stringent powertrain regulations like the US EPA's Tier 4 Final and Europe's Stage V adds significant cost and complexity through required after-treatment systems.
- High Capital Expenditure:The substantial upfront purchase price of heavy tandem drum and pneumatic tire rollers represents a significant financial barrier for smaller contractors, limiting their ability to expand fleets.
- Raw Material Price Volatility:Fluctuations in the global price of steel, the primary component for roller drums and frames, directly impact manufacturing costs and create margin pressure for equipment producers.
Strategic Opportunities
- Electrification of Compact Rollers:Developing battery-electric single drum models for use in urban environments and noise-sensitive areas opens a new product category aligned with municipal sustainability goals.
- Rental Fleet Development:Establishing robust rental channels in underpenetrated construction markets, such as those in parts of Africa, offers a path to market entry that bypasses high initial purchase costs for end-users.
- Alternative Fuel Powertrains:Investing in research for hydrogen or HVO-fueled engines for heavy tandem rollers provides a long-term solution to navigate future diesel restrictions and decarbonization pressures.
Industry Challenges
- Skilled Operator Scarcity:A shortage of operators trained to effectively use advanced features like intelligent compaction and telematics systems can limit the realization of efficiency gains from new technology.
- Service Network Complexity:Supporting electronically controlled engines and hydraulic systems in remote job sites requires significant investment in technician training and global parts logistics, challenging service scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Roller Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Drum, Tandem Drum, Pneumatic Tire, Combination Roller Technology: Vibratory, Static, Hydraulic, Pneumatic Application: Road Construction, Airport Runways, Sports Grounds, Dams End User: Construction Companies, Civil Contractors, Road Maintenance Agencies, Municipal Corporations |
| Companies Covered | Volvo Construction Equipment, Sany Group, Caterpillar, Hamm, Ammann Group, Bomag GmbH, XCMG Group, Sakai Heavy Industries, Dynapac AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Roller Market Strategic Shifts & Innovations
The market is defined by a fundamental pivot towards digitalization for enhancing job site efficiency and a concurrent push for powertrain decarbonization. This dynamic compels manufacturers to innovate on both the software controlling the machine and the hardware propelling it.
Onboard telematics and intelligent compaction systems provide operators with real-time data on material density, temperature, and pass counts. Large civil contractors adopt these systems on major infrastructure projects to meet strict quality assurance specifications. This technology is decentralizing quality control from delayed, post-compaction analysis to immediate, operator-led adjustments on the machine itself.
Regulations such as Europe's Stage V and the US EPA's Tier 4 Final emission standards are a primary force in product design. These rules necessitate the integration of complex after-treatment technologies like diesel particulate filters and selective catalytic reduction into powertrains. Heavy tandem drum rollers are most impacted by these changes, pushing manufacturers to accelerate development of alternative fuel solutions and electrified components.
A clear behavioral shift involves end-users favoring long-term rental and leasing agreements over direct equipment purchases. This trend disrupts the traditional dealer sales model, with large rental corporations and direct-from-manufacturer fleet services gaining prominence. The shift is most visible in the mature construction markets of North America and Europe, where contractors prioritize operational flexibility and reduced capital outlay.
Road Roller Market Segmentation
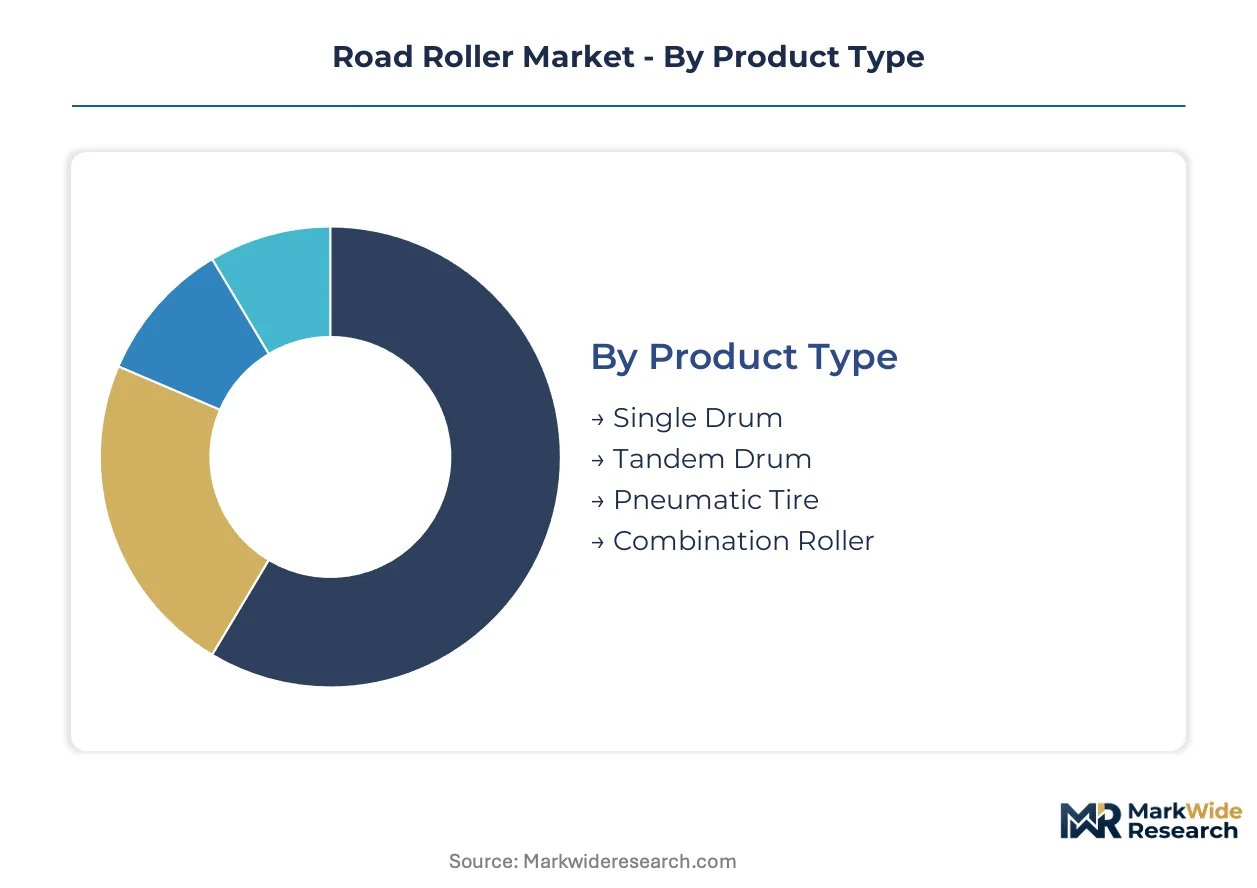
Understanding the distinct segments within the road roller market is crucial for manufacturers to align their product development and service offerings with specific end-user requirements. This segmentation reveals varied demands across equipment types, technological preferences, operational applications, and customer profiles. Each category reflects unique purchasing criteria and operational priorities for compaction equipment.
Product Type:
The customization-vs-standardization spectrum significantly influences product type offerings, with specialized rollers designed for niche applications alongside high-volume general-purpose machines.
- Single Drum:These rollers feature one large compaction drum at the front and rubber tires at the rear, primarily used for compacting soil, gravel, and sub-bases in foundational work.
- Tandem Drum:These rollers feature two drums, one at the front and one at the rear, primarily used for compacting asphalt layers on large road surfaces. Demand concentrates on new highway construction projects in India and Brazil, driven by extensive infrastructure development programs.
- Pneumatic Tire:Characterized by multiple rubber tires, these rollers achieve a kneading and sealing effect on asphalt and granular bases, critical for finishing work. Manufacturers often realize higher margins from these specialized units due to their essential role in final surface quality.
- Combination Roller:These units combine a steel drum at the front with pneumatic tires at the rear, offering versatility for both initial compaction and finishing tasks.
Leading the category by volume: Tandem Drum. Growing fastest: Pneumatic Tire.
Technology:
The functional capabilities defining compaction methods differentiate the technology segment, ranging from simple static pressure to advanced vibratory and hydraulic systems.
- Vibratory:These rollers use a vibrating drum to generate dynamic force, allowing for more efficient compaction of various materials, including soil, aggregate, and asphalt. Large civil contractors increasingly specify vibratory models for federal projects to meet stringent density requirements.
- Static:Static rollers rely solely on the weight of the machine and its drums to achieve compaction, commonly used for finishing surfaces where vibration is undesirable.
- Hydraulic:This technology refers to rollers employing hydraulic systems for steering, braking, and drum vibration, offering precise control and enhanced operational efficiency. Manufacturers integrate advanced hydraulic components to improve machine responsiveness and reduce maintenance needs.
- Pneumatic:This technology, often seen in pneumatic tire rollers, utilizes the kneading action of rubber tires and variable tire pressures to compact and seal asphalt or granular layers.
Vibratory technology drives efficiency, while hydraulic systems enhance control and precision.
Application:
Demand patterns across various construction projects shape the application landscape, from large-scale infrastructure to specialized compacting tasks.
- Road Construction:This segment encompasses the compaction of sub-bases, bases, and asphalt layers for new highways, urban roads, and rural pathways. Infrastructure investment programs in nations like India and Brazil create substantial demand for tandem drum and pneumatic tire rollers.
- Airport Runways:Specialized rollers are required for the precise compaction of airport runways, demanding high-quality surfaces capable of withstanding heavy aircraft loads. Large-scale airport expansion projects globally provide a significant market for advanced compaction equipment.
- Sports Grounds:Rollers in this application compact soil and turf for athletic fields, golf courses, and other recreational areas, often requiring lighter, more maneuverable equipment.
- Dams:Compaction equipment for dam construction involves heavy-duty rollers capable of compacting large volumes of earth and rockfill to ensure structural integrity and stability.
Road construction forms the largest segment, with airport runway projects requiring specialized equipment.
End User:
The scale and operational models of end-user organizations delineate this segment, influencing equipment size, technology adoption, and service needs.
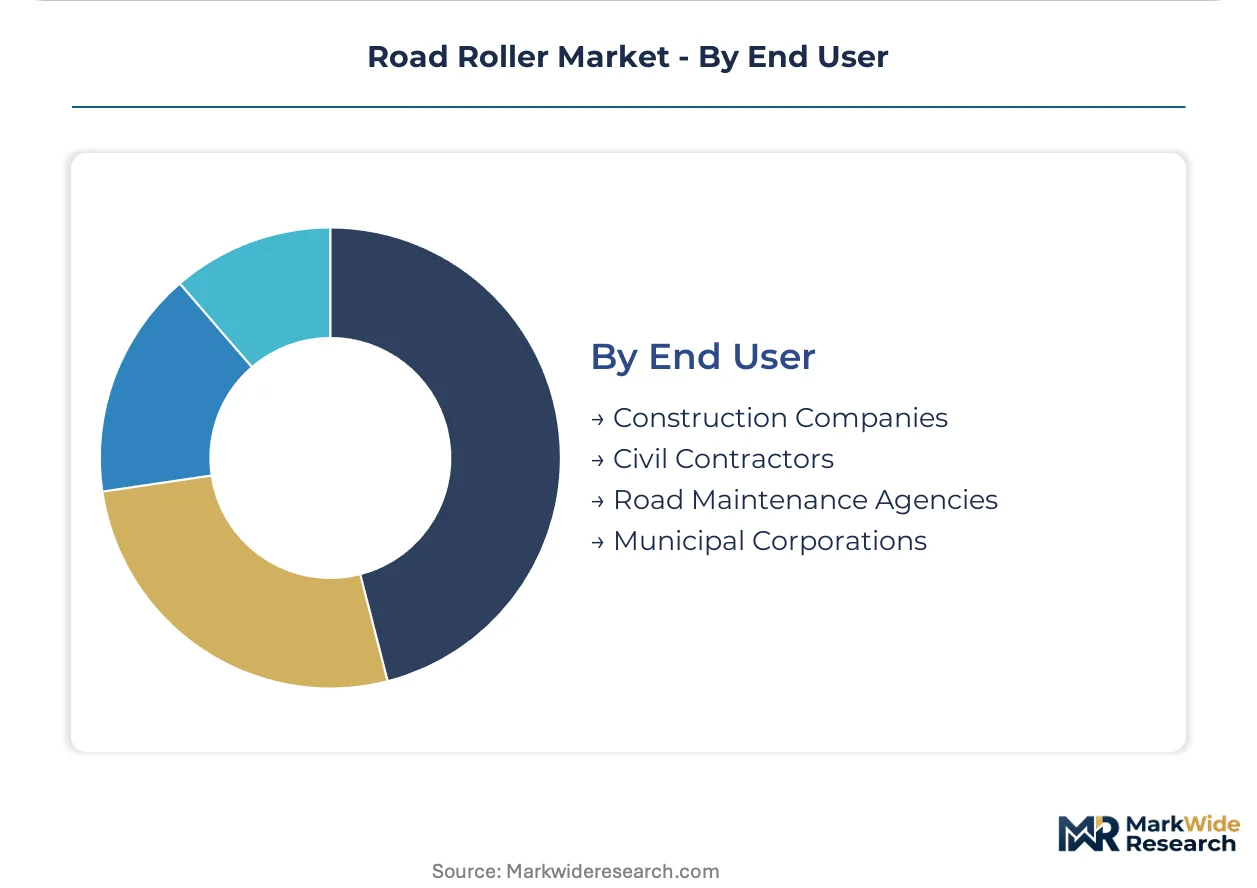
- Construction Companies:General construction firms utilize road rollers for various building foundations, commercial developments, and smaller-scale infrastructure work. They prioritize versatile equipment that can handle diverse material types and job site conditions.
- Civil Contractors:These entities undertake large-scale infrastructure projects, including highways, bridges, and airport runways, requiring extensive fleets of heavy-duty road rollers. Their demand often includes intelligent compaction systems to meet project specifications and quality control mandates.
- Road Maintenance Agencies:These government or private entities use rollers for repairing existing roads, patching potholes, and maintaining road networks, often requiring smaller, agile equipment.
- Municipal Corporations:Local government bodies procure road rollers for urban road construction, maintenance, and public works projects within city limits, increasingly favoring quieter, lower-emission models.
Civil contractors represent the largest demand pool, with municipal corporations expanding their equipment needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure development zones in emerging economies like India and Brazil concentrate significant demand for road rollers. These regions benefit from government initiatives prioritizing connectivity and urban expansion. Such focused investment creates localized hubs of equipment procurement and service.
India
India's extensive highway network expansion and airport upgrades drive substantial demand for tandem drum rollers. The government's Production Linked Incentive (PLI) scheme encourages domestic manufacturing of heavy construction equipment. Infrastructure projects around the Delhi-NCR region consistently require advanced compaction technologies.
Brazil
Brazil's national infrastructure programs, particularly new road construction, create a consistent market for compaction equipment. Government commitments to improve logistics networks support the procurement of heavy-duty road rollers. The São Paulo metropolitan area sees ongoing demand for specialized equipment in urban development projects.
United States
US federal projects and airport runway construction require advanced road rollers meeting stringent quality controls. The US EPA's Tier 4 Final emission standards directly influence powertrain design for all new equipment. Construction hubs in Texas and California drive significant equipment upgrades for large civil contractors.
Germany
Germany's focus on maintaining its high-quality road network and urban infrastructure sustains demand for efficient rollers. Europe's Stage V emission regulations necessitate significant R&D investment in engine after-treatment systems. Manufacturers in Bavaria concentrate on developing specialized compaction technologies for niche applications.
China
China's vast Belt and Road Initiative and ongoing domestic infrastructure projects generate immense demand for all roller types. The Ministry of Ecology and Environment (MEE) mandates stricter emission controls for construction machinery. Manufacturing clusters in the Yangtze River Delta actively produce a wide range of road rollers for domestic and export markets.
Road Roller Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the road roller market. The market exhibits a tiered structure, with a few global leaders dominating the heavy-duty segment and numerous regional players serving compact equipment needs. Strategic archetypes include integrated original equipment manufacturers (OEMs), niche technology providers, and value-focused assemblers. Dominant competitive moves involve geographic expansion into emerging economies and continuous investment in intelligent compaction technologies.
On the global scale vector, Caterpillar, a US-based corporation, exemplifies a comprehensive portfolio approach with extensive dealer networks and robust service packages that support diverse end-user demands. Sany Group, a Chinese heavy equipment manufacturer, represents an archetype focused on aggressive pricing strategies and rapid lead times in key emerging markets, particularly across Asia, Africa, and Latin America. Ammann Group, a Swiss-based specialist, anchors the niche technology segment, consistently differentiating through advanced compaction solutions for specialized applications like dam construction, often supporting higher margins for its products.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| Sany Group |
| Caterpillar |
| Hamm |
| Ammann Group |
| Bomag GmbH |
| XCMG Group |
| Sakai Heavy Industries |
| Dynapac AB |
| Others |
Cost & Logistics Intelligence
Vertical integration into key component manufacturing anchors pricing stability for large road roller OEMs, mitigating raw material volatility and securing supply for complex powertrains.
Pricing Analysis
Short lead times command a premium in road roller procurement, especially for urgent infrastructure projects. Per-unit transactional pricing dominates, with after-sales service and brand premium differentiating offerings. Pricing pressure stems from aggressive competition by Sany Group in emerging economies. Smaller contractors exhibit higher price sensitivity compared to large civil contractors focused on project specifications.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke logistics models underpin the road roller supply chain, ensuring timely equipment delivery and spare parts availability. Geographic supply concentrates in China for components, Germany for specialized technology, and the US for advanced powertrains. Raw material price volatility for steel and hydraulic components represents a structural risk. Distribution runs through extensive global dealer networks and direct-from-manufacturer fleet services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The road roller market operates under supply constraints, with specialized engine after-treatment system production representing a critical capacity bottleneck that props equipment pricing.
For Market Incumbents: Cement market leadership by accelerating alternative fuel powertrain development for heavy tandem rollers. Invest in advanced compaction technologies to counter aggressive pricing from Sany Group. Expand global service networks to support complex electronically controlled systems, mitigating the threat of skilled operator scarcity.
For New Entrants and Emerging Players: Europe's Stage V emission regulations in the EU opens a window for specialized manufacturers focusing on electric single drum rollers. Target urban environments and noise-sensitive areas, which represent a penetrable segment for quieter, lower-emission models. A direct-to-municipalities go-to-market angle emphasizes sustainability goals.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers and regional rental fleet aggregators within the road roller market. Long-term viability remains strong over the next decade, driven by global infrastructure development. Monitor the uptake rate of intelligent compaction mandates in new geographies as an inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification of Compact Rollers | Aligns with municipal sustainability goals, expanding product categories for urban environments. |
| Investment in Hydrogen/HVO Powertrains | Provides a long-term solution to navigate future diesel restrictions for heavy tandem units. |
| Expansion of Rental Fleet Services | Offers market entry in underpenetrated regions, bypassing high initial purchase costs for end-users. |
| Integration of Intelligent Compaction | Meets increasing mandates from transportation authorities for quality control on federal projects. |
| Strengthening Global Dealer Networks | Supports the transition in end-user demand from municipal corporations to large civil contractors. |
Research Approach
Government infrastructure reports from India and Brazil, EPA and Stage V regulatory documents, and construction equipment manufacturer annual reports formed the secondary backbone of this analysis. Primary interviews included civil contractor project managers, equipment rental company executives, OEM R&D leads, and municipal procurement officers. This approach combined bottom-up estimations with top-down validation.
A bottom-up analytical lens estimated market volumes by product type and application, validated by top-down assessments of overall infrastructure spending. Segmentation dimensions included product type, technology, application, end-user, and regional infrastructure spend. CAGRs were derived from historical growth rates and projected infrastructure investment across the analysis window. Road construction project pipelines provided key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hydrogen or HVO-fueled engines would alter the outlook for heavy tandem rollers. Forecasts reflect assumptions concerning raw material price stability and regional infrastructure policy. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Shield Machines Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Crane Rail Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Backhoes Market
Construction Equipment
Static Crane Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market