
 Global Confectionery Market | 2026-2036
Global Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Confectionery Market Analysis
India is rewriting the competitive map for confectionery with new manufacturing investments targeting domestic and regional export demand. Mars, Inc. leverages its vertically integrated cocoa supply chain to secure raw material consistency across volatile commodity cycles. Mondelēz International sustains dominant shelf presence through deep distribution partnerships with modern trade and traditional kirana networks. Ferrero Group differentiates via premium gifting formats that command disproportionate margin pools in festive-season purchasing.
Confectionery comprises sugar-based or chocolate-based food products formulated with cocoa mass, cocoa butter, sweeteners, emulsifiers, and flavoring agents, manufactured through conching, tempering, molding, or depositing processes for indulgent consumption. Chocolate commands the largest value share due to cocoa butter's structural role in texture engineering and consumer willingness to pay for bean-origin provenance. Gummies represent the fastest-expanding product type as gelatin-free pectin formulations attract flexitarian and halal-certified demand pools. Specialty Stores within the distribution channel capture outsized margins through experiential retail and limited-edition collaborations that build brand equity beyond transactional pricing.
FDA nutrition-labeling requirements and EU F-Gas Regulation compliance for industrial cooling systems impose capital costs that favor scaled producers with dedicated regulatory affairs teams. India's FSSAI progressive enforcement of contaminant limits and front-of-pack labeling accelerates consolidation among unorganized sector manufacturers unable to fund laboratory testing infrastructure. Stakeholders must monitor evolving sugar-tax proposals across state-level jurisdictions and calibrate portfolio architecture between permissive and restrictive regulatory environments.
Market Dynamics
EU Green Deal sugar-reduction mandates and F-Gas Regulation compliance costs are bifurcating the competitive landscape between scaled multinationals with dedicated regulatory infrastructure and unorganized producers facing consolidation pressure.
Growth Catalysts
- India's Premium Chocolate Surge:Rising disposable incomes among youthful demographics in Mumbai, Delhi, and Bangalore drive demand for bean-origin provenance products. Domestic manufacturing investments target both local consumption and regional export channels.
- EU Green Deal Formulation Mandates:Sugar-reduction frameworks reshape export-oriented producer requirements, accelerating clean-label R&D spending across cocoa processing operations.
- Halal-Certified Pectin Gummies:Gelatin-free formulations capture flexitarian demand pools in Indonesia, Malaysia, and Middle Eastern markets previously underserved by conventional confectionery.
Market Restraints
- Cocoa Butter Price Volatility:West African supply concentration exposes margins to weather-driven commodity swings and port logistics disruptions.
- Industrial Cooling Compliance:EU F-Gas Regulation imposes capital costs for refrigeration retrofits that favor producers with dedicated regulatory affairs teams.
- Front-of-Pack Labeling Friction:India's FSSAI enforcement of contaminant limits and warning labels accelerates unorganized sector exits.
Strategic Opportunities
- Vietnam and Philippines Penetration:Underdeveloped modern trade infrastructure in secondary cities creates first-mover shelf space for premium gifting formats.
- Experiential Specialty Retail:Limited-edition collaborations and bean-to-bar tasting rooms build brand equity beyond transactional pricing in Tokyo, Seoul, and Singapore.
- Dual Carbon Alignment:China's SAMR carbon-neutral manufacturing incentives reward renewable energy adoption in cocoa processing facilities.
Industry Challenges
- Conching and Tempering Skill Scarcity:Artisan chocolate production requires specialized technicians rarely trained outside European or Japanese technical institutes.
- Laboratory Testing Infrastructure:India's FSSAI contaminant limits demand capital equipment that unorganized manufacturers cannot fund, forcing exit or acquisition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Confectionery Market |
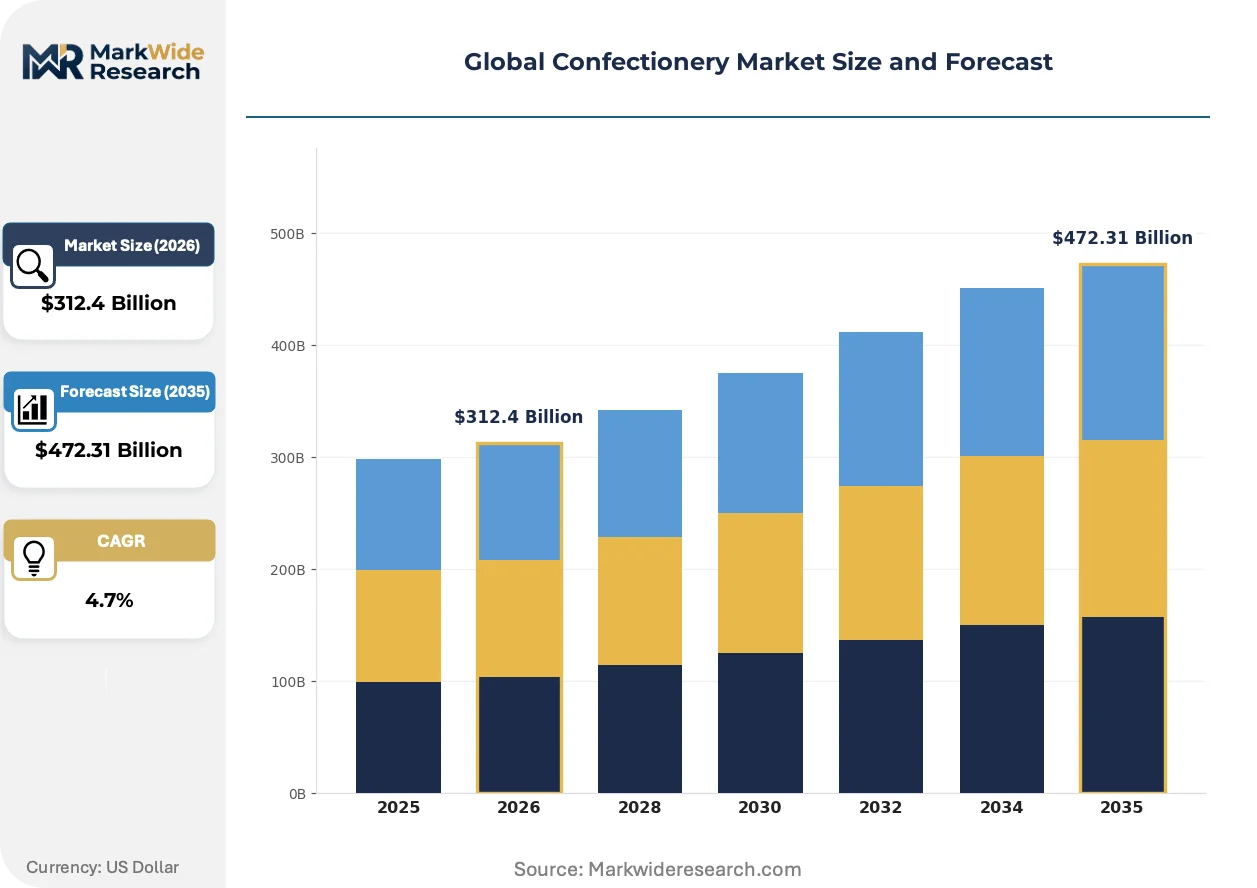
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candy, Chewing Gum Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Kids, Teens, Adults, Seniors Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Mars, Inc., Mondelēz International, Inc., Ferrero Group, Nestlé S.A., The Hershey Company, Lindt & Sprüngli, Meiji Holdings Co., Ltd., Barry Callebaut, Ezaki Glico Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Confectionery Market Emerging Trajectories
Confectionery innovation clusters around clean-label formulation, regulatory compliance automation, and channel experience design that transcends commodity pricing.
Pectin-based gelling systems are migrating from niche dietary products to mainstream gummy manufacturing as halal certification requirements expand across Southeast Asian and Middle Eastern markets. Major producers in Indonesia and Malaysia now specify pectin as the default hydrocolloid, compressing gelatin's historical dominance in volume applications. This shift enables simultaneous access to vegetarian, halal, and kosher certification pools without parallel production lines.
EU F-Gas Regulation Phase-down schedules force industrial cooling system replacements across European chocolate tempering and storage facilities. Manufacturers face compressed timelines for retrofitting refrigeration infrastructure to lower-GWP alternatives, with penalties for non-compliance escalating through 2030. German and Swiss processing plants lead adoption of transcritical CO2 systems, while Italian and Spanish facilities lag due to fragmented ownership structures.
Snacking occasions among remote-working professionals fragment traditional seasonal purchasing patterns. Premium chocolate brands now deploy micro-batch releases through direct-to-consumer channels to maintain engagement outside festive peaks. This behavior shift concentrates in US coastal metros and Northern European capitals where subscription commerce penetration exceeds conventional retail growth rates.
Global Confectionery Market Segmentation
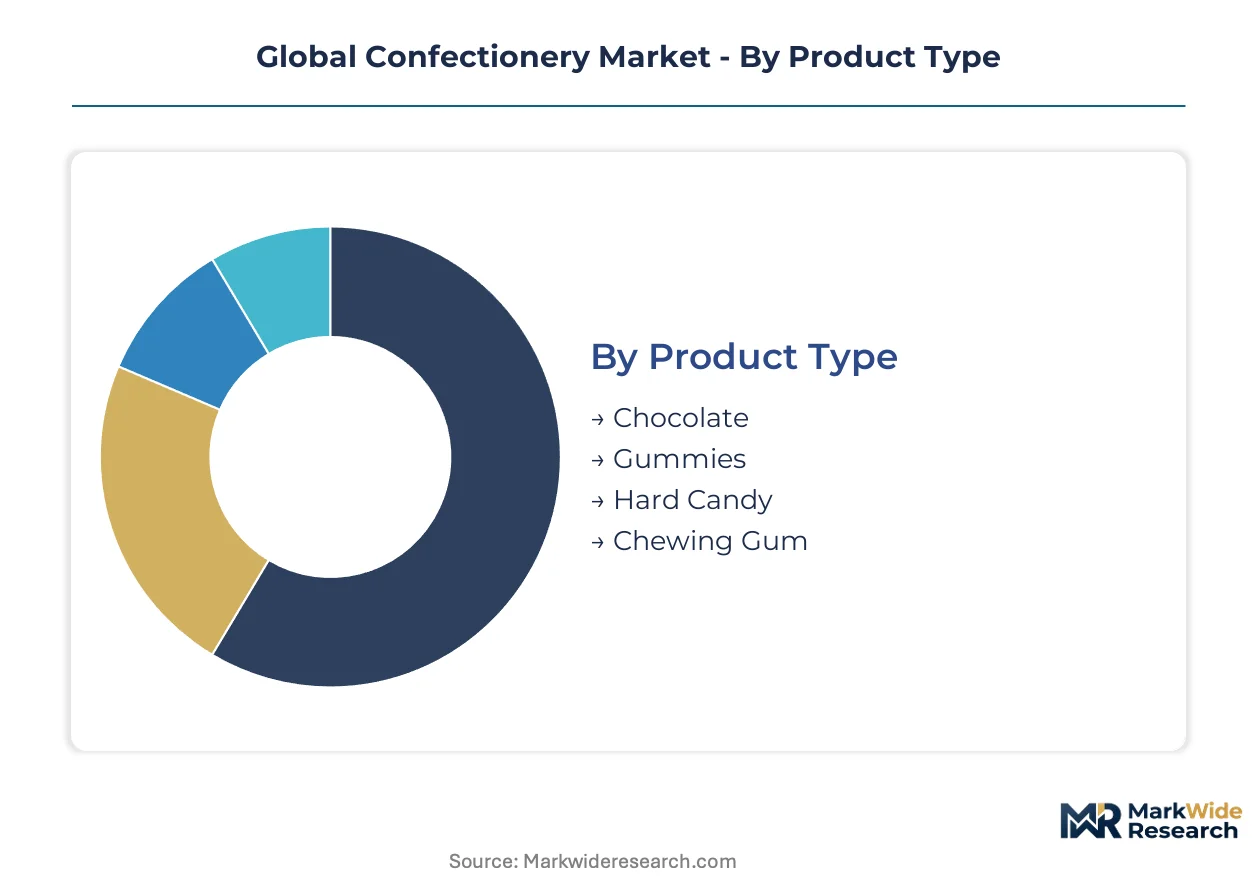
Segmentation in confectionery reveals how formulation complexity, channel economics, and demographic targeting create divergent margin profiles. Product type determines capital intensity in processing equipment, while distribution channel governs working capital cycles and brand control.
Product Type:
Chocolate commands the longest production cycle from bean to finished good, while gummies turn inventory fastest through simplified thermal processing and shorter shelf-life windows.
- Chocolate:Cocoa butter's crystalline structure demands precise tempering and conching protocols that extend manufacturing lead times. Bean-origin provenance commands price premiums in Mumbai, Delhi, and Bangalore where youthful consumers validate authenticity through direct-to-origin narratives.
- Gummies:Pectin-based gelling systems enable rapid batch turnaround and halal certification access across Indonesia, Malaysia, and Middle Eastern markets. Gelatin-free formulations attract flexitarian demand pools previously excluded from conventional confectionery.
- Hard Candy:High-temperature depositing processes yield extended shelf stability and lower per-unit logistics costs for ambient distribution networks.
- Chewing Gum:Polymer base and flavor encapsulation requirements tie manufacturers to specialized extrusion equipment with limited cross-product flexibility.
Chocolate dominates installed base. Gummies are where expansion concentrates.
Distribution Channel:
Channel selection determines margin capture versus volume velocity, with specialty stores extracting maximum value per transaction while supermarkets optimize throughput.
- Specialty Stores:Experiential retail formats in Tokyo, Seoul, and Singapore deploy bean-to-bar tasting rooms and limited-edition collaborations that transcend transactional pricing. High fixed costs per location restrict footprint scalability.
- Supermarkets:Modern trade chains in Vietnam and Philippines secondary cities allocate premium shelf space through slotting fee negotiations that favor scaled producers with dedicated category management teams.
- Convenience Stores:Impulse-driven purchase occasions favor single-serve packaging formats with abbreviated decision windows.
- Online Retail:Direct-to-consumer subscription models fragment traditional seasonal purchasing patterns among remote-working professionals in US coastal metros and Northern European capitals.
Supermarkets anchor volume throughput. Specialty stores concentrate margin expansion.
Customer Type:
Life-stage segmentation aligns formulation intensity with physiological tolerance and discretionary spending authorization.
- Adults:Working professionals drive snacking occasion fragmentation outside traditional festive peaks, validating micro-batch release strategies through digital channels.
- Teens:Social sharing behaviors on visual platforms elevate packaging aesthetics and limited-edition collectibility over intrinsic product attributes.
- Kids:Parental gatekeeping around sugar content and portion control shapes single-serve and reduced-sugar line extensions.
- Seniors:Texture-softening formulations and functional ingredient claims address mastication limitations and health-positioning preferences.
Adults concentrate purchasing frequency. Teens concentrate viral brand amplification.
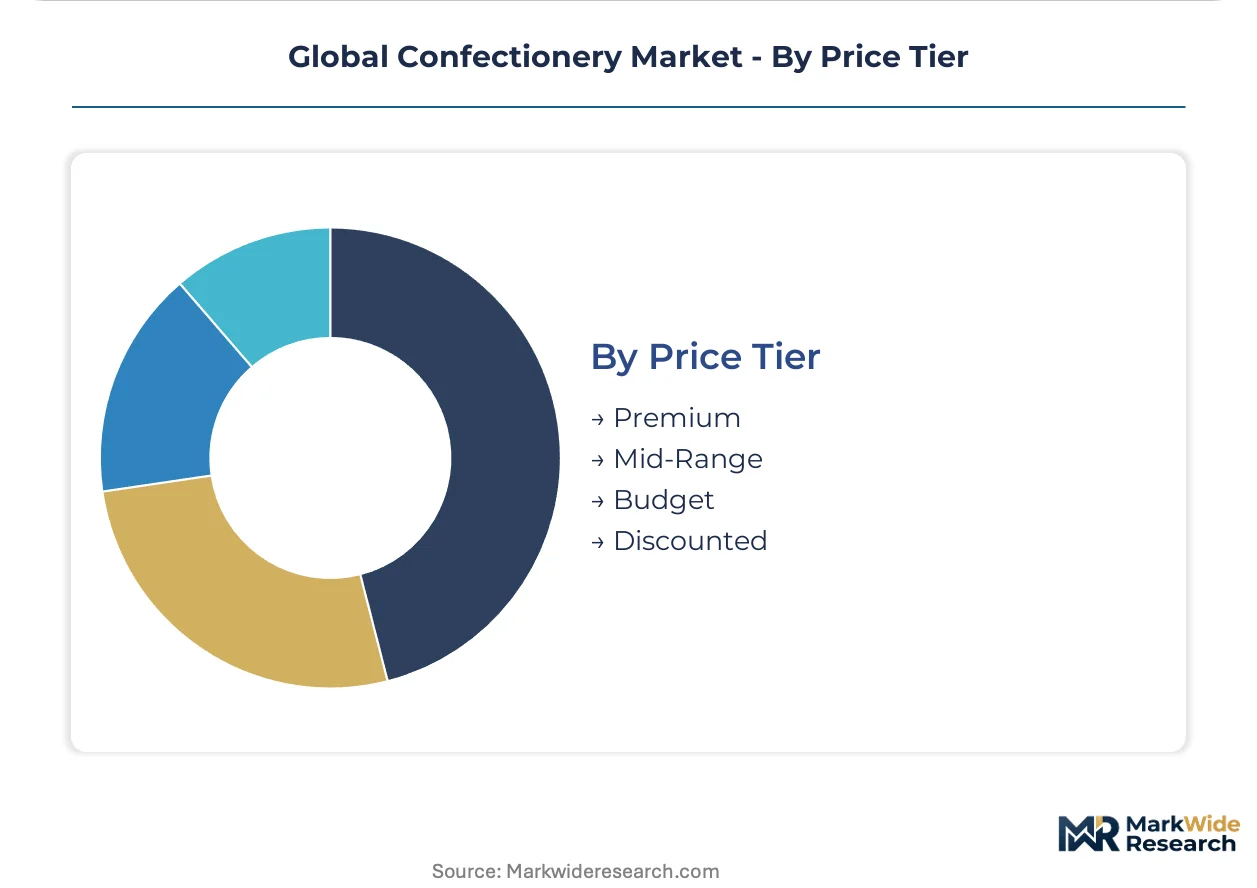
Price Tier:
Pricing stratification separates bean-provenance storytelling from commodity cocoa sourcing, with certification grade and volume scale as primary differentiation levers.
- Premium:Single-origin cocoa mass and artisan conching protocols target gift-giving occasions in India's festive-season purchasing clusters.
- Mid-Range:Balanced cocoa butter ratios and established brand equity capture routine indulgence without origin narrative investment.
- Budget:Compound chocolate formulations with cocoa powder substitution penetrate price-sensitive rural distribution in secondary Indian markets.
- Discounted:Near-expiry clearance and promotional bundling liquidate seasonal overstock through value-oriented channels.
Mid-Range commands transaction volume. Premium captures value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's role as the primary redistribution hub for cocoa butter and chocolate finished goods entering from West African origins.
United States
Remote-working professionals in New York and San Francisco fragment traditional seasonal purchasing through subscription commerce channels. FDA nutrition-labeling requirements impose reformulation costs that favor scaled producers with dedicated regulatory affairs teams. Pennsylvania's chocolate belt concentrates manufacturing heritage and bean-to-bar craft production.
Germany
EU F-Gas Regulation Phase-down schedules force industrial cooling retrofits across chocolate tempering facilities in Cologne and Hamburg. The country's national food safety regulator enforces contaminant limits that accelerate consolidation among mid-tier processors. Bavaria's specialty confectionery clusters lead adoption of transcritical CO2 refrigeration systems.
India
Rising disposable incomes in Mumbai, Delhi, and Bangalore drive premium chocolate demand among youthful demographics. FSSAI progressive enforcement of front-of-pack labeling and contaminant limits forces unorganized sector exits. Maharashtra's domestic manufacturing investments target both local consumption and regional export channels to Southeast Asia and the Middle East.
Indonesia
Halal-certified pectin gummy demand expands across flexitarian consumer pools in Jakarta and Surabaya. The country's national food and drug regulator enforces halal certification requirements that reshape gelling agent specifications. Java's processing facilities migrate from gelatin to pectin as the default hydrocolloid for volume applications.
Japan
Experiential specialty retail in Tokyo and Osaka deploys bean-to-bar tasting rooms and limited-edition collaborations. METI standards for carbon-neutral manufacturing incentives reward renewable energy adoption in cocoa processing. Kansai region's artisan chocolate production requires specialized technicians rarely trained outside domestic technical institutes.
Global Confectionery Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The competitive structure concentrates around vertically integrated cocoa processors and brand-holding multinationals with dedicated regulatory infrastructure. Three archetypes dominate: bean-to-origin storytellers capturing premium gifting occasions, scaled manufacturers optimizing supermarket slotting fees, and pectin-formulation specialists serving halal-certified demand pools. Capacity expansion in Indian domestic manufacturing and M&A targeting unorganized sector exits constitute the dominant competitive moves.
Within the integrated processing tier, Mars, Inc. and Mondelēz International, Inc. occupy positions defined by upstream cocoa supply chain control and deep distribution partnerships respectively. Ferrero Group exemplifies the premium-gifting archetype through festive-season format specialization. These three entities represent contrasting strategic postures: captive raw material security, modern trade and traditional kirana network penetration, and disproportionate margin capture through limited-edition positioning.
| Leading Market Players |
|---|
| Mars, Inc. |
| Mondelēz International, Inc. |
| Ferrero Group |
| Nestlé S.A. |
| The Hershey Company |
| Lindt & Sprüngli |
| Meiji Holdings Co., Ltd. |
| Barry Callebaut |
| Ezaki Glico Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's cold-chain infrastructure connects West African cocoa butter origins to European processing hubs, where freight cost dynamics amplify pricing power for bean-origin storytellers while compressing margins on commodity compound formulations. This corridor's refrigeration-dependent transit economics bifurcate downstream price differentiation between premium provenance claims and budget-tier cocoa powder substitutions.
Pricing Analysis
Volume-discount tiering structures separate procurement contracts for industrial cocoa processors from spot-market purchases by artisan manufacturers. Three-tier pricing stratification across premium single-origin, standard mass-market, and economy compound formulations reflects certification grade and bean-provenance validation costs. Pricing pressure stems from EU F-Gas Regulation compliance capital requirements that favor scaled producers with dedicated regulatory infrastructure. Budget-tier buyers in India's secondary rural markets exhibit highest price sensitivity, while premium gifting purchasers in Mumbai and Delhi validate authenticity premiums with minimal elasticity.
Supply Chain Analysis
Upstream feedstock concentration in Côte d'Ivoire, Ghana, and Ecuador anchors global cocoa butter supply, with West African weather patterns and port logistics disruptions transmitting volatility through futures markets. Cocoa mass, cocoa butter, and sweetener inputs draw from geographically concentrated origins with limited short-term substitution elasticity. Single-source vulnerability runs through Abidjan and San Pedro port chokepoints, where vessel queuing extends lead times unpredictably. Distribution runs through modern trade slotting-fee negotiations in Vietnam and Philippines secondary cities, alongside direct-to-consumer subscription channels fragmenting traditional wholesale structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery platform economics are reshaping around halal-certification interoperability and pectin-formulation standardization across Southeast Asian manufacturing ecosystems, creating new gatekeeper positions for ingredient-technology licensors.
For Market Incumbents: Pre-empt unorganized sector consolidation in India by acquiring FSSAI-compliant laboratory infrastructure before contaminant-limit enforcement accelerates. Backward integration into pectin gelling agent production secures halal-certification supply security against Indonesian and Malaysian regulatory shifts. Channel control through kirana network digitization defends shelf presence against direct-to-consumer subscription encroachment. For New Entrants and Emerging Players: Mid-market pectin gummy production for Middle Eastern export markets represents the most penetrable entry point, with Jakarta and Surabaya processing capacity available for contract manufacturing partnerships. Vietnam's underdeveloped modern trade infrastructure in secondary cities offers first-mover slotting-fee negotiation advantages unavailable in saturated primary metros. A go-to-market angle emphasizing simultaneous vegetarian, halal, and kosher certification without parallel production lines compresses competitor differentiation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from European family-owned chocolate tempering facilities facing EU F-Gas Regulation retrofit capital requirements beyond their balance sheet capacity. Long-term viability over a 5-10 year window favors processors with transcritical CO2 refrigeration adoption completed and bean-to-origin narrative assets already validated in Asian gifting markets. The signal to watch is Maharashtra domestic manufacturing investment announcements targeting regional export channels, indicating consolidation momentum among unorganized Indian producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pectin Production | Secures halal-certification supply autonomy for Indonesian and Malaysian volume applications without gelatin dependency. |
| Direct-to-Consumer Subscription Launch | Captures remote-working professional demand in US coastal metros and Northern European capitals outside festive peaks. |
| Transcritical CO2 Refrigeration Retrofit | Anticipates EU F-Gas Regulation penalties while positioning Bavarian processing plants as carbon-aligned suppliers. |
| Experiential Specialty Retail Expansion | Deploys bean-to-bar tasting rooms in Tokyo and Seoul that transcend transactional pricing through limited-edition collaborations. |
| FSSAI Compliance Laboratory Acquisition | Accelerates unorganized sector consolidation in India by capturing contaminant-testing infrastructure ahead of enforcement tightening. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, FSSAI enforcement circulars, EU regulatory filing databases, and cocoa futures market data. Interviews with chocolate brand managers, modern trade category buyers, cocoa processing plant engineers, and halal certification body technical directors informed demand-side and supply-side validation. Secondary sources include Nielsen retail audit data, SEC 10-K filings of listed confectionery multinationals, and FAO cocoa production statistics. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Forecast inputs incorporate product-type segmentation across chocolate, gummies, hard candy, and chewing gum alongside distribution channel dynamics, customer life-stage targeting, and price-tier positioning. Modeled variables span formulation complexity, certification requirements, and regional regulatory cluster stringency. CAGRs derive from regression analysis against disposable income elasticity and snacking occasion frequency indices. Cocoa butter price volatility bands and EU F-Gas Regulation compliance cost curves inform scenario-weighted projections across the modeling period.
Stress conditions across West African supply disruptions, Indian state-level sugar-tax implementation, and pandemic-era logistics recurrence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timelines and consumer substitution elasticity between premium and economy tiers. Cross-checking against ICCO cocoa production forecasts and regional retail scanner data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Real and Compound Chocolate Market
Confectionery
Buttercream Frosting Market
Confectionery
UK Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Mints Market
Confectionery
Confectionery Fats Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
South Korea Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Cocoa and Chocolate Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Salted Caramel Products Market
Confectionery
Gum Base Candy Market
Confectionery
Licorice Candy Market
Confectionery
Macarons Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market