
 CAM Software Market | 2026-2036
CAM Software Market Size, Share, and Industry Trends Forecast 2026-2036
CAM Software Market Intelligence
The increasing complexity of components in the aerospace and automotive sectors is repositioning the CAM software market toward multi-axis and simulation-heavy solutions. Siemens leverages its extensive industrial automation portfolio to offer integrated hardware and software systems. Autodesk differentiates through its flexible cloud-based platforms and subscription models, appealing to a wide range of users from small businesses to large enterprises. Dassault Systèmes anchors its CAM capabilities within the broader 3DEXPERIENCE platform, promoting a unified product lifecycle management environment.
Computer-Aided Manufacturing (CAM) software translates computer-aided design (CAD) models into machine-readable instructions, commonly known as G-code. Its primary purpose is to automate and optimize the programming of computer numerical control (CNC) machine tools, reducing manual errors and improving production efficiency. While 2D and 3D CAM remain foundational, the multi-axis CAM segment shows significant momentum, driven by the need for five-axis machining. Concurrently, cloud-based and subscription deployment models are gaining share from perpetual on-premise licenses, lowering the barrier to entry for smaller manufacturers.
The market operates within a framework of rigorous quality and safety standards. Adherence to ISO 9001 for quality management systems is a common requirement, while specific sectors impose stricter rules like AS9100 for aerospace, demanding complete part traceability. In Europe, CE marking for machinery safety necessitates robust simulation and verification, functions directly supported by advanced CAM software. Vendor success will depend on balancing the development of highly specialized features for regulated industries with the creation of accessible, scalable solutions for the broader manufacturing base.
Market Dynamics
The integration of digital twin technologies under Industry 4.0 principles is the central force defining the market. This shift is driven by the manufacturing needs for complex geometries in the aerospace and automotive sectors, demanding more sophisticated simulation and optimization capabilities.
Growth Catalysts
- Multi-Axis Adoption:The medical device industry's move toward patient-specific implants and surgical tools requires the precision of 5-axis CAM software to machine complex organic shapes from materials like titanium and PEEK.
- National Initiatives:Government programs, such as Germany's Industry 4.0 platform and China's advanced manufacturing directives, provide incentives and create demand for integrated digital manufacturing solutions, including CAM.
- Aerospace Material Innovation:Demand for lightweighting in aircraft design is pushing the use of composite materials and complex metal alloys, which necessitates advanced CAM strategies for efficient and safe machining.
Market Restraints
- High Implementation Cost:The significant upfront investment in multi-axis CAM software licenses, coupled with the cost of high-performance computing hardware and machine tools, remains a substantial barrier for small and medium-sized enterprises.
- Skilled Labor Scarcity:A persistent shortage of CNC programmers, machinists, and manufacturing engineers with the expertise to effectively operate and optimize advanced CAM systems constrains wider adoption and full utilization.
- Interoperability Hurdles:Lack of seamless data exchange between disparate CAD, CAM, and Product Lifecycle Management (PLM) systems creates workflow inefficiencies and requires costly custom integration, slowing down implementation.
Strategic Opportunities
- Hybrid Manufacturing:The convergence of additive (3D printing) and subtractive (CNC machining) processes creates an opportunity for hybrid CAM software that can program both operations within a single environment for complex part production.
- AI-Powered Optimization:Integrating artificial intelligence and machine learning into CAM platforms to automate toolpath generation, optimize cutting parameters, and predict tool wear offers a significant avenue for improving efficiency and autonomy.
- Geographic Expansion:The expanding industrial manufacturing base in Southeast Asian nations, including Vietnam and Thailand, presents an underpenetrated market for CAM software vendors as local companies upgrade their production capabilities.
Industry Challenges
- Cybersecurity of IP:For cloud-based CAM solutions, protecting sensitive intellectual property, such as proprietary part designs and manufacturing processes, from cyber threats is a critical challenge, especially for defense and aerospace contractors.
- Post-Processor Standardization:The lack of a universal standard for post-processors, which translate neutral CAM data into machine-specific G-code, results in ongoing customization costs and integration friction for end-users with diverse machine fleets.
- Legacy System Integration:Manufacturers face operational difficulties when trying to integrate modern CAM software with older, legacy CNC machines and factory IT infrastructure, often leading to fragmented workflows and data silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CAM Software Market |
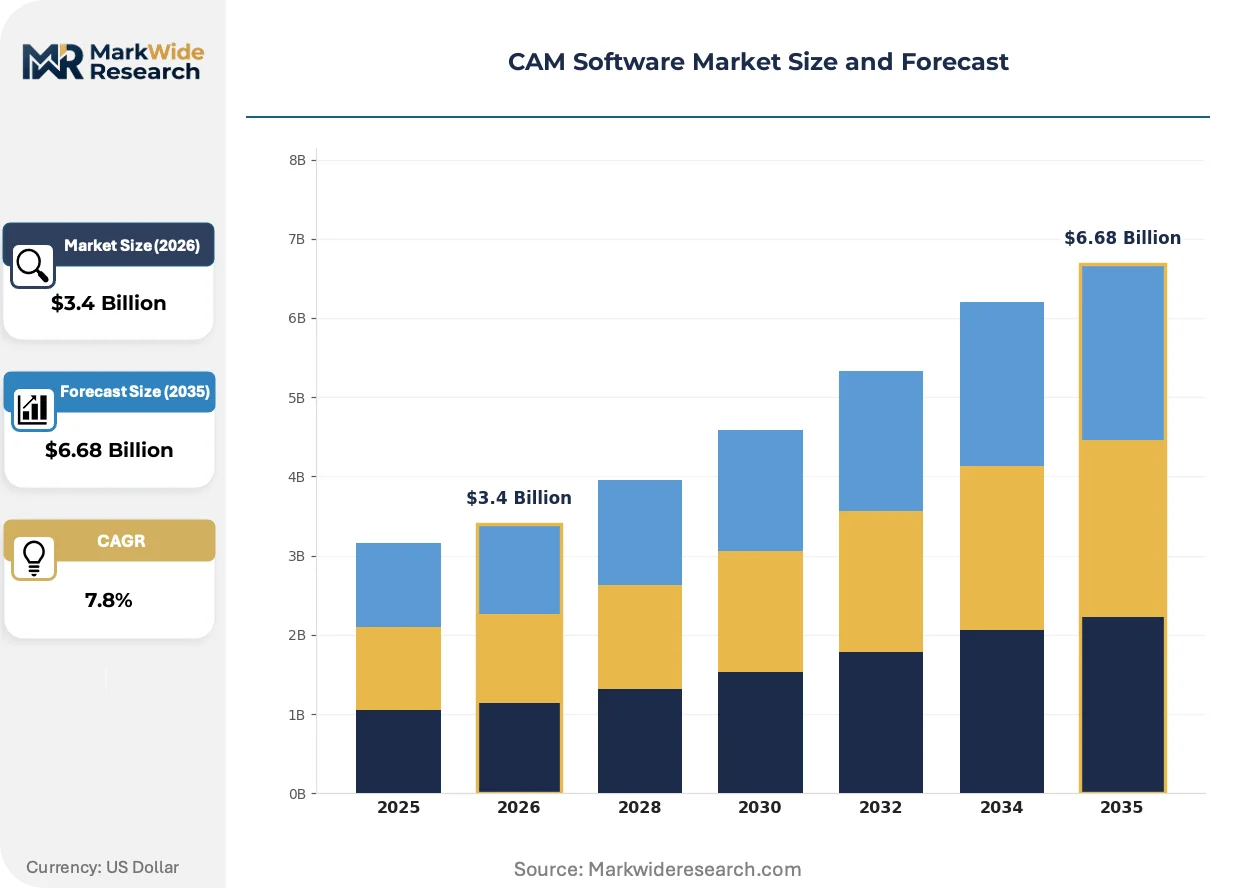
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CAM, 3D CAM, Multi-axis CAM, Software Suite Deployment: On-premise, Cloud-based, Hybrid, Subscription User Type: Manufacturers, Designers, Engineers, Small Businesses Industry Vertical: Aerospace, Automotive, Electronics, Furniture |
| Companies Covered | PTC, Mastercam, Autodesk, Open Mind Technologies, 3D Systems, Siemens, Hexagon, Tebis, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CAM Software Market Strategic Shifts & Innovations
A fundamental shift toward autonomous and data-driven manufacturing is defining the evolution of CAM software. This trend prioritizes the integration of intelligence directly into toolpath generation and process verification, moving beyond simple CAD-to-code translation to create self-optimizing production workflows.
Generative design, an AI-driven process, automatically creates optimized part geometries based on specified constraints like weight, material, and performance. The automotive and aerospace sectors are early adopters, seeking to reduce component mass and material consumption. This AI-powered approach is absorbing traditional iterative design tasks, feeding optimized, manufacturable models directly into the CAM workflow.
European Union regulations, particularly the CE marking for machinery safety, mandate rigorous risk assessment and documented verification. This directive compels manufacturers to use CAM software with robust simulation and collision detection features to prove machine toolpath safety before physical production. The industrial machinery and automation sectors are most affected, embedding verification modules into their standard pre-production processes to ensure compliance.
Subscription-based access models are supplanting perpetual software licenses as the preferred procurement method for many users. This change favors direct-to-customer online platforms and is altering the role of traditional value-added resellers, especially for small businesses. This trend is most prominent in North America and Europe, where manufacturing startups leverage the lower upfront cost to access advanced CAM capabilities.
CAM Software Market Segmentation
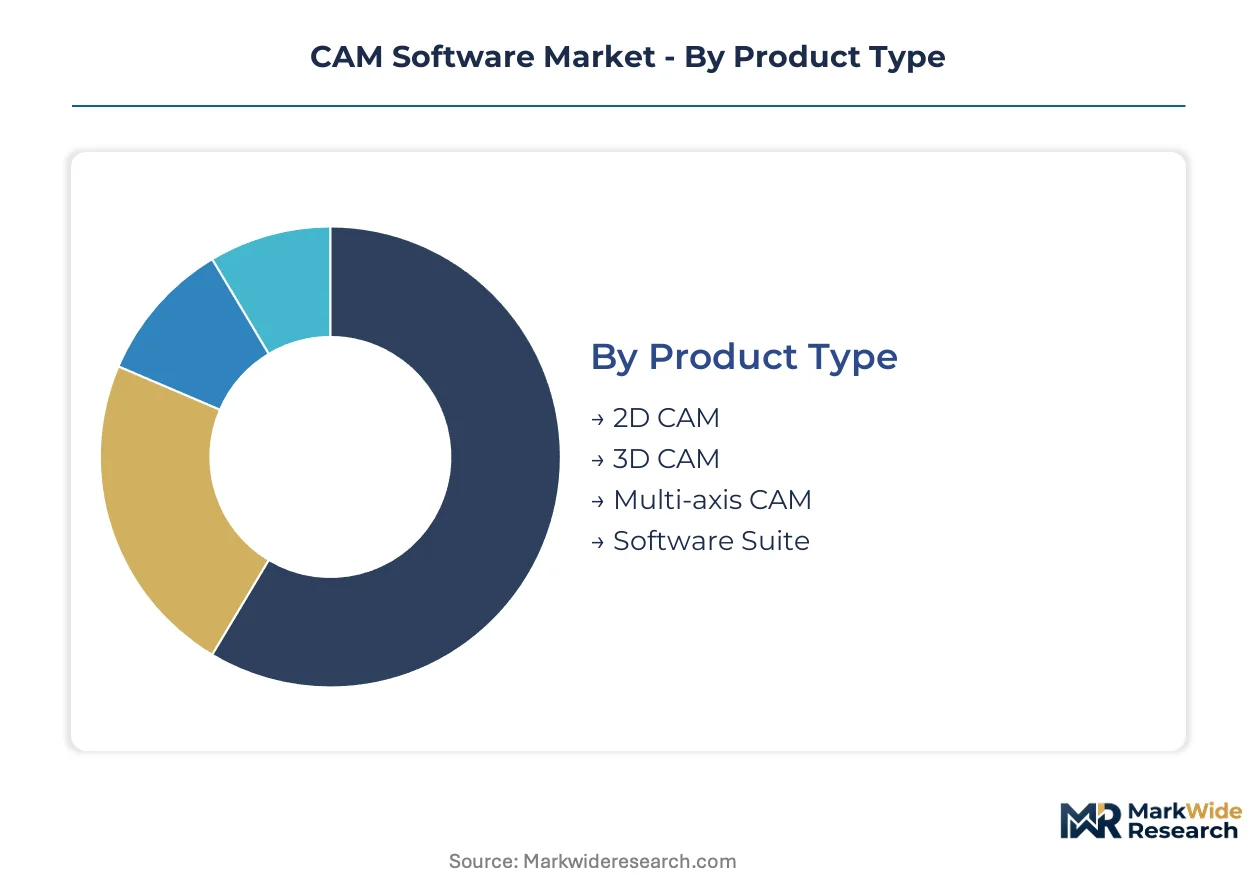
The CAM software market serves diverse manufacturing needs, requiring precise classification of solutions to understand demand patterns and technological evolution. Understanding how different product types, deployment models, user categories, and industry applications interact reveals the market's underlying structure. This segmentation highlights key areas of innovation and competitive focus for vendors.
Product Type:
Buyer sophistication and part complexity differentiate demand across CAM software product types.
- 2D CAM:This segment focuses on flat, two-dimensional geometries for basic machining operations like cutting and drilling.
- 3D CAM:This software handles three-dimensional part models, enabling more complex contouring and surface machining.
- Multi-axis CAM:This advanced software supports machining with four or more axes, crucial for complex, organic shapes common in aerospace and medical devices. Manufacturers in Germany and Japan demand multi-axis CAM for high-precision turbine blades and patient-specific implants.
- Software Suite:These integrated platforms combine CAD, CAM, and sometimes CAE functionalities into a single environment, streamlining the design-to-manufacturing workflow. Large enterprises and those seeking comprehensive product lifecycle management often invest in software suites for efficiency.
Multi-axis CAM leads volumes today; Software Suite is gaining share fastest.
Deployment:
Deployment model preferences vary significantly based on a customer's IT infrastructure and security requirements.
- On-premise:This traditional model involves software installation and management directly on the user's local servers and hardware.
- Cloud-based:This model delivers software functionality over the internet, accessible from any location with an internet connection. Small and medium-sized enterprises in North America increasingly adopt cloud-based CAM for its lower upfront costs and scalability.
- Hybrid:This approach combines elements of both on-premise and cloud deployments, allowing users to leverage the benefits of each.
- Subscription:This licensing model grants software access for a defined period, typically monthly or annually, rather than a one-time perpetual purchase. European startups favor subscription models for predictable budgeting and access to continuous updates.
On-premise deployment still holds significant volume; cloud-based solutions are expanding most quickly.
User Type:
The operational roles and organizational scale of users determine the specific CAM software features prioritized.
- Manufacturers:This segment includes production facilities and large enterprises that utilize CAM software for high-volume or complex component fabrication. Automotive and aerospace manufacturers require robust integration with PLM systems for end-to-end process control.
- Designers:These professionals typically use CAM for design verification, manufacturability analysis, and rapid prototyping before full production.
- Engineers:This group employs CAM for process planning, toolpath optimization, and simulation to ensure manufacturing efficiency and quality.
- Small Businesses:This segment comprises job shops and independent contractors seeking cost-effective, user-friendly CAM solutions with flexible licensing. Startups in Southeast Asia are increasingly adopting accessible CAM platforms to enhance their production capabilities.
Manufacturers currently represent the largest user base; small businesses show the steepest expansion trajectory.
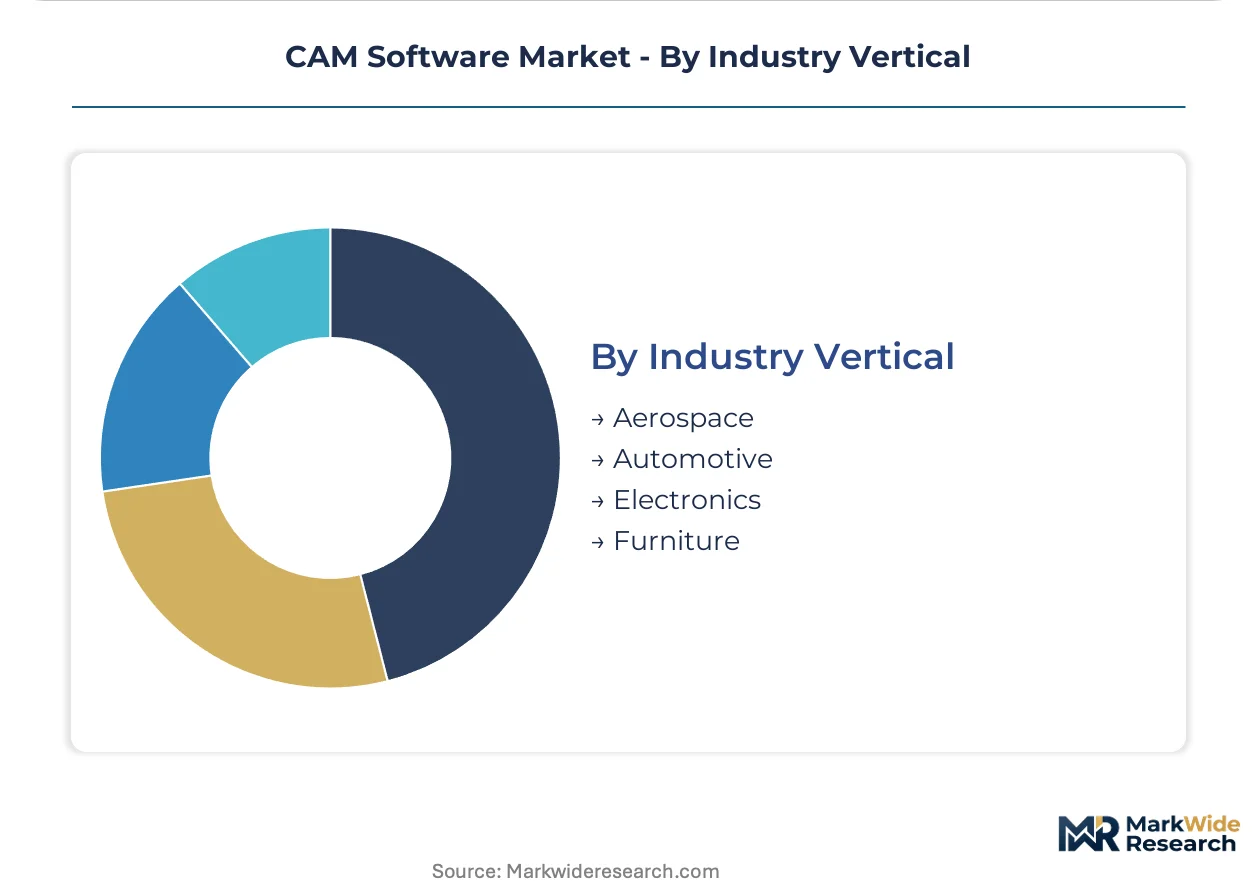
Industry Vertical:
The specialized production requirements and regulatory frameworks of each industry vertical shape its CAM software needs.
- Aerospace:This sector requires CAM software capable of machining high-performance alloys and composites with extreme precision and traceability for critical aircraft components. Demand in the US and Europe focuses on solutions supporting advanced materials and stringent AS9100 standards.
- Automotive:This industry uses CAM for high-volume production of engine parts, body panels, and tooling, prioritizing speed, efficiency, and surface finish. German automotive engineering firms drive demand for CAM solutions integrated with advanced automation systems.
- Electronics:This vertical employs CAM software for manufacturing intricate molds, circuit board components, and specialized tooling.
- Furniture:This sector utilizes CAM for efficient cutting, shaping, and assembly of wood and composite materials for various furniture designs.
Aerospace and Automotive verticals dominate current demand; Electronics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global CAM software market exhibits regional shifts where varying regulatory burdens and economic incentives influence manufacturing investment. Production of complex components gravitates towards regions with supportive industrial policies. This dynamic shapes the geographic distribution of advanced CAM software adoption.
Germany
German manufacturing drives demand for CAM software, particularly in automotive engineering and advanced machinery production. Germany's Industry 4.0 platform provides incentives for integrated digital manufacturing solutions. Automotive firms in Baden-Württemberg utilize advanced CAM for high-precision tooling and engine components.
United States
United States aerospace and defense sectors fuel demand for highly specialized CAM software, especially for high-performance alloys. Adherence to AS9100 standards necessitates CAM solutions with robust traceability and verification capabilities. Manufacturers in Wichita employ advanced CAM for precision machining of complex airframe structures.
China
China's ambitious advanced manufacturing directives are accelerating CAM software adoption across diverse industrial sectors. Government programs encourage domestic enterprises to upgrade production capabilities with sophisticated digital tools. Manufacturers in Shenzhen leverage CAM for intricate mold making and high-volume electronics component fabrication.
Japan
Japanese manufacturers prioritize CAM software for ultra-high precision machining and integration with advanced robotics. METI initiatives encourage digital transformation across the manufacturing base, fostering CAM adoption. Precision engineering firms in the Chubu region deploy sophisticated CAM for demanding applications like patient-specific implants.
Vietnam
Vietnamese manufacturing expansion creates significant opportunities for accessible CAM software solutions among local enterprises. Government investment incentives attract foreign manufacturers, driving demand for modern production technologies. Industrial parks in Binh Duong Province increasingly utilize CAM for efficient fabrication of components for export markets.
CAM Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with larger enterprises favoring integrated platforms. The CAM software market exhibits a tiered structure, from comprehensive solution providers to niche application specialists. Strategic archetypes include established CAD/CAM suite vendors, independent CAM software developers, and emerging cloud-based innovators. Companies pursue portfolio diversification and strategic partnerships to broaden their market reach and integrate new technologies.
Within the integrated software suite archetype, Siemens represents a major player leveraging its extensive industrial automation portfolio to offer combined hardware and software systems. The German-based company focuses on delivering robust solutions for complex industrial processes. Autodesk exemplifies a leading provider through its flexible cloud-based platforms and subscription models, appealing to a wide range of users from small businesses to large enterprises. Dassault Systèmes, a French multinational, anchors its CAM capabilities within the broader 3DEXPERIENCE platform, promoting a unified product lifecycle management environment. These firms collectively demonstrate the industry's push towards comprehensive, interconnected manufacturing solutions that streamline workflows across the product lifecycle.
| Leading Market Players |
|---|
| PTC |
| Mastercam |
| Autodesk |
| Open Mind Technologies |
| 3D Systems |
| Siemens |
| Hexagon |
| Tebis |
| Dassault Systèmes |
| Others |
Cost & Logistics Intelligence
The integration of digital twin technologies as a production-method transition simultaneously reshapes cost economics and supply concentration within the CAM software market. This shift necessitates higher initial investments in software and hardware, yet it centralizes expertise and reduces long-term operational costs for manufacturers.
Pricing Analysis
Direct-to-customer online platforms reduce traditional distributor margins, impacting overall pricing structures. Subscription models dominate the market, offering tiered access based on feature sets and user count. Price differentiation stems from the level of customization required for specific industry applications and the breadth of after-sales integration support. Pricing pressure stems from the proliferation of accessible cloud-based solutions, driving down entry-level costs. Small businesses exhibit the highest price sensitivity, while large enterprises prioritize comprehensive features and robust support over minimal cost savings.
Supply Chain Analysis
Adherence to rigorous certification standards like AS9100 and CE marking acts as a significant qualification gate for CAM software vendors. The supply of advanced CAM software development expertise concentrates in countries such as Germany, the United States, and Japan. The market relies heavily on specialized software libraries and high-performance computing hardware for simulation capabilities. A structural risk involves the persistent scarcity of skilled manufacturing engineers and CNC programmers capable of optimizing advanced CAM systems. Distribution runs primarily through direct sales channels and specialized value-added resellers, particularly for complex enterprise solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAM software market presents a geographic-arbitrage play, leveraging differences in skilled labor costs and regulatory compliance burdens between established manufacturing hubs and emerging industrial regions.
For Market Incumbents:Cement leadership through continuous innovation in AI-powered optimization and hybrid manufacturing capabilities. Deepen integration with existing PLM systems to offer seamless end-to-end solutions, countering threats from niche cloud-based disruptors. Invest heavily in certification processes, such as AS9100 for aerospace, to maintain a competitive edge in regulated industries. Expand R&D efforts into generative design workflows to capture early-adopter customers in automotive and aerospace.
For New Entrants and Emerging Players:Online subscription platforms and freemium models offer a penetrable entry point into the CAM software market. Target the underserved small and medium-sized enterprise segment in rapidly industrializing Southeast Asian nations, such as Vietnam. Focus on developing user-friendly, accessible CAM solutions that minimize upfront costs and reduce the need for extensive specialized training. Emphasize cloud-based deployment to offer scalability and lower IT infrastructure requirements for local manufacturers.
For Investors and Strategic Acquirers:Valuations sit cheapest among niche CAM specialists focused on specific vertical applications or emerging technologies like AI optimization. Invest in companies developing robust simulation and verification tools, aligning with increasing regulatory demands like Europe's CE marking. The long-term viability of the market is strong, driven by the ongoing Industry 4.0 transformation and demand for complex component manufacturing. A signal to watch is the increased M&A activity involving firms specializing in hybrid additive-subtractive manufacturing software.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate design and manufacturing workflows, enhancing operational efficiency for large enterprises. |
| AI-Powered Optimization | Automates complex toolpath generation, reducing programming time and improving machining outcomes. |
| Geographic Expansion | Accesses new customer bases in industrializing regions, broadening market reach and revenue streams. |
| Acquisition of Specialist Firm | Integrates niche expertise in areas like hybrid manufacturing, accelerating product development cycles. |
| Subscription Model Refinement | Optimizes pricing tiers and feature sets, attracting a wider range of users from startups to large corporations. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for the CAM software market. This involved extensive primary interviews with CAM software engineers, manufacturing executives, CNC programmers, and IT procurement officers. Secondary validation drew from industry association reports, government manufacturing directives like Germany's Industry 4.0, financial filings of public CAM vendors, and academic research on advanced manufacturing technologies.
The input-output matrix frames the analytical framework across the analysis window. Segmentation dimensions modeled include product type, deployment, user type, industry vertical, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trends, projected technological shifts, and macroeconomic indicators. Key industry-specific forecast inputs included manufacturing output indices for aerospace and automotive sectors, alongside global R&D spending in advanced materials.
The model assumes a particular technology adoption path; alternative pathways for AI-driven generative design would alter the outlook. Forecasts reflect assumptions regarding sustained investment in Industry 4.0 initiatives and the availability of skilled labor. A model refresh is warranted upon material change in global manufacturing output or major regulatory shifts affecting aerospace and automotive production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Audit Software Market
Software & Services
Meditation Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Digital Painting Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Automotive Dealership Software Market
Software & Services
Inventory Management Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Policy Management Software Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Global Customer Experience Software Market
Software & Services
Staffing Agency Software Market