
 Global Home Inspection Software Market | 2026-2036
Global Home Inspection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Inspection Software Market Foresight
Certified home inspector workforce shortages across major metros is rotating demand toward software that compresses inspection cycle times and automates compliance documentation. Spectora leverages cloud-native architecture to dominate the mobile reporting segment for residential property analysis. HomeGauge anchors its position through deep integration with multiple listing services and real estate transaction platforms. Inspection Support Network competes by bundling scheduling modules with customer management tools that reduce no-show rates for independent inspectors.
Home inspection software comprises digital platforms that standardize property condition assessment through structured data capture, photographic annotation, and automated report generation compliant with jurisdictional standards. These systems typically operate on iOS and Android tablets with offline synchronization, enabling field inspectors to complete residential property analysis and commercial building assessment without continuous connectivity. Cloud-based deployment leads the solution landscape due to lower upfront capital requirements and automatic regulatory template updates, while mobile applications represent the fastest-expanding segment as inspectors prioritize tablet-native workflows over laptop-dependent tools. Data analytics offerings command premium pricing by converting historical inspection findings into predictive maintenance intelligence for facility managers and insurance underwriters.
FDA guidelines on data integrity for electronic records, ASHI and InterNACHI standards for report content, and state-level licensing boards in Texas, California, and Florida collectively shape product requirements and market access conditions for vendors. The EU AI Act and GDPR frameworks constrain automated defect recognition features in European deployments, compelling region-specific engineering investments. Stakeholders must monitor evolving inspector certification mandates and data portability requirements as jurisdictions digitize building safety oversight.
Market Dynamics
Cloud-native mobile architectures are compressing inspection cycle times while state-level licensing boards mandate digital documentation standards, forcing legacy paper-based workflows into obsolescence across residential and commercial property assessment segments.
Growth Catalysts
- ASHI and InterNACHI Standards:Professional association mandates for standardized report content are compelling inspector adoption of templated digital platforms that automate compliance documentation.
- Tablet-Native Workflows:iOS and Android field applications with offline synchronization are eliminating connectivity dependencies during rural and basement inspections.
- Texas, California, Florida Licensing:State-level inspector certification requirements are tightening across the three largest US housing markets, creating captive demand for regulatory-compliant software.
Market Restraints
- EU AI Act Constraints:Automated defect recognition features face algorithmic transparency requirements that compel region-specific engineering investments and delay product launches.
- GDPR Data Localization:European cloud deployments require sovereign hosting infrastructure that fragments vendor economics and raises operational complexity.
- Inspector Workforce Shortages:Certified professional scarcity across major metros limits addressable user base expansion regardless of software accessibility.
Strategic Opportunities
- Australia Licensing Expansion:Tightening home inspector certification requirements across New South Wales and Victoria are creating first-mover advantages for compliant platform entrants.
- Insurance Underwriter Integration:Predictive maintenance intelligence derived from historical inspection findings opens premium-priced data analytics revenue streams.
- API-First Architecture:Open integration protocols enable embedding within real estate transaction platforms and multiple listing services.
Industry Challenges
- Legacy System Migration:Established inspection firms face workflow disruption costs and staff retraining requirements when transitioning from paper-based processes.
- Jurisdictional Template Fragmentation:State and municipal variation in reporting standards forces vendors to maintain parallel compliance libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Inspection Software Market |
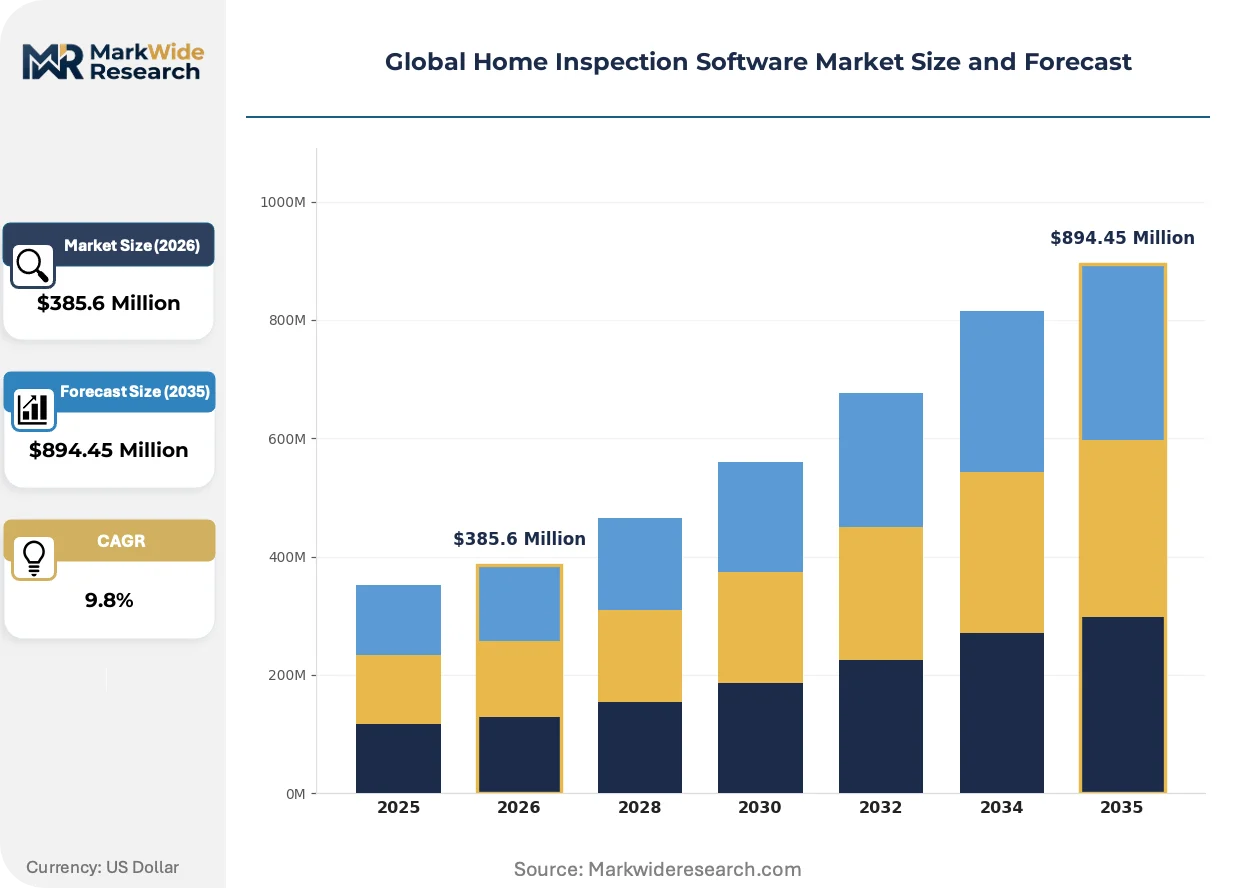
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution/Offering: Reporting Tools, Scheduling Modules, Mobile Applications, Data Analytics, Customer Management Application: Residential Property Analysis, Commercial Building Assessment, Pre-Sale Inspection, Insurance Inspection, Maintenance Check End User: Property Inspectors, Real Estate Agencies, Insurance Firms, Facility Managers, Contractors |
| Companies Covered | Home Inspector Pro, InspectPro, InspectorData, Palm-Tech, Inspection Support Network, Spectora, Inspector Toolbelt, Tap Inspect, HomeGauge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Inspection Software Market Shifts & Advancements
Artificial intelligence and edge computing are restructuring how property defects are detected, documented, and communicated to stakeholders across the transaction chain.
Computer vision algorithms embedded in tablet-native inspection applications are miniaturizing specialized diagnostic equipment by enabling photographic defect recognition for moisture intrusion, thermal bridging, and structural settlement. Residential inspectors in Australia and Canada are deploying these tools during pre-purchase assessments. The technology is compressing equipment capital requirements for independent practitioners while elevating report consistency.
GDPR and the EU AI Act are constraining automated defect classification features in European deployments, compelling vendors to implement human-in-the-loop validation workflows and algorithmic explainability documentation. German and French regulators are enforcing data portability requirements for inspection archives. Commercial building assessors are responding by segmenting product roadmaps between high-autonomy North American releases and compliance-heavy European variants.
Buyer procurement preferences are rotating toward subscription-based platform access with embedded scheduling and customer management modules rather than standalone reporting tools. Independent inspection firms and small multi-inspector practices are consolidating vendor relationships. This consolidation is most visible in the United States and Canada where transaction velocity pressures compress software evaluation cycles.
Global Home Inspection Software Market Segmentation
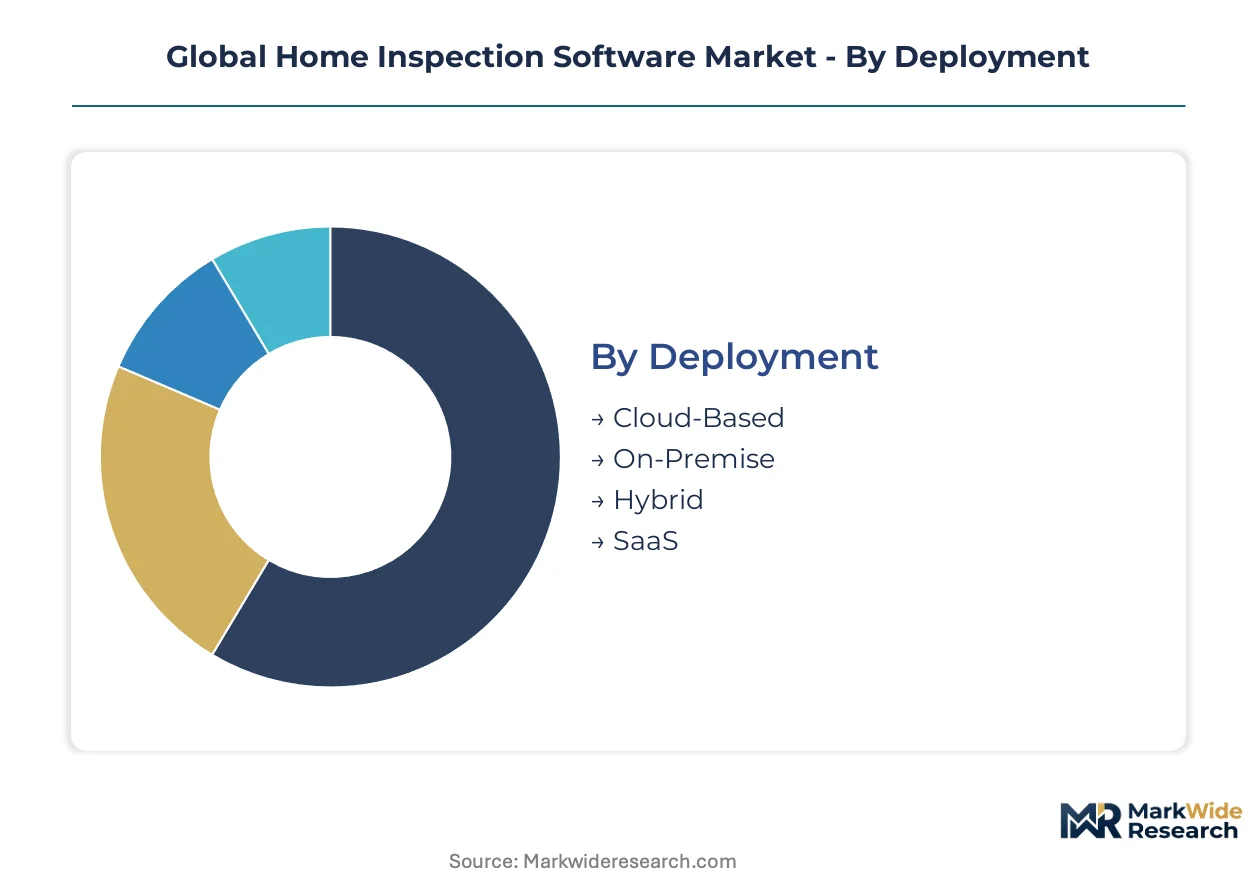
Home inspection software vendors structure product portfolios around deployment economics, inspector workflow requirements, and regulatory compliance mandates. Segment boundaries determine pricing architecture, integration complexity, and customer lifetime value profiles across residential and commercial property assessment verticals.
Deployment:
Margin pools concentrate in recurring revenue models that minimize customer acquisition costs while embedding automatic compliance updates.
- Cloud-Based:Multi-tenant architectures with automatic regulatory template synchronization dominate independent inspector adoption in the United States, Canada, and Australia. Lower upfront capital requirements and continuous feature delivery create sticky subscription relationships with small multi-inspector practices.
- SaaS:Purpose-built subscription platforms with embedded scheduling and payment processing command premium pricing by consolidating vendor relationships. Texas, California, and Florida licensing boards mandate digital documentation standards that SaaS vendors monetize through compliance module tiering.
- Hybrid:Split architectures maintaining sensitive client data on local infrastructure while leveraging cloud analytics for reporting generation.
- On-Premise:Legacy server installations persisting in large commercial assessment firms with specialized security requirements.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
Solution/Offering:
Customer willingness-to-pay escalates with workflow integration depth rather than standalone feature count.
- Mobile Applications:iOS and Android-native field tools with offline synchronization eliminate connectivity dependencies during rural and basement inspections. Tablet-native workflows are displacing laptop-dependent tools across North American residential markets.
- Data Analytics:Predictive maintenance intelligence derived from historical inspection findings opens premium-priced revenue streams with insurance underwriters and facility managers in Germany and France.
- Reporting Tools:Automated report generation compliant with ASHI and InterNACHI standards.
- Scheduling Modules:Calendar integration with customer notification systems reducing no-show rates.
- Customer Management:CRM functionality bundling client communication and document archival.
Mobile Applications anchor volume concentration. Data Analytics is climbing the fastest.
Application:
Commercial use cases sustain higher per-seat pricing through specialized equipment integration and extended report complexity.
- Residential Property Analysis:Pre-purchase assessment workflows dominate transaction velocity in the United States, Australia, and Canada where buyer financing mandates inspection contingencies. Photographic annotation and structured data capture standardize condition documentation for mortgage underwriters.
- Commercial Building Assessment:Facility condition indexing and capital planning integration serve property portfolio managers with multi-year maintenance forecasting requirements. German and French regulators enforce data portability requirements that elevate platform switching costs.
- Pre-Sale Inspection:Seller-initiated assessments accelerating transaction timelines.
- Insurance Inspection:Risk-adjusted premium calculations based on documented property conditions.
- Maintenance Check:Recurring facility monitoring for institutional property owners.
Residential Property Analysis commands transaction volume. Commercial Building Assessment is gaining share fastest.
End User:
Procurement authority fragmentation between field practitioners and enterprise procurement functions complicates vendor sales motion design.
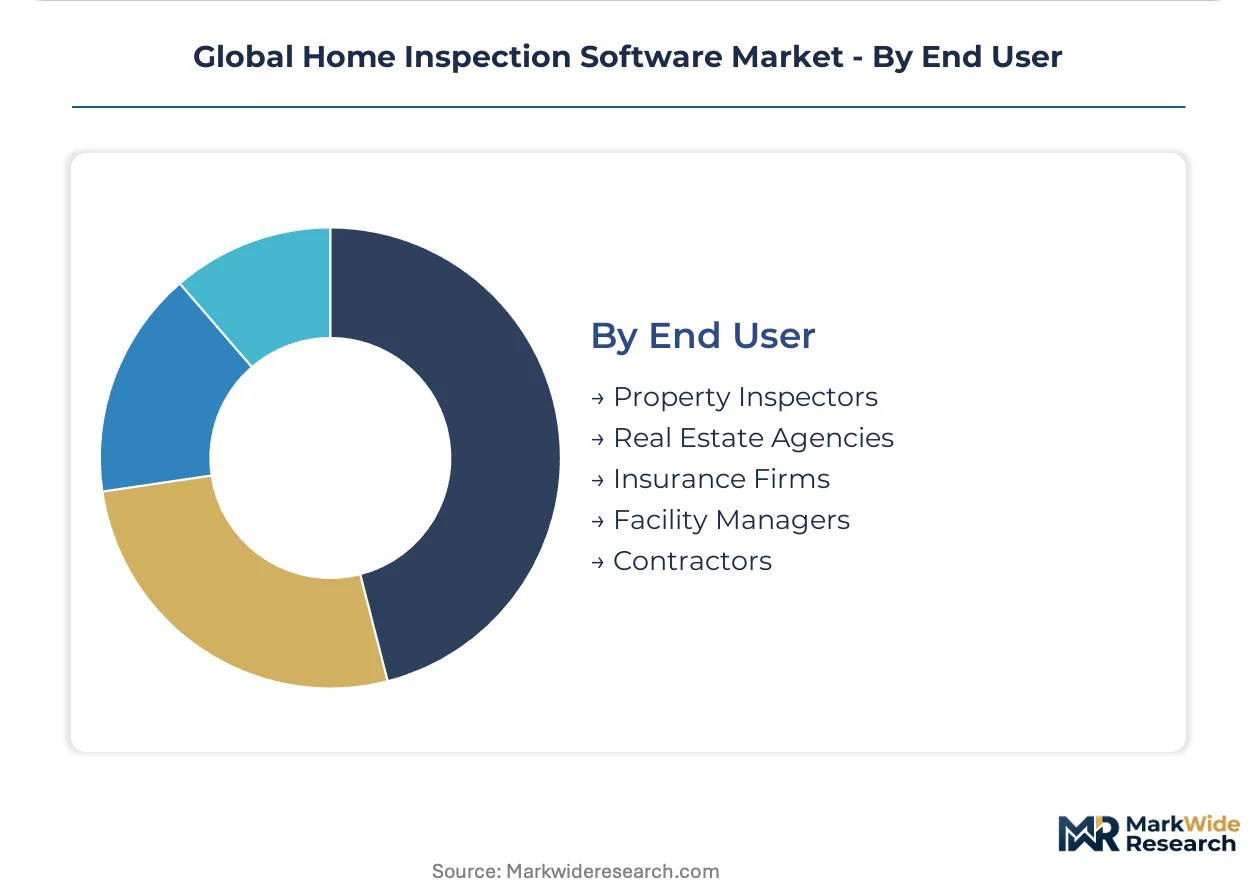
- Property Inspectors:Independent practitioners and small multi-inspector practices drive mobile-first adoption with subscription sensitivity and rapid software evaluation cycles. Workforce shortages across major US metros limit addressable base expansion regardless of accessibility improvements.
- Real Estate Agencies:Brokerage-level platform licensing for transaction coordination and referral relationship management.
- Insurance Firms:Underwriter integration for predictive risk modeling based on historical inspection archives.
- Facility Managers:Enterprise property portfolio oversight with multi-year capital planning requirements.
- Contractors:Repair scope verification and warranty documentation workflows.
Property Inspectors represent the installed base core. Insurance Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidelines on data integrity for electronic records intersect with ASHI and InterNACHI standards to shape product requirements across multiple jurisdictions. State-level licensing boards in Texas, California, and Florida collectively establish compliance benchmarks that vendors must satisfy for market access.
United States
Property inspector workforce shortages across major metros rotate demand toward software that compresses inspection cycle times. Texas, California, and Florida licensing boards mandate digital documentation standards that create captive demand for regulatory-compliant platforms. Transaction velocity pressures in the Southeast and Southwest compress software evaluation cycles for independent inspection firms.
Canada
Buyer financing mandates for inspection contingencies drive pre-purchase assessment workflows in Ontario and British Columbia. Health Canada guidelines on electronic record integrity shape data capture requirements for cross-border operators. Toronto and Vancouver clusters concentrate multi-inspector practices consolidating vendor relationships toward subscription-based platform access.
Australia
Tightening home inspector certification requirements across New South Wales and Victoria create first-mover advantages for compliant platform entrants. TGA frameworks influence data portability expectations for inspection archives. Sydney and Melbourne metropolitan areas anchor residential property analysis transaction volume.
Germany
Commercial building assessors segment product roadmaps between high-autonomy North American releases and compliance-heavy European variants. GDPR data localization requirements enforce sovereign hosting infrastructure that fragments vendor economics. Berlin and Munich facility management clusters drive predictive maintenance intelligence demand.
France
ANSM and CNIL regulators enforce algorithmic explainability documentation for automated defect classification features. Data portability requirements for inspection archives elevate platform switching costs among commercial property portfolio managers. Paris and Lyon industrial zones concentrate enterprise property oversight with multi-year capital planning requirements.
Global Home Inspection Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the home inspection software market. Cloud-native mobile architectures and API-first integration capabilities separate the upper tier from legacy-dependent competitors. Three archetypes dominate: cloud-native reporting specialists, scheduling-centric platform bundlers, and data analytics premium providers. Competitive motion concentrates on strategic partnerships with real estate transaction platforms and compliance module tiering for state licensing requirements.
Within the cloud-native reporting tier, Spectora and HomeGauge exemplify divergent positioning strategies. Spectora occupies a position emphasizing mobile-first field workflows with offline synchronization capabilities. HomeGauge anchors its representation through deep integration archetypes with multiple listing services. Inspection Support Network sits within the scheduling-centric bundler category, exemplifying customer management tool consolidation. These three players collectively represent the strategic archetype spectrum visible in the vendor landscape.
| Leading Market Players |
|---|
| Home Inspector Pro |
| InspectPro |
| InspectorData |
| Palm-Tech |
| Inspection Support Network |
| Spectora |
| Inspector Toolbelt |
| Tap Inspect |
| HomeGauge |
| Others |
Supply & Pricing Matrix
Ninety-day feature delivery cycles for cloud-native compliance modules concentrate pricing power with SaaS vendors serving Texas, California, and Florida inspector licensing boards. This temporal compression of regulatory template updates feeds directly into subscription tiering strategies and customer lock-in dynamics across North American residential inspection markets.
Pricing Analysis
North American subscription rates for mobile-first inspection platforms command premiums over Australian and European equivalents due to tighter state-level licensing mandates. Three-tier pricing structure across premium, standard, and economy levels segments by compliance module depth and API integration access. Pricing pressure stems from independent inspector consolidation toward bundled scheduling-reporting platforms. Small multi-inspector practices exhibit highest price sensitivity; enterprise facility management clients show lowest.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes marginally affect tablet hardware procurement costs for field deployment kits. Software development concentrates in the United States, Canada, and Ireland; cloud infrastructure draws from AWS, Azure, and Google Cloud regional data centers. Single-source vulnerability sits with iOS and Android platform dependency for mobile-native workflows. Distribution runs through direct vendor sales teams and channel partners serving real estate transaction platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home inspection software sits in early-cycle expansion as state-level digital documentation mandates accelerate inspector platform adoption across the three largest US housing markets.
For Market Incumbents: Consolidate API-first integration capabilities with multiple listing services and real estate transaction platforms before emerging scheduling-centric bundlers capture brokerage-level licensing. Deepen backward integration into predictive maintenance analytics to defend margin position against insurance underwriter direct procurement. Invest in Texas, California, and Florida compliance module specialization as regulatory tiering intensifies. For New Entrants and Emerging Players: InterNACHI certification fast-track partnerships offer lowest-friction market entry for mobile-native reporting tools targeting independent inspector workforce shortages. White-space concentrates in Australia licensing expansion across New South Wales and Victoria, plus commercial building assessment data analytics for German and French facility managers. Go-to-market should anchor in embedded scheduling modules that reduce no-show rates for small multi-inspector practices. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because regulatory digitization of building safety oversight creates persistent compliance-driven demand. Target acquisition profiles emphasize cloud-native mobile architectures with offline synchronization and established API integration protocols. Watch inspector certification mandate expansion across Australian states as inflection indicator for geographic demand rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding with multiple listing services captures brokerage procurement authority in Texas and Florida. |
| Compliance Module Tiering | State-specific licensing templates monetize regulatory fragmentation across California and Florida boards. |
| Geographic Expansion | Australian certification tightening creates first-mover positioning in Sydney and Melbourne metro clusters. |
| Acquisition of Specialist Firm | Scheduling-centric bundlers add customer retention tools that reduce churn in independent inspector segments. |
| Product Launch | Human-in-the-loop AI defect recognition navigates EU AI Act constraints for European market entry. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with home inspection software executives, state licensing board administrators, and real estate transaction platform engineers; and secondary validation against ASHI and InterNACHI regulatory filings, SEC SaaS vendor disclosures, and state-level inspector certification databases. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against property transaction velocity data anchored market sizing.
Across the analysis window, the forecasting framework modeled segmentation by deployment architecture, inspector practice size, application vertical, and regional regulatory cluster. CAGRs derived from historical cloud-native platform penetration rates and projected state-level digital documentation mandate implementation timelines. Inspector workforce shortage trajectories and insurance underwriter integration demand curves served as industry-specific demand inputs.
Decision-makers should treat outputs as directional under assumptions of continued state-level licensing digitization and stable property transaction velocity; material deviation would warrant model refresh. Specific risk factors include EU AI Act enforcement intensity on automated defect recognition and inspector certification program delays in Australian jurisdictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Florist Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Global Automation Software Market
Software & Services
Freight Management Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Board Portal Market
Software & Services
Customs Declaration Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Global VR Game Engine Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Stock Media Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Orchestration Tools Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Global Nosql Database Market