
 Mobile Speech Recognition Software Market | 2026-2036
Mobile Speech Recognition Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Speech Recognition Software Market Foresight
Healthcare provider adoption is decoupling from enterprise IT budgets as clinical voice documentation becomes essential infrastructure. Nuance Communications dominates medical speech recognition through deep workflow integration with electronic health records. Alphabet leverages its tensor processing infrastructure to sustain low-latency inference for Android voice services. Amazon competes through Alexa Custom Assistant deployments in automotive and hospitality verticals.
Mobile speech recognition software encompasses algorithms, acoustic models, and language processors that convert spoken audio into machine-readable text or executable commands on portable computing devices. The technology relies on mel-frequency cepstral coefficients for feature extraction and recurrent neural networks for sequence modeling, enabling hands-free operation in clinical, industrial, and consumer environments. Cloud-based deployment leads in revenue contribution due to elastic scaling for natural language processing workloads, while edge computing segments show the fastest trajectory as on-device inference reduces latency for voice biometric authentication. Machine learning technology anchors the core architecture, though voice biometrics is emerging as a distinct margin pool where specialized vendors command premium positioning.
FDA guidelines on software as a medical device shape clinical voice product validation requirements in the United States, while the EU AI Act imposes conformity assessments for biometric identification systems deployed in European markets. HIPAA and GDPR compliance frameworks directly constrain how voice data traverses cloud infrastructure, forcing vendors to architect region-specific data residency. Stakeholders must monitor evolving interoperability standards between on-premise hospital systems and cloud-based speech APIs to preserve competitive positioning.
Market Dynamics
Healthcare providers are decoupling clinical voice documentation from enterprise IT cycles, treating speech recognition as essential infrastructure rather than discretionary software spend. This structural shift is compressing procurement timelines and elevating workflow integration above standalone accuracy metrics in vendor selection criteria.
Growth Catalysts
- HIPAA-compliant cloud architectures:Healthcare systems in the United States are accelerating migration to FedRAMP-authorized speech APIs, eliminating on-premise infrastructure burdens while preserving audit trails for protected health information.
- EU AI Act conformity pathways:Biometric voice identification systems deployed in European markets now follow standardized assessment procedures, reducing regulatory uncertainty for vendors and accelerating hospital procurement decisions.
- Automotive cabin computing:Embedded neural accelerators in vehicle head units are enabling offline speech command processing, creating new deployment surfaces independent of smartphone tethering.
Market Restraints
- GPU memory pricing volatility:Training runs for large acoustic models remain exposed to NVIDIA H100 supply constraints and cloud compute spot pricing swings, compressing R&D margins for mid-tier vendors.
- Taiwanese foundry concentration:Edge AI inference chips for on-device speech processing depend on TSMC N4 and N3 process nodes, creating single-source vulnerability for voice biometric hardware.
- Accent and dialect coverage gaps:Low-resource language variants and regional phonetic patterns require prohibitively expensive data collection, limiting addressable market expansion in Sub-Saharan Africa and Central Asia.
Strategic Opportunities
- India's BIS certification pipeline:The country's mandatory testing requirements for voice-enabled IoT devices create first-mover advantage for vendors establishing local data residency and Hindi-Tamil-Telugu model coverage.
- Convergence with ambient clinical intelligence:Pairing speech recognition with passive sensor fusion in hospital rooms enables automated progress note generation without explicit wake-word activation.
- Japan's METI voice data governance framework:The ministry's guidelines on anonymized speech corpus sharing reduce data acquisition costs for vendors targeting elderly care and manufacturing voice interfaces.
Industry Challenges
- FDA SaMD validation timelines:Clinical decision support features triggered by voice commands require 510(k) clearance pathways averaging 180 days, delaying revenue recognition for healthcare-focused releases.
- Legacy EHR integration complexity:Hospital systems running Cerner and Epic variants from 2015-2019 lack modern FHIR endpoints, forcing costly custom middleware development for speech-to-text insertion workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Speech Recognition Software Market |
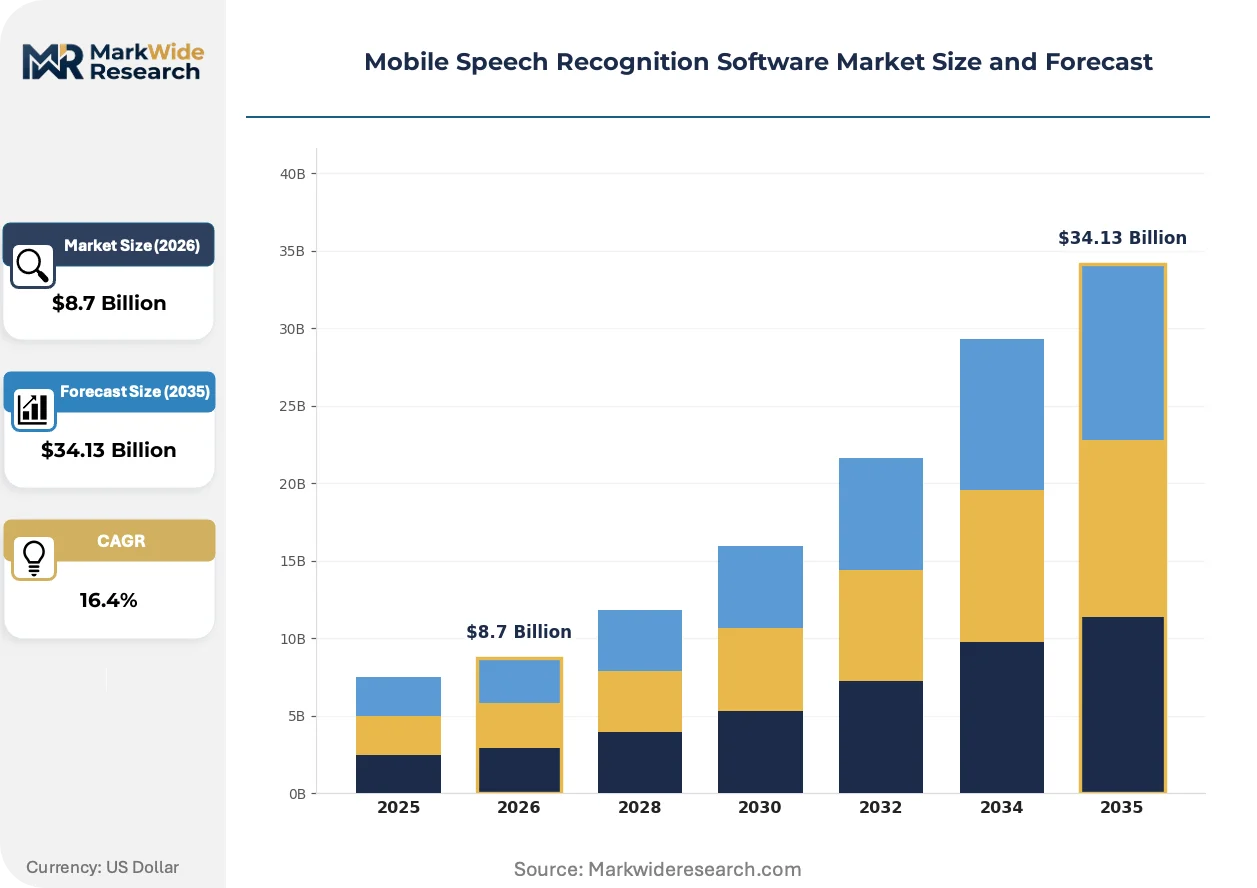
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Natural Language Processing, Machine Learning, Voice Biometrics, Signal Processing End User: Healthcare Providers, Educational Institutions, Enterprises, Individual Users Application: Virtual Assistants, Voice Search, Transcription Services, Customer Support |
| Companies Covered | Nuance Communications, Alphabet, Apple, Baidu, Amazon, Microsoft, LumenVox, Pareteum Corporation, Sensory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Speech Recognition Software Market Shifts & Advancements
Foundation models pretrained on multilingual speech corpora are compressing the traditional acoustic model and language model pipeline into unified architectures. This convergence is lowering the capital threshold for specialized vertical deployment while raising performance floors for baseline transcription accuracy.
Neural audio codecs operating below 1 kbps are electrifying real-time speech transmission for cloud-based recognition services. Telemedicine platforms and dispatch centers are adopting these compression standards to maintain transcription fidelity over congested cellular networks. The technology is compressing bandwidth costs to marginal levels, enabling voice-first interfaces in bandwidth-constrained environments previously served by text-only inputs.
The EU AI Act's risk classification system for biometric identification is forcing architectural separations between voice authentication and general speech recognition stacks. Vendors serving European healthcare and financial services are maintaining parallel codebases to isolate high-risk processing pathways. German automotive manufacturers and French banking consortia are requiring explicit conformity documentation as a procurement gate, displacing vendors lacking notified body relationships.
Hospital procurement committees are unbundling speech recognition from comprehensive EHR contracts, issuing standalone RFPs for clinical documentation specialty vendors. This pattern is most visible in United States academic medical centers and German university hospital networks, where informatics departments seek best-of-breed accuracy rather than single-vendor consolidation. The shift is elevating specialized clinical speech vendors against generalist platform providers in competitive evaluations.
Mobile Speech Recognition Software Market Segmentation
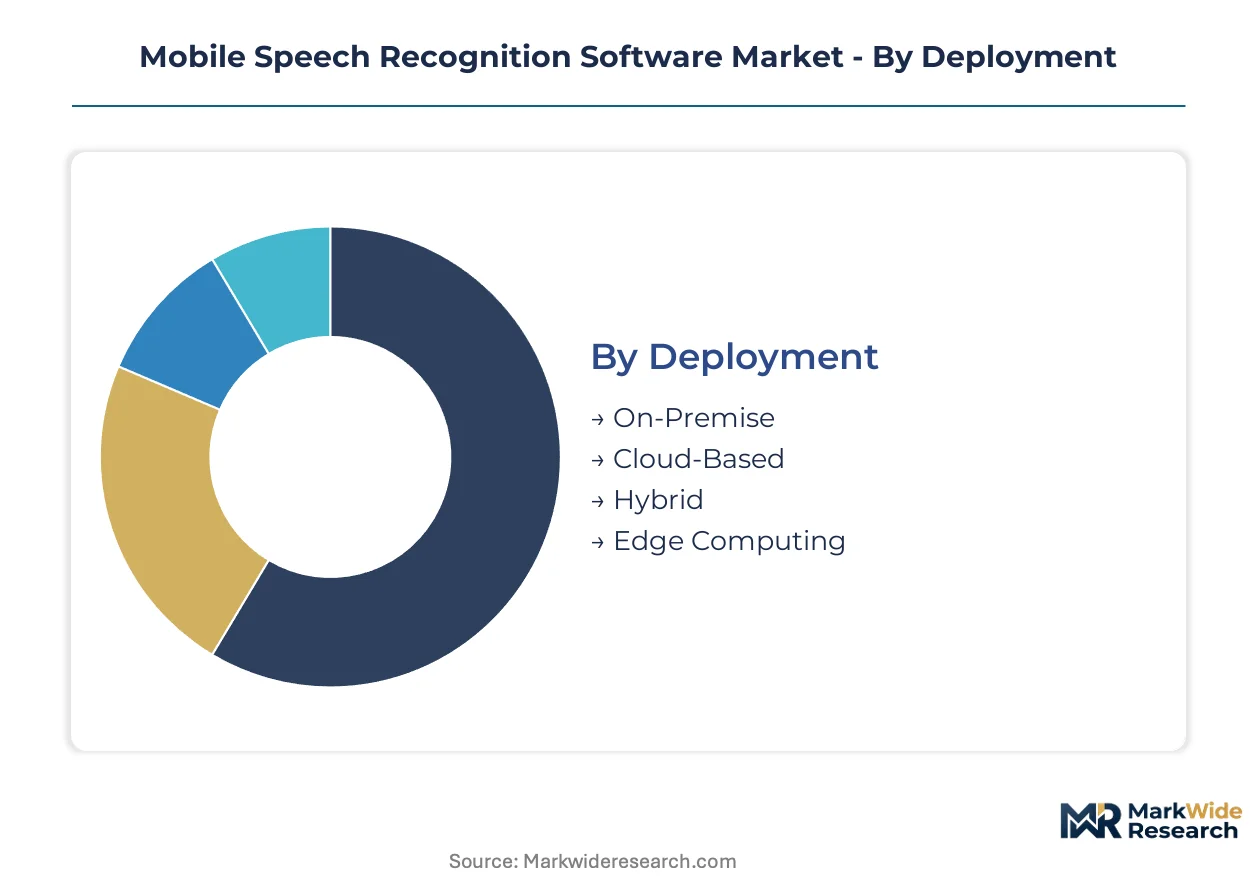
Deployment architecture determines regulatory exposure and latency trade-offs for mobile speech recognition vendors. Technology selection governs whether solutions compete on accuracy benchmarks or specialized biometric security. End-user concentration and application modality together shape pricing power and integration complexity across the value chain.
Deployment:
Standardized cloud APIs dominate volume, while customized edge and hybrid configurations capture premium workflows requiring data sovereignty.
- Cloud-Based:Elastic infrastructure scales NLP workloads across concurrent users without capital expenditure. United States healthcare systems favor FedRAMP-authorized cloud speech APIs to eliminate on-premise hardware burdens while preserving HIPAA audit trails for protected health information.
- Edge Computing:On-device inference executes acoustic modeling within smartphone neural accelerators or automotive head units. German automotive manufacturers and Japanese electronics firms are embedding offline speech command processing to reduce cellular dependency and latency for cabin control systems.
- Hybrid:Split architectures process wake-word detection locally while streaming complex transcription to cloud endpoints. This configuration balances responsiveness with accuracy for enterprise virtual assistant deployments.
- On-Premise:Air-gapped installations serve defense contractors and classified government facilities where voice data cannot traverse external networks.
Most installed capacity flows through Cloud-Based deployment. Expansion is steepest in Edge Computing.
Technology:
Cost tier stratification separates commodity transcription engines from premium biometric authentication stacks requiring specialized training data.
- Machine Learning:Recurrent neural networks and transformer architectures anchor acoustic and language modeling for general-purpose speech recognition. Healthcare documentation and enterprise dictation systems concentrate demand here, driven by continuous accuracy improvements from multilingual pretraining.
- Voice Biometrics:Speaker identification and verification algorithms extract unique vocal tract characteristics for authentication workflows. European banking consortia and United States financial services firms are deploying voice biometric gates under EU AI Act conformity pathways and FFIEC authentication guidelines.
- Natural Language Processing:Semantic parsing and intent classification layers transform transcribed text into executable commands or structured data extraction.
- Signal Processing:Noise suppression, echo cancellation, and mel-frequency cepstral coefficient extraction form the preprocessing foundation for all downstream recognition.
Machine Learning captures the broadest deployment base. Voice Biometrics is gaining share fastest in regulated authentication verticals.
End User:
Customer type determines procurement cycle length and integration depth, from individual app store purchases to multi-year enterprise contracts.
- Healthcare Providers:Clinical documentation workflows demand specialty-trained acoustic models for medical terminology and integration with Epic, Cerner, and athenahealth EHR systems. United States academic medical centers are unbundling speech recognition from comprehensive EHR contracts to pursue best-of-breed accuracy.
- Enterprises:Call center analytics, meeting transcription, and CRM voice data entry drive volume procurement across financial services, legal, and professional services sectors.
- Educational Institutions:Accessibility services and lecture captioning create institutional demand with extended procurement timelines and accessibility compliance requirements.
- Individual Users:Smartphone virtual assistants, voice search, and messaging dictation represent high-volume, low-margin consumer adoption through preinstalled platform services.
Healthcare Providers command the highest per-seat pricing. Enterprises are scaling fastest as remote work normalizes meeting transcription demand.
Application:
Maturity gradients separate established transcription commodities from emerging ambient intelligence modalities requiring sensor fusion.
- Transcription Services:Real-time and batch conversion of speech to text serves medical documentation, legal discovery, and media captioning. Cloud APIs from major platform providers have commoditized baseline accuracy, compressing margins for standalone vendors.
- Virtual Assistants:Task-oriented dialogue systems execute commands, retrieve information, and control connected devices through natural language interfaces. Automotive and hospitality verticals are deploying branded assistants through Alexa Custom Assistant and equivalent programs.
- Voice Search:Query-by-voice interfaces for web, application, and device content retrieval compete with text-based search for mobile user attention.
- Customer Support:Automated speech recognition powers interactive voice response systems and agent assist tools for call routing and real-time coaching.
Transcription Services retain the largest installed base. Virtual Assistants are climbing the fastest as automotive and healthcare ambient intelligence deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting speech recognition infrastructure investment toward jurisdictions with clearer biometric data governance frameworks. Vendors are relocating cloud inference capacity to exploit compliance-cost differentials between markets with established AI conformity pathways and those with evolving standards.
United States
FedRAMP-authorized cloud APIs and HIPAA-compliant architectures drive healthcare provider adoption. FDA software-as-a-medical-device guidelines extend validation timelines for clinical voice products. Academic medical centers in Boston and the Research Triangle are unbundling speech recognition from EHR contracts to pursue specialty accuracy.
Germany
Automotive cabin computing demand and EU AI Act conformity assessments shape vendor strategies. KBA and notified body relationships are becoming procurement gates for voice biometric systems. Stuttgart and Munich manufacturing clusters are embedding offline neural accelerators for embedded speech command processing.
Japan
METI voice data governance frameworks reduce corpus acquisition costs for elderly care applications. PMDA guidance on software medical devices influences clinical product validation. Tokyo and Osaka electronics firms are deploying on-device inference for manufacturing voice interfaces and ambient hospital intelligence.
India
BIS certification requirements for voice-enabled IoT devices create first-mover structural advantages. TRAI data localization norms and RBI financial authentication standards constrain cloud architecture choices. Bengaluru and Hyderabad technology corridors are building Hindi-Tamil-Telugu model coverage for domestic and export markets.
United Kingdom
NHS digital transformation programs and MHRA software medical device regulations shape procurement patterns. Post-Brexit data adequacy arrangements with the EU affect cross-border voice data flows. London financial services and Cambridge speech technology clusters are deploying voice biometric authentication under FCA authentication guidelines.
Mobile Speech Recognition Software Market Competitive Landscape
Strategic partnership formation dominates the current landscape as vendors seek EHR integration depth and automotive deployment surfaces. The market structures around three tiers: platform-scale cloud providers with tensor processing infrastructure, clinical workflow specialists with deep EHR integration, and edge-AI chip vendors with automotive design wins. Platform providers leverage multilingual pretraining scale. Clinical specialists compete on specialty acoustic model accuracy. Edge vendors differentiate through neural accelerator integration. Vertical integration into custom silicon and backward integration into training data collection represent the dominant competitive vectors.
Within the clinical workflow specialist tier, Nuance Communications exemplifies deep EHR integration positioning. Among platform-scale providers, Alphabet and Amazon occupy anchor positions through contrasting deployment strategies—Alphabet via Android tensor processing infrastructure, Amazon through Alexa Custom Assistant vertical programs. These three entities represent the archetypal competitive positions shaping vendor selection criteria across healthcare and automotive procurement committees.
| Leading Market Players |
|---|
| Nuance Communications |
| Alphabet |
| Apple |
| Baidu |
| Amazon |
| Microsoft |
| LumenVox |
| Pareteum Corporation |
| Sensory |
| Others |
Supply & Pricing Matrix
NVIDIA H100 GPU memory pricing volatility propagates through cloud inference costs into tiered SaaS subscription rates for healthcare and automotive buyers. Cloud compute spot pricing swings compress R&D margins for mid-tier acoustic model vendors while elevating procurement leverage for enterprise customers with FedRAMP-authorized contract vehicles.
Pricing Analysis
Direct-to-OEM discount structures dominate automotive cabin computing deployments, bypassing distributor markups for German and Japanese manufacturers embedding neural accelerators. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant clinical documentation stacks from general-purpose transcription APIs and consumer virtual assistant bundles. Cost compression in edge AI inference chips is intensifying because TSMC N4 and N3 foundry allocation constraints limit supply elasticity. Healthcare providers exhibit lowest price sensitivity due to workflow integration lock-in, while individual consumer segments drive volume at margins approaching commoditization.
Supply Chain Analysis
FedRAMP authorization and EU AI Act conformity documentation function as procurement gates, filtering vendor participation before pricing negotiations commence. Cloud inference capacity concentrates in the United States, Germany, and Japan where data residency frameworks align with healthcare and financial services compliance requirements. Edge AI inference chips draw from TSMC N4 and N3 process nodes, NVIDIA tensor processing units, and ARM neural accelerator IP. Single-source vulnerability in Taiwanese foundry concentration threatens automotive and biometric hardware supply continuity. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with embedded compliance consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's biometric identification risk classification functions as a regulatory compounder, forcing architectural separations that sustain premium pricing for compliant vendors while displacing non-conforming competitors from European healthcare and financial procurement.
For Market Incumbents: Extend EHR integration depth through FHIR-native middleware development targeting Cerner and Epic variants lacking modern endpoints. Deepen backward integration into Hindi-Tamil-Telugu training data collection for India's BIS certification pipeline, defending against emerging entrants with localized model coverage. Threat substitution from foundation model commoditization demands continuous specialty acoustic model investment to preserve clinical accuracy differentiation. For New Entrants and Emerging Players: Cloud marketplace channel partners offer lowest-friction distribution for ambient clinical intelligence solutions targeting United States academic medical centers unbundling speech recognition from comprehensive EHR contracts. White-space concentrates in Sub-Saharan African and Central Asian dialect coverage where incumbent data collection costs remain prohibitive. Go-to-market leverage through automotive Tier 1 supplier relationships bypasses OEM direct procurement complexity. For Investors and Strategic Acquirers: Consolidation pressure builds where voice biometric authentication stacks require parallel EU AI Act codebase maintenance and notified body relationships that strain mid-tier vendor capital structures. Long-term viability centers on clinical workflow specialists with captive EHR integration depth and automotive edge-AI design wins. Signal to monitor: hospital procurement committee unbundling velocity accelerating standalone RFP issuance versus platform consolidation preference.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep FHIR-native EHR connectivity preserves competitive positioning in United States academic medical centers. |
| Geographic Expansion | India BIS certification and Hindi-Tamil-Telugu model coverage establish first-mover structural advantage in voice-enabled IoT. |
| Acquisition of Specialist Firm | Voice biometric authentication vendors with EU notified body relationships command premium positioning under AI Act conformity pathways. |
| Strategic Partnership | Automotive Tier 1 supplier alliances embed offline neural accelerators for cabin computing independent of smartphone tethering. |
| Product Launch | Ambient clinical intelligence sensor fusion enables automated progress note generation without explicit wake-word activation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with healthcare CIOs, EHR integration specialists, automotive platform engineers, and cloud procurement officers with secondary validation against FDA software-as-a-medical-device filings, EU AI Act conformity assessment documentation, and hyperscaler capex disclosures. SEC 10-K infrastructure investment disclosures, hospital GPO contract databases, and automotive semiconductor design win registries anchored supply-side triangulation. Bottom-up deployment model tracking and top-down regulatory pathway analysis converged on segment-level estimates.
Segment-weighting approaches distributed value across cloud-based, edge computing, hybrid, and on-premise deployment architectures, with technology stratification between machine learning, voice biometrics, natural language processing, and signal processing layers. End-user concentration in healthcare providers, enterprises, educational institutions, and individual consumers shaped pricing power assumptions across the projection horizon. CAGRs derived from elasticity modeling of clinical documentation adoption curves and automotive cabin computing penetration rates, with neural audio codec compression standards and ambient intelligence sensor fusion treated as technology inflection inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA SaMD validation timeline extensions, TSMC foundry allocation constraints, and EU AI Act enforcement consistency across notified bodies. Deviation in hospital procurement unbundling velocity or automotive embedded neural accelerator design win concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
CAD Modeling Software Market
Software & Services
Audit Management Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Board Portal Market
Software & Services
Global User Interface Service Market
Software & Services
Live Software Market
Software & Services
Enterprise Software Market
Software & Services
Server Software Market
Software & Services
Smartphone OS Market
Software & Services
Deck Software Market
Software & Services
Data Preparation Tools Market
Software & Services
Communication Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Spain Sports Management Software Market
Software & Services
Attendance Management Software Market