
 Data Compression Software Market | 2026-2036
Data Compression Software Market Size, Share, and Industry Trends Forecast 2026-2036
Data Compression Software Market Intelligence
The capability gap between hyperscale infrastructure operators and specialized compression vendors is unwinding as cloud economics reshape investment priorities. International Business Machines Corporation leverages its enterprise storage heritage to anchor mainframe-to-cloud migration contracts. Google LLC sustains leadership in video codec integration across its content delivery network. Microsoft Corporation competes through native compression embedded in Azure data services.
Data compression software encompasses algorithms and systems that reduce file size through mathematical encoding while preserving information integrity or acceptable fidelity thresholds, typically achieving ratios from 2:1 to 100:1 depending on source entropy and technique. Lossless compression dominates financial services and database management where bit-exact recovery is mandatory, while lossy methods lead media streaming applications where perceptual quality trade-offs unlock bandwidth savings. Cloud-based deployment is capturing the fastest expansion as SaaS delivery models eliminate on-premises infrastructure overhead for mid-market buyers.
The EU GDPR and the EU AI Act impose data minimization obligations that directly expand demand for preprocessing compression in European enterprise pipelines. The US FCC net neutrality framework and HIPAA storage requirements shape how telecommunications and healthcare providers architect compression layers for compliant transmission. Stakeholders must monitor whether emerging quantum-resistant encryption standards will force algorithmic redesigns that alter compression-to-security performance trade-offs.
Market Dynamics
Real-time video encoding workloads are compressing deployment cycles for cloud-native compression engines as streaming platforms demand sub-100-millisecond latency thresholds. This pressure is restructuring vendor roadmaps toward hardware-accelerated inference pipelines.
Growth Catalysts
- EU AI Act data minimization:GDPR-aligned preprocessing mandates in European enterprise pipelines are expanding automated compression procurement for AI training datasets.
- Industrial IoT sensor density:German manufacturing clusters require edge-native compression to manage bandwidth saturation from high-frequency vibration and thermal monitoring streams.
- Hardware-accelerated codecs:AV1 and VVC silicon integration in consumer devices is unlocking royalty-efficient compression for over-the-top video distributors.
Market Restraints
- Patent pool fragmentation:HEVC and VVC licensing complexity from Access Advance and MPEG LA creates royalty stacking risks for embedded software vendors.
- Compute cost volatility:GPU and NPU cloud instance pricing fluctuations compress margins for SaaS compression providers serving mid-market buyers.
- Lossless algorithm ceiling:Entropy encoding limits in LZ4 and Zstandard libraries constrain further ratio improvements for database and financial transaction workloads.
Strategic Opportunities
- Quantum-resistant encryption convergence:NIST post-quantum cryptographic standards create whitespace for compression algorithms optimized for lattice-based ciphertext expansion.
- India PLI scheme:Domestic data center buildouts under production-linked incentives are attracting edge-compression vendors to localize software stacks.
- Medical imaging DICOM optimization:FDA 510(k) pathways for AI-assisted diagnosis are driving demand for lossless compression of volumetric CT and MRI datasets.
Industry Challenges
- Codec engineering talent scarcity:Deep expertise in discrete cosine transform optimization and entropy coding is concentrating at semiconductor firms, starving independent software vendors.
- Legacy storage integration friction:Mainframe-era tape archive systems at financial institutions resist API-native compression without costly middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Compression Software Market |
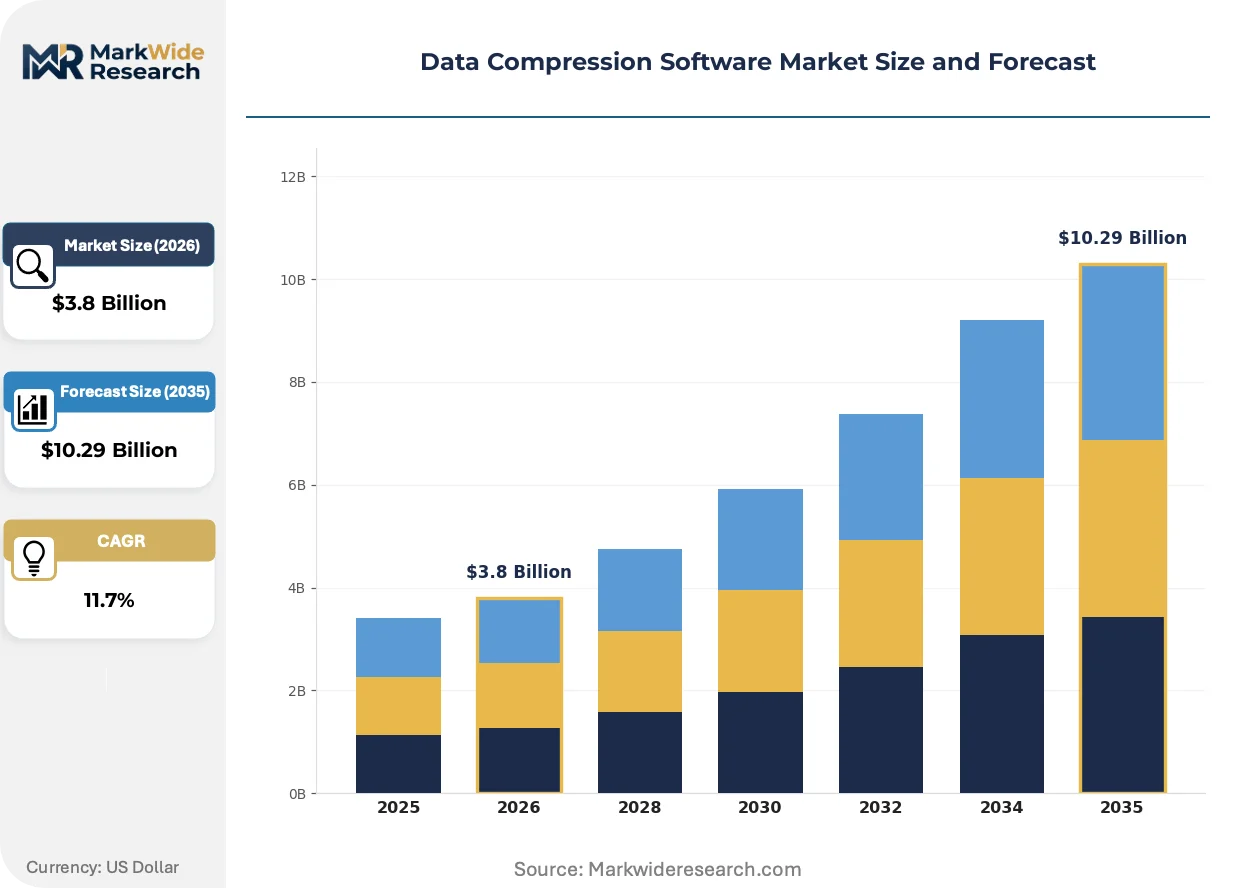
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
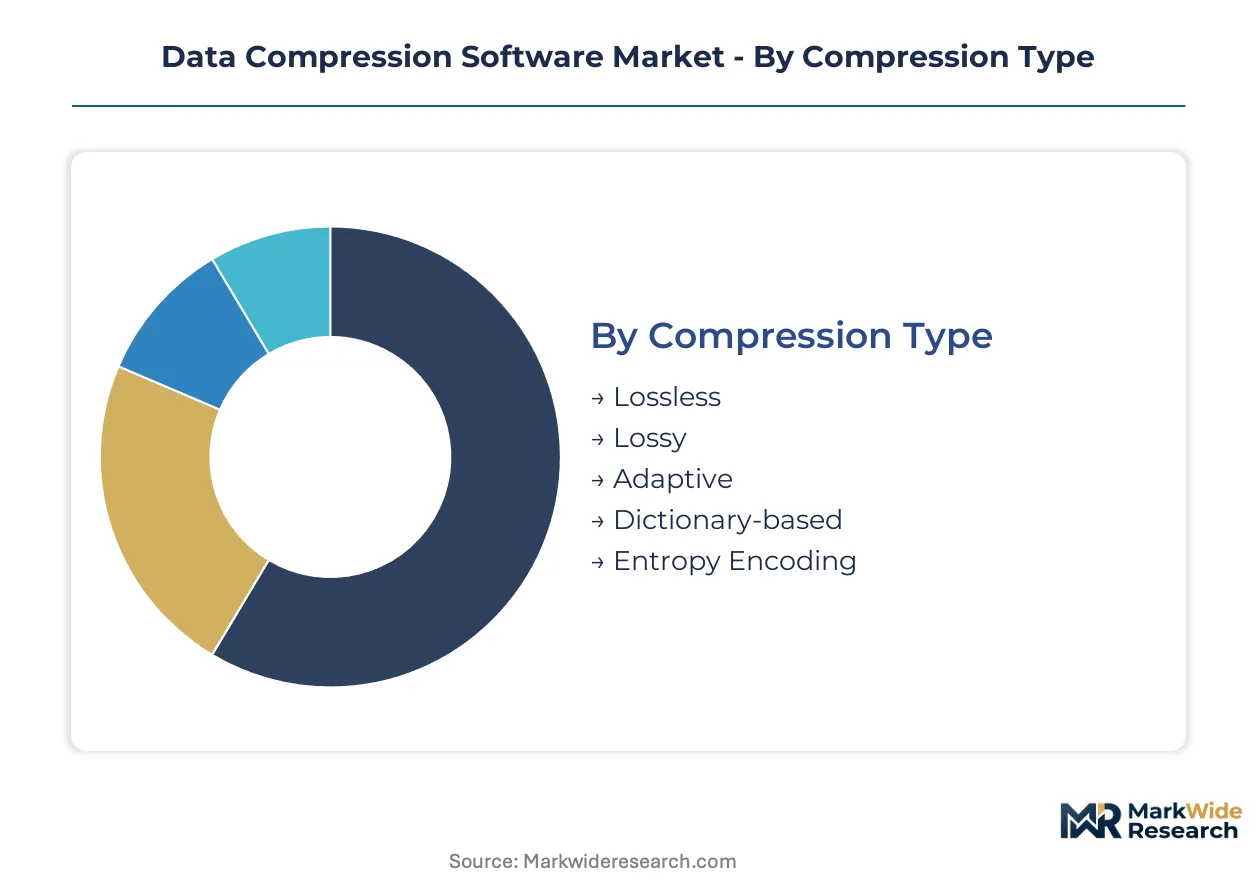
| Segmentation | Compression Type: Lossless, Lossy, Adaptive, Dictionary-based, Entropy Encoding Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing, SaaS Application Area: Data Storage Optimization, Media Streaming, Database Management, Network Transmission, Backup & Archiving End User: Telecommunications, Financial Services, Government Agencies, Media & Entertainment, Software Developers |
| Companies Covered | International Business Machines Corporation, Broadcom Inc., Google LLC, NortonLifeLock Inc., SAS Institute Inc., Microsoft Corporation, Oracle Corporation, Corel Corporation, Meta Platforms Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Compression Software Market Strategic Shifts & Innovations
Algorithm-hardware co-design is displacing pure software optimization as the primary vector for compression efficiency gains. Vendors now optimize for specific NPU instruction sets rather than generic CPU architectures.
Neural compression codecs are miniaturizing model architectures for on-device inference. Smartphone OEMs in South Korea and Taiwan are adopting sub-10-megabyte autoencoder networks for camera pipeline optimization. This shift is miniaturizing the boundary between cloud and edge processing responsibilities.
The EU AI Act risk classification framework is mandating technical documentation for high-risk AI systems that includes data lineage and preprocessing steps. Compression vendors serving European healthcare and finance sectors must now embed audit trails into encoding pipelines. German automotive suppliers are retrofitting existing sensor data lakes with GDPR-compliant compression gateways to satisfy conformity assessment requirements.
Enterprise procurement of compression infrastructure is consolidating under platform engineering teams rather than decentralized IT purchasing. Buyers now evaluate codecs as components of unified data pipelines rather than standalone tools. This pattern is most pronounced in US technology and media conglomerates building internal developer platforms for analytics and content delivery.
Data Compression Software Market Segmentation
Compression software vendors architect pricing and distribution around deployment complexity and data sensitivity tiers. Channel economics diverge sharply between enterprise license sales and consumption-based SaaS metering.
Compression Type:
Channel flow splits between embedded licensing for hardware OEMs and standalone procurement by enterprise IT teams.
- Lossless:Bit-exact recovery algorithms using LZ4 and Zstandard libraries preserve transaction integrity for financial databases and medical records. German automotive suppliers embed these codecs into ECU firmware for warranty-compliant sensor logging.
- Lossy:Perceptual encoding methods discard non-critical data to achieve 10:1 to 100:1 ratios for video and audio streams. Cloud service providers in the United States deploy these at CDN edge nodes to reduce backbone transit costs.
- Adaptive:Dynamic switching between lossless and lossy modes based on content entropy and latency constraints.
- Dictionary-based:Pre-trained symbol tables accelerate compression for repetitive log files and genomic datasets.
- Entropy Encoding:Arithmetic and Huffman coding variants optimize symbol frequency distribution for archival storage systems.
Lossless dominates installed base. Lossy is where expansion concentrates.
Deployment Model:
Margin structures vary by infrastructure ownership — perpetual licenses carry higher upfront recognition while SaaS smooths revenue recognition over contract terms.
- On-Premises:Perpetual licensing with annual maintenance contracts serves regulated industries requiring air-gapped environments. Financial institutions in Switzerland deploy these for vault-stored backup tapes under national banking secrecy frameworks.
- Cloud-Based:Metered consumption tied to egress and storage tiers attracts mid-market buyers eliminating data center overhead. Indian SaaS startups leverage these deployments to bypass capital expenditure requirements under RBI digital lending guidelines.
- Hybrid:Policy-driven tiering between local and remote compression engines.
- Edge Computing:Sub-100-millisecond inference pipelines for industrial IoT gateways.
- SaaS:Fully managed API services with auto-scaling compute pools.
On-Premises anchors maintenance revenue. Cloud-Based is climbing the fastest.
Application Area:
Procurement authority concentrates with infrastructure teams for storage workloads and with content operations for media pipelines.
- Data Storage Optimization:Capacity reduction algorithms extend flash and disk array lifecycles. Japanese manufacturing conglomerates embed these into factory-floor MES systems under METI productivity targets.
- Media Streaming:Real-time transcoding for adaptive bitrate delivery. South Korean broadcasters deploy AV1 encoders to meet KCC bandwidth allocation rules for terrestrial multiplexes.
- Database Management:Page-level compression for OLTP and OLAP engines.
- Network Transmission:WAN acceleration for branch-to-datacenter traffic.
- Backup & Archiving:Deduplication-integrated compression for long-term retention.
Data Storage Optimization holds the largest footprint. Media Streaming shows steepest expansion trajectory.
End User:
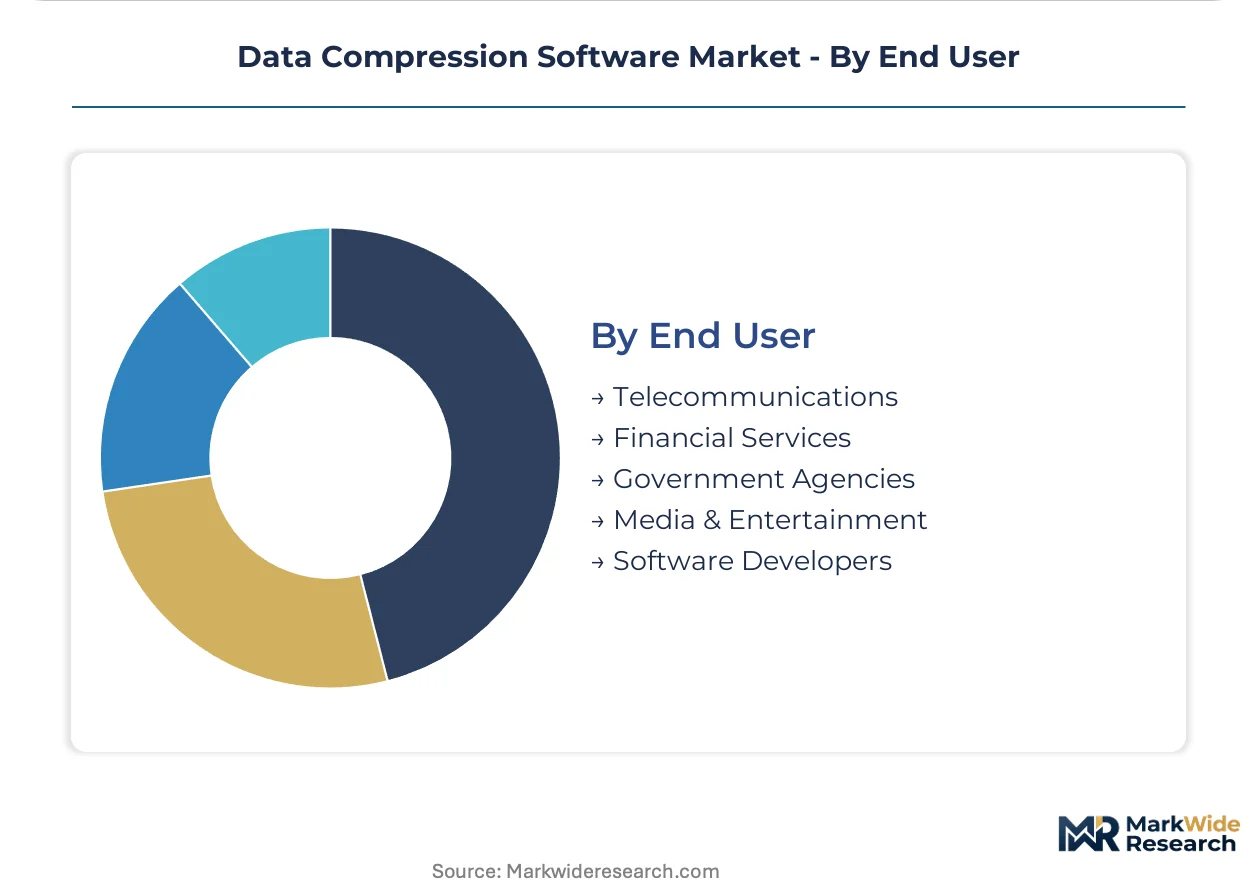
Contract structures diverge by procurement sophistication — telecommunications carriers negotiate volume commitments while government agencies require certification-heavy fixed-price awards.
- Telecommunications:Core network compression for signaling and user plane traffic. Brazilian operators deploy these under ANATEL infrastructure modernization mandates for 5G backhaul.
- Financial Services:Regulatory-compliant compression for trade reconstruction and audit trails. UK banks align deployments with FCA operational resilience requirements for secondary site recovery.
- Government Agencies:Classified environment deployments with FIPS 140-2 validation.
- Media & Entertainment:Post-production and distribution pipeline optimization.
- Software Developers:Embedded SDK licensing for application integration.
Telecommunications dominates committed volumes. Financial Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial IoT deployments while Indian SaaS providers compete on metered consumption economics. Cloud service providers in the United States extract premium margins from real-time video encoding workloads. European regulatory compliance costs create entry barriers that favor established vendors with GDPR-aligned preprocessing pipelines.
United States
FCC net neutrality frameworks and HIPAA storage requirements shape compression architectures for telecommunications and healthcare providers. Cloud service providers deploy AV1 and VVC silicon-integrated codecs at CDN edge nodes to reduce backbone transit costs. Silicon Valley hyperscalers anchor hardware-accelerated inference pipelines for sub-100-millisecond latency thresholds.
Germany
Industrial IoT sensor density from high-frequency vibration and thermal monitoring streams drives edge-native compression procurement. KBA automotive regulations and EU AI Act conformity assessments mandate technical documentation for preprocessing pipelines. Bavarian manufacturing clusters retrofit existing sensor data lakes with GDPR-compliant compression gateways.
India
Domestic data center buildouts under PLI scheme incentives attract edge-compression vendors to localize software stacks. RBI digital lending guidelines push mid-market buyers toward consumption-based SaaS deployments bypassing capital expenditure requirements. Bangalore and Hyderabad SaaS startups leverage metered cloud compression to eliminate data center overhead.
Japan
METI productivity targets embed capacity reduction algorithms into factory-floor MES systems for manufacturing conglomerates. JIS standards and national banking secrecy frameworks sustain perpetual licensing demand for air-gapped vault-stored backup tapes. Tokyo-based financial institutions deploy mainframe-to-cloud migration contracts with heritage storage vendors.
South Korea
KCC bandwidth allocation rules for terrestrial multiplexes drive AV1 encoder deployment among broadcasters. Smartphone OEMs adopt sub-10-megabyte autoencoder networks for camera pipeline optimization. Seoul Capital Area technology clusters miniaturize neural compression codecs for on-device inference across consumer electronics.
Data Compression Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Hyperscale cloud operators anchor premium pricing through integrated platform ecosystems while specialized compression vendors compete on algorithmic efficiency. Three archetypes dominate: infrastructure-integrated platforms, standalone algorithm specialists, and hardware-optimized codec licensors. Competitive moves concentrate on strategic partnerships for silicon integration and geographic expansion through localized compliance offerings.
Within the infrastructure-integrated tier, International Business Machines Corporation and Microsoft Corporation exemplify archetypes leveraging enterprise storage heritage and native cloud service embedding respectively. Google LLC occupies a position at the intersection of video codec integration and content delivery network scale. These three anchors represent distinct competitive vectors: mainframe-to-cloud migration contracting, Azure-embedded data services, and CDN-optimized streaming infrastructure.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Broadcom Inc. |
| Google LLC |
| NortonLifeLock Inc. |
| SAS Institute Inc. |
| Microsoft Corporation |
| Oracle Corporation |
| Corel Corporation |
| Meta Platforms Inc |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud infrastructure utilization rates above 80% compress unit economics for compression-as-a-service providers while concentrating pricing power among silicon-integrated codec licensors in the United States and Taiwan. This density dynamic forces mid-market SaaS vendors toward consumption-based metering models that sacrifice margin for volume retention.
Pricing Analysis
The customization-premium spread separates enterprise-configured compression pipelines from standard SaaS tiers by a factor of three to five in annual contract value. Three-tier pricing structure across premium, standard, and economy levels aligns with deployment complexity — air-gapped perpetual licenses command the highest tier, metered cloud APIs the lowest. Price differentiation hinges on GDPR compliance certification and hardware acceleration integration. Pricing pressure stems from GPU instance cost volatility eroding SaaS provider margins. Mid-market buyers exhibit highest price sensitivity; financial services procurement teams show lowest sensitivity due to regulatory mandate rigidity.
Supply Chain Analysis
The United States and Taiwan anchor semiconductor fabrication for hardware-accelerated codecs, while India and Germany concentrate software development and edge-deployment engineering. Raw material dependencies include advanced process node wafers from TSMC and Samsung, specialized NPU intellectual property from ARM and NVIDIA, and rare earth elements for magnetics in storage systems. Supply chain risk centers on single-source vulnerability for sub-5nm foundry capacity. Distribution runs through hyperscaler marketplaces, direct enterprise licensing, and embedded OEM royalties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data compression software market is in a cyclical recovery phase driven by cloud infrastructure refresh cycles following pandemic-era overbuild. Enterprise procurement normalization is restoring pricing discipline after two years of aggressive discounting.
For Market Incumbents: Shield installed base revenue by embedding compression deeper into data pipeline workflows rather than selling standalone tools. Accelerate vertical integration into silicon-optimized codec cores to reduce dependency on third-party NPU licensing. Patent pool participation in Access Advance and MPEG LA creates defensive moats against royalty stacking threats from emerging AV1 competitors.
For New Entrants and Emerging Players: Lead with quantum-resistant encryption convergence as a differentiated architecture for post-NIST standardization procurement cycles. Target Indian PLI-scheme data center buildouts where localized compliance requirements disadvantage foreign incumbents. Pursue API-first go-to-market positioning that embeds compression as invisible infrastructure rather than visible software procurement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-hardware co-design specialists over pure software optimization vendors. Long-term viability rests on NPU instruction set optimization capabilities that concentrate at semiconductor-adjacent firms. The signal to watch is AV1 silicon penetration rates in consumer devices as an inflection indicator for royalty-efficient codec displacement of HEVC.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Hardware Co-Design Partnership | TSMC N3E process integration with AV1 encoders reduces power consumption for smartphone OEMs. |
| GDPR-Compliant Preprocessing Pipeline Certification | EU AI Act technical documentation requirements create vendor lock-in for German automotive suppliers. |
| Edge-Native Compression SDK Localization | India PLI scheme incentives attract software stacks to domestic data center buildouts. |
| Neural Codec Miniaturization for On-Device Inference | South Korean smartphone OEMs adopt sub-10-megabyte autoencoders for camera pipeline optimization. |
| Quantum-Resistant Encryption-Convergent Architecture | NIST post-quantum standards create whitespace for lattice-optimized compression algorithms. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, CTOs, IT procurement officers, and channel partners at compression software vendors; and secondary validation against SEC filings, hyperscaler capex disclosures, patent pool licensing records, and EU regulatory submissions. Bottom-up triangulation across deployment model, organization size, vertical industry, and regional adoption pattern segments reconciled with top-down market sizing from infrastructure spend correlations.
Across the analysis window, the forecasting framework modeled compression type, deployment model, application area, and end-user industry dimensions. CAGRs derived from segment-level growth rate reconciliation against macro technology adoption curves. Industry-specific inputs included cloud storage growth trajectories, video streaming bandwidth demand curves, and industrial IoT sensor deployment densities.
Forecasts assume regulatory continuity in EU AI Act implementation and FCC net neutrality frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include quantum-resistant encryption standard acceleration, patent pool litigation outcomes, and hyperscaler vertical integration into compression silicon. Recalibration cycles align with material shifts in NIST cryptographic standardization and foundry capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Application Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Business Productivity Software Market
Software & Services
Content Curation Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Forestry Software Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Global Software Resellers Market
Software & Services
Application Server Market
Software & Services
PLM and Engineering Software Market
Software & Services
Data Preparation Tools Market
Software & Services
PLM Software Market