
 Global Content Management Systems (CMS) Market | 2026-2036
Global Content Management Systems (CMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Content Management Systems (CMS) Market Foresight
A shortage of full-stack CMS architects is unwinding deployment timelines for enterprise clients. WordPress leverages its open-source ecosystem to sustain developer loyalty across millions of active installations. Adobe Experience Manager anchors premium digital experience budgets through deep integration with creative workflows. Contentful competes by specializing in API-first architectures that decouple content from presentation layers.
Content management systems are software applications that enable users to create, edit, organize, and publish digital content through structured databases, templating engines, and role-based access controls. These systems serve the primary commercial purpose of reducing technical dependency for marketing teams while enforcing governance standards across distributed publishing environments. Cloud-based deployment leads solution uptake as organizations retire on-premises infrastructure, though hybrid configurations retain relevance in regulated sectors where data residency requirements persist. Web content management captures the largest solution share, while digital asset management represents the fastest-growing segment as video and rich media volumes expand across e-commerce portals and media publishing workflows.
The EU AI Act, GDPR, and ISO 27001 framework collectively shape vendor selection criteria by mandating algorithmic transparency, data localization, and information security management certifications. The US SEC and HIPAA impose additional compliance layers on CMS deployments within financial services and healthcare contexts. Stakeholders must monitor how fragmented regulatory requirements across jurisdictions influence total cost of ownership for multi-region implementations.
Market Dynamics
The migration from monolithic suites to composable architectures is fragmenting vendor lock-in patterns across enterprise procurement cycles. Cloud-native deployment models are forcing incumbents to restructure licensing frameworks while specialized API-first platforms capture developer mindshare.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and healthcare enterprises across Germany, France, and Italy are accelerating CMS replacement cycles to embed algorithmic transparency and audit trail capabilities required by the 2024 enforcement timeline.
- Headless architecture adoption:E-commerce and media publishers are decoupling content repositories from presentation layers, enabling simultaneous deployment across web, mobile, IoT, and emerging immersive channels without platform replication.
- India's digital infrastructure expansion:Government digitization initiatives and startup ecosystem maturation in Bangalore, Mumbai, and Hyderabad are driving localized CMS procurement for vernacular content management and regional compliance.
Market Restraints
- Specialized talent scarcity:Full-stack CMS architects capable of orchestrating distributed content graphs, edge caching, and multi-tenant security configurations command premium compensation that extends implementation timelines.
- Data residency enforcement:Brazil's LGPD, China's PIPL, and Saudi Arabia's PDPL are fragmenting cloud deployment architectures, requiring region-specific infrastructure investments that inflate total cost of ownership.
- Legacy system entrenchment:On-premises SharePoint and custom-built Java/.NET content repositories in regulated sectors carry sunk-cost dependencies that resist cloud migration despite operational inefficiencies.
Strategic Opportunities
- Indonesia's underpenetrated enterprise segment:Southeast Asia's largest economy exhibits low CMS saturation outside Jakarta, presenting first-mover advantages for localized SaaS offerings addressing Bahasa Indonesia content workflows.
- Generative AI content orchestration:Convergence of large language models with structured content repositories enables automated variant generation, translation, and personalization at scale for multinational publishers.
- ISO 27001 and SOC 2 certification premiums:Enterprise procurement committees are mandating information security management certifications that create margin expansion opportunities for compliant vendors against uncertified competitors.
Industry Challenges
- Multi-jurisdiction compliance engineering:Engineering teams must simultaneously satisfy GDPR data localization, HIPAA audit logging, and SEC record-keeping requirements without fragmenting user experience or content workflows.
- Integration complexity with ERP and CRM estates:Salesforce, SAP, and Oracle system interdependencies create brittle API connections that fail during high-velocity publishing events, requiring dedicated middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Content Management Systems (CMS) Market |
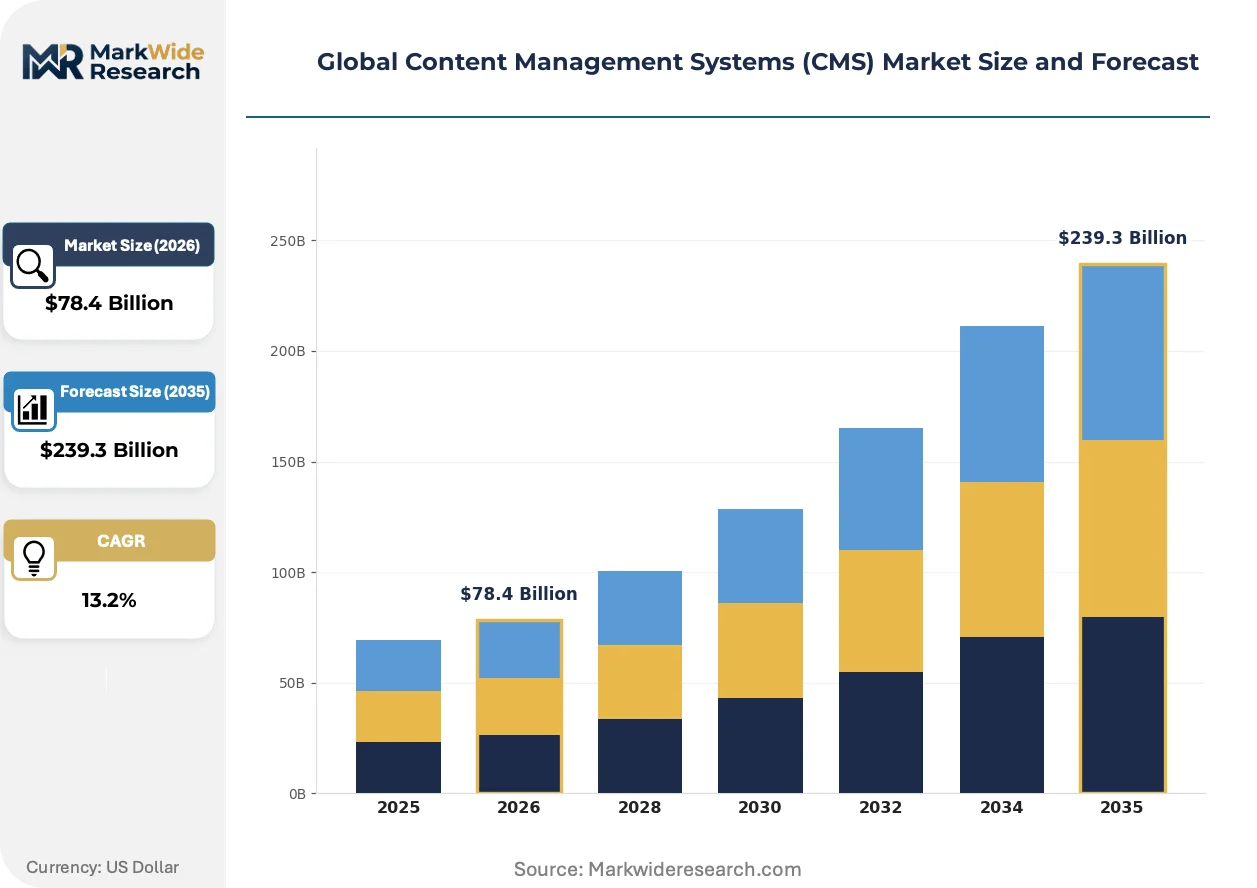
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $239.3 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Managed Services Solution/Offering: Web Content Management, Enterprise Content Management, Digital Asset Management, Document Management, Workflow Management Use Case: Corporate Websites, E-Commerce Portals, Educational Platforms, Media & Publishing, Government Portals End User Industry: Financial Services, Education Sector, Media Houses, Public Administration, Non-Governmental Organizations |
| Companies Covered | Sitecore, Drupal, WordPress, Contentstack, Wix, Shopify, Contentful, CoreMedia, Adobe Experience Manager, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Content Management Systems (CMS) Market Shifts & Advancements
Composable architecture principles are dissolving the boundaries between content management, digital asset management, and customer data platforms. Vendor specialization is accelerating as buyers reject one-size-fits-all suites in favor of best-of-breed integration.
Microservices-based content infrastructure is decomposing traditional monolithic CMS deployments into discrete, API-connected services for authoring, rendering, personalization, and analytics. Retail and media enterprises in the United States and United Kingdom are adopting this pattern fastest, with 18-24 month migration timelines replacing 5-7 year platform commitments. The structural consequence is compressing vendor consolidation economics while elevating integration-platform-as-a-service providers to critical supply chain positions.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for content recommendation engines deployed to European Union audiences. Publishers and e-commerce operators must now document training data provenance, bias testing protocols, and human oversight mechanisms. French and German regulatory authorities are conducting the first wave of compliance audits, with financial services CMS implementations facing the most immediate remediation deadlines.
Enterprise buying committees are consolidating vendor relationships and demanding outcome-based commercial structures tied to content velocity, engagement metrics, and conversion lift rather than seat-based or storage-based pricing. This pattern is most visible in North American B2B technology and financial services verticals, where procurement teams are reducing approved vendor lists from 12-15 platforms to 3-4 strategic partners with dedicated customer success investments.
Global Content Management Systems (CMS) Market Segmentation
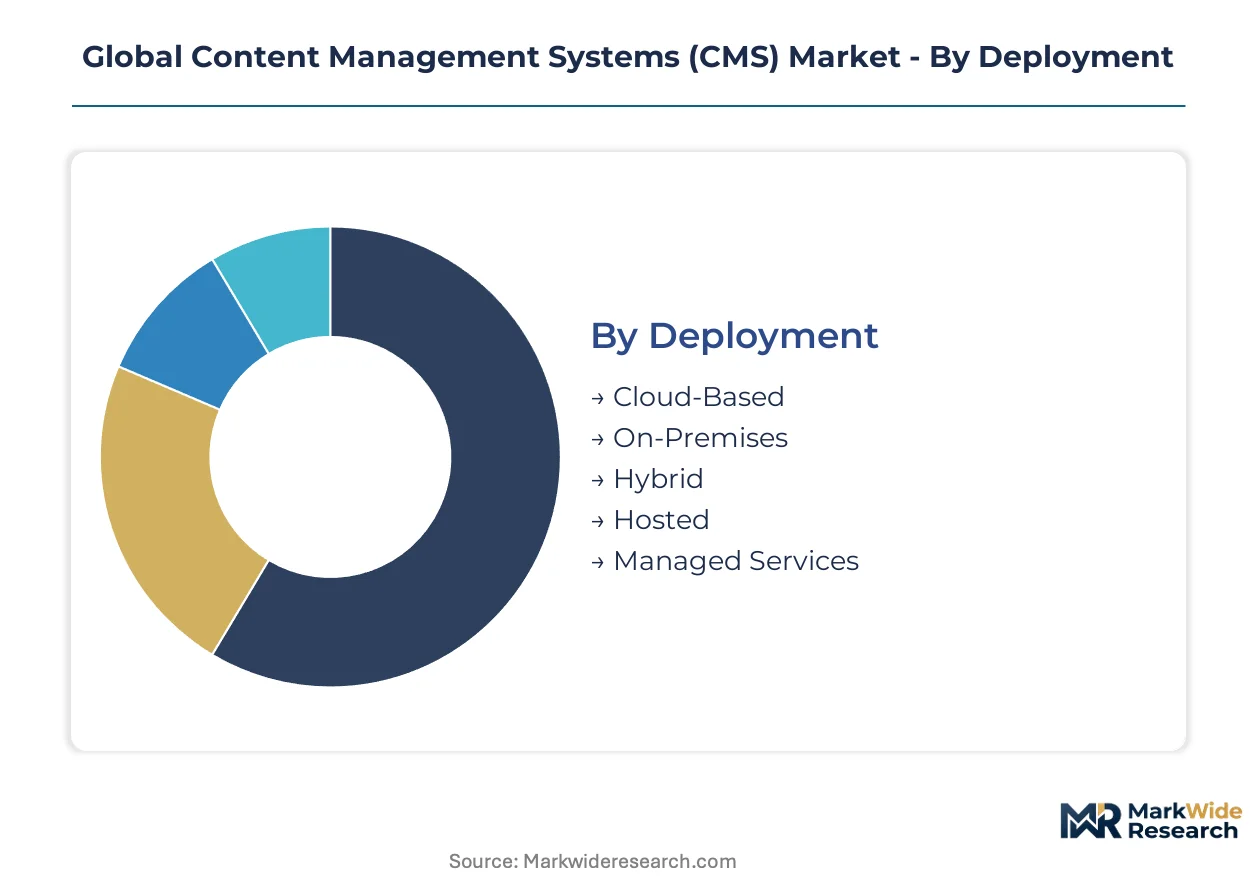
CMS procurement patterns diverge sharply across deployment architectures, solution types, and industry verticals. Understanding these fault lines enables vendors to align product roadmaps with buyer budget cycles and compliance requirements.
Deployment:
Cloud-based deployments dominate procurement in the United States, Germany, and India, while on-premises and hybrid configurations retain strongholds in regulated sectors where data residency mandates persist.
- Cloud-Based:Multi-tenant SaaS architectures with automatic scaling and continuous delivery pipelines. Financial services firms in New York and Frankfurt are accelerating migrations to satisfy EU AI Act audit trail requirements while retiring capital-intensive data center commitments.
- On-Premises:Self-hosted infrastructure with direct hardware control and customized security hardening. German automotive suppliers and Japanese pharmaceutical manufacturers maintain these deployments to satisfy ISO 27001 air-gapped requirements and national data sovereignty laws.
- Hybrid:Split workloads across private infrastructure and public cloud with orchestrated data synchronization. Brazilian banks and Saudi healthcare networks adopt this pattern to keep sensitive records local while pushing marketing content to edge delivery networks.
- Hosted:Single-tenant managed environments where vendors operate dedicated hardware on client behalf. Mid-market publishers in Australia and Canada prefer this model for predictable costs without operational overhead.
- Managed Services:Fully outsourced CMS operations including content operations, security patching, and performance optimization. Indian IT services providers capture significant share from European retailers seeking 24x7 vernacular content support.
Cloud-based holds the largest share; momentum sits with hybrid configurations bridging compliance and agility requirements.
Solution/Offering:
Enterprise procurement committees are consolidating around solutions that demonstrate measurable content velocity and engagement lift rather than feature breadth alone.
- Web Content Management:Core publishing platforms with templating engines, version control, and multi-channel rendering. E-commerce operators in the United Kingdom and United States prioritize these systems for conversion-optimized product detail page management.
- Digital Asset Management:Centralized repositories for video, image, and rich media with automated transcoding and rights management. Media houses in France and streaming platforms in South Korea are expanding storage volumes fastest as 4K and short-form video production accelerates.
- Enterprise Content Management:Document lifecycle platforms with records management, legal hold, and discovery capabilities. Public administration bodies in Italy and Spain deploy these for citizen service digitization and archival compliance.
- Document Management:Focused systems for creation, collaboration, and approval workflows on structured documents. Legal and professional services firms in Singapore and Switzerland standardize on these for contract versioning and client confidentiality.
- Workflow Management:Process orchestration tools connecting content creation with business approval chains. Non-governmental organizations across Sub-Saharan Africa adopt lightweight versions for grant reporting and field communication coordination.
Web content management anchors the majority of enterprise budgets; digital asset management is climbing the fastest as video-centric commerce expands.
Use Case:
Buyer sophistication varies dramatically across use cases, with corporate websites demanding governance sophistication and e-commerce portals prioritizing sub-second performance.
- E-Commerce Portals:Product information management with real-time inventory synchronization and personalized recommendation engines. Retailers in India and Indonesia invest heavily here as mobile-first shopping becomes dominant.
- Corporate Websites:Brand-controlled publishing with strict approval hierarchies and multi-language localization. Multinational B2B technology vendors in Germany and the United States standardize on these for investor relations and careers content.
- Media & Publishing:High-velocity editorial workflows with breaking news alerts and subscriber paywall integration. News organizations in Brazil and Nigeria leverage these for advertising yield optimization and audience segmentation.
- Educational Platforms:Learning management integration with accessibility compliance and mobile-responsive course delivery. Universities in Australia and South Africa deploy these for hybrid learning infrastructure post-pandemic.
- Government Portals:Citizen service platforms with WCAG accessibility mandates and multi-channel service delivery. Municipalities in Denmark and the Netherlands lead adoption for digital-first public service transformation.
Corporate websites command the highest per-seat pricing; e-commerce portals are expanding most quickly as direct-to-consumer channels proliferate.
End User Industry:
Regulatory intensity shapes vendor selection criteria, with financial services and public administration imposing the most stringent certification requirements.
- Financial Services:Banks, insurers, and asset managers requiring SEC audit logging, GDPR data lineage, and EU AI Act algorithmic transparency. Institutions in London, Zurich, and Singapore are replacing legacy platforms fastest to meet enforcement deadlines.
- Public Administration:National and local government bodies with accessibility mandates, record retention laws, and procurement transparency rules. Agencies in France and Germany lead European digitization with substantial CMS modernization budgets.
- Media Houses:Broadcasters, newspapers, and digital-native publishers monetizing through subscriptions and programmatic advertising. Consolidation in the United States and expansion in Southeast Asia drive diverging platform requirements.
- Education Sector:K-12 districts and higher education institutions with FERPA student privacy obligations and accessibility compliance. State university systems in the United States and vocational colleges in India represent contrasting procurement scales.
- Non-Governmental Organizations:International development and humanitarian organizations with distributed field operations and donor reporting requirements. Operations spanning Kenya, Bangladesh, and Colombia prioritize low-bandwidth optimization and offline functionality.
Financial services contributes the highest revenue per deployment; public administration represents the steepest expansion trajectory as government digitization accelerates across OECD and emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States and German enterprise procurement cycles, while Indian and Indonesian markets compete on localized cost structures and vernacular content capabilities.
United States
Financial services firms in New York and San Francisco are replacing legacy SharePoint installations with cloud-native architectures to satisfy SEC audit logging requirements. The 2024 EU AI Act extraterritorial provisions force US-based multinationals to embed algorithmic transparency into content recommendation engines. Chicago and Austin host the fastest-growing clusters of headless CMS implementations for B2B technology vendors.
Germany
Automotive suppliers in Munich and Stuttgart demand ISO 27001 air-gapped deployments for proprietary engineering documentation. The BSI IT-Grundschutz framework and GDPR enforcement by Hamburg's data protection authority shape vendor certification requirements. Berlin's startup ecosystem is driving API-first procurement for digital-native publishers expanding across DACH markets.
India
Government digitization initiatives and vernacular content mandates are accelerating CMS procurement in Bangalore, Mumbai, and Hyderabad. RBI data localization rules for financial services and the Digital India program create compliance-driven replacement cycles. Chennai and Pune host expanding delivery centers for European retailers seeking 24x7 content operations support.
United Kingdom
E-commerce operators in London and Manchester prioritize sub-second performance optimization for mobile-first shopping experiences. The UK GDPR retention and Financial Conduct Authority record-keeping rules extend audit trail requirements beyond EU baseline standards. Edinburgh's fintech cluster is emerging as a specialized demand center for compliance-integrated content workflows.
Indonesia
Jakarta-based enterprises represent the primary penetration point, with underdeveloped demand across Surabaya, Bandung, and Medan creating first-mover opportunities. The Ministry of Communication and Informatics data localization guidance and Bahasa Indonesia content requirements favor localized SaaS offerings. Bali's tourism technology sector is experimenting with headless architectures for multi-channel destination marketing.
Global Content Management Systems (CMS) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the CMS vendor base. Premium digital experience platforms with deep creative workflow integration command enterprise budgets in financial services and media verticals. Open-source ecosystems and API-first specialists capture developer mindshare through community-driven extensibility and composable architecture flexibility. The competitive dynamic centers on M&A activity consolidating adjacent capabilities and strategic partnerships embedding CMS functionality into broader enterprise software estates.
Within the premium enterprise tier, Adobe Experience Manager and Sitecore exemplify vendors anchoring high-value procurement cycles through integrated marketing cloud positioning. Contentful and Contentstack occupy positions as API-first specialists decoupling content infrastructure from presentation layers. WordPress represents the open-source archetype sustaining mass-market penetration through plugin ecosystem network effects.
| Leading Market Players |
|---|
| Sitecore |
| Drupal |
| WordPress |
| Contentstack |
| Wix |
| Shopify |
| Contentful |
| CoreMedia |
| Adobe Experience Manager |
| Others |
Supply & Pricing Matrix
Cloud-native infrastructure substitution for on-premises data centers simultaneously redistributes supply geography toward hyperscaler regions and compresses pricing economics for legacy vendors. This shift forces incumbent providers to restructure licensing frameworks while API-first specialists capture margin expansion through consumption-based models.
Pricing Analysis
Enterprise procurement cycles in the United States and Germany command 40-60% price premiums over equivalent deployments in India and Indonesia. Subscription-based SaaS tiers dominate, with differentiation driven by ISO 27001 certification status and integration complexity with existing ERP estates. Cost compression in mid-market segments intensifies as open-source alternatives mature, while financial services buyers exhibit lowest price sensitivity due to compliance mandates.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native implementations, though regulated sectors maintain strategic stockpiles of on-premises capacity for data residency compliance. Supply concentrates in the United States, Germany, and India, with component dependencies spanning hyperscaler infrastructure, edge caching networks, and identity management services. Single-source vulnerability runs through concentrated hyperscaler regions, while distribution runs through direct vendor sales and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act enforcement timeline creates a high-growth disruption window as enterprises accelerate replacement cycles to embed algorithmic transparency and audit capabilities.
For Market Incumbents: Shield market position by accelerating ISO 27001 and SOC 2 certification roadmaps before procurement committees narrow approved vendor lists. Deepen API ecosystem investments to counter API-first specialists displacing monolithic architectures in developer evaluations. For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated enterprise segment outside Jakarta, where Bahasa Indonesia content workflows and data localization guidance favor localized SaaS offerings. Target mid-market retailers with managed services wrappers that bundle 24x7 content operations. For Investors and Strategic Acquirers: Capital is best deployed toward API-first platforms with established developer communities and vertical-specific compliance integrations. Watch for inflection when EU AI Act audit findings trigger replacement waves in financial services procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe Experience Manager deepens creative workflow embedding to defend enterprise budgets. |
| Acquisition of Specialist Firm | API-first vendors absorb DAM capabilities to capture video-centric commerce expansion. |
| Strategic Partnership | Systems integrators embed CMS functionality into broader digital transformation contracts. |
| Geographic Expansion | Localized SaaS offerings address Bahasa Indonesia and vernacular content requirements in Southeast Asia. |
| Product Launch | Generative AI content orchestration modules enable automated variant generation for multinational publishers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement notices. Interviews with CTOs, IT procurement officers, platform engineers, and integration specialists inform demand-side validation. Bottom-up deployment estimates triangulate against top-down vendor revenue analysis across cloud-based, on-premises, and hybrid configurations.
Segmentation dimensions modeled include deployment architecture, solution type, use case complexity, and end-user industry regulatory intensity. CAGRs derive from regression analysis of historical adoption curves and forward projection of compliance-driven replacement cycles. Integration complexity with Salesforce, SAP, and Oracle estates and edge caching performance requirements inform forecast sensitivity.
Underlying assumptions cover sustained EU AI Act enforcement rigor and continued hyperscaler infrastructure expansion, with deviation risk concentrated in data residency regulation fragmentation and talent scarcity extending implementation timelines. Revision becomes warranted when compliance audit failure rates cross thresholds that accelerate procurement committee vendor consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Parametric Design Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Recruiting Software Market
Software & Services
Procurement Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Image Analysis Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Document Capture Software Market
Software & Services
Batch Management Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Global Mobile Middleware Market
Software & Services
Global SAP S-4HANA Application Market