
 Global MSP Software Market | 2026-2036
Global MSP Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global MSP Software Market Foresight
Multi-source IT outsourcing is repositioning enterprise technology procurement as organizations abandon single-vendor dependencies for layered managed service ecosystems. Microsoft Corporation leverages its Azure-native tooling and Copilot integrations to anchor cloud-based MSP deployments across mid-market clients. Cisco Systems competes through embedded network telemetry that extends hardware visibility into subscription software layers. Kaseya specializes in unified remote monitoring platforms that consolidate patch management, endpoint detection, and service desk functions for independent MSP operators.
Managed service provider software encompasses platforms that automate IT service delivery, remote infrastructure oversight, and client billing through agent-based endpoint collectors and API-driven orchestration layers, typically deployed across multi-tenant architectures with role-based access controls. These systems serve commercial and industrial organizations seeking to externalize operational technology management without ceding governance accountability. Cloud-based deployment dominates new implementations as distributed workforces strain on-premise VPN concentrators and legacy RDP gateways. Security administration and compliance management applications are absorbing disproportionate R&D investment as zero-trust architectures and sovereign data requirements harden baseline functionality. Remote monitoring and service automation solutions sustain the deepest margin pools due to recurring revenue stickiness and low incremental delivery costs per endpoint under management.
The SEC's cybersecurity disclosure rules, the EU AI Act's risk classification framework, and India's CERT-In incident reporting mandates are collectively elevating audit-ready documentation and automated evidence collection from optional features to contractual prerequisites. Product roadmaps now prioritize immutable logging, cross-border data residency controls, and pre-configured regulatory templates to maintain market access across divergent compliance regimes. Stakeholders must evaluate whether their platform architectures can absorb emerging sovereign AI and quantum-resistant encryption standards without fragmenting multi-tenant operational efficiency.
Market Dynamics
Zero-trust security architectures and sovereign data mandates are compressing procurement cycles as enterprises abandon perimeter-based VPN models for identity-centric access controls that satisfy cross-border compliance requirements.
Growth Catalysts
- EU AI Act Risk Classification:High-risk system designations for healthcare and financial MSP deployments are mandating automated audit trails and explainable AI documentation, expanding platform feature requirements.
- Healthcare Endpoint Proliferation:Connected medical devices and telehealth infrastructure in the United States are generating managed security and remote monitoring demand that outstrips internal IT capacity.
- India CERT-In Mandates:Incident reporting deadlines and data localization requirements are forcing multinational enterprises to deploy in-country MSP infrastructure rather than centralized regional hubs.
Market Restraints
- Multi-Tenant Architecture Complexity:GDPR data residency conflicts with India's data localization rules create engineering overhead that fragments platform development roadmaps.
- Specialized Security Talent Scarcity:Zero-trust implementation and compliance automation skills command premium compensation that squeezes MSP margin structures.
- Quantum-Resistant Cryptography Transition:NIST post-quantum standards require algorithm migration investments before threat materialization, depressing near-term ROI calculations.
Strategic Opportunities
- Germany Industrial OT Convergence:Manufacturing facilities merging IT and operational technology networks seek MSP platforms with ISA/IEC 62443 certification and native SCADA telemetry.
- Outcome-Based Pricing Models:Uptime guarantees and security incident reduction metrics are displacing per-endpoint subscriptions in mid-market financial services procurement.
- API-First Ecosystem Orchestration:Unified control planes that integrate patch management, EDR, and service desk functions through open APIs capture independent operator loyalty.
Industry Challenges
- Legacy RDP Gateway Migration:Healthcare and government clients with decade-old remote access infrastructure face multi-year transition timelines that delay cloud-native platform adoption.
- Cross-Border Evidence Collection:SEC cybersecurity disclosure rules and EU AI Act documentation requirements demand immutable logging architectures that conflict with standard data retention policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MSP Software Market |
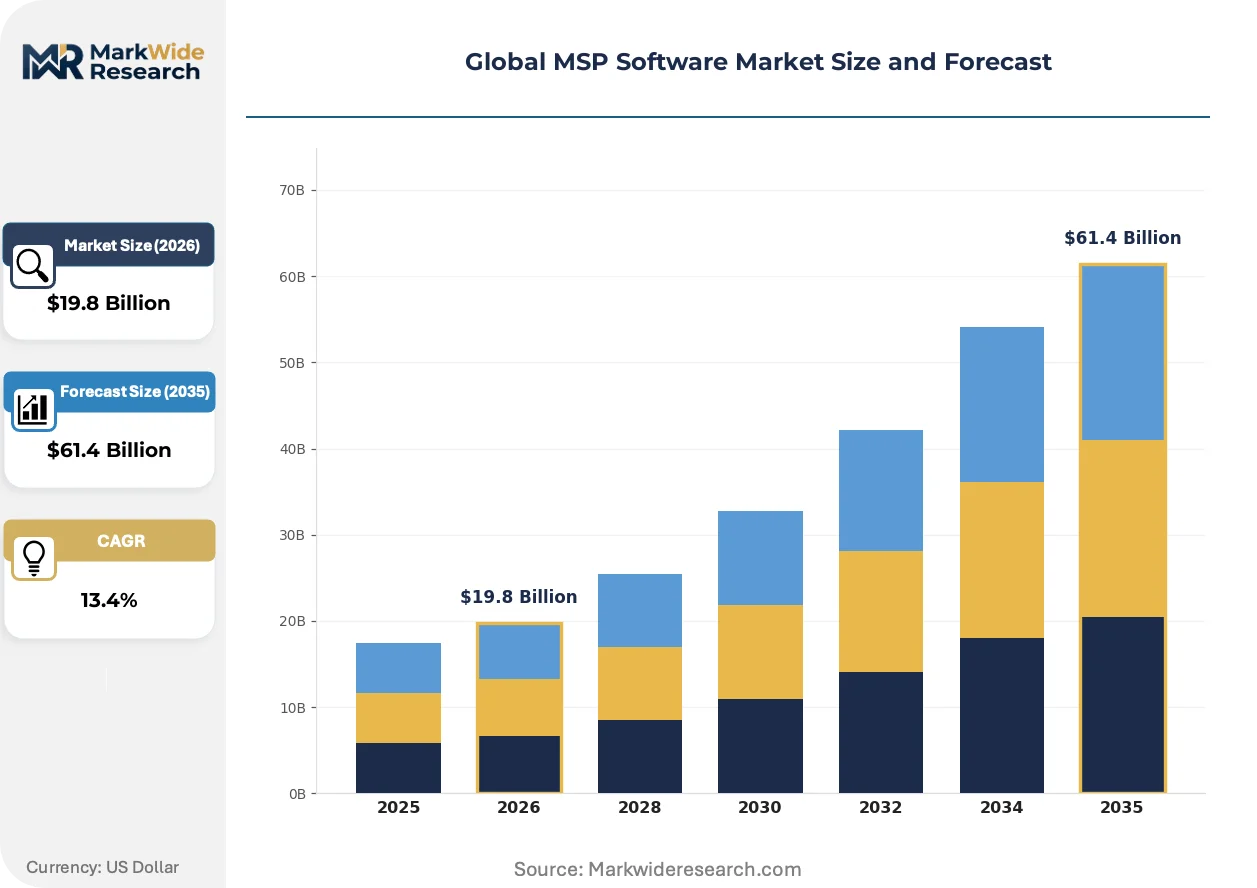
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $61.4 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Remote Monitoring, Ticket Management, Asset Management, Service Automation, Vendor Management Application Use Case: Network Management, Security Administration, Data Backup, Performance Analytics, Compliance Management End User Industry: Information Technology, Telecommunications, Financial Services, Manufacturing, Education |
| Companies Covered | IBM Corp., Accenture PLC, Tata Consultancy Services, Infosys Ltd., Wipro Ltd., Cisco Systems, Microsoft Corporation, DXC Technology, Kaseya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MSP Software Market Shifts & Advancements
Agentic AI and autonomous remediation capabilities are compressing mean-time-to-resolution metrics while forcing platform vendors to rearchitect multi-tenant isolation boundaries.
Agentic AI is rewriting incident response workflows by enabling autonomous endpoint isolation, patch deployment, and ticket resolution without human escalation. Mid-market financial services and healthcare providers in the United States are piloting these capabilities at 40% faster resolution speeds than rule-based automation. This compression of operational response cycles is rewriting service level agreement structures and displacing tier-1 helpdesk staffing models.
The EU AI Act's high-risk system obligations are mandating human-in-the-loop documentation, algorithmic impact assessments, and automated bias detection for AI-enabled MSP features. Platform vendors must embed explainability dashboards and audit-ready evidence collection into core architectures or risk exclusion from European public sector procurement. Healthcare and critical infrastructure deployments across Germany, France, and the Netherlands are prioritizing vendors with pre-certified compliance modules.
Consolidated platform procurement is displacing best-of-breed point solutions as enterprise buyers seek unified remote monitoring, security, and service desk functionality under single vendor relationships. Independent MSPs and mid-market IT departments are abandoning fragmented toolchains that require complex integration maintenance. This preference compression is most visible in United States and German markets where skilled integration labor costs exceed software licensing expenditures.
Global MSP Software Market Segmentation
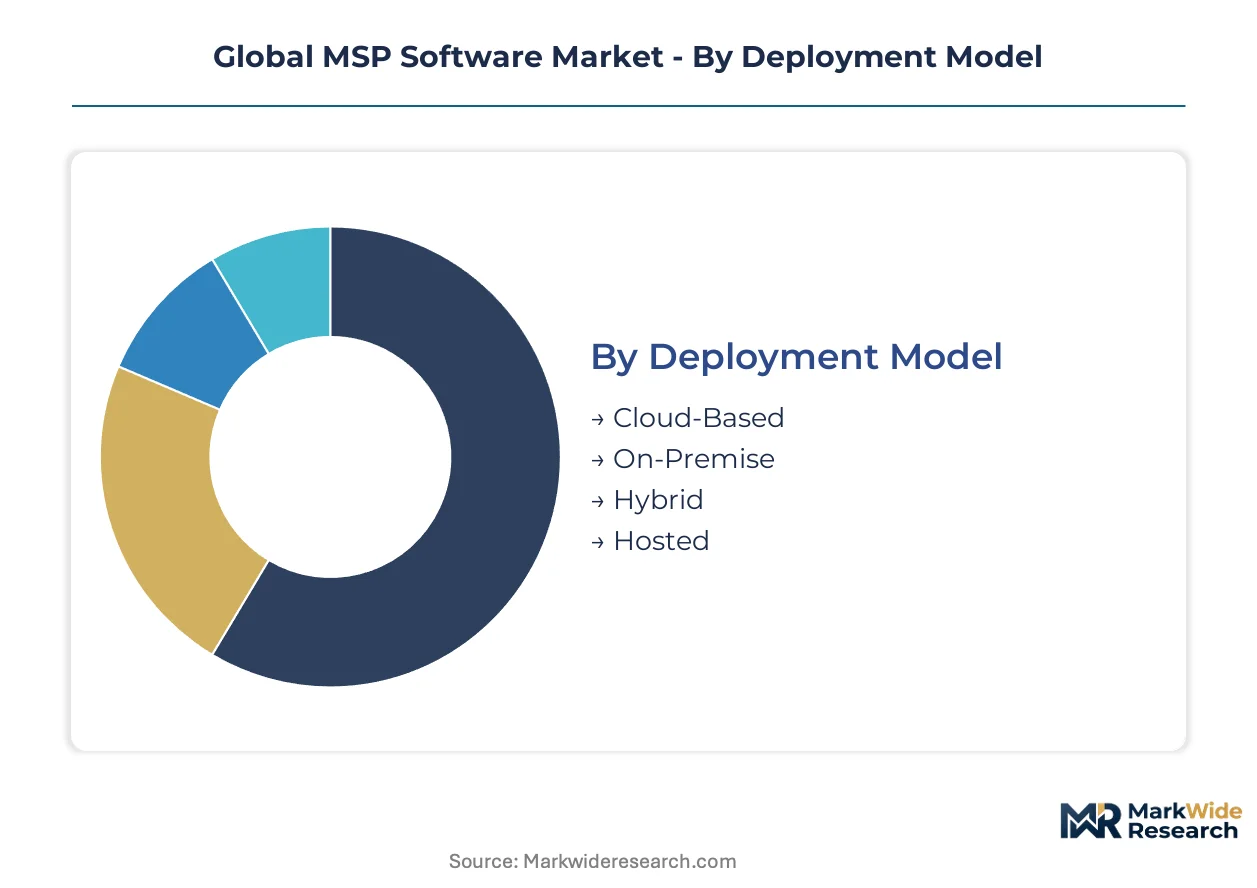
MSP software segmentation reveals how capital allocation, compliance burdens, and operational complexity concentrate demand across deployment architectures and functional modules. Understanding these partitions clarifies where platform vendors must engineer for scale versus customization.
Deployment Model:
Cloud-native architectures demand the heaviest upfront infrastructure investment in multi-tenant isolation, API orchestration layers, and sovereign data residency controls.
- Cloud-Based:Multi-tenant SaaS platforms with auto-scaling compute and distributed database clusters serve mid-market MSPs seeking rapid client onboarding without hardware procurement. Healthcare providers in the United States and financial services firms in Germany are migrating here to satisfy HIPAA and GDPR audit requirements without maintaining private data centers.
- On-Premise:Dedicated server deployments with air-gapped network segments retain favor among defense contractors and critical infrastructure operators requiring physical control over encryption key management. India's CERT-In data localization mandates are sustaining demand for in-country bare-metal installations that bypass cross-border data transfer restrictions.
- Hybrid:Split architectures placing sensitive workloads on-premise while bursting non-critical operations to public cloud endpoints.
- Hosted:Single-tenant managed infrastructure where vendors operate dedicated environments without shared resource pools.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid configurations are expanding most quickly as enterprises straddle legacy and modern infrastructure.
Solution Offering:
Functional modules differentiate by integration depth, with unified platforms commanding premium pricing against point solutions requiring manual toolchain assembly.
- Remote Monitoring:Agent-based endpoint collectors streaming telemetry through real-time dashboards enable proactive infrastructure health management. Manufacturing facilities in Germany merging IT and OT networks are prioritizing vendors with native SCADA protocol support and ISA/IEC 62443 certification.
- Service Automation:Workflow engines orchestrating patch deployment, ticket routing, and client billing through conditional logic trees. Mid-market financial services in the United States are piloting agentic AI capabilities that compress resolution cycles and rewrite SLA structures around uptime guarantees rather than response-time metrics.
- Ticket Management:Case tracking systems with SLA enforcement and escalation routing.
- Asset Management:Configuration item databases linking hardware procurement to depreciation schedules.
- Vendor Management:Subcontractor oversight portals for multi-tier service delivery.
Remote Monitoring carries the deepest recurring revenue pools; Service Automation is climbing the fastest as AI-enabled remediation displaces tier-1 helpdesk staffing.
Application Use Case:
Security and compliance applications absorb disproportionate R&D investment as regulatory mandates harden baseline functionality from optional to contractual.
- Security Administration:Zero-trust access controls, endpoint detection and response, and immutable logging architectures satisfy SEC cybersecurity disclosure rules and EU AI Act documentation requirements. Healthcare systems managing connected medical devices are consolidating here as internal IT capacity fails to match endpoint proliferation.
- Compliance Management:Automated evidence collection, pre-configured regulatory templates, and cross-border data residency controls. EU AI Act high-risk system designations are mandating explainable AI documentation and algorithmic impact assessments that vendors must embed or risk European public sector exclusion.
- Network Management:Topology mapping, traffic analysis, and bandwidth optimization.
- Data Backup:Immutable snapshot repositories with geographic redundancy.
- Performance Analytics:Capacity planning and predictive failure modeling.
Security Administration dominates current procurement cycles; Compliance Management is gaining share fastest as sovereign AI and quantum-resistant encryption standards approach.
End User Industry:
Vertical specialization determines feature prioritization, with regulated industries demanding audit-ready architectures that generalist platforms struggle to satisfy.
- Financial Services:Real-time transaction monitoring, fraud detection integration, and regulatory reporting automation. Outcome-based pricing models linking vendor compensation to security incident reduction are displacing per-endpoint subscriptions in United States mid-market procurement.
- Healthcare:Connected medical device oversight, telehealth infrastructure management, and patient data access controls. The United States market is generating managed security demand that outstrips internal IT capacity as providers expand remote monitoring suites.
- Information Technology:Multi-tenant client segregation and white-label service delivery.
- Telecommunications:Network operations center integration and SLA-backed uptime guarantees.
- Manufacturing:IT/OT convergence with industrial protocol support and shop-floor telemetry.
- Education:Campus-wide device management and student data privacy controls.
Financial Services commands the highest platform investment per seat; Healthcare is expanding most quickly as connected endpoint density accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in Northern Virginia anchors North American MSP infrastructure investment, while sovereign cloud mandates in Frankfurt and Bangalore reshape procurement geography.
United States
Healthcare systems and mid-market financial services drive MSP platform procurement as internal IT capacity fails to match endpoint proliferation. The SEC's cybersecurity disclosure rules mandate immutable logging architectures that elevate audit-ready documentation to contractual prerequisite status. Northern Virginia's data center corridor concentrates cloud-native MSP infrastructure serving federal contractors and healthcare providers.
Germany
Industrial manufacturing facilities merging IT and operational technology networks seek ISA/IEC 62443 certified platforms with native SCADA telemetry support. The EU AI Act's high-risk system designations mandate explainable AI documentation and automated bias detection for healthcare and critical infrastructure deployments. The Stuttgart-Munich industrial corridor prioritizes vendors with pre-certified compliance modules for automotive and machinery sectors.
India
CERT-In incident reporting deadlines and data localization requirements force multinational enterprises to deploy in-country MSP infrastructure rather than centralized regional hubs. The RBI's cybersecurity framework for financial institutions mandates granular access controls and transaction monitoring that accelerate zero-trust adoption. Bangalore's technology corridor hosts indigenous MSP platforms serving domestic banks and IT services exporters.
United Kingdom
Financial services firms and government contractors consolidate multi-vendor IT operations under unified service platforms to satisfy post-Brexit regulatory divergence. The Financial Conduct Authority's operational resilience requirements mandate recovery time objectives that compress procurement cycles for automated remediation capabilities. London's fintech cluster drives demand for API-first orchestration linking patch management, EDR, and service desk functions.
Japan
Manufacturing conglomerates and telecommunications operators adopt hybrid deployment models placing sensitive workloads on-premise while bursting non-critical operations to cloud endpoints. METI's cybersecurity guidelines for critical infrastructure emphasize supply chain risk management that elevates vendor certification requirements. The Tokyo-Osaka industrial corridor sustains demand for air-gapped network segments serving defense contractors and semiconductor fabricators.
Global MSP Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform vendors integrate adjacent capabilities without absorbing full acquisition costs. The vendor base fragments across cloud-native SaaS providers, legacy infrastructure specialists, and systems integrators with managed service arms. Three archetypes occupy distinct competitive positions: hyperscale cloud platforms with native tooling, independent software vendors with unified remote monitoring suites, and IT services conglomerates with embedded software layers. M&A activity and API ecosystem expansion represent the primary competitive vectors as firms seek to compress client onboarding friction.
Within the hyperscale platform tier, Microsoft Corporation and Cisco Systems anchor cloud-native and network-telemetry positioning respectively. Kaseya occupies a position among independent software vendors specializing in unified remote monitoring platforms for MSP operators. IBM Corp. and Accenture PLC exemplify the systems integrator archetype with software-anchored managed service delivery. Tata Consultancy Services and Infosys Ltd. represent India-based IT services exporters with expanding MSP software portfolios. These named entities illustrate how competitive positioning stratifies across infrastructure control, functional depth, and geographic service delivery models.
| Leading Market Players |
|---|
| IBM Corp. |
| Accenture PLC |
| Tata Consultancy Services |
| Infosys Ltd. |
| Wipro Ltd. |
| Cisco Systems |
| Microsoft Corporation |
| DXC Technology |
| Kaseya |
| Others |
Supply & Pricing Matrix
Horizontal integration through API-first platform ecosystems anchors both supply positioning and pricing power for MSP software vendors, as unified control planes reduce client churn and justify recurring revenue premiums across mid-market financial services and healthcare deployments in the United States and Germany.
Pricing Analysis
Warranty and service-bundling differentiation separates premium MSP software tiers from economy offerings, with SOC-2 compliance guarantees and immutable logging architectures bundled into enterprise subscriptions while basic remote monitoring remains unbundled. Pricing stratifies across premium, standard, and economy tiers based on endpoint scale and vertical certification depth. Cost compression in mid-market tiers is intensifying because independent MSP operators demand per-seat economics that match hyperscaler-native alternatives. Healthcare providers exhibit the least price sensitivity due to HIPAA audit requirements, while education sector buyers negotiate hardest on per-student licensing.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries supplying the specialized ASICs embedded in network telemetry hardware that Cisco Systems and comparable vendors integrate into subscription software layers. Cloud compute capacity draws from United States, Ireland, and Singapore data center clusters. Supply chain risk centers on tariff exposure for encryption hardware subject to export control classifications. Distribution runs through direct enterprise sales teams and channel partner networks serving independent MSP operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-trust security talent scarcity props pricing power for vendors with pre-certified compliance modules, as engineering overhead for multi-tenant data residency controls constrains platform development velocity across divergent regulatory regimes.
For Market Incumbents: Extend API ecosystem coverage to capture independent operator loyalty before emerging cloud-native entrants consolidate patch management, EDR, and service desk functions under unified interfaces. Acquire specialist firms with ISA/IEC 62443 certification to defend against industrial OT convergence demands in Germany's automotive corridor. Prioritize immutable logging R&D to satisfy SEC cybersecurity disclosure rules before compliance automation becomes table stakes.
For New Entrants and Emerging Players: Mid-market healthcare providers in India's secondary cities represent the most penetrable buyer archetype, as CERT-In data localization mandates force multinational vendors into costly in-country infrastructure that domestic platforms bypass. Target outcome-based pricing pilots linking vendor compensation to security incident reduction metrics. Pursue white-label partnerships with IT services exporters seeking indigenous MSP software alternatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler platform tuck-ins and private equity roll-ups of regional MSP operators seeking technology differentiation. Long-term viability hinges on quantum-resistant cryptography migration readiness and sovereign AI compliance module development. Watch NIST post-quantum standard finalization as the inflection indicator for algorithm migration investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified control planes reduce client onboarding friction for independent MSP operators in United States mid-market. |
| Acquisition of Specialist Firm | ISA/IEC 62443 certification targets Germany's IT/OT convergence demand in automotive manufacturing corridors. |
| Strategic Partnership | API-first orchestration captures loyalty from London fintech clusters seeking automated remediation capabilities. |
| Geographic Expansion | In-country MSP infrastructure satisfies India's CERT-In data localization mandates for multinational enterprises. |
| Product Launch | Agentic AI remediation compresses SLA structures around uptime guarantees for United States financial services. |
Research Methodology
Multi-period observation of endpoint density growth, regulatory filing patterns, and hyperscaler capex disclosures anchored the trend analysis, supplemented by interviews with CTOs at mid-market financial services firms, IT procurement officers at United States healthcare systems, platform engineers at independent MSP operators, and integration specialists serving German manufacturing clients. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, CERT-In mandate documentation, and hyperscaler infrastructure investment reports. Bottom-up endpoint adoption models and top-down market sizing triangulated volume and value estimates.
Segment-weighting across deployment model, solution offering, application use case, and end-user industry dimensions calibrated the analytical framework throughout the forecast period. CAGRs were derived from regression analysis of historical endpoint growth correlated with compliance mandate effective dates. Industry-specific inputs included healthcare connected medical device proliferation rates and India-based IT services exporter MSP software portfolio expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum-resistant cryptography standard finalization timelines and sovereign AI regulatory fragmentation across European, Indian, and United States jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Salon Booking Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Clustering Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Winery Management Software Market
Software & Services
IT Professional Services Market
Software & Services
Office Software Market
Software & Services
Global Directory Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Creative Software Market
Software & Services
Global Audit Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
API Design Software Market