
 Global Computer Assisted Coding Market | 2026-2036
Global Computer Assisted Coding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer Assisted Coding Market Foresight
Software vendor capacity in North America is hardening around clinical natural language processing engines and cloud-native architectures. 3M Company leverages its long-standing encoder technology relationships with large health systems to sustain recurring revenue streams. Nuance Communications Inc. anchors its position through voice recognition integration with computer-assisted coding workflows. Optum Inc. competes by combining payer data assets with provider-facing coding tools, creating differentiated analytics depth.
Computer assisted coding refers to software systems that analyze clinical documentation using natural language processing and rules-based algorithms to suggest or assign standardized medical codes, typically operating at processing speeds exceeding thousands of charts per hour to support revenue cycle management and compliance verification. The technology serves primarily to reduce manual coding labor, minimize claim denial rates, and accelerate reimbursement timelines for healthcare providers. Natural language processing capabilities within encoder software represent the fastest-expanding capability layer, as vendors race to parse unstructured physician notes with greater semantic accuracy. Cloud-based and SaaS platforms are displacing on-premise installations among mid-size hospitals seeking lower capital commitment and faster implementation cycles.
FDA oversight of clinical decision support software, HIPAA security requirements for protected health information, and the HITECH Act's meaningful use provisions collectively shape product development roadmaps and procurement criteria for healthcare technology buyers. ISO 27001 certification and SOC 2 compliance have become baseline prerequisites for vendor qualification in enterprise hospital RFP processes. Stakeholders must monitor evolving CMS reimbursement rule changes and state-level privacy laws that could alter coding specificity requirements and deployment architecture decisions.
Market Dynamics
Natural language processing engines are compressing coding cycle times from days to hours, forcing hospital revenue cycle departments to restructure staffing models around exception-handling rather than line-by-line review.
Growth Catalysts
- ICD-10-CM/PCS complexity:The expanded code set in the United States demands algorithmic assistance to maintain accuracy at scale, particularly for procedure coding in surgical specialties.
- Cloud-native architectures:SaaS deployment models eliminate capital expenditure barriers for mid-size hospitals, accelerating procurement cycles and reducing IT backlog constraints.
- United States:Federal penalties for coding errors under Medicare's quality reporting programs create institutional pressure for automated compliance verification.
Market Restraints
- Implementation costs:Health systems face substantial integration expenses connecting CAC platforms to existing electronic health record infrastructures, particularly Epic and Cerner environments.
- Physician documentation variability:Unstructured clinical notes contain idiosyncratic abbreviations and specialty-specific terminology that degrade NLP accuracy, requiring persistent model retraining.
- HIPAA security requirements:Protected health information handling mandates impose architectural constraints on cloud deployments, particularly for smaller vendors lacking enterprise-grade compliance infrastructure.
Strategic Opportunities
- Outpatient and ambulatory settings:United States physician practices and surgical centers remain underpenetrated relative to inpatient hospital adoption, presenting expansion headroom for specialized CAC modules.
- Real-time coding integration:Convergence of voice recognition with live documentation is enabling point-of-care code suggestion, compressing the revenue cycle to discharge.
- India:The country's expanding health insurance coverage and digitization push under the Ayushman Bharat scheme create demand for coding standardization in emerging corporate hospital chains.
Industry Challenges
- Clinical coder workforce shortages:Experienced certified professional coders command premium salaries, constraining health system capacity to supervise and validate automated outputs.
- Interoperability friction:HL7 FHIR implementation gaps between vendor platforms and hospital EHR systems delay go-live timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer Assisted Coding Market |
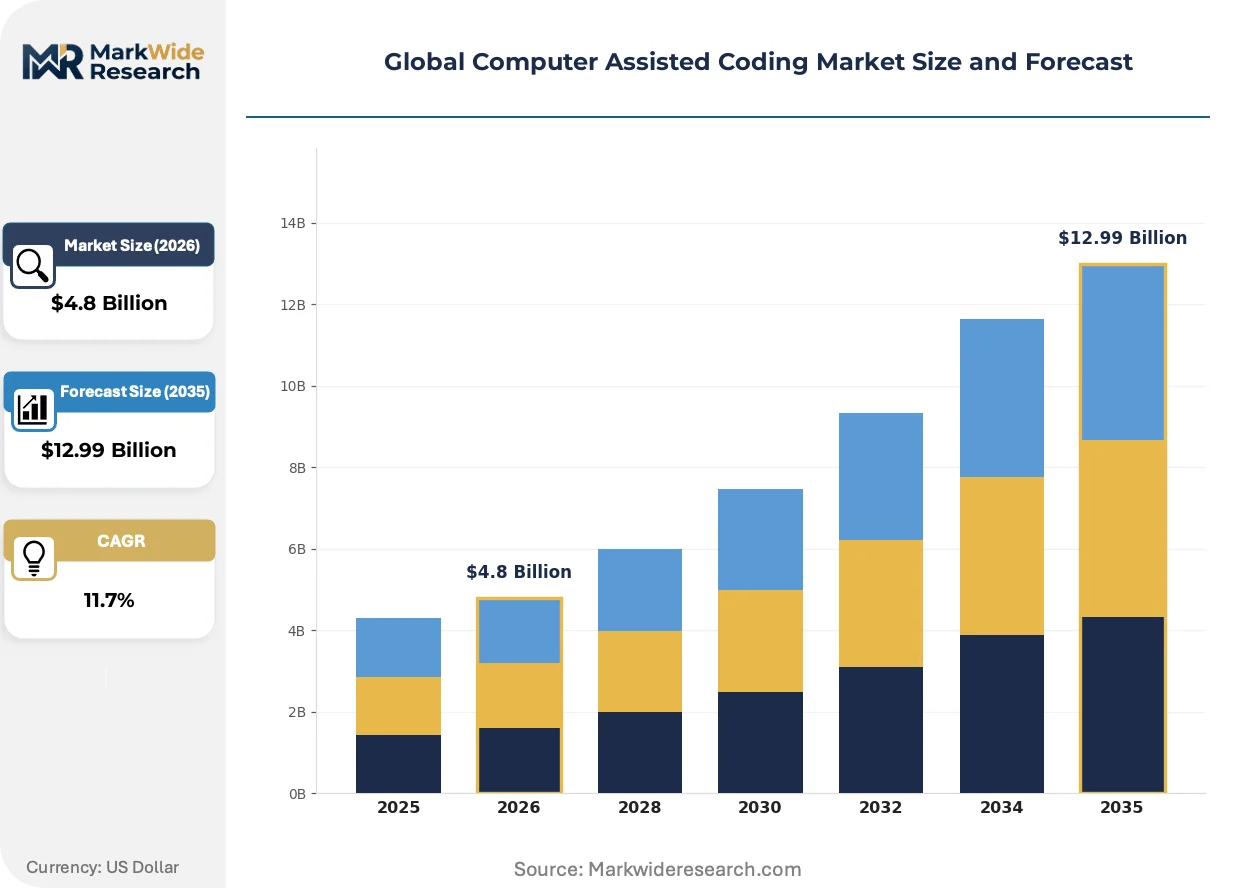
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encoder Software, Natural Language Processing, Computer-Assisted Coding Software, Automated Coding Systems Application: Medical Billing, Health Record Analysis, Clinical Documentation Improvement, Regulatory Compliance End User: Hospitals, Insurance Providers, Medical Coding Agencies, Physician Offices Deployment: On-Premise, Cloud-Based, Hybrid Systems, SaaS Platforms |
| Companies Covered | 3M Company, Cerner Corporation, Optum Inc., Nuance Communications Inc., Oracle, Epic Systems Corporation, Artificial Medical Intelligence Inc., Craneware PLC, Dolbey Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer Assisted Coding Market Shifts & Advancements
Large language models trained on clinical corpora are rewriting how documentation transforms into billable codes, compressing the traditional encoder workflow into near-real-time processing pipelines.
Transformer-based clinical NLP is rewriting the accuracy benchmarks for concept extraction from unstructured physician narratives. Academic medical centers in the United States are piloting these models for complex surgical case coding, reducing retrospective query volumes by enabling concurrent documentation improvement. The technology is rewriting competitive requirements for vendor RFPs, as health systems now demand demonstrable semantic understanding capabilities alongside traditional rules-based engines.
The EU AI Act's risk classification framework for medical device software is reshaping product development roadmaps for vendors seeking European market access. High-risk categorization for coding systems that influence reimbursement decisions will mandate conformity assessment procedures and post-market surveillance obligations. Vendors are responding by establishing EU authorized representatives and restructuring quality management systems to satisfy MDR-aligned expectations.
Hospital procurement departments are consolidating vendor relationships around integrated revenue cycle platforms rather than standalone coding modules. United States health systems increasingly demand bundled contracts spanning clinical documentation improvement, coding automation, and denial management analytics. This preference shift favors vendors with payer data assets and cross-continuum visibility, compressing the addressable market for point-solution specialists.
Global Computer Assisted Coding Market Segmentation
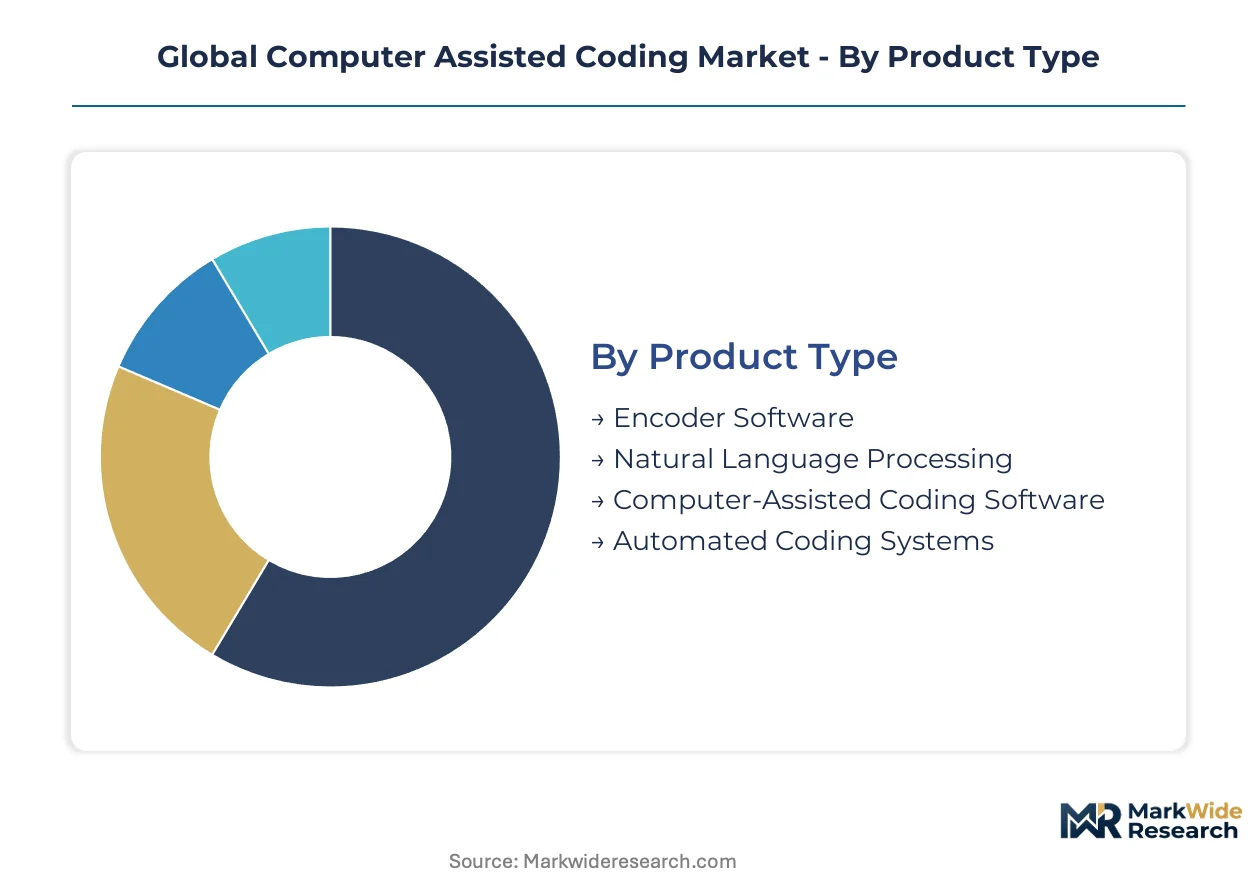
Computer assisted coding vendors structure product portfolios around four intersecting dimensions. Deployment architecture and end-user scale determine pricing elasticity, while application depth shapes integration complexity and recurring revenue potential.
Product Type:
Procurement teams evaluate technical sophistication against existing EHR infrastructure and coder workforce capacity.
- Encoder Software:Rules-based engines map clinical terminology to standardized code sets through structured query interfaces. United States hospital systems with legacy IT investments drive replacement cycles as ICD-10-CM specificity requirements intensify.
- Natural Language Processing:Clinical NLP engines parse unstructured physician narratives using transformer architectures to extract billable concepts. Academic medical centers in the United States pilot these systems for complex surgical documentation, reducing retrospective query volumes through concurrent coding workflows.
- Computer-Assisted Coding Software:Integrated platforms combine encoder logic with workflow management for revenue cycle departments.
- Automated Coding Systems:Fully autonomous solutions target high-volume, low-complexity encounters in emergency and outpatient settings.
Volume sits with encoder software; growth tilts toward natural language processing.
Application:
Functional use cases segment by reimbursement touchpoint proximity and compliance risk exposure.
- Medical Billing:Code generation for claims submission demands accuracy thresholds that minimize denial rates and accelerate accounts receivable. United States physician practices prioritize billing automation as Medicare reimbursement rules tighten documentation requirements.
- Health Record Analysis:Retrospective chart review for quality reporting and risk adjustment requires semantic depth across longitudinal patient data. United States Medicare Advantage plans drive demand as hierarchical condition category capture directly affects premium revenue.
- Clinical Documentation Improvement:Real-time physician query generation targets specificity gaps before discharge.
- Regulatory Compliance:Automated audit trails and HIPAA-aligned access controls satisfy federal oversight requirements.
Medical billing commands installed base; health record analysis expands most quickly.
End User:
Customer scale determines implementation complexity and professional services attachment rates.
- Hospitals:Enterprise health systems deploy multi-module platforms across inpatient, outpatient, and emergency departments. United States integrated delivery networks consolidate vendor relationships around bundled revenue cycle contracts spanning documentation, coding, and denial management.
- Insurance Providers:Payer-side coding validation and risk adjustment analytics leverage proprietary claims data assets. United States Medicare Advantage organizations invest heavily as CMS-HCC model updates increase diagnosis capture requirements.
- Medical Coding Agencies:Third-party coding vendors seek scalable automation to maintain margins against labor cost pressure.
- Physician Offices:Small practice adoption concentrates in surgical specialties with procedure-heavy encounters.
Hospitals anchor current deployment; insurance providers gain share fastest.
Deployment:
Capital availability and IT staffing density shape architecture preferences across customer tiers.
- On-Premise:Local server installations satisfy stringent data residency requirements for large United States health systems with dedicated security operations centers. Epic and Cerner integration complexity sustains demand despite higher total cost of ownership.
- Cloud-Based:Scalable infrastructure eliminates hardware procurement cycles and accelerates go-live timelines. United States mid-size hospitals adopt aggressively as SaaS models shift expenditure from capital to operational budgets.
- Hybrid Systems:Split architectures isolate protected health information on-premise while leveraging cloud analytics.
- SaaS Platforms:Subscription pricing with automatic updates reduces IT backlog constraints for resource-constrained organizations.
On-premise retains large-system preference; cloud-based climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical documentation digitization concentrates where health system consolidation and reimbursement complexity intersect. The United States anchors installed capacity through federal mandate density. Germany, Japan, India, and the United Kingdom follow as distinct regulatory environments reshape procurement criteria.
United States
Medicare Advantage risk adjustment and CMS quality reporting programs drive enterprise-scale deployments. HIPAA security requirements and the HITECH Act's meaningful use provisions shape vendor qualification protocols. Academic medical centers in Boston and the Research Triangle pilot transformer-based NLP for surgical documentation.
Germany
Hospital digitization under the Hospital Future Act accelerates EHR integration spending. The EU AI Act's risk classification framework mandates conformity assessments for coding systems influencing reimbursement. Health technology clusters in Berlin-Brandenburg and Bavaria concentrate vendor implementation partnerships.
Japan
Aging demographics and universal health coverage expansion strain manual coding capacity. METI's healthcare productivity initiatives subsidize AI adoption in regional hospital networks. Tokyo-Osaka corridor health systems deploy speech recognition integration for point-of-care documentation.
India
Corporate hospital chains under Ayushman Bharat digitization require standardized coding for insurance claims processing. CDSCO oversight of clinical software and RBI data localization norms constrain cloud architecture choices. Bengaluru and Hyderabad host emerging health IT development centers for revenue cycle automation.
United Kingdom
NHS England's electronic patient record targets create procurement pipelines for integrated documentation platforms. GDPR compliance requirements and NHS Digital security standards filter vendor eligibility. London and Manchester health systems evaluate concurrent coding workflows for elective surgery backlogs.
Global Computer Assisted Coding Market Competitive Landscape
Global majors compete with regional champions across NLP engine sophistication and EHR integration depth. The vendor base stratifies into three tiers: diversified health technology conglomerates, specialized clinical NLP developers, and EHR-native module providers. Strategic archetypes include payer-data integrators, voice recognition specialists, and encoder legacy maintainers. Competitive moves concentrate on bundling revenue cycle contracts and acquiring clinical NLP talent.
Within the diversified health technology tier, 3M Company and Optum Inc. occupy positions anchored by long-standing health system relationships and proprietary data assets. Nuance Communications Inc. exemplifies the voice-to-coding convergence archetype. These three entities represent distinct competitive vectors: encoder technology legacy, payer-provider data synthesis, and speech recognition workflow integration.
| Leading Market Players |
|---|
| 3M Company |
| Cerner Corporation |
| Optum Inc. |
| Nuance Communications Inc. |
| Oracle |
| Epic Systems Corporation |
| Artificial Medical Intelligence Inc. |
| Craneware PLC |
| Dolbey Systems Inc. |
| Others |
Supply & Pricing Matrix
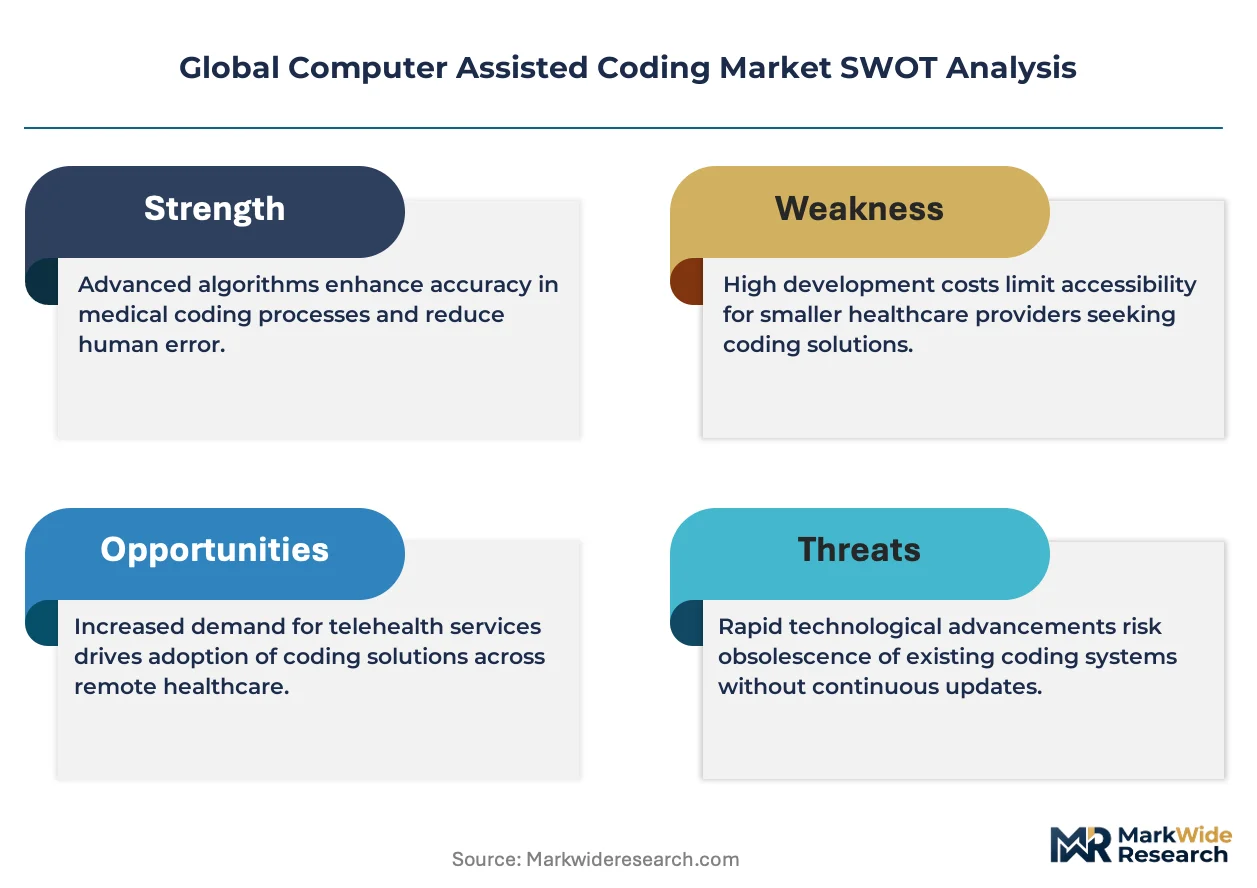
ISO 27001 certification gates qualified supply for enterprise hospital procurement, restricting premium-tier pricing access to vendors with enterprise-grade compliance infrastructure while compressing margins for uncertified competitors seeking mid-market entry.
Pricing Analysis
Warranty and professional services bundling separates premium vendor tiers from unbundled SaaS offerings targeting cost-constrained buyers. Pricing stratifies across premium, standard, and economy tiers based on NLP engine sophistication and Epic-Cerner integration depth. Cost compression in the mid-market intensifies as cloud-native entrants undercut legacy encoder maintenance contracts. Physician offices exhibit highest price sensitivity; integrated delivery networks prioritize total cost of ownership over license fees.
Supply Chain Analysis
Dual-sourcing mandates from United States health systems require vendors to maintain redundant cloud infrastructure across AWS and Azure environments. Software development concentrates in the United States, India, and Ireland. Transformer model training draws from proprietary clinical corpora, cloud compute capacity, and certified coder validation labor. Single-source vulnerability in NLP talent pools constrains scaling velocity. Distribution runs through direct enterprise sales teams and EHR vendor marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where HIPAA security requirements and CMS reimbursement rule density create regulatory moats favoring incumbent vendors with established certification infrastructure.
For Market Incumbents: Anticipate margin pressure from large language model commoditization by deepening encoder-NLP integration and acquiring clinical documentation improvement platforms. Consolidate around bundled revenue cycle contracts spanning coding automation, denial management, and payer data analytics to neutralize point-solution disruptors. For New Entrants and Emerging Players: Enter via outpatient surgical centers and ambulatory settings in the United States where CAC penetration lags inpatient adoption. Target India corporate hospital chains digitizing under Ayushman Bharat for greenfield deployment without legacy system displacement costs. Lead with SaaS pricing and rapid Epic integration to compress sales cycles. For Investors and Strategic Acquirers: FDA clinical decision support software enforcement actions are the leading indicator that regulatory compliance capabilities will determine acquisition premiums. Long-term viability rests on vendors with demonstrated NLP accuracy benchmarks and established health system reference contracts. Monitor CMS-HCC model updates as signals for risk adjustment coding demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical NLP Engine Acquisition | Secures transformer-based coding accuracy advantages against rules-based legacy encoders. |
| Epic-Cerner Integration Partnership | Accelerates procurement cycles through pre-certified EHR marketplace distribution channels. |
| EU Authorized Representative Establishment | Enables European market access under MDR-aligned quality management requirements. |
| Payer Data Asset Integration | Differentiates analytics depth through claims history cross-referenced with provider documentation. |
| Real-Time Voice Recognition Deployment | Compresses revenue cycle timelines through point-of-care code suggestion workflows. |
Research Methodology
Independent corroboration across revenue cycle executives, clinical documentation improvement directors, health system CIOs, and certified professional coders underwrites the qualitative findings. Secondary validation draws from CMS Medicare reimbursement data, hospital procurement databases, GPO contract filings, and SEC disclosures from publicly traded health technology vendors. Bottom-up deployment estimates triangulate against top-down market sizing from EHR vendor ecosystem data.
Comparable historical adoption curves anchored the forecast window to cloud-SaaS transition patterns in adjacent health IT segments. Segmentation modeling spans deployment architecture, end-user scale, application depth, and NLP engine sophistication across the projection horizon. CAGRs derive from algorithmic coding penetration rates, ICD-10-CM specificity requirement trajectories, and mid-size hospital capital expenditure elasticity.
Revisions become necessary when CMS reimbursement rule changes, state-level privacy law expansions, or large language model accuracy breakthroughs materialize. Forecasts reflect assumptions about EHR integration friction and clinical coder workforce availability. Deviation in FDA clinical decision support enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Global Voice Cloning Market