
 Asia-Pacific Aircraft Band Clamps Market | 2026-2036
Asia-Pacific Aircraft Band Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Band Clamps Market Insights
Aerospace metallurgy talent shortages across East Asian manufacturing zones is reorganizing supplier qualification timelines for precision fastening components. Breeze Industrial Products Corporation leverages captive forging capacity to sustain delivery schedules for narrowbody programs. TE Connectivity Ltd. anchors its position through AS9100-certified production lines serving Japanese tier-one aerostructures. Voss Industries Inc. competes on specialty alloy formulations that withstand extreme thermal cycling in turbofan environments.
Aircraft band clamps are circumferential fastening devices engineered from precipitation-hardened stainless steel or titanium alloys, typically specified to AS1895 or MS21919 dimensional tolerances, designed to secure fluid lines, wiring harnesses, and ducting against vibration-induced fatigue in pressurized airframes. Stainless steel variants dominate OEM procurement volumes due to established supply bases and predictable corrosion performance, while composite-reinforced thermoplastic clamps represent the fastest-growing product category as airframers pursue gram-level weight reduction targets. Military application demand generates premium margin pools through small-batch, high-reliability specifications, whereas commercial aviation maintenance channels drive recurring revenue through standardized replacement cycles.
China's SAMR enforces GB/T aviation fastener standards that constrain import pathways for non-certified suppliers, while Japan's METI coordinates JIS material specifications through domestic sub-tier networks. India's BIS has aligned clamp testing protocols with FAA AC 20-107 guidance, streamlining export eligibility for qualified manufacturers. Stakeholders must monitor evolving CSAM and cold spray additive manufacturing qualifications that could displace conventional machined band clamp production economics.
Market Dynamics
COMAC's C919 production ramp and India's MRO infrastructure buildout are compressing supplier qualification timelines across the Asia-Pacific aerospace fastener ecosystem. Tier-one aerostructure manufacturers now demand concurrent engineering capabilities from band clamp vendors to align with narrowbody delivery schedules.
Growth Catalysts
- China's MIIT Material Certification:Accelerated GB/T standard harmonization with AS1895 specifications is unlocking domestic supply chain substitution for import-dependent airframers.
- Southeast Asian Fleet Expansion:Low-cost carriers in Vietnam, Indonesia, and the Philippines are driving recurring procurement of corrosion-resistant clamp assemblies for high-cycle operations.
- Precipitation-Hardened Stainless Steel:Established metallurgy supply bases in Japan and South Korea are enabling cost-competitive OEM volumes with predictable fatigue performance.
Market Restraints
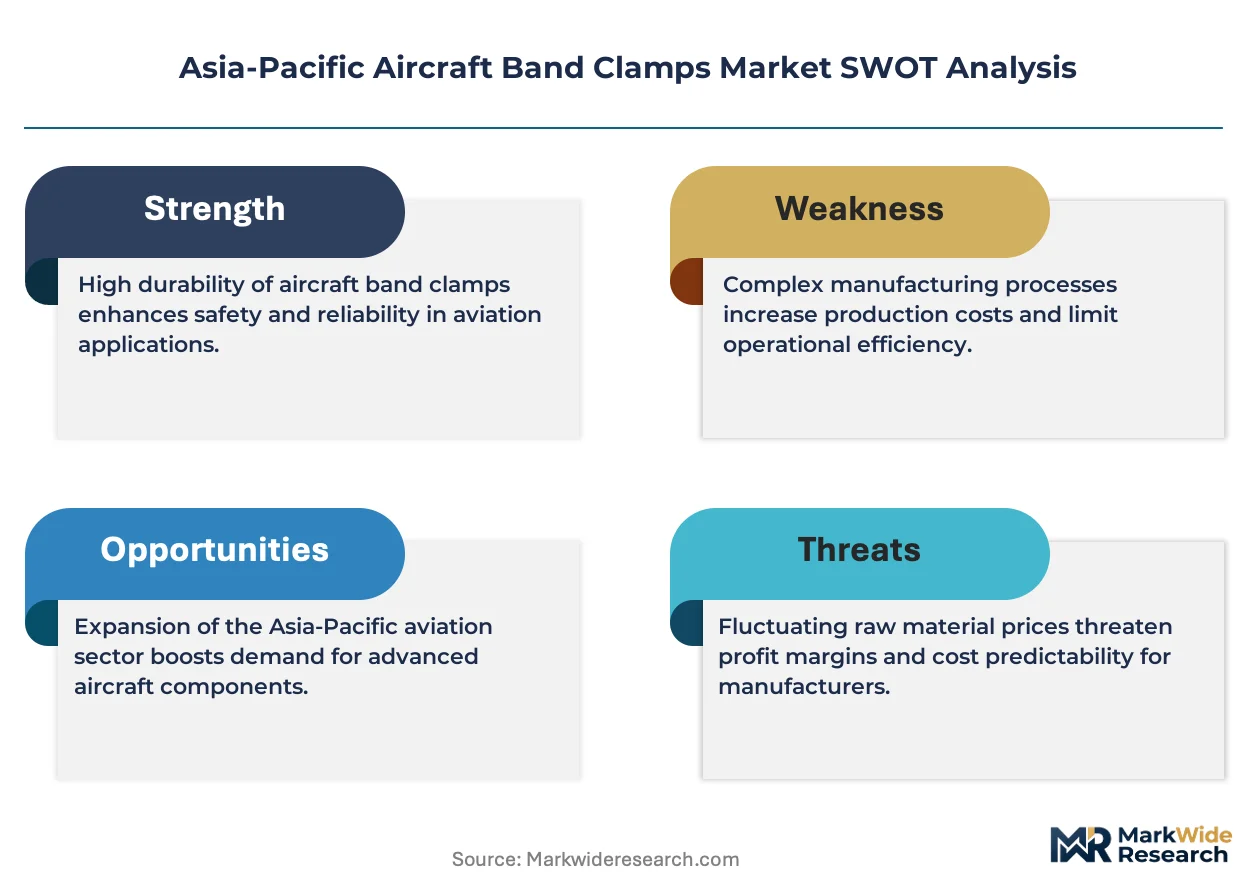
- Titanium Alloy Input Volatility:Sponge titanium price fluctuations from Russian and Kazakh suppliers are compressing margin pools for specialty clamp formulations.
- Supplier Concentration in East China:Forging capacity clustering around Shanghai-Ningbo corridors creates single-point vulnerability for just-in-time aerospace logistics.
- AS9100 Certification Bottlenecks:Limited third-party auditor availability across Asia-Pacific is extending qualification timelines for new market entrants.
Strategic Opportunities
- India's Bengaluru-Hyderabad MRO Corridor:Greenfield maintenance facilities lack established fastener supply relationships, creating first-mover positioning for qualified vendors.
- Cold Spray Additive Manufacturing:Near-net-shape deposition techniques are converging with conventional machining to enable complex clamp geometries without tooling investment.
- Japan's METI Aerospace Sub-Tier Support:Domestic content incentives for JIS-certified components are opening procurement pathways previously reserved for incumbent suppliers.
Industry Challenges
- Aerospace Metallurgy Talent Scarcity:Precipitation hardening process expertise is retiring faster than vocational programs in China and South Korea can replenish.
- Concurrent Engineering Integration:Band clamp vendors must embed design-for-manufacturing teams within COMAC and Tata Advanced Systems workflows without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Band Clamps Market |
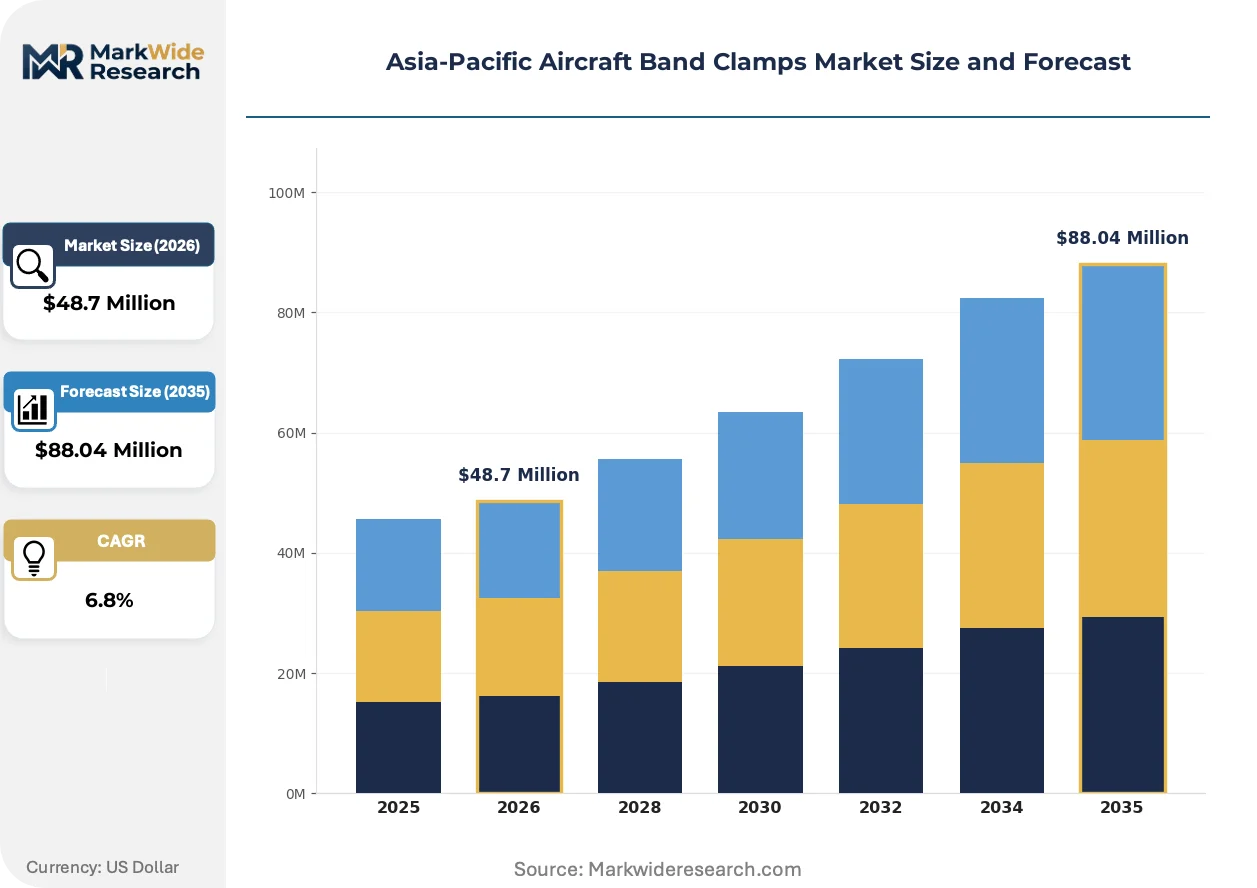
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Thermoplastic, Composite Application: Aerospace, Military, Commercial Aviation, Maintenance End User: OEMs, MRO Providers, Aircraft Manufacturers, Aviation Authorities Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | Breeze Industrial Products Corporation, Maudlin Products, Rotor Clip Company Inc., Band-N-Go Inc., TRU-WORKS INC., Voss Industries Inc., TE Connectivity Ltd., BOA Group, Ideal Clamp Products Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Band Clamps Market Trends and Innovations
Composite-reinforced thermoplastic clamps are disrupting established stainless steel procurement patterns as gram-level weight reduction targets harden across next-generation narrowbody programs. Material science advances and regulatory pressure on fuel efficiency are converging to accelerate qualification of non-metallic alternatives.
Additive manufacturing of titanium alloy clamp bodies is decomposing traditional five-axis machining economics for low-volume, high-complexity geometries. Japanese tier-one suppliers are piloting electron beam melting for thermal-management-optimized designs. This capability is compressing lead times for prototype-to-production transitions in turbofan nacelle applications.
China's SAMR enforcement of GB/T aviation fastener standards is tightening import pathway constraints for non-certified suppliers. Domestic airframers must now source certified components or absorb extended qualification costs. COMAC supply chain managers are responding by consolidating vendor panels around pre-approved domestic manufacturers with established MIIT certifications.
Maintenance channel procurement is consolidating around long-term service agreements that bundle clamp replacement with predictive analytics. Indian MRO operators at Bengaluru and Hyderabad are displacing spot-buying with multi-year contracts tied to flight-hour metrics. This shift is most visible in narrowbody engine overhaul programs where vibration-induced fatigue drives predictable consumption patterns.
Asia-Pacific Aircraft Band Clamps Market Segmentation
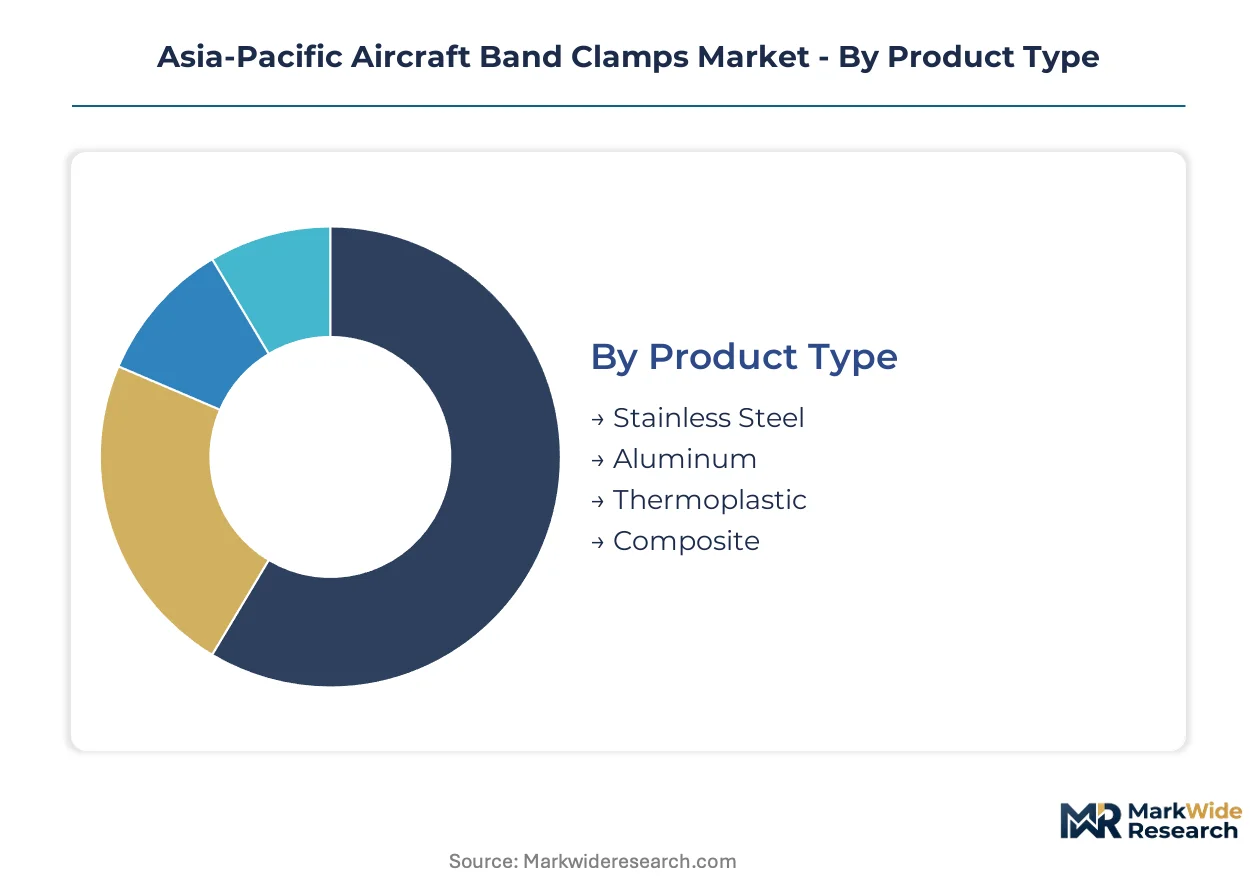
Segmentation in the Asia-Pacific aircraft band clamps market reveals how procurement patterns split between domestic certification requirements and export-oriented supply chains. Understanding these divisions exposes where margin pools concentrate and where qualification barriers create defensible positioning.
Product Type:
Domestic procurement across China and India favors locally certified metallic variants, while thermoplastic and composite formulations flow through export channels to tier-one aerostructure suppliers.
- Stainless Steel:Precipitation-hardened grades dominate OEM volumes due to established supply bases in Japan and South Korea with predictable corrosion performance under AS1895 specifications. China's COMAC supply chain corridors absorb the majority of regional output for narrowbody programs.
- Thermoplastic:Composite-reinforced polymer clamps are displacing metallic alternatives as airframers pursue gram-level weight reduction targets. Demand concentrates in Japanese tier-one aerostructures serving next-generation turbofan nacelle applications where thermal cycling resistance is critical.
- Aluminum:Lightweight alloy variants serve secondary fluid line securing in regional aircraft where cost sensitivity outweighs extreme fatigue requirements.
- Composite:Carbon-fiber-reinforced formulations are emerging for specialized ducting applications in military platforms requiring electromagnetic interference shielding.
Stainless steel commands the established base. The steepest expansion runs through thermoplastic.
Application:
Volume tiers separate high-cycle commercial operations from low-batch military specifications, with maintenance channels generating recurring revenue through standardized replacement cycles.
- Commercial Aviation:Narrowbody fleet expansion across Vietnam, Indonesia, and the Philippines drives procurement of corrosion-resistant clamp assemblies for high-cycle operations. Southeast Asian low-cost carriers prioritize standardized replacement protocols to minimize ground time.
- Maintenance:Indian MRO operators at Bengaluru and Hyderabad are consolidating procurement around long-term service agreements tied to flight-hour metrics. This shift displaces spot-buying with predictive consumption models for vibration-induced fatigue replacements.
- Aerospace:General aviation and business jet applications require smaller batch sizes with accelerated qualification timelines for custom geometries.
- Military:Small-batch, high-reliability specifications generate premium margin pools through extended testing protocols and specialized alloy formulations.
Commercial aviation anchors volume throughput. Maintenance channels are climbing the fastest as fleet age profiles deepen across the region.
End User:
Customer concentration varies sharply between integrated airframers with captive engineering teams and independent MRO facilities lacking established fastener relationships.
- OEMs:COMAC and Tata Advanced Systems demand concurrent engineering capabilities from band clamp vendors to align with narrowbody delivery schedules. Embedded design-for-manufacturing teams have become a qualification prerequisite without guaranteed volume commitments.
- MRO Providers:Greenfield maintenance facilities around India's Bengaluru-Hyderabad corridor lack established supply relationships, creating first-mover positioning for qualified vendors with BIS-certified testing protocols.
- Aircraft Manufacturers:Tier-one aerostructure producers in Japan coordinate through METI-supported sub-tier networks favoring JIS-certified domestic components.
- Aviation Authorities:Regulatory procurement for certification testing and airworthiness validation represents a specialized channel with extended qualification cycles.
OEMs dominate technical specification setting. MRO providers are gaining share fastest as infrastructure buildout accelerates.
Distribution Channel:
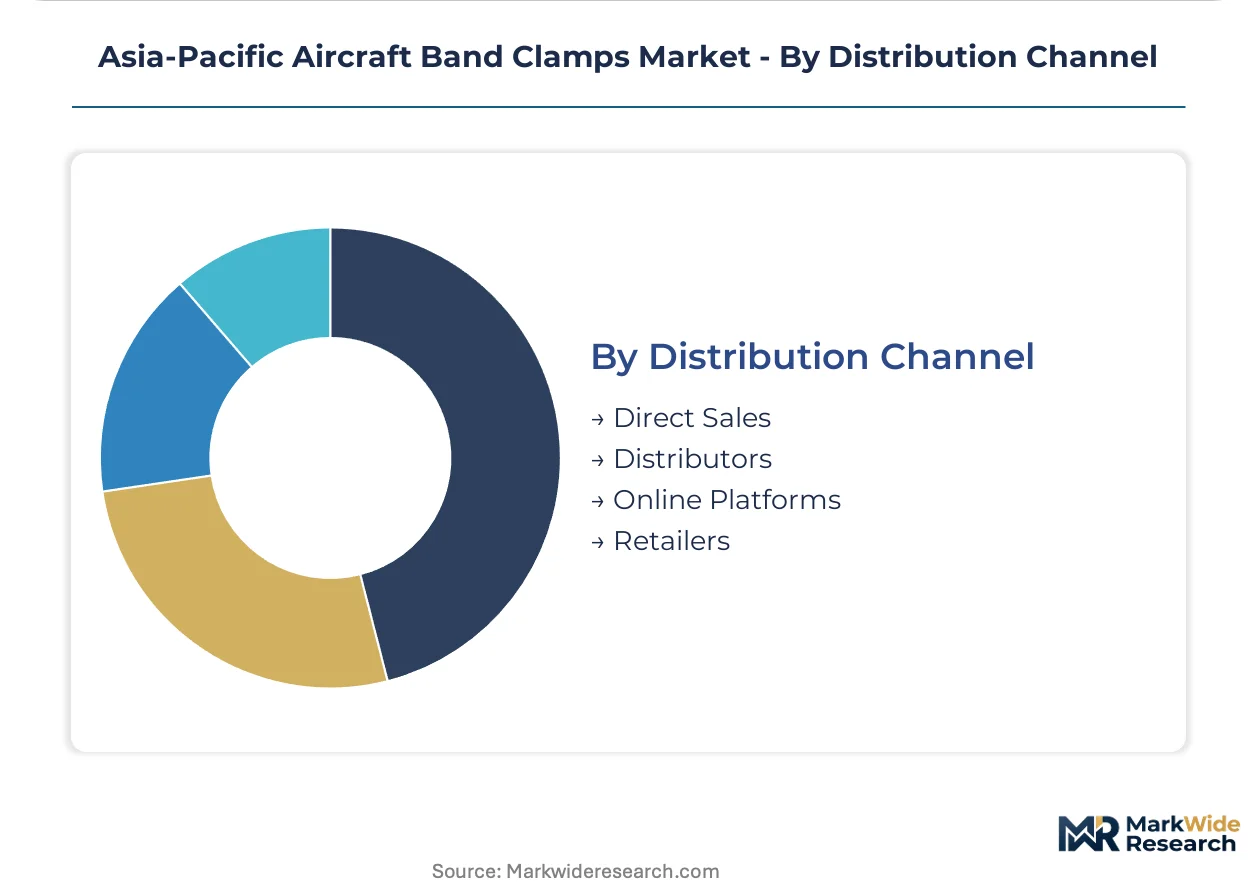
Channel selection tracks customer scale and certification complexity, with direct relationships reserved for qualified tier-one suppliers and distributor networks serving fragmented maintenance demand.
- Direct Sales:AS9100-certified manufacturers maintain dedicated account teams for Japanese tier-one aerostructures and COMAC supply chain managers. These relationships bypass intermediaries to align with just-in-time aerospace logistics requirements.
- Distributors:Specialized aviation fastener distributors serve Indian MRO operators and Southeast Asian carriers with consolidated procurement of standardized clamp specifications.
- Online Platforms:Digital procurement channels are emerging for non-critical replacement parts in general aviation where traceability requirements are less stringent.
- Retailers:Limited penetration exists through aviation supply retailers serving maintenance technicians with emergency replacement needs.
Direct sales capture the premium tier. Distributor networks are expanding most quickly as MRO facility counts multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese tier-one aerostructures while Chinese domestic suppliers compete on volume scale. Southeast Asian procurement runs through Singaporean distribution hubs. Indian MRO facilities face certification premiums that compress margin recovery.
China
COMAC's C919 production ramp drives narrowbody clamp procurement through Shanghai-Ningbo forging corridors. MIIT enforces GB/T aviation fastener standards that constrain import pathways for non-certified suppliers. Domestic airframers consolidate vendor panels around pre-approved manufacturers with established certifications.
Japan
Tier-one aerostructures serving next-generation turbofan programs anchor premium demand for thermal-cycling-resistant formulations. METI coordinates JIS material specifications through domestic sub-tier networks favoring certified domestic components. Nagoya-based suppliers pilot electron beam melting for complex prototype-to-production transitions.
India
Greenfield MRO facilities at Bengaluru and Hyderabad lack established fastener supply relationships, creating positioning opportunities for qualified vendors. BIS has aligned clamp testing protocols with FAA AC 20-107 guidance, streamlining export eligibility. Maintenance operators displace spot-buying with multi-year contracts tied to flight-hour metrics.
South Korea
Precipitation-hardened stainless steel supply bases enable cost-competitive OEM volumes with predictable fatigue performance. MFDS coordinates aerospace material qualifications through domestic certification pathways. Seoul Capital Area suppliers serve as secondary sourcing options for Japanese tier-one aerostructures.
Vietnam
Low-cost carrier fleet expansion drives recurring procurement of corrosion-resistant clamp assemblies for high-cycle operations. The country's national aviation regulator tightens airworthiness compliance timelines for imported components. Da Nang and Ho Chi Minh City maintenance facilities emerge as procurement consolidation points for Southeast Asian carriers.
Asia-Pacific Aircraft Band Clamps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific aerospace fastener ecosystem. AS9100-certified Japanese and Korean manufacturers command premium positioning through metallurgical precision, while Chinese fabricators compete on scale economics within domestic supply chains. The market structures around three archetypes: integrated forging specialists with captive capacity, precision component suppliers with embedded design teams, and distribution-focused intermediaries serving fragmented MRO demand. Competitive moves concentrate on strategic partnerships with COMAC and Tata Advanced Systems workflows, plus cold spray additive manufacturing qualifications that could reshape production economics.
Among North American-anchored specialists, Breeze Industrial Products Corporation and Voss Industries Inc. exemplify the forging-integrated archetype with captive capacity advantages. TE Connectivity Ltd. represents the precision-component tier through AS9100-certified production lines. These three occupy positions that bridge technology differentiation with regional certification requirements.
| Leading Market Players |
|---|
| Breeze Industrial Products Corporation |
| Maudlin Products |
| Rotor Clip Company Inc. |
| Band-N-Go Inc. |
| TRU-WORKS INC. |
| Voss Industries Inc. |
| TE Connectivity Ltd. |
| BOA Group |
| Ideal Clamp Products Inc. |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day forging lead times for precipitation-hardened stainless steel components concentrate pricing power with Shanghai-Ningbo corridor suppliers serving COMAC's narrowbody programs. This inventory compression dynamic reinforces cost premiums for AS9100-certified alternatives while squeezing margins on standardized commercial aviation volumes.
Pricing Analysis
Configured-to-order pricing for specialty titanium alloy formulations commands spreads exceeding standard stainless steel procurement by multiples reflecting material input volatility and small-batch thermal cycling qualification. Pricing stratifies across certification tiers, with MIIT GB/T-certified domestic suppliers in China competing on scale against JIS-certified Japanese tier-one premiums. Cost compression in commercial aviation replacement cycles intensifies as Indian MRO operators consolidate procurement around flight-hour-based contracts. Low-cost carriers across Vietnam and Indonesia exhibit highest price sensitivity, whereas military platforms with high-reliability specifications demonstrate lowest elasticity.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo container corridors elevates inbound logistics costs for Russian and Kazakh sponge titanium feedstock critical to specialty alloy formulations. Manufacturing concentration clusters in China, Japan, and South Korea, with precipitation-hardened stainless steel supply anchored in East Asian forging networks. Raw material dependencies center on nickel-chromium alloys, titanium sponge, and composite polymer resins. Single-source vulnerability persists around electron beam melting capacity for prototype-to-production transitions. Distribution runs through direct account teams for OEM integration and specialized aviation fastener distributors serving fragmented MRO demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through COMAC vendor panel consolidation and Indian MRO long-term agreement standardization, fragmenting supplier leverage across standardized product tiers.
For Market Incumbents: Shield AS9100-certified positioning by embedding design-for-manufacturing teams within COMAC and Tata Advanced Systems workflows before cold spray additive manufacturing qualifications displace conventional machining economics. Deepen backward integration into captive forging capacity to sustain delivery schedules against titanium alloy input volatility from Russian and Kazakh supply disruptions. For New Entrants and Emerging Players: Differentiate on BIS-certified testing protocols aligned with FAA AC 20-107 guidance to capture first-mover positioning in India's Bengaluru-Hyderabad MRO corridor where greenfield facilities lack established fastener relationships. Target thermoplastic composite formulations for next-generation turbofan nacelle applications where gram-level weight reduction targets outpace incumbent metallurgy capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized aerospace fastener divisions lacking AS9100 certification scale. Long-term viability hinges on additive manufacturing qualification trajectories and regional certification harmonization progress. Monitor MIIT GB/T standard enforcement intensity as inflection indicator for domestic supply chain substitution velocity in China.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Spray Additive Manufacturing Qualification | Near-net-shape deposition converges with machining to enable complex clamp geometries without tooling investment. |
| AS9100 Certification Expansion | Third-party auditor capacity constraints across Asia-Pacific extend qualification timelines for new market entrants. |
| Concurrent Engineering Partnership | Embedded design teams within COMAC and Tata workflows become prerequisite without guaranteed volume commitments. |
| Long-Term Service Agreement Consolidation | Indian MRO operators displace spot-buying with multi-year contracts tied to predictive flight-hour metrics. |
| Composite Thermoplastic Formulation Development | Carbon-fiber-reinforced alternatives accelerate qualification as airframers pursue gram-level weight reduction targets. |
Research Methodology
Initial hypotheses were tested against primary input from aerostructure procurement directors, MRO supply chain managers, metallurgical process engineers, and regulatory compliance officers, then refined through secondary validation against FAA airworthiness directives, MIIT certification databases, BIS testing protocol filings, and COMAC supplier qualification records. Bottom-up demand modeling triangulated with top-down aerospace fastener trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers by product type, application tier, end-user concentration, and regional certification cluster. CAGRs derive from segment-level elasticity modeling against narrowbody delivery schedules and MRO infrastructure buildout trajectories. Forecast inputs incorporate sponge titanium price volatility indices and AS9100 certification pipeline backlogs.
The analysis sits within stated boundaries; outcomes outside sustained COMAC production ramp rates and Indian MRO facility commissioning timelines would require recalibration. Forecasts reflect documented assumptions regarding GB/T-AS1895 harmonization progress and cold spray additive manufacturing qualification velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market