

Aircraft Exterior Structure Digital Twin Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exterior Structure Digital Twin Platforms Market Insights
Digital distribution channels for aerospace engineering software are reshaping how OEMs and tier-one suppliers access simulation capabilities. Siemens leverages its industrial software portfolio to anchor European digital twin deployments across airframe programs. Dassault Systèmes sustains dominance in 3D modeling through its CATIA ecosystem, which occupies a central position in Airbus design workflows. PTC competes by extending ThingWorx connectivity into real-time structural monitoring applications for defense and commercial aviation.
Aircraft exterior structure digital twin platforms integrate physics-based solvers, sensor fusion architectures, and geometric fidelity models to replicate load-bearing surfaces including wings, fuselage panels, and empennage assemblies under operational stress. These systems execute finite element analysis at sub-millimeter mesh resolution to predict fatigue crack propagation, corrosion onset, and impact damage accumulation before physical inspection intervals. Simulation software leads platform revenue as legacy PLM environments require high-performance computing upgrades to accommodate multiphysics coupling. Machine learning represents the fastest-expanding technology segment as neural surrogates replace computationally expensive CFD runs in aerodynamic load prediction. Structural health monitoring commands the dominant application share because regulatory pressure on continuing airworthiness drives airline adoption.
EASA airworthiness directives and FAA advisory circulars on condition-based maintenance now explicitly reference validated digital twin methodologies for structural integrity assessment. ISO 23247 framework for digital twin manufacturing interoperability shapes vendor development roadmaps and procurement specifications across NATO-aligned aerospace supply chains. Stakeholders must monitor evolving certification pathways for AI-augmented predictive models as regulators weigh deterministic physics against probabilistic machine learning outputs in safety-critical airworthiness decisions.
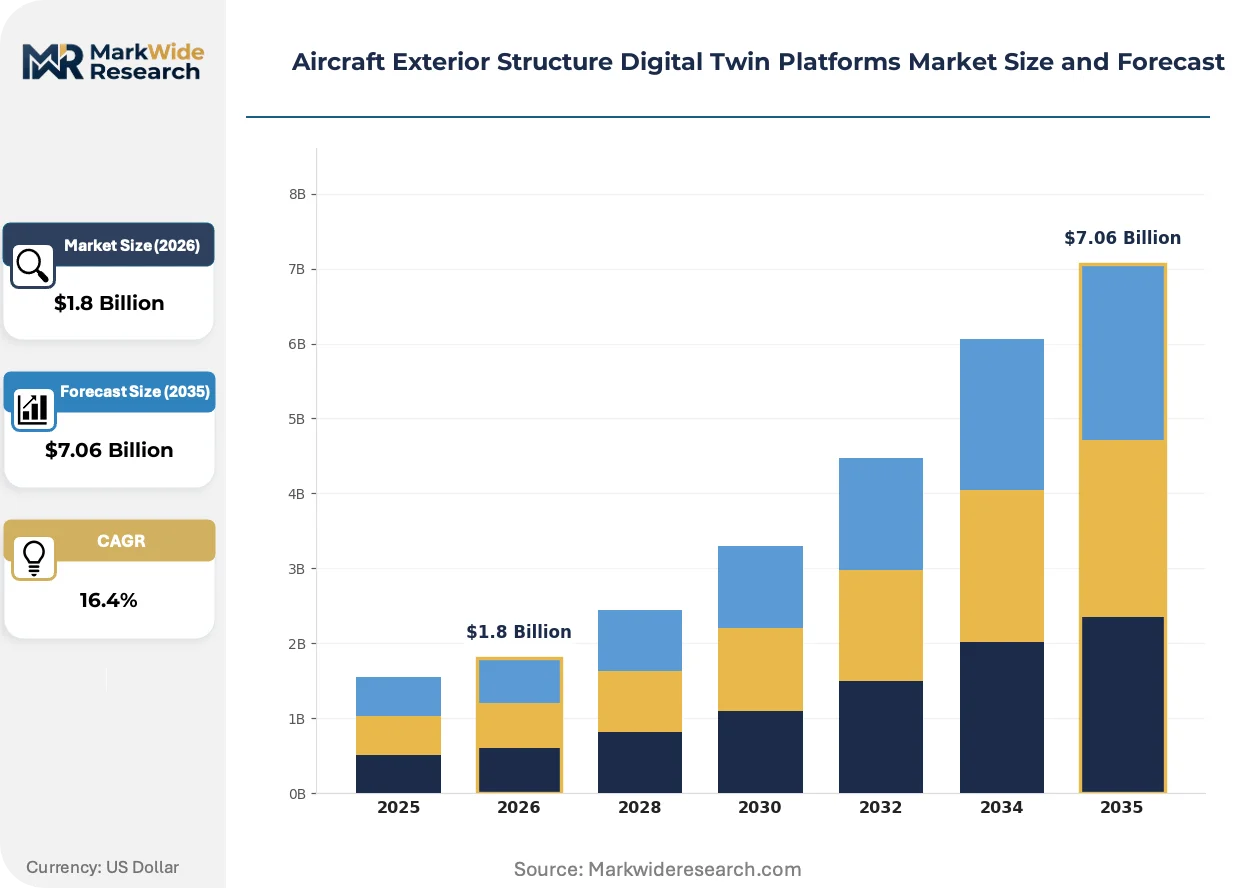
Market Dynamics
Physics-based certification requirements from EASA and FAA are forcing platform vendors to rebuild solver architectures around traceable, deterministic outputs rather than black-box machine learning predictions.
Growth Catalysts
- EASA Airworthiness Directives:Regulatory mandates for condition-based maintenance explicitly validate digital twin methodologies, compelling commercial airlines to deploy structural integrity platforms across aging fleets.
- Neural Surrogate Models:Machine learning architectures trained on high-fidelity simulation data compress computational fluid dynamics runtimes from hours to seconds, enabling real-time load prediction during flight operations.
- German Aerospace Cluster:Concentrated expertise around Airbus Hamburg and Lufthansa Technik Munich creates dense supplier ecosystems and accelerates technology transfer from research to operational deployment.
Market Restraints
- High-Performance Computing Infrastructure:Sub-millimeter finite element mesh resolution for full airframe models demands GPU clusters costing millions in capital expenditure, excluding mid-tier MRO providers.
- Sensor Hardware Supply Concentration:Fiber optic strain gauges and piezoelectric accelerometers for structural health monitoring concentrate among Japanese and German component specialists, creating single-source vulnerabilities.
- Deterministic Physics Requirements:FAA advisory circulars on virtual certification reject probabilistic AI outputs for safety-critical fatigue predictions, limiting neural network deployment scope.
Strategic Opportunities
- Defense Aviation Modernization:Military operators in NATO-aligned nations seek digital twin platforms for legacy fleet life extension, creating demand insulated from commercial aviation cyclicality.
- ISO 23247 Manufacturing Interoperability:The framework's formalization enables vendor-agnostic data exchange, lowering switching costs and expanding addressable market for second-tier platform providers.
- Edge Computing Convergence:Integration of onboard inference chips with satellite connectivity architectures permits real-time structural alerts without ground station dependency, opening oceanic and remote route applications.
Industry Challenges
- Multiphysics Simulation Expertise Scarcity:Coupling aerodynamic, thermal, and structural solvers requires rare cross-disciplinary engineering talent, elongating implementation timelines and inflating professional services costs.
- Legacy PLM Integration Friction:Airframe OEMs operate decades-old product lifecycle management environments; API incompatibilities and data schema mismatches consume 40% of typical deployment resources.
- AI-Augmented Certification Pathways:Regulators have not established standardized validation protocols for machine learning models in airworthiness decisions, creating regulatory uncertainty that stalls procurement commitments.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exterior Structure Digital Twin Platforms Market Trends and Innovations
Computational architectures and certification methodologies are undergoing simultaneous transformation as vendors race to satisfy deterministic regulatory requirements while capturing machine learning efficiency gains.
Neural surrogate models trained on high-fidelity computational fluid dynamics datasets are collapsing the cost structure of aerodynamic load prediction. Tier-one suppliers now embed these lightweight approximations directly into flight control systems for real-time gust response optimization. The compression enables continuous structural monitoring that was previously restricted to pre-flight ground analysis.
EU AI Act risk classification frameworks are extending into aerospace software certification, requiring explainability documentation for any algorithm influencing airworthiness decisions. Platform vendors must now maintain full provenance chains from training data through inference outputs. German and French aerospace authorities are piloting these requirements ahead of formal EASA adoption, pressuring development roadmaps.
Airline engineering departments are unbundling predictive maintenance software from traditional airframe OEM service contracts. Lufthansa Technik and similar independent MRO specialists now procure digital twin capabilities directly from Siemens, Dassault Systèmes, and PTC, bypassing Airbus and Boeing as intermediaries. This disintermediation concentrates in European markets where regulatory frameworks explicitly permit third-party structural integrity assessments.
Aircraft Exterior Structure Digital Twin Platforms Market Segmentation
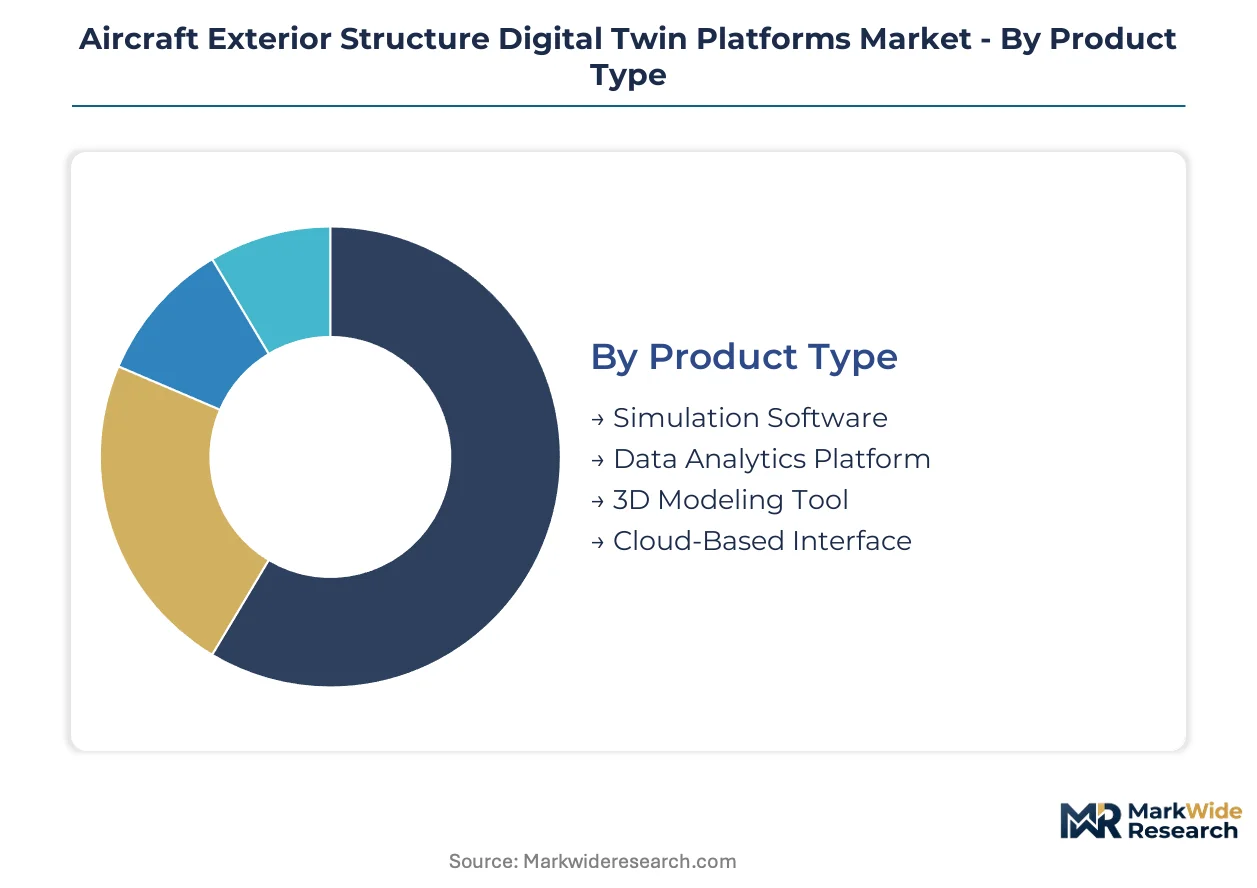
Aircraft exterior structure digital twin platforms fragment across four intersecting dimensions. Each segmentation axis reflects distinct procurement patterns, technical requirements, and regulatory compliance burdens that shape vendor positioning and customer switching costs.
Product Type:
Mature simulation environments coexist with emerging cloud-native interfaces, creating a bifurcated procurement landscape where legacy PLM upgrades compete against greenfield deployments.
- Simulation Software:Finite element analysis solvers execute sub-millimeter mesh resolution for fatigue crack propagation modeling. Commercial airlines in Germany anchor demand as EASA airworthiness directives mandate validated structural integrity assessments for aging fuselage fleets.
- Data Analytics Platform:Sensor fusion architectures aggregate strain gauge outputs, accelerometer streams, and flight parameter logs into unified degradation models. MRO providers concentrate procurement in Hamburg and Munich, driven by Lufthansa Technik's predictive maintenance program expansion.
- 3D Modeling Tool:Geometric fidelity engines replicate wing panels and empennage assemblies under operational stress.
- Cloud-Based Interface:Browser-accessible dashboards enable distributed engineering teams to collaborate on virtual certification workflows.
Simulation software retains volume leadership; cloud-based interfaces hold the steepest expansion curve.
Technology:
Cost tiers separate computationally intensive physics solvers from lightweight neural approximations, with procurement decisions hinging on hardware infrastructure and regulatory risk tolerance.
- Physics-Based Modeling:Deterministic solvers deliver traceable outputs required by FAA advisory circulars on virtual certification. German aerospace authorities pilot EU AI Act explainability requirements ahead of formal EASA adoption, reinforcing demand for transparent calculation chains.
- Machine Learning:Neural surrogate models compress computational fluid dynamics runtimes from hours to seconds for real-time gust response optimization. Defense aviation modernization programs across NATO-aligned nations drive adoption where deterministic constraints are relaxed for non-critical monitoring.
- Real-Time Monitoring:Edge computing architectures process structural alerts onboard without ground station dependency.
- Predictive Maintenance:Degradation forecasting algorithms schedule inspection intervals based on accumulated damage models.
Physics-based modeling commands the premium tier; machine learning is gaining share fastest among technology segments.
Application:
Application segmentation maps directly to customer operational priorities, from regulatory compliance through design innovation.
- Structural Health Monitoring:Continuous assessment of load-bearing surfaces using fiber optic strain gauges and piezoelectric networks. Regulatory pressure on continuing airworthiness from EASA and FAA compels airline adoption across European and North American fleets.
- Design Optimization:Multiphysics coupling enables weight reduction in wing spars and fuselage frames without compromising fatigue life. Airbus design workflows in Toulouse and Hamburg integrate these capabilities for next-generation airframe programs.
- Lifecycle Management:Digital thread continuity from initial certification through retirement planning.
- Failure Analysis:Post-incident reconstruction of impact damage and corrosion propagation patterns.
Structural health monitoring dominates deployment scale; design optimization shows the steepest expansion trajectory.
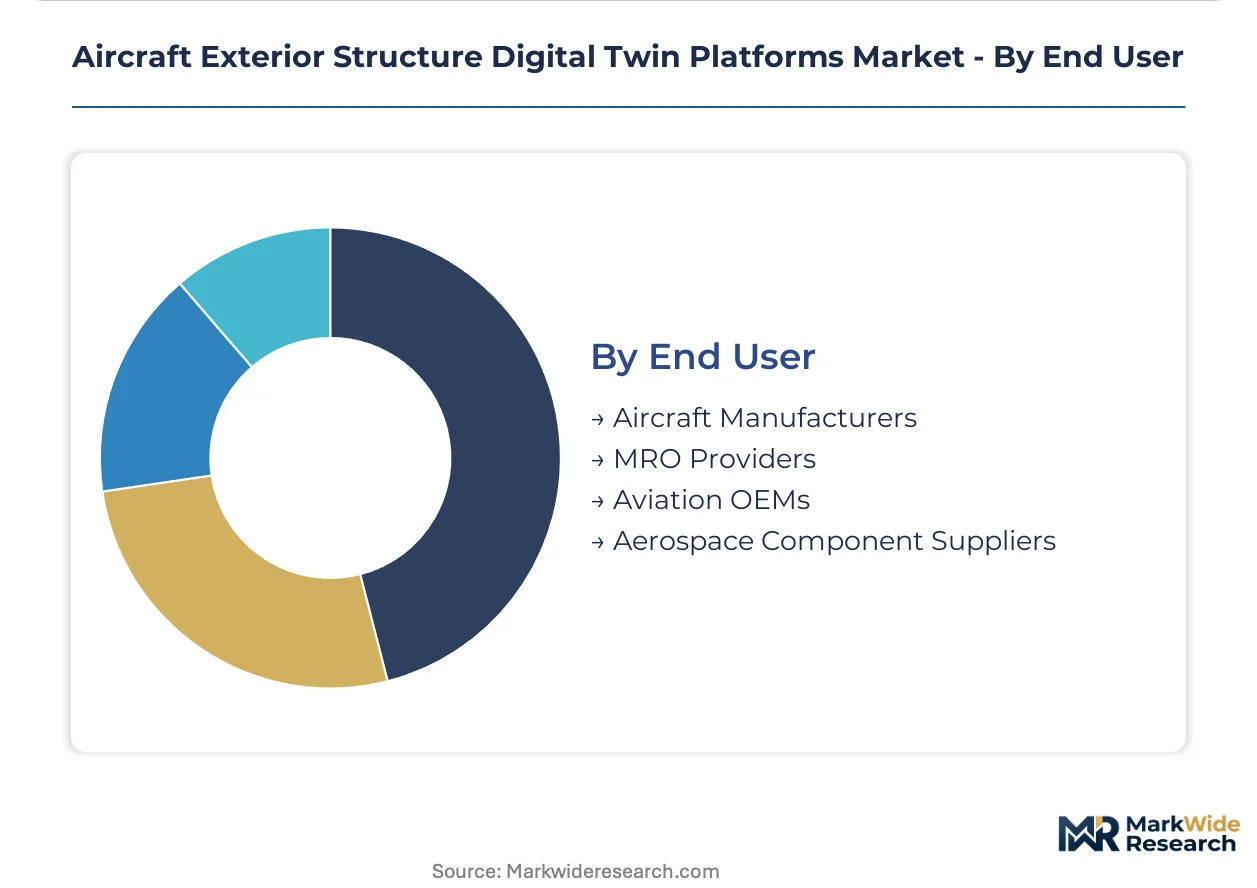
End User:
Customer type segmentation reveals divergent procurement authority, with independent MRO specialists increasingly bypassing traditional OEM intermediaries.
- Aircraft Manufacturers:Airframe OEMs deploy comprehensive digital twin ecosystems across development and production phases. Legacy PLM integration friction consumes substantial deployment resources as decades-old environments resist API connectivity.
- MRO Providers:Independent maintenance specialists procure platform capabilities directly from Siemens, Dassault Systèmes, and PTC. German regulatory frameworks explicitly permit third-party structural integrity assessments, accelerating disintermediation in European markets.
- Aviation OEMs:Tier-one suppliers embed neural surrogates into flight control systems for real-time load prediction.
- Aerospace Component Suppliers:Specialized fabricators validate individual part performance against digital twin specifications.
MRO providers are expanding procurement fastest; aircraft manufacturers retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where Airbus and Lufthansa Technik anchor aerospace digitalization expertise, while US operators absorb premium licensing costs for FAA-compliant deterministic solvers. This asymmetry shapes procurement patterns across NATO-aligned supply chains.
United States
Defense aviation modernization programs drive platform demand for legacy fleet life extension across military operators. FAA advisory circulars on virtual certification explicitly reject probabilistic AI outputs for fatigue predictions, reinforcing physics-based solver procurement. Boeing anchors development activity in Seattle and Charleston, where airframe engineering teams integrate multiphysics coupling for next-generation programs.
Germany
Commercial airlines expand predictive maintenance programs for aging fuselage structures under EASA airworthiness directives. The EU AI Act risk classification framework pilots explainability requirements ahead of formal adoption, pressuring vendor development roadmaps. Hamburg and Munich host dense supplier ecosystems around Airbus Hamburg and Lufthansa Technik Munich, accelerating technology transfer from research to deployment.
France
Airbus design workflows in Toulouse integrate 3D modeling capabilities for wing spar weight reduction without fatigue life compromise. French aerospace authorities pilot EU AI Act documentation requirements for algorithmic airworthiness decisions. The Toulouse-Blagnac cluster concentrates multiphysics simulation expertise for next-generation airframe development programs.
United Kingdom
Independent MRO specialists procure digital twin capabilities directly from platform vendors, bypassing traditional OEM intermediaries. The country's national aviation regulator aligns with EASA condition-based maintenance mandates for continuing airworthiness assessments. Southeast England hosts engineering teams serving both commercial airlines and defense aviation modernization contracts.
Japan
Fiber optic strain gauge supply concentrates among Japanese component specialists, creating single-source vulnerabilities for structural health monitoring hardware. METI industrial policy supports digital twin manufacturing interoperability aligned with ISO 23247 frameworks. Nagoya and Tokyo metropolitan areas anchor aerospace supplier networks serving regional airline maintenance programs.
Aircraft Exterior Structure Digital Twin Platforms Market Competitive Landscape
Industrial software conglomerates and specialized aerospace engineering firms split the market along capability-depth and geographic-coverage axes. Siemens leverages its industrial software portfolio to anchor European deployments, while Dassault Systèmes sustains dominance in 3D modeling through CATIA ecosystem integration. Two strategic archetypes dominate: diversified industrial technology providers with cross-sector simulation platforms, and aerospace-native specialists with regulatory-certification depth. Competitive moves concentrate on strategic partnerships with airframe OEMs and technology licensing for neural surrogate model deployment.
Within the diversified industrial technology tier, Siemens and Dassault Systèmes occupy positions defined by legacy PLM ecosystem integration. PTC represents the connectivity-focused archetype, extending industrial IoT platforms into real-time structural monitoring applications. Among aerospace-native specialists, Lufthansa Technik exemplifies the independent MRO procurement model now expanding across European markets where regulatory frameworks permit third-party structural integrity assessments. German Aerospace Center anchors publicly funded research-to-deployment pathways distinct from commercial vendor strategies.
| Leading Market Players |
|---|
| Airbus |
| Boeing |
| Siemens |
| Dassault Systèmes |
| PTC |
| NTT DATA |
| Lufthansa Technik |
| Air France Industries KLM Engineering & Maintenance |
| German Aerospace Center |
| Others |
Pricing and Supply Chain Analysis
Hamburg-Munich logistics corridors carry GPU cluster components and fiber optic sensor hardware at freight premiums that compound downstream price spreads between configured-to-order digital twin deployments and standardized SaaS offerings. EASA certification requirements for deterministic physics solvers concentrate procurement authority among German MRO specialists and Airbus engineering teams, amplifying their negotiating leverage against platform vendors.
Pricing Analysis
The customization-premium spread separates deterministic physics-based solver licensing from lightweight machine learning SaaS tiers, with FAA-compliant certification packages commanding substantial uplifts over neural surrogate alternatives. Price differentiation rests on EASA validation status and GPU infrastructure bundling, with certified deployments in Germany absorbing the highest premiums. Cost compression in cloud-native interfaces is intensifying as PTC and Siemens compete for mid-tier MRO contracts. Independent maintenance providers exhibit the greatest price sensitivity; defense aviation operators show the least.
Supply Chain Analysis
Supplier-financing facilities from Japanese fiber optic component specialists and German piezoelectric sensor vendors extend payment terms to 90 days, easing working capital pressure for platform integrators. Hardware concentration in Japan and Germany draws from specialized semiconductor substrates, precision optical assemblies, and high-temperature adhesives. Single-source vulnerability in fiber optic strain gauge supply creates exposure to METI export licensing delays. Distribution runs through direct OEM partnerships and independent MRO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EASA airworthiness directives mandate validated digital twin methodologies for continuing airworthiness, accelerating penetration beyond experimental deployments into operational fleet management.
For Market Incumbents: Entrench deterministic solver dominance by embedding explainability documentation chains ahead of formal EU AI Act adoption in German and French aerospace authorities. Acquire neural surrogate specialists to neutralize machine learning efficiency threats from cloud-native entrants. Prioritize certification investment in edge computing architectures for oceanic route applications. For New Entrants and Emerging Players: Southeast Asian airline MRO networks represent underpenetrated demand where regulatory frameworks lag EASA stringency. Target independent maintenance specialists in Thailand and Singapore with lightweight SaaS interfaces bypassing legacy PLM integration friction. Pursue partnership-led go-to-market positioning with regional system integrators possessing existing airline relationships. For Investors and Strategic Acquirers: Aerospace-native simulation boutiques with EASA pre-certification status offer acquisition exposure to regulatory moat expansion. Long-term viability hinges on deterministic physics dominance persisting through the projection horizon against machine learning efficiency gains. Monitor FAA advisory circular evolution on AI-augmented fatigue prediction as inflection signal for neural surrogate model permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Pre-Certification Investment | Deterministic solver validation creates regulatory moats against probabilistic AI competitors in German markets. |
| Neural Surrogate Acquisition | Machine learning talent absorption compresses CFD runtime economics for real-time structural monitoring applications. |
| Edge Computing Partnership | Onboard inference chip integration with satellite architectures opens oceanic route deployments beyond ground station coverage. |
| Independent MRO Channel Development | Direct procurement relationships with Lufthansa Technik and Air France Industries KLM bypass traditional OEM intermediaries. |
| ISO 23247 Interoperability Certification | Vendor-agnostic data exchange compliance expands addressable market for second-tier platform providers in NATO supply chains. |
Research Methodology
A spread of perspectives from airframe OEM platform engineers, MRO predictive maintenance directors, EASA certification specialists, and fiber optic sensor procurement leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA advisory circulars, EASA airworthiness directives, ISO 23247 framework documentation, and aerospace PLM vendor technical disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from German Aerospace Center research publications and METI industrial policy filings.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling procurement patterns by product type, technology tier, application priority, and end-user authority. Segmentation dimensions included physics-based versus machine learning deployment, deterministic versus probabilistic regulatory acceptance, and OEM-captive versus independent MRO procurement channels. CAGRs derived from installed base expansion rates and replacement cycle compression in aging fleet structural monitoring programs.
Practitioners should monitor EASA AI Act implementation timelines, FAA neural network certification pathway evolution, and fiber optic sensor export licensing shifts from Japanese authorities for early signals of forecast revision. Macroeconomic contraction in commercial aviation, regulatory rejection of probabilistic models for safety-critical predictions, or breakthrough deterministic machine learning architectures would prompt reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.