
 Aerostructures Market | 2026-2036
Aerostructures Market Size, Share, and Industry Trends Forecast 2026-2036
Aerostructures Market Analysis
Aftermarket service revenue is tilting toward composite repair and structural health monitoring as airlines extend fleet lifecycles. Spirit AeroSystems dominates integrated fuselage and wing assembly production for narrowbody platforms. GKN Aerospace specializes in engine nacelles and advanced composite structures across European and North American facilities. Airbus SE leverages its vertically integrated aerostream manufacturing network to control critical subassembly flows.
An aerostructure comprises the primary load-bearing framework of an aircraft, including wings, fuselage, and empennage, typically fabricated from aluminum alloys, titanium, carbon-fiber-reinforced polymers, or hybrid stacks through processes such as automated fiber placement, resin transfer molding, and high-speed machining to achieve specific strength-to-weight ratios and fatigue resistance thresholds. Wing structures command the largest value share due to their complexity and material intensity, while composite materials represent the fastest-expanding material category as OEMs pursue fuel efficiency targets. Fuselage components remain the most mature segment, with established aluminum supply chains and qualified repair networks sustaining incumbent positions.
FAA airworthiness directives and EASA CS-25 certification standards govern structural integrity, damage tolerance, and flammability requirements that dictate material selection and testing protocols for all commercial aerostructures. The EPA regulates volatile organic compound emissions from surface finishing and adhesive curing operations, pushing fabricators toward closed-loop spray systems and waterborne primer technologies. Stakeholders must monitor evolving sustainability mandates from regulators and OEM customers that will reshape supplier qualification criteria and capital allocation priorities across the value chain.
Market Dynamics
FAA and EASA damage tolerance mandates are compressing composite material qualification timelines while OEMs simultaneously push for higher production rates, creating a structural squeeze between regulatory rigor and throughput acceleration.
Growth Catalysts
- Fleet Renewal Programs:Commercial airlines are replacing aging narrowbody aircraft with fuel-efficient platforms, expanding procurement of lightweight wing assemblies and integrated fuselage systems.
- Automated Fiber Placement:This manufacturing technology reduces material scrap rates and labor hours for complex composite geometries, enabling suppliers to meet OEM cost targets without sacrificing structural performance.
- EPA Surface Finishing Rules:Emission limits on volatile organic compounds from primer and adhesive operations are forcing fabricators toward closed-loop spray systems, creating upgrade demand for environmental compliance equipment.
Market Restraints
- Titanium Input Volatility:Aerospace-grade titanium sponge pricing fluctuates with Russian and Chinese export policies, squeezing margin predictability for machined structural components.
- Single-Source Concentration:Large integrated fuselage assemblies depend on a concentrated supplier base in Wichita, Kansas, creating geographic vulnerability to weather disruptions and labor actions.
- Resin Transfer Molding Limitations:Thick-section composite parts suffer from void formation and cure non-uniformity, restricting application in primary load-bearing structures beyond current size thresholds.
Strategic Opportunities
- Urban Air Mobility Airframes:eVTOL manufacturers require novel aerostructure architectures with distributed electric propulsion integration, opening design contracts outside traditional commercial aviation procurement channels.
- Structural Health Monitoring:Embedded sensor networks for real-time fatigue crack detection represent an underdeveloped aftermarket service layer with recurring revenue potential.
- EU Green Deal Aviation:Sustainable aviation fuel compatibility requirements and lifecycle carbon accounting are reshaping supplier qualification criteria toward recyclable thermoplastic composites.
Industry Challenges
- Composite Repair Certification:FAA-approved repair stations face a shortage of technicians qualified to inspect and restore carbon-fiber structures to original design allowables.
- CS-25 Amendment Integration:EASA's evolving certification standards for electrical system interaction with composite structures require continuous engineering redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerostructures Market |
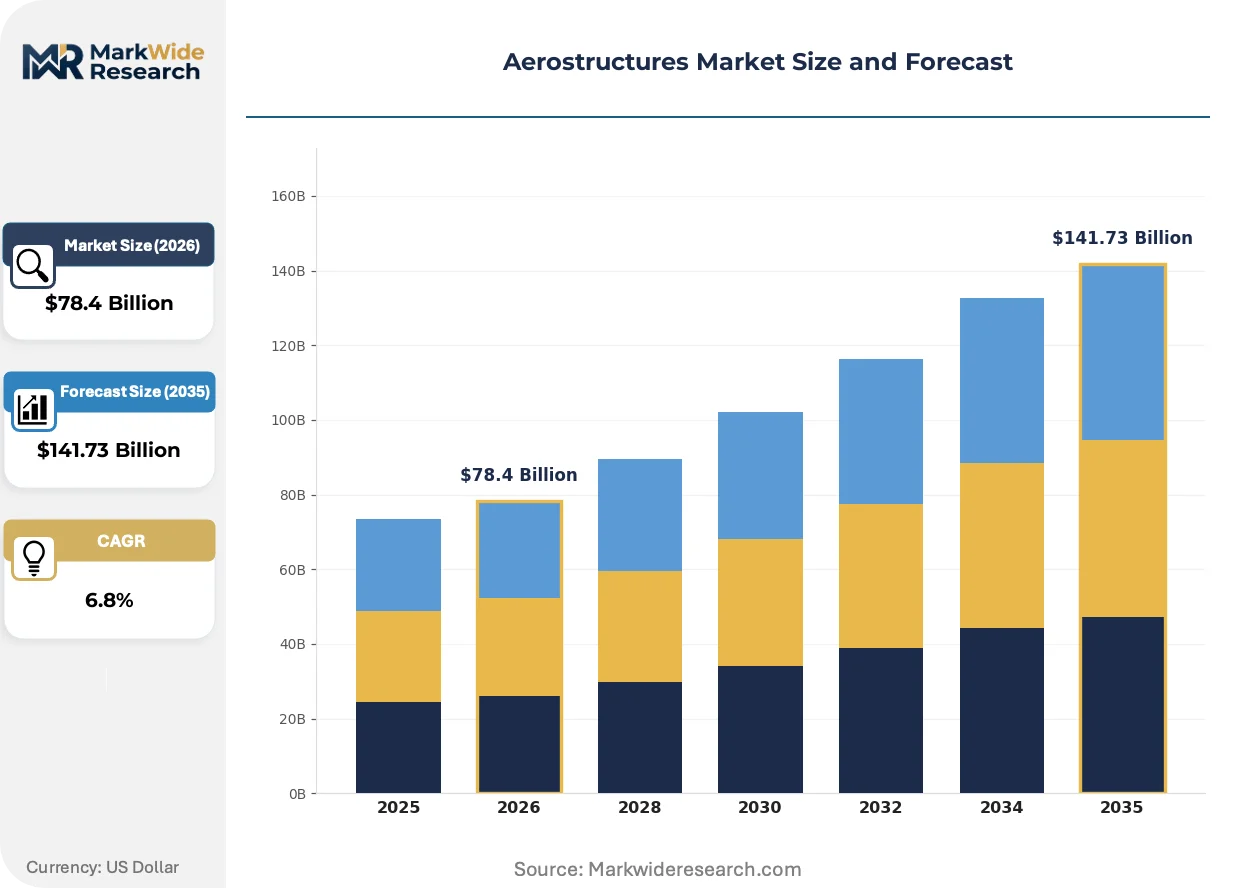
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wing Structures, Fuselage Components, Tail Assemblies, Control Surfaces Material: Aluminum, Titanium, Composite Materials, Steel End User: Commercial Aviation, Military Aviation, Space Exploration, UAVs Manufacturing Stage: Design, Fabrication, Assembly, Testing |
| Companies Covered | Spirit AeroSystems Inc., Airbus SE, The Boeing Company, Leonardo S.p.A, GKN Aerospace, Saab AB, Triumph Group, Inc., AAR Corp., Cyient Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerostructures Market Emerging Trajectories
Material science breakthroughs and regulatory carbon accounting are converging to accelerate thermoplastic adoption while digital thread implementation compresses design-to-certification timelines.
Thermoplastic composites are replacing thermoset systems in secondary structures and select primary applications due to their weldability, recyclability, and indefinite shelf life. Airbus and Boeing supplier teams are qualifying carbon-fiber-reinforced PEEK and PPS formulations for wing ribs and control surfaces. This material transition is hybridizing manufacturing footprints as fabricators retool from autoclave curing to ultrasonic welding and induction consolidation processes.
EASA CS-25 certification amendments for damage tolerance and electrical system interaction are forcing redesign cycles for composite-intensive airframes. The regulatory pressure extends material qualification timelines by months but simultaneously validates advanced non-destructive inspection methods. European suppliers are investing in automated ultrasonic testing and digital radiography to satisfy these evolving structural integrity demonstrations.
Airline engineering departments are unbundling structural maintenance from full-service contracts and awarding discrete repair events to specialized composite shops. This procurement fragmentation shifts volume away from OEM-authorized networks toward independent repair stations with focused capabilities. The pattern is most pronounced in Southeast Asia, where rapid fleet expansion outpaces OEM service infrastructure deployment.
Aerostructures Market Segmentation
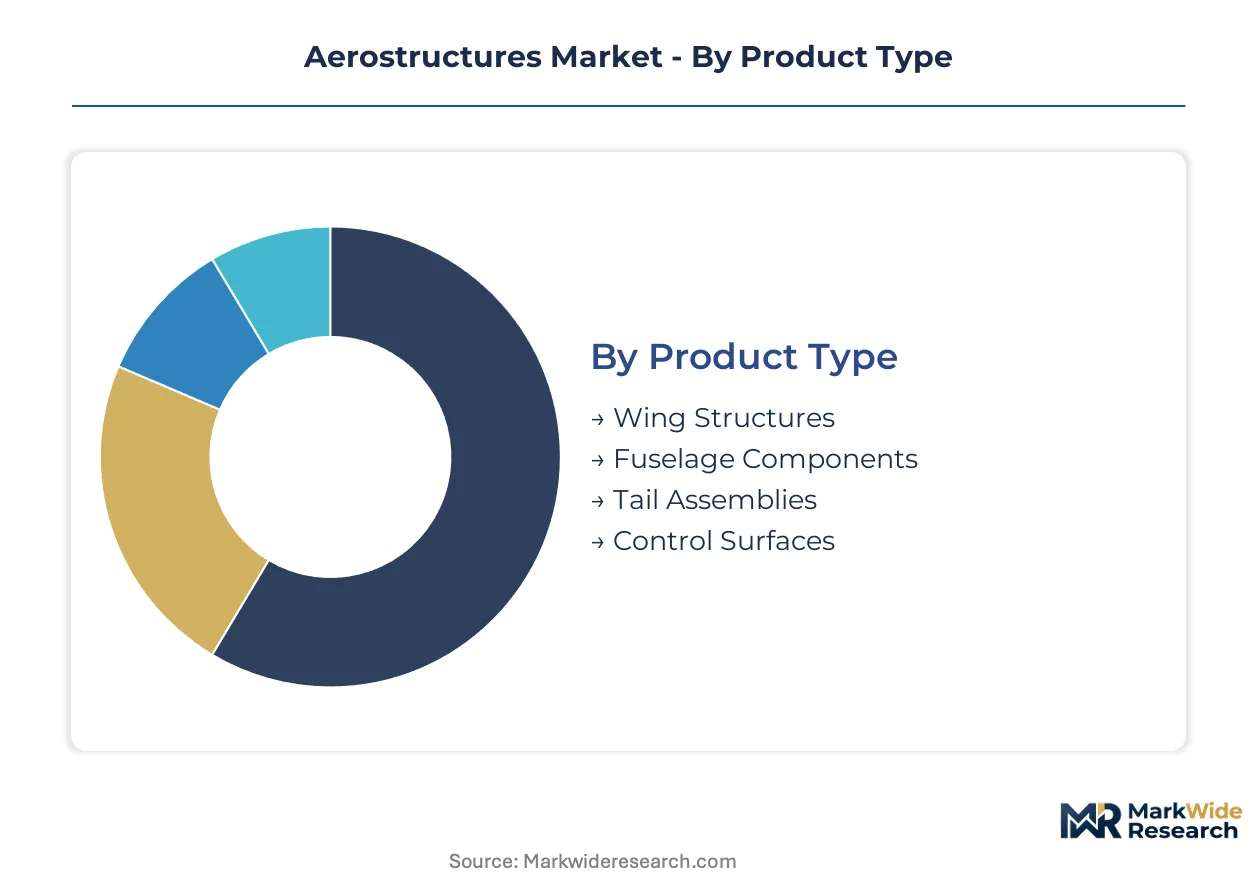
Aerostructure procurement patterns diverge sharply across product architectures, material systems, and end-use missions. Each segmentation axis reveals distinct qualification barriers, margin structures, and supplier concentration dynamics that shape competitive positioning.
Product Type:
Use cases span from high-lift devices on narrowbody transports to hypersonic thermal protection systems, with complexity and certification rigor scaling accordingly.
- Wing Structures:These assemblies integrate spars, ribs, skins, and control surface attachment points that must sustain millions of load cycles. Boeing and Airbus procurement teams concentrate demand for lightweight wing boxes in Wichita, Kansas and Broughton, United Kingdom, driven by fleet renewal programs for single-aisle platforms.
- Fuselage Components:Cylindrical and conical shell structures form the pressurized pressure vessel and cargo hold. Established aluminum supply chains in Japan and Germany sustain incumbent fabricators, though composite barrel sections gain share in next-generation programs.
- Tail Assemblies:Empennage structures provide stability and control authority through horizontal and vertical stabilizers.
- Control Surfaces:Ailerons, flaps, slats, and rudders demand precise aerodynamic profiles and actuation integration.
Established volume favors fuselage components; emerging adoption favors wing structures.
Material:
Cost tiers separate legacy metal systems from advanced composite architectures, with qualification timelines and scrap rates determining total cost of ownership.
- Aluminum:2XXX and 7XXX series alloys dominate legacy fuselage applications with mature forging, extrusion, and high-speed machining supply chains. Airbus A320 and Boeing 737 programs in France and the United States anchor residual demand as OEMs transition toward composite-intensive designs.
- Composite Materials:Carbon-fiber-reinforced polymers enable 20-30% weight reductions versus metallic alternatives. Automated fiber placement lines in Italy and Japan are climbing the fastest as thermoplastic formulations gain EASA qualification for secondary structures.
- Titanium:High strength-to-weight ratio and corrosion resistance suit engine pylons and landing gear attachments.
- Steel:Landing gear components and high-load fittings require ultra-high-strength steels with controlled hydrogen embrittlement resistance.
Procurement gravity centers on aluminum for near-term programs; composite materials capture engineering investment for next-generation platforms.
End User:
Customer type dictates specification stringency, batch size, and aftermarket service intensity across divergent mission profiles.
- Commercial Aviation:Scheduled airlines and lessors demand damage-tolerant designs with 60,000-cycle economic lives. FAA and EASA certification mandates for transport category aircraft concentrate procurement with tier-one integrators in the United States and European Union.
- Military Aviation:Stealth signatures, survivability, and rapid field repair requirements drive specialized composite formulations and classified manufacturing processes.
- Space Exploration:Launch vehicle structures and reentry vehicles face extreme thermal and acoustic environments.
- UAVs:Remotely piloted platforms prioritize cost minimization over fatigue life for disposable or limited-duration missions.
Commercial aviation commands procurement scale; military and space segments absorb premium pricing for mission-specific performance.
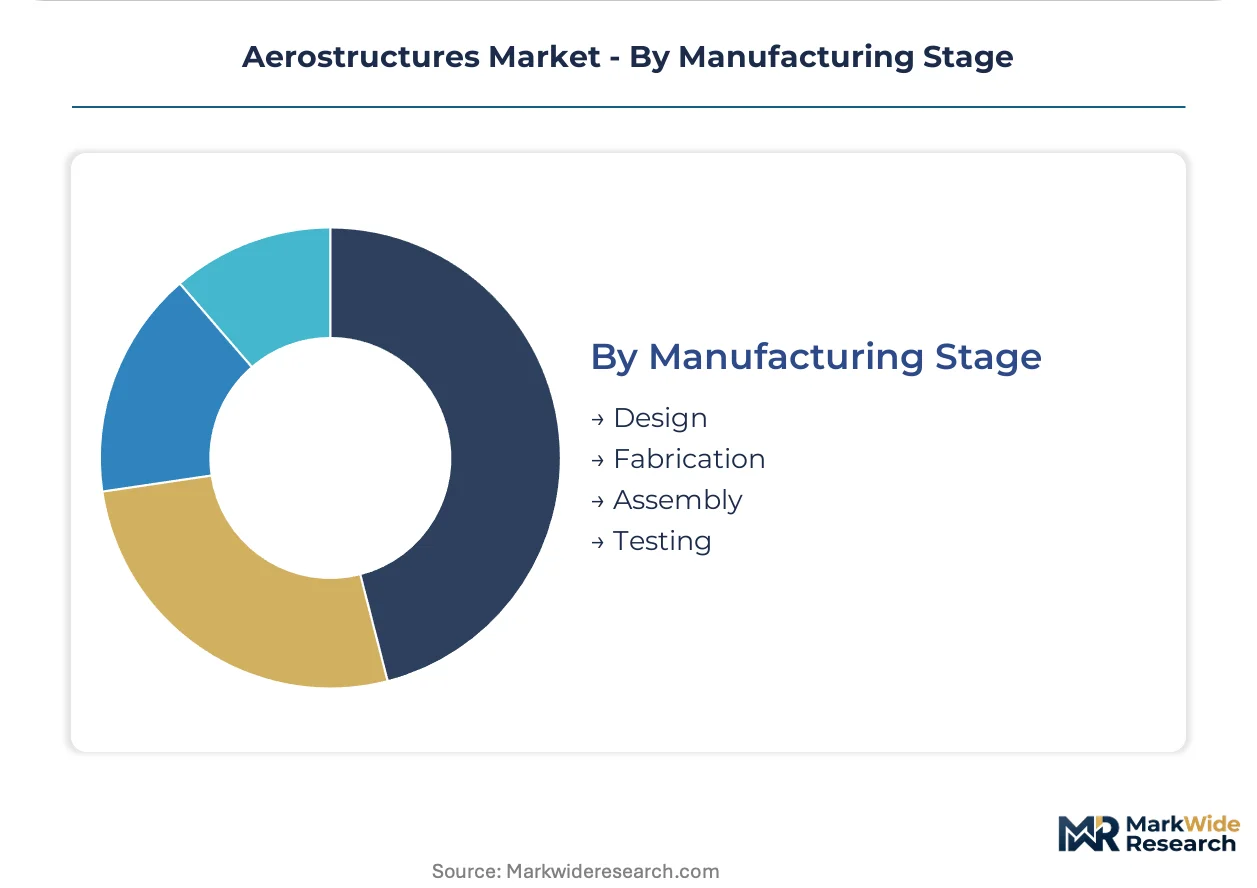
Manufacturing Stage:
Margin concentration varies across the value chain, with design and testing phases capturing intellectual property rents while fabrication and assembly compete on throughput efficiency.
- Design:Structural sizing, load path optimization, and certification planning require specialized aerospace engineering talent. Boeing and Airbus engineering centers in Seattle and Toulouse retain core aeromechanical design capabilities, outsourcing detailed design to specialized engineering services firms.
- Fabrication:Raw material conversion into detail parts through machining, forming, and composite layup. Spirit AeroSystems and GKN Aerospace facilities in the United Kingdom and United States compete on automated fiber placement throughput and titanium machining cycle times.
- Assembly:Integration of detail parts into major subassemblies and final aerostructure joining.
- Testing:Static, fatigue, and damage tolerance validation to demonstrate compliance with CS-25 and FAR Part 25 requirements.
Design and testing phases concentrate value capture; fabrication and assembly face margin compression from OEM rate acceleration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation procurement patterns diverge sharply by geography, with North American carriers prioritizing fleet renewal velocity while Asian operators emphasize MRO infrastructure buildout and European airlines integrate sustainability compliance into supplier selection.
United States
Boeing's 737 MAX and 777X production ramps drive concentrated demand for composite wing boxes and integrated fuselage systems. FAA damage tolerance mandates under Part 25 certification compress supplier qualification timelines. Wichita, Kansas anchors final assembly capacity, with Spirit AeroSystems operating major facilities for narrowbody platforms.
United Kingdom
Airbus wing manufacturing at Broughton and GKN Aerospace's composite operations sustain high-value fabrication employment. EASA CS-25 amendments for electrical system interaction with carbon-fiber structures force continuous engineering redesign cycles. The Midlands aerospace cluster specializes in engine nacelles and advanced composite tooling systems.
France
Airbus SE's vertically integrated aerostream manufacturing network controls critical subassembly flows from Toulouse engineering centers. EU Green Deal Aviation requirements reshape supplier qualification toward recyclable thermoplastic composites. The Occitanie region concentrates automated fiber placement capacity for next-generation wing programs.
Germany
Premium aerostructure engineering services cluster around Munich and Hamburg, supporting detailed design outsourcing from OEM engineering centers. REACH chemical regulations and national carbon accounting standards accelerate waterborne primer technology adoption. Northern German facilities specialize in titanium machining for engine pylons and landing gear attachments.
Japan
Composite material suppliers serve Boeing and Airbus tier-one integrators through qualified automated fiber placement lines in Nagoya and surrounding industrial zones. METI industrial policy supports carbon-fiber precursor manufacturing scale-up. Japanese fabricators concentrate on wing rib and control surface production for twin-aisle platforms.
Aerostructures Market Vendor Landscape
Capability concentration sits with tier-one integrators commanding FAA and EASA certification relationships; scale advantage sits with vertically aligned OEMs controlling final assembly flows. The market structures around three tiers: integrated platform specialists, component-focused fabricators, and engineering services providers. Consolidation pressure intensifies as OEM rate demands squeeze mid-tier suppliers. Dominant competitive moves include strategic partnerships for composite qualification and selective capacity expansion in low-cost manufacturing zones.
Among US-based fabricators, Spirit AeroSystems Inc. occupies the integrated fuselage and wing assembly tier, while Triumph Group, Inc. sits within the diversified component supplier archetype. GKN Aerospace represents the European specialist model focused on engine nacelles and advanced composite structures. These three anchors illustrate the geographic and capability segmentation shaping procurement negotiations.
| Leading Market Players |
|---|
| Spirit AeroSystems Inc. |
| Airbus SE |
| The Boeing Company |
| Leonardo S.p.A |
| GKN Aerospace |
| Saab AB |
| Triumph Group, Inc. |
| AAR Corp. |
| Cyient Ltd. |
| Others |
Supply Flow & Price Mechanics
The Wichita-Kansas-to-Seattle air freight corridor shapes cost dynamics for Boeing's tier-one suppliers, concentrating pricing power among composite wing box fabricators while forcing tier-two machine shops to absorb volatile titanium sponge costs from Russian and Chinese export channels.
Pricing Analysis
Long-term offtake agreements dominate Boeing and Airbus procurement, locking in aluminum and carbon-fiber pricing for multi-year production blocks while spot purchases govern titanium machining for engine pylons. Price differentiation rests on FAA/EASA certification tier and volume scale, with qualified suppliers commanding premiums over uncertified competitors. Cost compression in standard-grade fuselage aluminum is intensifying because Japanese and German mills compete on throughput for legacy narrowbody programs. Low-cost carriers and regional lessors exhibit highest price sensitivity, whereas flag carriers prioritize damage-tolerant design allowances over unit economics.
Supply Chain Analysis
Extended payment terms from Boeing and Airbus strain Wichita-based fuselage integrators, forcing tier-two fabricators toward supply-chain finance facilities backed by Japanese trading houses. Raw material flows draw from U.S. carbon-fiber precursor plants, Russian and Chinese titanium sponge exporters, and German aluminum rolling mills. Single-source vulnerability concentrates in large integrated fuselage assemblies dependent on Spirit AeroSystems' Kansas facilities. Distribution runs through OEM-controlled aerostream networks rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite qualification cycles and EASA CS-25 electrical system amendments are disrupting established supply relationships, creating openings for fabricators with induction consolidation capabilities and embedded sensor integration expertise.
For Market Incumbents: Entrench certification relationships with FAA and EASA by accelerating automated ultrasonic testing investments, countering the threat from European suppliers qualifying carbon-fiber PEEK formulations for wing ribs. Prioritize backward integration into carbon-fiber precursor manufacturing to offset Russian titanium volatility, while expanding Wichita-area capacity to defend against weather-disruption vulnerabilities. For New Entrants and Emerging Players: Establish a beachhead in urban air mobility airframe contracts, where eVTOL manufacturers lack established supplier relationships and demand distributed electric propulsion integration. Target Southeast Asian composite repair stations as airlines unbundle structural maintenance from full-service contracts. Lead with structural health monitoring aftermarket services, offering embedded sensor networks as a recurring-revenue wedge against OEM-authorized networks. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core aerostructure divisions to refocus on defense electronics. Long-term viability hinges on thermoplastic composite capabilities and EASA qualification track records. Monitor Airbus and Boeing supplier consolidation announcements as the primary inflection signal for mid-tier acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Qualification | Airbus and Boeing supplier teams are validating PEEK and PPS formulations for recyclable wing structures under EU Green Deal Aviation mandates. |
| Automated Fiber Placement Scale-Up | Italian and Japanese fabricators are climbing production lines to meet OEM rate targets for next-generation narrowbody platforms. |
| Structural Health Monitoring Integration | Embedded sensor networks for real-time fatigue detection capture unbundled airline maintenance spend away from OEM service networks. |
| Composite Repair Certification Investment | FAA-approved repair stations address technician shortages to capture Southeast Asian fleet expansion beyond OEM infrastructure deployment. |
| Closed-Loop Surface Finishing Compliance | EPA volatile organic compound rules push fabricators toward waterborne primer technologies and environmental equipment upgrades. |
Methodological Framework
A spread of perspectives from Boeing and Airbus procurement executives, Spirit AeroSystems plant managers, GKN Aerospace composite engineers, FAA certification specialists, and airline engineering directors converged on the working assumptions. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment documentation, EPA surface finishing enforcement records, and customs data on titanium sponge imports. Bottom-up fabrication capacity tallies were triangulated against top-down OEM production rate announcements.
Demand-supply balance modeling across the projection horizon incorporated fleet renewal program schedules, composite material qualification timelines, and labor availability at Wichita and Broughton manufacturing clusters. Segmentation dimensions included product architecture, material system, end-use mission profile, and manufacturing stage value capture. CAGRs were derived from production rate trajectories and material substitution elasticities, with automated fiber placement throughput and thermoplastic adoption curves as primary forecast inputs.
Stress conditions across titanium export policy shifts, EASA certification amendment timelines, and eVTOL program funding continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on OEM rate acceleration and regulatory compliance cost pass-through. Macroeconomic contraction, trade restriction escalation, or breakthrough thermoplastic processing technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market