
 Cold Gas Thrusters Market | 2026-2036
Cold Gas Thrusters Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Gas Thrusters Market Insights
The capability gap between vertically integrated prime contractors and specialized component suppliers is unwinding as constellation-scale orders force new procurement models. Moog Inc. leverages its heritage in precision fluid control to dominate high-reliability satellite attitude control contracts. THRUST ME sustains a differentiated position through proprietary iodine-compatible system architectures that extend to cold gas derivatives. Bradford Space anchors European supply for small satellite integrators seeking qualified non-U.S. propulsion sources.
Cold gas thrusters are propulsion devices that expel stored inert gas through converging-diverging nozzles to generate thrust, typically operating at specific impulse values below 80 seconds with feed pressures ranging from 100 to 400 bar depending on mission duty cycle. These systems serve primary industrial functions in satellite attitude determination and control, orbital insertion corrections, and deorbiting maneuvers where simplicity and reliability outweigh propulsive efficiency. Nitrogen propellant configurations lead the installed base due to heritage qualification and benign handling characteristics, while xenon segments capture margin pools where missions demand higher storage density for extended operational life. Small satellite applications represent the fastest-growing structural category as megaconstellation operators standardize on miniaturized, high-production-volume thruster designs.
NASA's technology readiness level requirements and the U.S. FAA's launch licensing framework shape product qualification pathways and market access conditions for domestic suppliers. ESA's Clean Space initiative and REACH chemical registration protocols in Europe impose material selection constraints and end-of-life disposal mandates on propulsion system designers. Stakeholders must monitor how emerging orbital debris regulations in multiple jurisdictions redefine minimum thrust performance and redundancy requirements for constellation-class spacecraft.
Market Dynamics
Megaconstellation procurement models are compressing supplier qualification cycles and forcing modular thruster architectures that sacrifice heritage customization for production velocity.
Growth Catalysts
- ESA Clean Space mandates:European orbital debris protocols now require deorbit capability on all new satellites, expanding addressable demand for precision cold gas systems in end-of-life maneuvers.
- Nitrogen propellant standardization:Ground handling infrastructure at launch sites from French Guiana to Vandenberg has consolidated around nitrogen-compatible interfaces, reducing integration friction for constellation operators.
- Small satellite volume scaling:Toulouse aerospace clusters now coordinate just-in-time thruster delivery for satellite integrators running parallel production lines.
Market Restraints
- Xenon feedstock concentration:Noble gas refining capacity concentrates in South African and Russian industrial complexes, exposing propellant costs to geopolitical supply interruptions.
- Specific impulse ceiling:Cold gas physics caps performance below 80 seconds, disqualifying the technology from orbital transfer missions where electric propulsion achieves 1500+ seconds.
- REACH material constraints:ECHA registration requirements for propulsion system coatings and seal materials extend European qualification timelines by 12-18 months versus U.S. pathways.
Strategic Opportunities
- India commercial launch growth:ISRO's SSLV program and private pad access at Sriharikota create demand for qualified non-U.S., non-European propulsion suppliers on accelerated timelines.
- Iodine-cold gas hybrid architectures:Convergence of electrospray and cold gas feed systems enables dual-mode propulsion packages that extend mission flexibility without doubling subsystem mass.
- On-orbit servicing standards:Emerging ISO protocols for satellite rendezvous and docking specify standardized thrust interfaces, opening retrofit markets for existing spacecraft.
Industry Challenges
- Propulsion systems engineering talent:Universities produce insufficient graduates with combined expertise in compressible flow, spacecraft dynamics, and space-qualified manufacturing.
- Space heritage certification timelines:NASA technology readiness level advancement to flight-qualified status demands 24-36 months of environmental testing and orbital demonstration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Gas Thrusters Market |
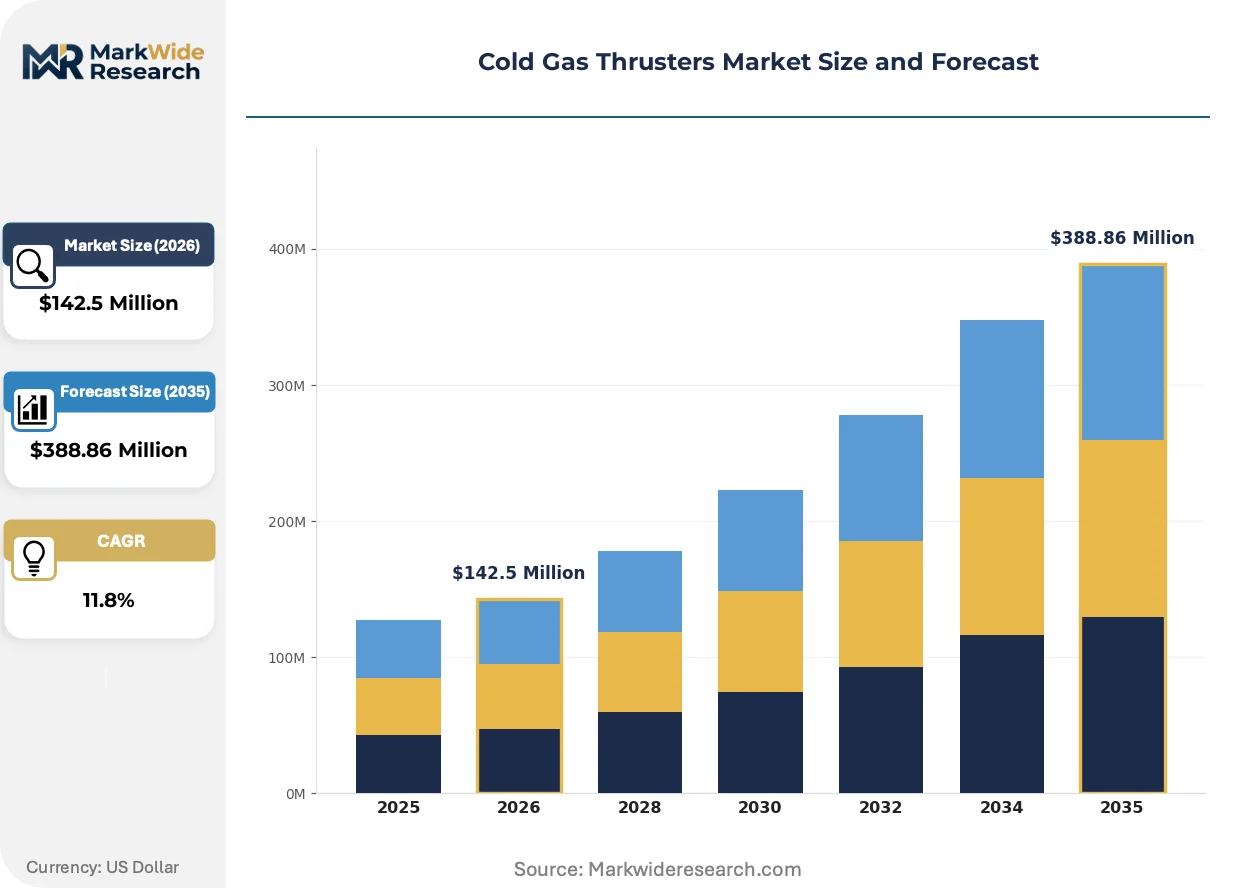
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $388.86 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Nitrogen, Helium, Xenon, Argon, Carbon Dioxide Application: Satellite Attitude Control, Spacecraft Orbital Maneuvers, Small Satellites, Launch Vehicle Systems, Scientific Missions Manufacturing Stage: Design, Assembly, Testing, Integration, Quality Assurance End User: Satellite Manufacturers, Space Agencies, Defense Contractors, Commercial Operators |
| Companies Covered | Moog Inc., VACCO Industries, THRUST ME, Safran SA, Northrop Grumman, Bradford Space, Aerojet Rocketdyne, Marotta Controls, Busek Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Gas Thrusters Market Trends and Innovations
Component miniaturization and additive manufacturing are collapsing the traditional trade-off between thruster performance and production scalability that defined satellite propulsion for three decades.
Additive-manufactured titanium propellant tanks with integrated plumbing channels are supplanting conventional welded assemblies in constellation-class satellite programs. SpaceX and Planet Labs procurement specifications now prioritize unit-to-unit consistency over individualized optimization. This manufacturing shift is compressing supplier margins while expanding addressable order volumes for qualified production houses.
REACH chemical registration protocols in Europe now require full substance disclosure for all materials with intended release to the space environment. Propulsion designers must reformulate valve greases and elastomer seals to meet SVHC screening thresholds. French suppliers around Toulouse have reorganized supply chains to source compliant alternatives from domestic specialty chemical producers.
Constellation operators now unbundle propulsion procurement from prime satellite contracts, establishing direct commercial relationships with thruster specialists. This channel disintermediation fragments order volumes across multiple suppliers but accelerates iteration cycles for performance improvements. The pattern is most visible in U.S. small satellite programs where vertical integration at primes has weakened.
Cold Gas Thrusters Market Segmentation
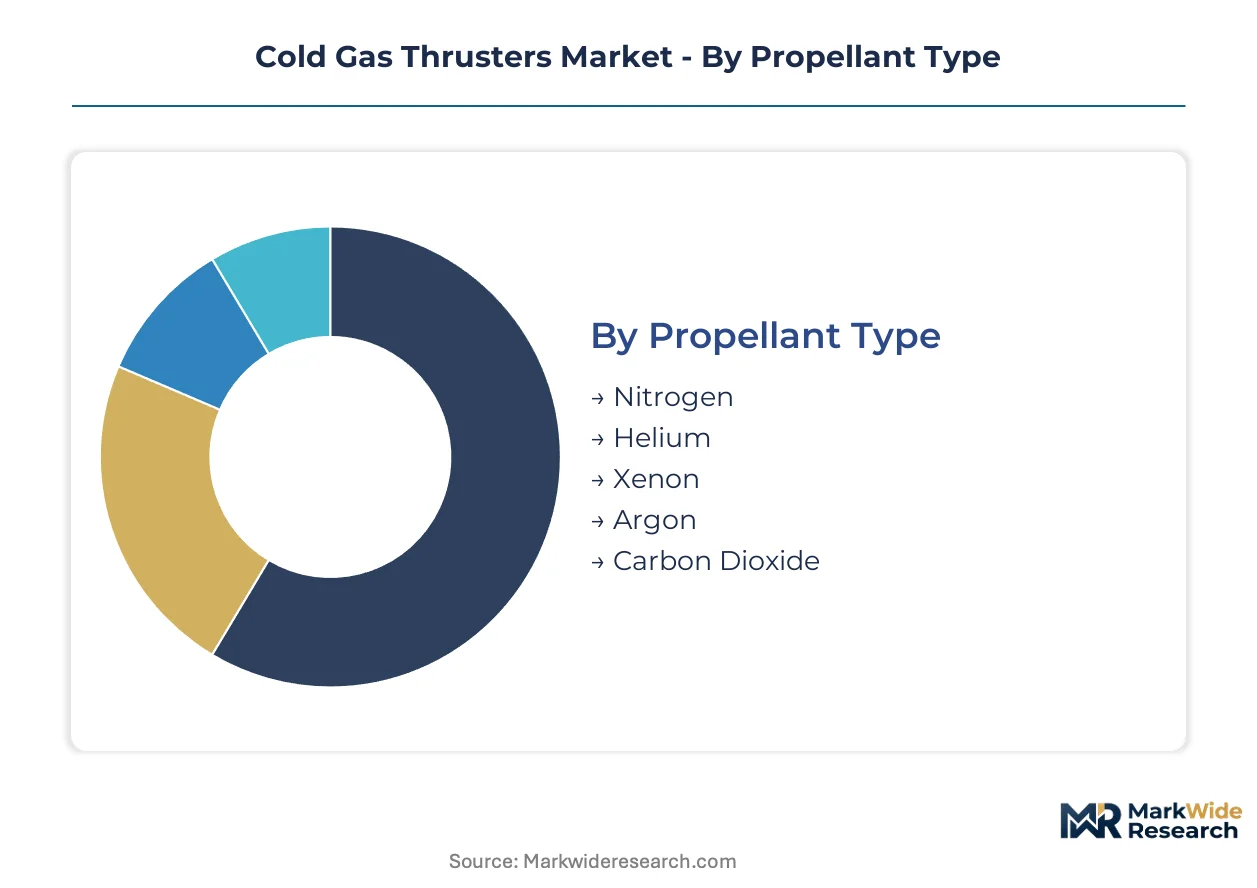
Cold gas thruster procurement patterns diverge sharply across propellant chemistry and mission class, with regulatory qualification pathways and constellation-scale production economics determining supplier positioning. Understanding these segment boundaries enables precise alignment of manufacturing capacity with demand concentration points.
Propellant Type:
NASA technology readiness requirements and ESA Clean Space mandates create divergent qualification burdens across inert gas chemistries, favoring propellants with established ground-handling infrastructure.
- Nitrogen:Dominates the installed base due to heritage qualification under NASA environmental testing protocols and benign handling characteristics at pressures between 100-400 bar. Demand concentrates at Vandenberg and French Guiana launch complexes where nitrogen-compatible ground infrastructure eliminates integration friction for constellation operators deploying small satellite networks.
- Xenon:Captures premium positioning where storage density determines mission endurance, though South African and Russian refining concentration exposes supply chains to geopolitical interruption. European small satellite programs in Toulouse prioritize xenon for extended operational life despite REACH registration complexity for system coatings.
- Helium:Serves specialized scientific missions requiring ultra-low temperature compatibility.
- Argon:Finds niche adoption in cost-sensitive applications where specific impulse requirements remain minimal.
- Carbon Dioxide:Enables in-situ resource utilization concepts for planetary missions with atmospheric processing capabilities.
Established volume favors nitrogen; emerging adoption favors xenon.
Application:
Constellation deployment schedules are compressing supplier qualification cycles and forcing modular architectures that sacrifice heritage customization for production velocity across mission categories.
- Small Satellites:Megaconstellation procurement now unbundles propulsion from prime satellite contracts, establishing direct commercial relationships with thruster specialists. SpaceX and Planet Labs specifications prioritize unit-to-unit consistency over individualized optimization, collapsing traditional performance-customization trade-offs.
- Satellite Attitude Control:Precision pointing requirements for Earth observation and communications payloads demand high-reliability valve response times under 50 milliseconds. Moog Inc. leverages heritage fluid control expertise to dominate this segment for geostationary and medium-Earth-orbit platforms.
- Spacecraft Orbital Maneuvers:Deorbit capability mandates under ESA Clean Space protocols now require end-of-life thrust profiles for all new satellites.
- Launch Vehicle Systems:Upper-stage attitude control and payload fairing separation sequences utilize cold gas for simplicity in single-use applications.
- Scientific Missions:Interplanetary probes and deep-space observatories employ cold gas where electric propulsion power constraints prohibit adoption.
Production scaling favors small satellites; margin concentration favors attitude control.
Manufacturing Stage:
Additive manufacturing adoption varies across the production sequence, with titanium propellant tank fabrication seeing the most rapid process transformation.
- Assembly:Additive-manufactured titanium tanks with integrated plumbing channels now supplant welded assemblies in constellation-class programs, compressing lead times from months to weeks.
- Testing:NASA technology readiness level advancement demands 24-36 months of environmental testing and orbital demonstration, creating bottlenecks for new market entrants.
- Design:Proprietary iodine-compatible architectures at THRUST ME extend to cold gas derivatives, enabling dual-mode system development.
- Integration:Just-in-time delivery coordination with Toulouse aerospace clusters supports parallel satellite production lines.
- Quality Assurance:REACH SVHC screening thresholds for valve greases and elastomer seals extend European qualification timelines 12-18 months versus U.S. pathways.
Process innovation concentrates in assembly; regulatory friction concentrates in quality assurance.
End User:
Procurement authority is fragmenting as constellation operators establish direct commercial relationships with propulsion specialists, bypassing traditional prime contractor channels.
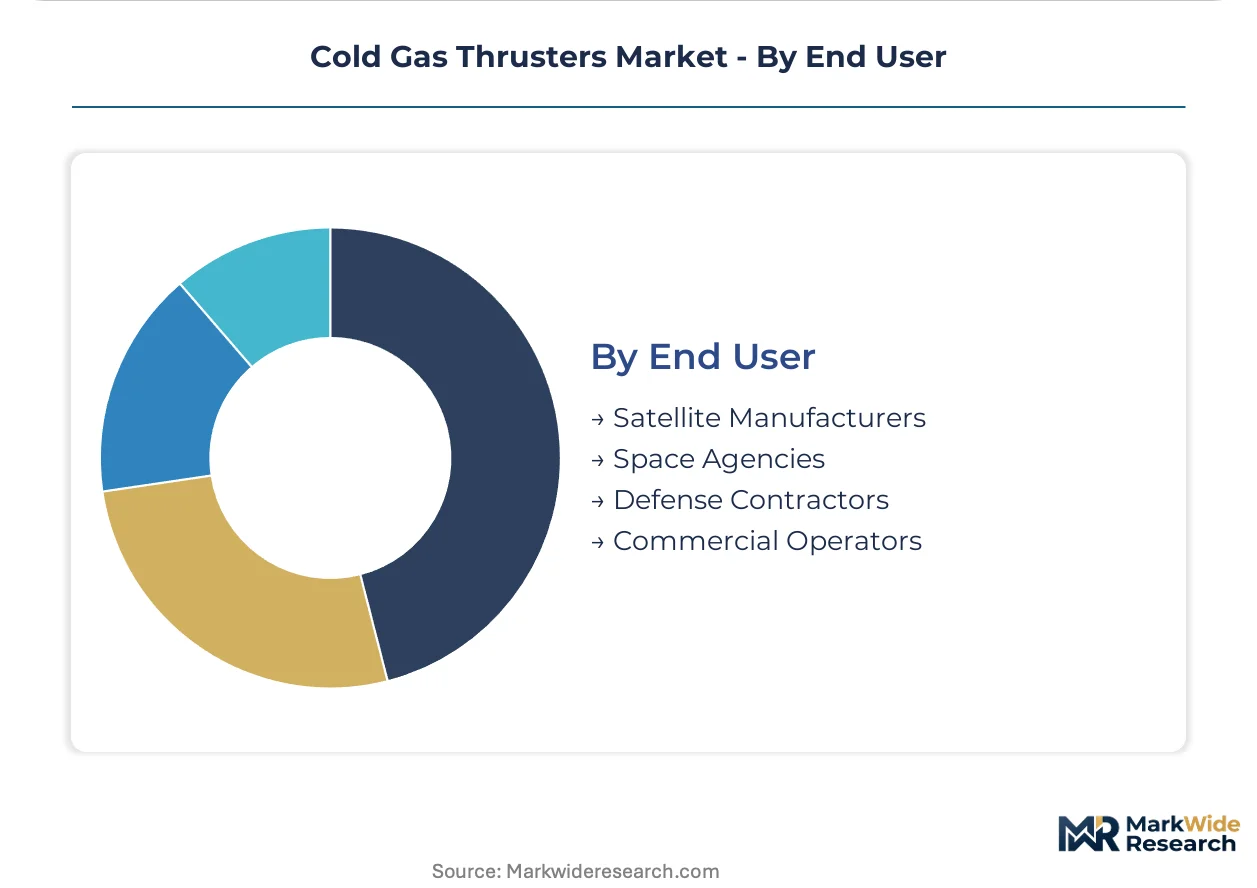
- Satellite Manufacturers:U.S. prime contractors face weakening vertical integration as megaconstellation operators standardize on miniaturized, high-production-volume thruster designs sourced directly from specialists.
- Commercial Operators:Planet Labs and similar constellation deployers now specify thruster performance requirements independently, accelerating iteration cycles but fragmenting order volumes.
- Space Agencies:ESA Clean Space mandates and NASA technology readiness frameworks shape qualification pathways and market access conditions.
- Defense Contractors:Classified payload requirements sustain demand for high-reliability heritage systems with extended environmental testing protocols.
Volume expansion favors commercial operators; margin protection favors defense contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive constellation operators in India and Southeast Asia drive volume procurement, while defense and scientific buyers in the United States and France absorb premium positioning for heritage-qualified systems.
United States
NASA's technology readiness level framework and FAA launch licensing requirements create steep qualification barriers that favor established suppliers. Vandenberg Space Force Base and Cape Canaveral consolidate nitrogen-compatible ground infrastructure for megaconstellation deployments. Moog Inc. leverages decades of precision fluid control heritage to dominate satellite attitude control contracts for geostationary and medium-Earth-orbit platforms.
France
ESA Clean Space mandates require deorbit capability on all new satellites, expanding demand for precision cold gas systems in end-of-life maneuvers. REACH chemical registration protocols impose material selection constraints on propulsion system designers. The Toulouse aerospace cluster coordinates just-in-time thruster delivery for satellite integrators running parallel production lines, with Safran SA anchoring regional supply chains.
Germany
Small satellite integrators seek qualified non-U.S. propulsion sources to diversify supply chain risk. The country's national space regulator enforces stringent environmental testing protocols aligned with ESA standards. Bavaria and Baden-Württemberg host specialized component suppliers serving European constellation programs with accelerated qualification timelines.
India
ISRO's SSLV program and private pad access at Sriharikota create demand for qualified propulsion suppliers on accelerated timelines. The country's national space agency promotes domestic manufacturing through technology transfer agreements. Bangalore and Hyderabad clusters attract thruster specialists seeking to bypass Western qualification bottlenecks for commercial launch growth.
Japan
METI funding for space debris removal missions stimulates precision pointing requirements for Earth observation payloads. JAXA technology demonstration programs provide orbital qualification pathways for new market entrants. Tokyo and Nagoya industrial corridors sustain heritage aerospace suppliers with defense and scientific mission expertise.
Cold Gas Thrusters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage-qualified precision specialists commanding premium positioning while volume manufacturers compress margins through modular architectures. The vendor base concentrates around three strategic tiers: vertically integrated prime contractors, specialized thruster component houses, and emerging dual-mode propulsion developers. Competitive dynamics center on qualification timeline acceleration and additive manufacturing adoption for production scaling.
Among heritage precision specialists, Moog Inc. and VACCO Industries occupy positions exemplifying decades of flight-proven fluid control expertise. THRUST ME represents the emerging archetype of dual-mode system developers, leveraging proprietary architectures that bridge electrospray and cold gas feed technologies. Bradford Space anchors the European non-U.S. supply tier for small satellite integrators seeking qualified alternatives to American sources.
| Leading Market Players |
|---|
| Moog Inc. |
| VACCO Industries |
| THRUST ME |
| Safran SA |
| Northrop Grumman |
| Bradford Space |
| Aerojet Rocketdyne |
| Marotta Controls |
| Busek Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Twenty-four to thirty-six month qualification timelines for NASA technology readiness level advancement compress pricing power for new entrants while amplifying margin protection for heritage-qualified suppliers with established flight-proven records. This lead-time band concentrates buyer leverage around constellation-scale procurement offices that unbundle propulsion from prime satellite contracts, forcing component specialists to absorb integration cost exposure in exchange for volume access.
Pricing Analysis
After-market service contracts and extended qualification support packages drive lifetime value capture for established suppliers, with heritage-qualified precision specialists commanding premium positioning over volume manufacturers. Three-tier pricing structure across heritage-certified, production-standard, and cost-optimized tiers separates Moog Inc.'s satellite attitude control offerings from Bradford Space's constellation-optimized alternatives. Cost compression in the production-standard tier is intensifying because megaconstellation operators prioritize unit-to-unit consistency over individualized optimization. Commercial constellation deployers exhibit highest price sensitivity, while defense contractors absorb premium positioning for extended environmental testing protocols.
Supply Chain Analysis
Just-in-time delivery coordination with Toulouse aerospace clusters supports parallel satellite production lines, though xenon feedstock dependence on South African and Russian refining capacity drives strategic stockpile preferences among European small satellite programs. Titanium propellant tank fabrication draws from U.S. additive manufacturing houses, French precision machining clusters, and Indian emerging production facilities. Supply chain risk centers on single-source vulnerability for noble gas refining capacity concentrated in geopolitically exposed industrial complexes. Distribution runs through direct commercial relationships between thruster specialists and constellation operators, bypassing traditional prime contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold gas thruster procurement is shifting toward platform-standardized interfaces that enable interoperability across megaconstellation fleets, with emerging ISO protocols for satellite rendezvous and docking creating ecosystem-level lock-in effects for early movers.
For Market Incumbents: Shield heritage positioning by accelerating additive manufacturing adoption for titanium propellant tank production, compressing lead times from months to weeks to match emerging volume manufacturer velocity. Deepen backward integration into nitrogen-compatible valve subsystems to capture margin pools threatened by channel disintermediation. Prioritize certification investment in ESA Clean Space deorbit capability requirements to maintain European market access against REACH-extended qualification timelines.
For New Entrants and Emerging Players: NASA technology readiness level fast-track pathways through orbital demonstration partnerships offer accelerated qualification timelines versus traditional 24-36 month environmental testing cycles. Target India's ISRO SSLV program and private pad access at Sriharikota, where demand for qualified non-U.S., non-European propulsion suppliers runs on accelerated timelines unmatched by Western qualification bottlenecks. Lead with iodine-cold gas hybrid architectures that extend mission flexibility without doubling subsystem mass, differentiating against pure-play cold gas incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because constellation-scale procurement volumes are fragmenting order flows across multiple suppliers while compressing margins, creating distressed asset opportunities among specialized component houses lacking production velocity. Target dual-mode propulsion developers with proprietary architectures bridging electrospray and cold gas feed technologies, representing the emerging archetype most vulnerable to strategic acquisition by vertically integrated primes. Watch ESA Clean Space mandate expansion to additional orbital debris protocols as the signal indicating accelerated deorbit capability demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Scale-Up | Titanium propellant tank production compresses lead times from months to weeks for constellation programs. |
| Dual-Mode Architecture Development | Iodine-compatible system convergence extends mission flexibility without doubling subsystem mass penalties. |
| REACH Compliance Reformulation | Valve grease and elastomer seal alternatives from French specialty chemical producers secure European market access. |
| Direct Constellation Procurement | Bypassing prime contractor channels accelerates iteration cycles but fragments order volumes across suppliers. |
| Orbital Demonstration Partnership | NASA technology readiness level advancement through flight-proven status opens heritage-qualified positioning. |
Research Methodology
Operator-level perspectives from satellite propulsion engineers, constellation procurement directors, ESA qualification officers, and launch site integration specialists anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FAA launch licensing records, ESA Clean Space technical documentation, NASA technology readiness level advancement databases, and customs trade data for noble gas feedstock flows. Bottom-up thruster unit demand estimates triangulated against top-down constellation deployment projections across the analysis window.
Sensitivity analysis framing tested propellant chemistry substitution elasticity, qualification timeline compression scenarios, and megaconstellation deployment schedule slippage impacts across the projection horizon. The analytical framework modeled segmentation dimensions including propellant type, application mission class, manufacturing stage process position, and end-user procurement authority. CAGRs were derived from installed base growth rates adjusted for replacement cycle acceleration and technology transition patterns. Industry-specific forecast inputs incorporated REACH registration timeline extensions and ISRO SSLV launch cadence assumptions.
Underlying assumptions cover nitrogen infrastructure consolidation at Vandenberg and French Guiana, xenon supply concentration persistence, and additive manufacturing adoption curves, with deviation risk concentrated in geopolitical noble gas supply interruptions and orbital debris regulation expansion beyond current ESA mandates. Forecasts reflect these documented conditions with acknowledged uncertainty bands. Revision becomes warranted when Clean Space mandate adoption crosses thresholds triggering mandatory deorbit capability on non-European flagged satellites.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market