
 Singapore Life and Non-Life Insurance Market | 2026-2036
Singapore Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Life and Non-Life Insurance Market Insights
SME buyers is rotating toward bundled commercial coverage as the fastest-growing buyer archetype in Singapore's insurance landscape. NTUC Income Insurance leverages its cooperative structure to sustain competitive positioning across mass-market segments. Great Eastern Life Assurance anchors the bancassurance channel through deep bank partnerships. AIA Singapore dominates the agency force with one of the largest tied-agent networks in the city-state.
Singapore Life and Non-Life Insurance encompasses risk-pooling contracts where insurers collect premiums to provide financial protection against mortality, morbidity, property damage, and liability events, with solvency ratios and risk-based capital requirements serving as core technical parameters governing product pricing and reserve adequacy. Life Insurance and Health Insurance occupy the mature premium base where margin pools concentrate in participating whole-life products and integrated shield plans. Property Insurance and Casualty Insurance represent faster-growing segments as climate risk awareness and cyber liability exposures expand corporate demand. Online Platforms within the Distribution Channel dimension are capturing disproportionate growth velocity among digitally native customer cohorts.
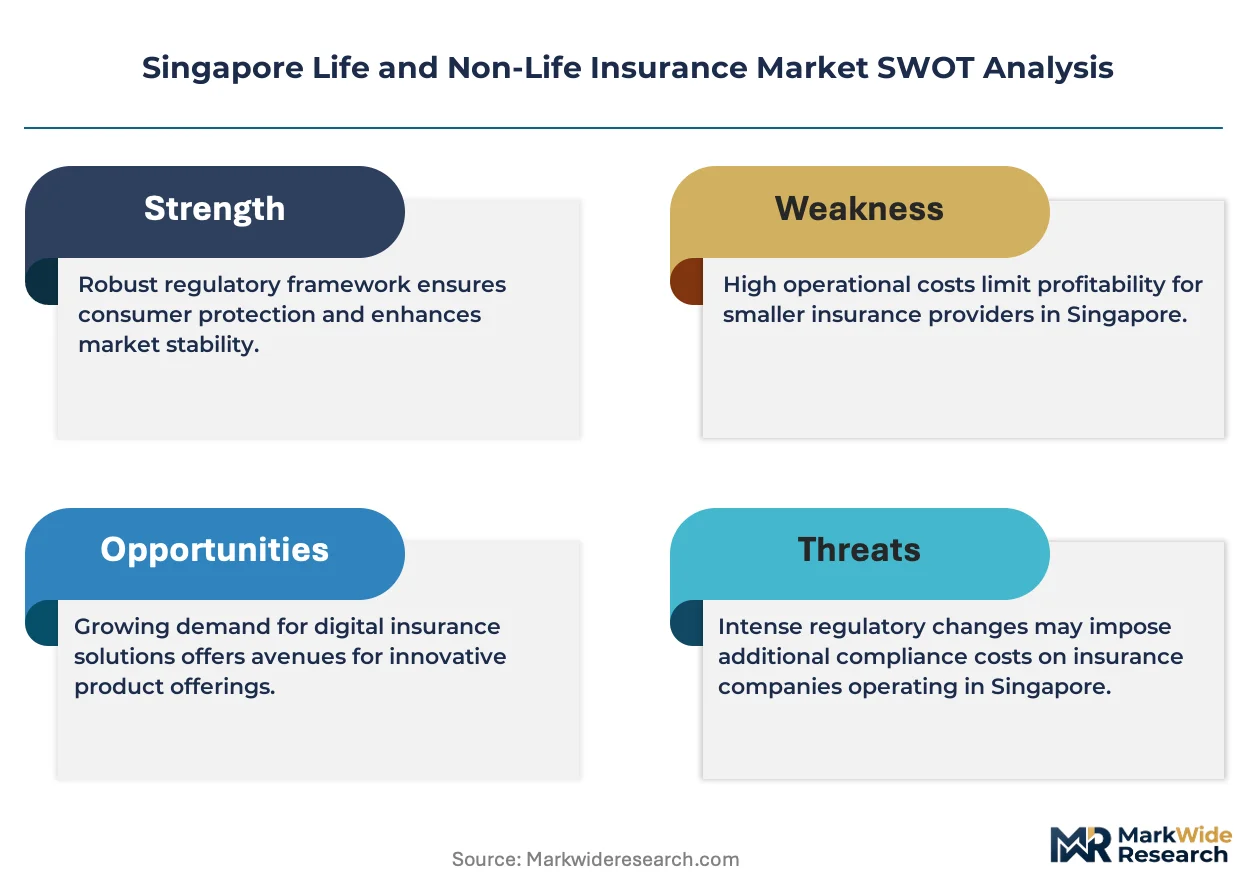
The Monetary Authority of Singapore enforces risk-based capital frameworks that elevate product standards and barrier to entry for new market participants. The country's national financial regulator coordinates with the Personal Data Protection Commission to shape data governance requirements for digital underwriting and claims processing. Stakeholders must monitor how evolving capital adequacy rules and open-architecture distribution mandates will reshape competitive positioning between incumbent insurers and technology-enabled challengers.
Market Dynamics
The Monetary Authority of Singapore's tightening risk-based capital frameworks is compressing product margins while forcing incumbents to rebalance toward higher-yielding commercial lines and digital distribution infrastructure.
Growth Catalysts
- Climate risk disclosure mandates:Corporate buyers in Singapore are accelerating property and casualty coverage purchases as the Personal Data Protection Commission aligns data governance with environmental liability reporting requirements.
- SME commercial bundling:Small and medium enterprises across the city-state are consolidating fragmented policies into integrated commercial packages, reducing acquisition costs and simplifying claims workflows.
- Embedded insurance APIs:Fintech platforms and neobanks are integrating life and health products directly into digital banking interfaces, collapsing traditional distribution friction for mass-market segments.
Market Restraints
- Low interest rate compression:Persistently compressed yields on fixed-income portfolios are constraining participating whole-life product profitability and forcing reserve strengthening.
- Reinsurance capacity concentration:Catastrophe bond markets and alternative capital providers in Bermuda and London dominate peak risk transfer, creating pricing volatility for property catastrophe layers.
- Legacy system technical debt:Core policy administration platforms running on decades-old architectures impose integration costs that exceed digital-native competitors' entire technology budgets.
Strategic Opportunities
- Cyber liability white space:ransomware and business interruption exposures among Singapore's financial services and technology sectors remain underpenetrated relative to peer Asian financial centers.
- Integrated shield plan innovation:The Central Provident Fund Board's MediShield Life framework creates a regulatory tailwind for private insurers to build supplementary coverage layers atop universal base protection.
- Parametric climate products:Converging satellite imagery and blockchain-based smart contracts enable index-triggered payouts for flood and extreme heat events without traditional loss adjustment.
Industry Challenges
- Actuarial data science talent scarcity:The intersection of predictive modeling, regulatory capital calculation, and cloud infrastructure engineering commands compensation premiums that strain mid-tier insurer cost structures.
- Open architecture distribution mandates:The Monetary Authority's push for unbundled advisory and product sales forces incumbents to reconfigure bancassurance economics and retrain tied-agent forces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Life and Non-Life Insurance Market |
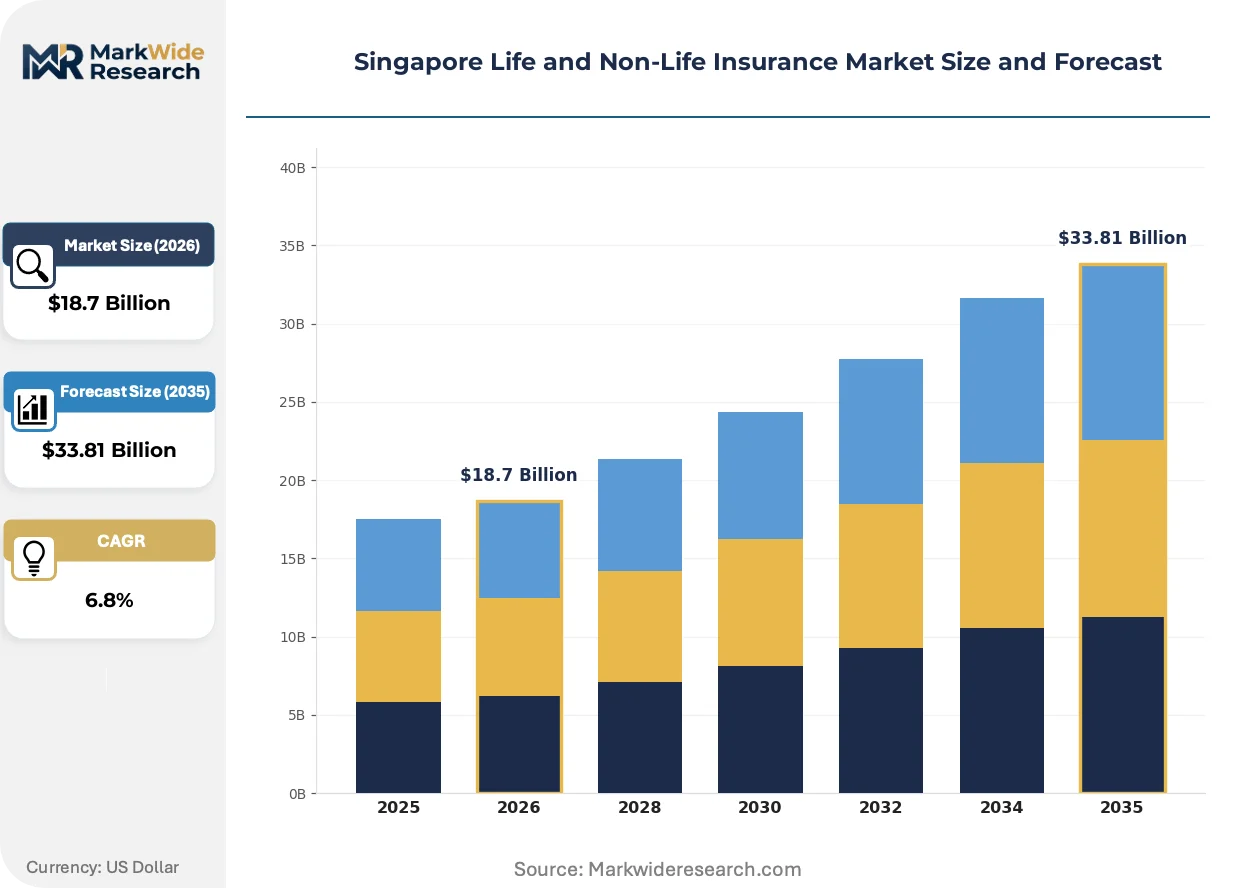
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Customer Type: Individuals, Corporates, SMEs, Government Distribution Channel: Direct Sales, Brokers, Banks, Online Platforms Coverage Type: Term Life, Whole Life, Supplementary, Comprehensive |
| Companies Covered | Manulife (Singapore) Pte. Ltd., NTUC Income Insurance, Great Eastern Life Assurance Co. Ltd., HSBC Life Singapore, Aviva Singapore, Prudential Plc, Singapore Life Holdings Pte. (Singlife), Chubb Singapore, AIA Singapore Pte. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Life and Non-Life Insurance Market Trends and Innovations
Digital underwriting infrastructure and alternative risk transfer mechanisms are compressing traditional value chain segments while creating new entry points for technology-enabled challengers and capital market participants.
Artificial intelligence-powered claims triage is displacing manual assessment workflows in high-frequency health and motor segments. Singapore's direct digital insurers are deploying natural language processing for first-notice-of-loss intake, compressing settlement cycles from weeks to hours. This capability is displacing traditional loss adjuster networks and forcing incumbents to restructure their claims operating models around exception-handling rather than routine processing.
Singapore's risk-based capital framework revisions are elevating internal model sophistication requirements for insurers writing commercial property and specialty casualty lines. The Monetary Authority now demands granular catastrophe exposure modeling and dynamic liquidity stress testing that exceeds Solvency II equivalence standards. Domestic carriers with limited actuarial depth are responding through mandatory reinsurance placements and third-party capital relief structures.
Corporate risk managers are consolidating broker relationships and demanding integrated analytics platforms that unify property, casualty, and employee benefits data. This concentration is compressing commission pools for traditional intermediaries while favoring global brokers with proprietary risk intelligence capabilities. The shift is most visible among Singapore's technology and pharmaceutical manufacturing clusters, where multinational parents mandate standardized coverage architectures across regional subsidiaries.
Singapore Life and Non-Life Insurance Market Segmentation
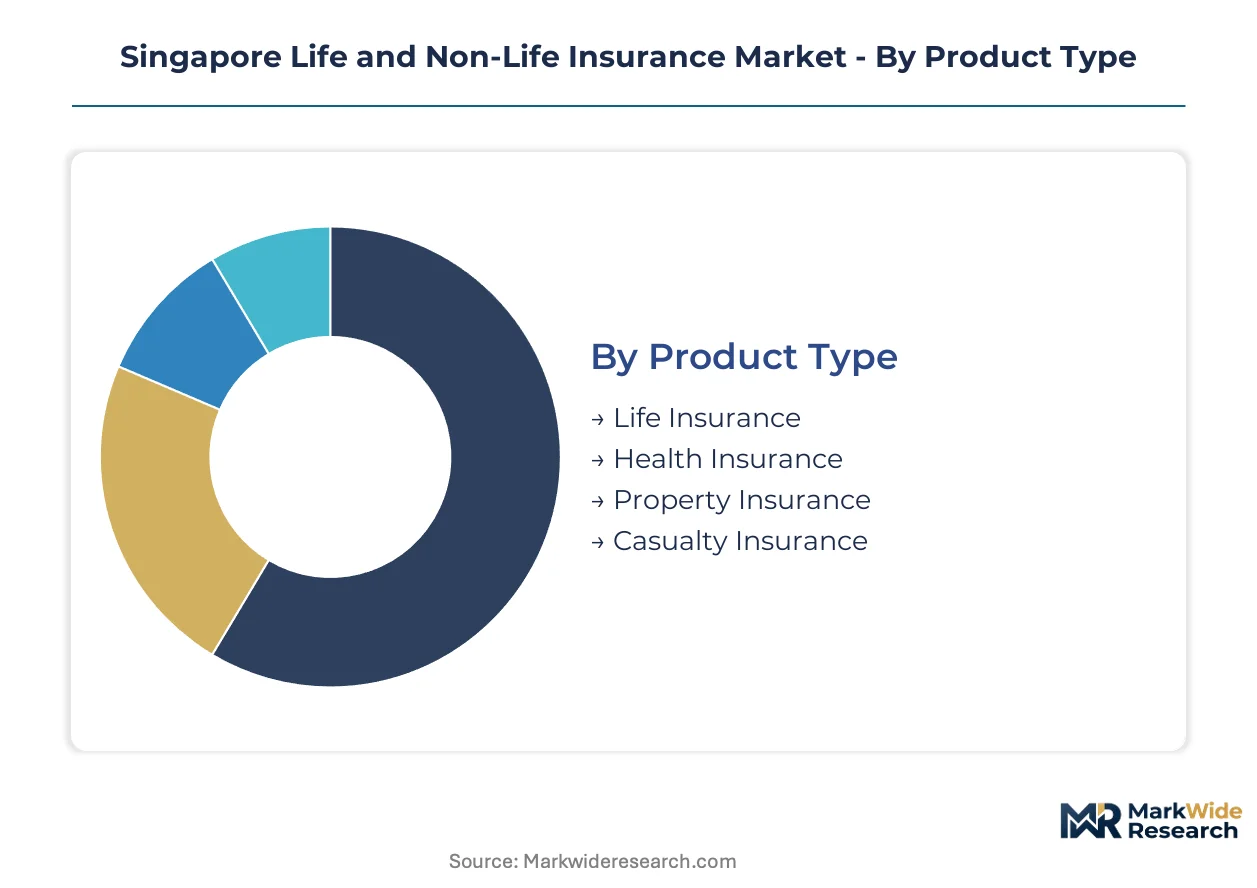
Segmentation in Singapore's insurance market reveals how regulatory capital requirements and distribution mandates reshape competitive boundaries across product lines and customer archetypes. The Monetary Authority of Singapore's risk-based capital frameworks create divergent margin profiles that favor certain combinations of coverage type and distribution infrastructure over others.
Product Type:
The Monetary Authority of Singapore applies differentiated risk-based capital charges across mortality, morbidity, and property-catastrophe exposures, compressing margins in capital-intensive segments while rewarding diversification into commercial lines.
- Life Insurance:Participating whole-life products dominate premium volumes through guaranteed surrender values and dividend accumulation features. The Central Provident Fund Board's mandatory savings framework channels mass-market demand toward insurers with bancassurance scale, though low interest rate compression strains participating fund profitability.
- Health Insurance:Integrated shield plans built atop MediShield Life represent the primary growth vector, with private insurers layering supplementary coverage for private hospital wards and pre-post hospitalization benefits. The Central Provident Fund's MediSave integration creates sticky customer relationships that reduce switching elasticity.
- Property Insurance:Commercial property coverage accelerates as climate risk disclosure mandates elevate corporate awareness of flood and business interruption exposures.
- Casualty Insurance:Cyber liability and professional indemnity lines expand fastest among Singapore's financial services and technology sectors.
Established volume favors Life Insurance; emerging adoption favors Health Insurance.
Customer Type:
Cost tier differentiation separates mass-market individual buyers from commercial segments where bundled coverage and risk engineering services command pricing power.
- Individuals:Mass-market buyers concentrate in term life and integrated shield plans distributed through bank branches and digital platforms. The Central Provident Fund's automatic payroll deduction infrastructure reduces friction for recurring premium collection.
- SMEs:Small and medium enterprises rotate fastest toward bundled commercial packages combining property, liability, and employee benefits coverage. The Monetary Authority's simplified risk-based capital treatment for SME-focused products attracts new market entrants.
- Corporates:Multinational subsidiaries demand standardized regional coverage architectures with centralized risk intelligence and captive insurance coordination.
- Government:Public sector procurement concentrates in large-ticket infrastructure and public health schemes with extended tenor requirements.
Margin concentration sits with Corporates; volume expansion concentrates with SMEs.
Distribution Channel:
Volume flows concentrate in bank partnerships and tied-agent networks, while growth velocity shifts toward digital infrastructure with lower customer acquisition costs.
- Banks:Bancassurance partnerships with DBS, OCBC, and UOB dominate mass-market life and health distribution through branch networks and digital banking integration. The Monetary Authority's open-architecture mandates are forcing unbundling of product sales from advisory services.
- Online Platforms:Direct digital insurers and embedded insurance APIs capture disproportionate growth among digitally native cohorts through natural language processing claims triage and instant underwriting. Fintech platforms collapse traditional distribution friction by integrating coverage into banking and e-commerce workflows.
- Direct Sales:Captive agent forces concentrate in affluent segments requiring complex estate planning and high-net-worth solutions.
- Brokers:Commercial property and specialty casualty placement depends on global brokers with proprietary catastrophe modeling and risk intelligence capabilities.
Legacy volume anchors Banks; growth velocity favors Online Platforms.
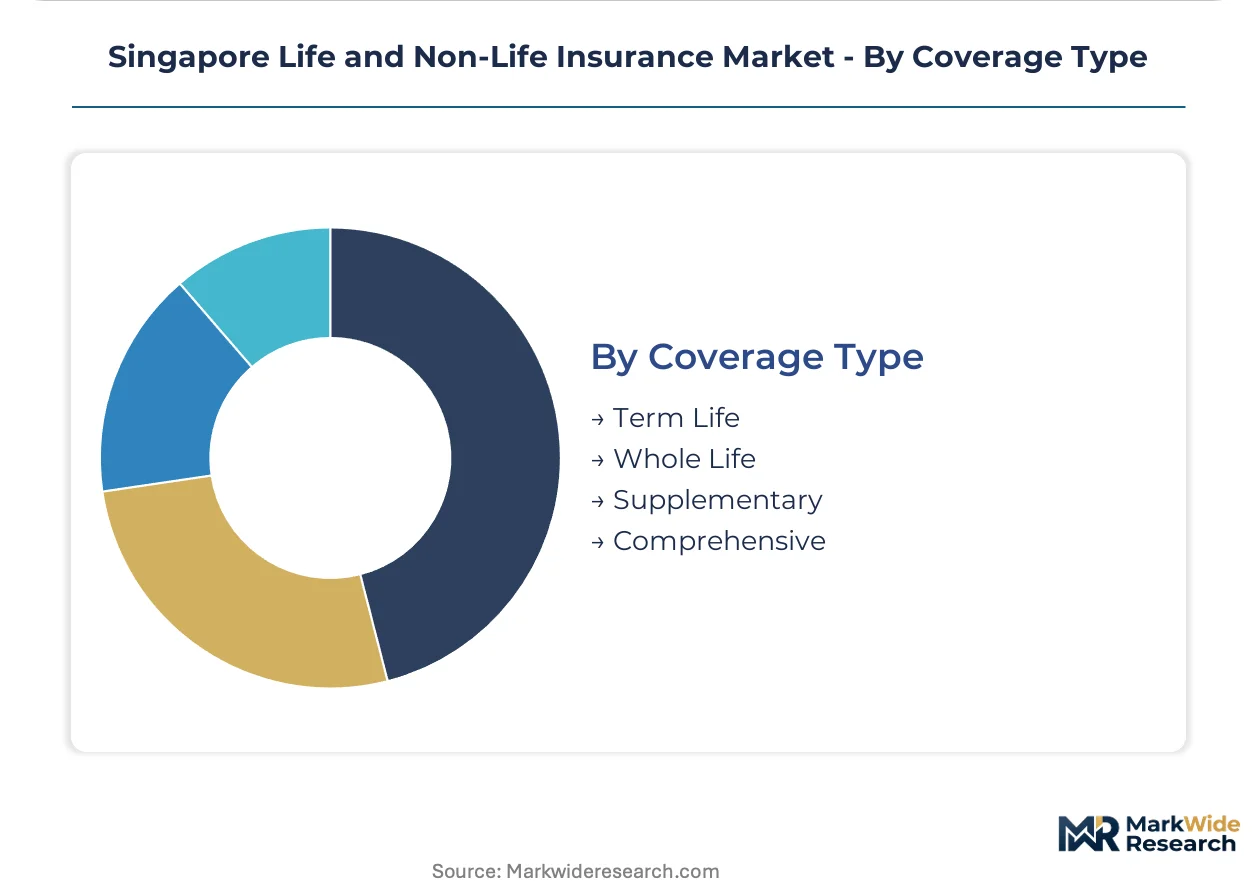
Coverage Type:
Maturity gradients separate commoditized term products from participating whole-life structures with embedded investment guarantees.
- Whole Life:Participating products with guaranteed cash values and non-guaranteed dividends anchor insurer balance sheets through long-duration liabilities. Reserve adequacy requirements under Singapore's risk-based capital framework demand conservative asset-liability matching.
- Supplementary:Riders and add-on coverage layers atop base policies represent the fastest-expanding margin pool, with critical illness and waiver of premium attachments driving attachment rate improvements.
- Term Life:Pure protection products compete on price through direct digital channels with minimal underwriting friction.
- Comprehensive:All-in-one packaged coverage consolidates multiple risk categories into single policies with simplified claims workflows.
Balance sheet scale concentrates in Whole Life; margin expansion favors Supplementary.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SME buyers concentrate commercial coverage demand across Southeast Asian insurance markets, with regulatory capital frameworks and digital distribution infrastructure shaping competitive positioning in each jurisdiction.
Malaysia
Small and medium enterprises drive commercial property and liability expansion as Bank Negara Malaysia tightens risk-based capital requirements for insurers. The central bank's Islamic regulatory framework channels takaful participation toward cooperative structures. Kuala Lumpur's financial district anchors bancassurance distribution through partnerships with Maybank and CIMB.
Thailand
Health insurance demand accelerates through employer-sponsored schemes as the Social Security Office expands mandatory coverage thresholds. The Office of Insurance Commission enforces solvency ratios that favor larger domestic carriers. Bangkok's metropolitan corridor concentrates digital insurer headquarters and embedded insurance API development.
Indonesia
Microinsurance penetration expands through mobile distribution as Otoritas Jasa Keuangan simplifies capital requirements for rural-focused products. The financial services authority coordinates with the Ministry of Health on universal coverage supplementation. Jakarta's fintech corridor hosts insurtech platforms integrating coverage into ride-hailing and e-commerce workflows.
Vietnam
Life insurance premium growth concentrates in participating products as the Ministry of Finance raises foreign ownership limits for domestic joint ventures. State-owned VietinBank and BIDV dominate bancassurance distribution through exclusive partnerships. Ho Chi Minh City's District 1 clusters regional headquarters for multinational carriers targeting emerging middle-class segments.
Philippines
Catastrophe bond issuance accelerates as the Insurance Commission mandates climate risk disclosure for property underwriters. The Bangko Sentral ng Pilipinas coordinates microinsurance regulation with rural banking expansion. Metro Manila's Makati Central Business District anchors reinsurance broker operations serving typhoon-exposed archipelago risks.
Singapore Life and Non-Life Insurance Market Competitive Landscape
Player mix skews toward established bancassurance partnerships and cooperative structures with deep payroll deduction infrastructure. Market concentration sits with incumbent life insurers holding Central Provident Fund distribution licenses, while digital challengers capture velocity among digitally native cohorts. Strategic archetypes include cooperative insurers with mass-market penetration, bancassurance-anchored conglomerates, and direct digital specialists. Competitive moves center on embedded insurance API partnerships and open-architecture distribution restructuring.
Within the cooperative tier, NTUC Income Insurance exemplifies member-owned structures sustaining competitive positioning through group affinity channels. Among bancassurance-anchored carriers, Great Eastern Life Assurance occupies a position reflecting deep bank partnership dependencies, while AIA Singapore represents the tied-agent network archetype with one of the largest captive sales forces in the city-state. These three carriers collectively illustrate how distribution infrastructure ownership shapes sustainable competitive advantage under Monetary Authority of Singapore capital requirements.
| Leading Market Players |
|---|
| Manulife (Singapore) Pte. Ltd. |
| NTUC Income Insurance |
| Great Eastern Life Assurance Co. Ltd. |
| HSBC Life Singapore |
| Aviva Singapore |
| Prudential Plc |
| Singapore Life Holdings Pte. (Singlife) |
| Chubb Singapore |
| AIA Singapore Pte. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Embedded insurance APIs substituting traditional broker commissions are redistributing pricing power toward fintech platforms while compressing acquisition cost structures across Singapore's distribution landscape. This substitution simultaneously concentrates supply geography in cloud-native infrastructure providers and erodes the historical premium attached to physical branch networks.
Pricing Analysis
Cost-plus reinsurance treaties with Singapore-dollar swap indexation dominate commercial property and casualty lines, passing through catastrophe bond yield movements to corporate buyers. Price differentiation rests on risk engineering depth and dynamic pricing algorithm sophistication rather than brand heritage. Pricing pressure stems from Monetary Authority capital adequacy requirements forcing reserve strengthening in participating whole-life products. SMEs exhibit highest price sensitivity through digital comparison platforms, while multinational corporates prioritize coverage architecture standardization over premium minimization.
Supply Chain Analysis
Strategic stockpiling of actuarial talent and catastrophe modeling licenses supersedes just-in-time recruitment as insurers build internal model sophistication for Monetary Authority compliance. Supply concentrates in London, Bermuda, and Singapore for reinsurance capacity and alternative capital structures. Raw material dependencies include mortality tables, satellite climate data feeds, and blockchain oracle networks. Single-source vulnerability sits with concentrated reinsurer panels for peak catastrophe layers. Distribution runs through bancassurance partnerships, embedded APIs, and global broker networks serving commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of actuarial data scientists capable of integrating predictive modeling with cloud infrastructure engineering is constraining mid-tier carrier competitiveness and elevating compensation costs beyond sustainable thresholds.
For Market Incumbents: Shield participating fund profitability by accelerating asset-liability matching optimization and reallocating capital toward commercial lines with simplified risk-based capital treatment. Defensive consolidation of legacy policy administration platforms through cloud-native core system replacement reduces technical debt exposure. Channel control through exclusive bancassurance renegotiations preserves mass-market access against embedded insurance disintermediation. For New Entrants and Emerging Players: Cyber liability white space among Singapore's financial services and technology sectors offers the most penetrable entry vector given underpenetration relative to peer Asian financial centers. Parametric climate products leveraging satellite imagery and blockchain smart contracts represent a distinctive go-to-market angle with minimal incumbent replication. Direct digital distribution through neobank API integration collapses customer acquisition friction versus traditional tied-agent recruitment cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct digital insurers possessing embedded distribution partnerships but constrained by capital adequacy requirements for scale expansion. Long-term viability across the analysis window favors carriers with diversified channel ownership and proprietary risk intelligence capabilities. The signal to watch is Monetary Authority open-architecture enforcement intensity, which would reconfigure bancassurance economics and create distressed repositioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Core System Cloud Migration | Replaces decades-old policy administration architectures with API-native platforms enabling real-time underwriting. |
| Embedded Insurance API Partnership | Integrates life and health products into DBS, OCBC, and UOB digital banking interfaces reducing distribution friction. |
| Cyber Liability Product Launch | Addresses ransomware and business interruption exposures among Singapore's technology and financial services clusters. |
| Parametric Climate Product Development | Combines satellite imagery with blockchain smart contracts for index-triggered flood and extreme heat payouts. |
| Actuarial Data Science Capability Buildout | Recruits predictive modeling talent capable of meeting Monetary Authority internal model sophistication requirements. |
Research Methodology
Cross-validation between primary interviews with chief risk officers, actuarial directors, distribution channel heads, and regulatory affairs specialists and secondary validation through Monetary Authority of Singapore regulatory filings, Central Provident Fund Board annual reports, and reinsurance market placement data anchors the qualitative findings. Bottom-up premium volume estimates by product line and distribution channel triangulate against top-down macroeconomic projections for insurance penetration rates.
Sensitivity analysis around interest rate trajectories, catastrophe loss assumptions, and capital adequacy rule changes informs the analytical framework across the modeling period. Segmentation dimensions include product type, customer archetype, distribution infrastructure, and coverage structure complexity. CAGRs derive from regression analysis of historical premium growth patterns adjusted for regulatory intervention effects and technology adoption curves. Forecast inputs incorporate MediShield Life framework evolution and open-architecture mandate implementation timelines.
Material uncertainties — Monetary Authority capital rule revisions, reinsurance capacity dislocations, and embedded insurance regulatory clarity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interest rate normalization and catastrophe frequency stability. Revision becomes warranted when risk-based capital treatment for SME-focused products crosses threshold changes affecting competitive economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market