
 Milk Chiller Market | 2026-2036
Milk Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Chiller Market Insights
Multi-source procurement toward integrated system suppliers is consolidating as dairy operators seek single-point accountability for cooling performance. DeLaval anchors its position through captive control over milking-to-chilling workflow integration. GEA Group leverages its refrigeration engineering heritage to compete on energy efficiency benchmarks in large-capacity installations. Paul Mueller Company specializes in stainless steel fabrication, sustaining premium positioning across North American dairy cooperatives.
A milk chiller is a refrigerated vessel engineered to reduce raw milk temperature from approximately 35°C to 4°C within two hours of collection, preserving bacteriological quality prior to transport or processing. Units employ direct expansion or water-cooled refrigeration cycles with insulated stainless steel inner walls and automated agitation systems to prevent cream separation. Vertical configurations dominate commercial dairy farm deployments due to footprint efficiency and ease of cleaning, while portable units represent the fastest-expanding category as mobile collection networks proliferate in emerging dairy regions. Water-cooled technology commands margin concentration in large processing plants where heat recovery integration offsets operational expenditure.
The EPA SNAP program and EU F-Gas Regulation are reshaping refrigerant specifications, compelling manufacturers to redesign compressor systems for R513A, R450A, and CO2 subcritical cycles. FDA Grade A Pasteurized Milk Ordinance standards govern sanitary construction, mandating 3-A Sanitary Standards-compliant surfaces and CIP compatibility across equipment sold into US interstate commerce. Stakeholders must monitor refrigerant phase-down schedules and energy labeling requirements as these dual pressures determine which cooling architectures remain viable across major dairy-producing territories.
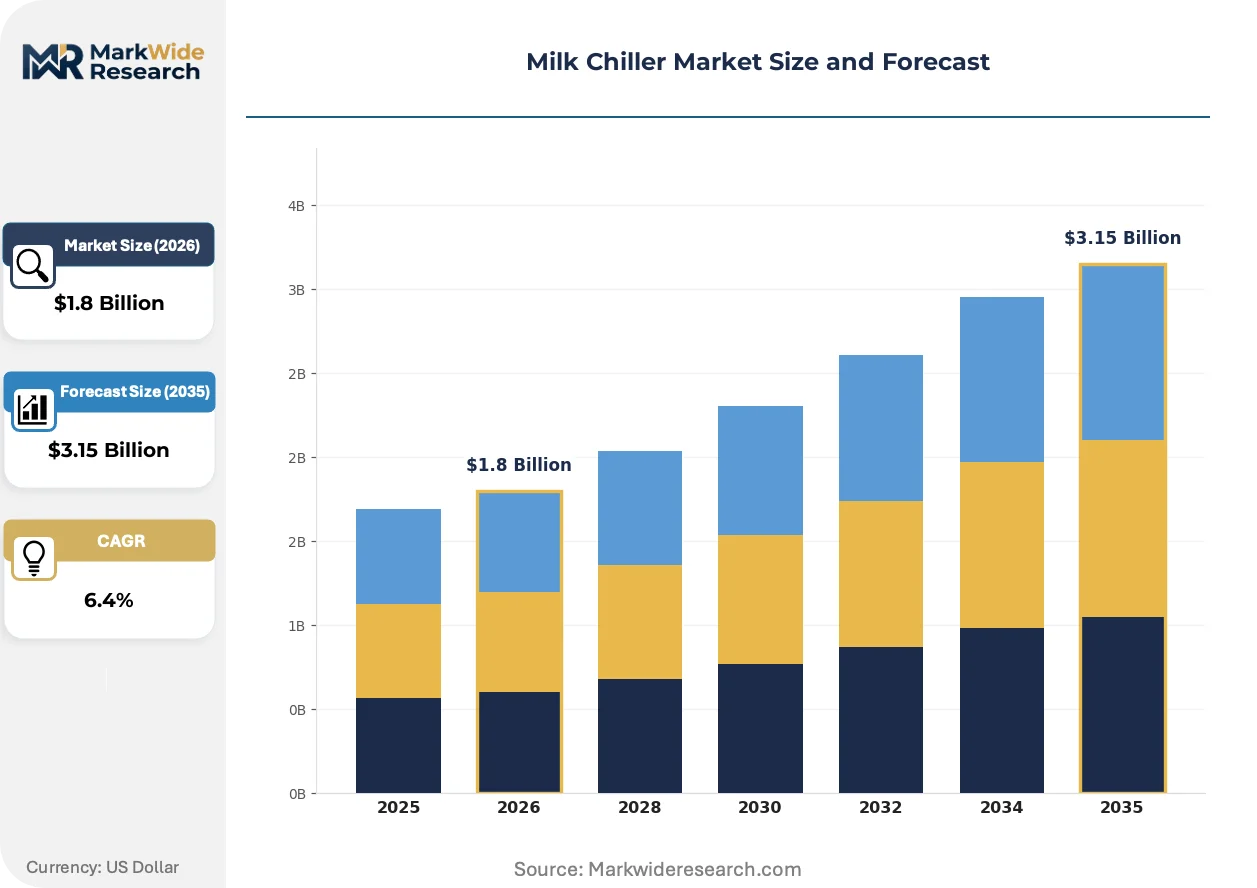
Market Dynamics
Refrigerant phase-down mandates under the EU F-Gas Regulation and EPA SNAP program are forcing compressor system redesigns across installed bases, compressing equipment replacement cycles while elevating energy efficiency specifications as primary procurement criteria.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for high-GWP refrigerants accelerates retrofit demand across European dairy cooperatives, creating replacement pull for lower-carbon cooling architectures.
- Village-level cooperative networks:India's National Dairy Development Board-backed chilling infrastructure expansion drives bulk cooler installations across rural procurement catchments.
- Heat recovery integration:Water-cooled systems with thermal capture capabilities are displacing air-cooled units in large processing plants seeking operational expenditure reduction.
Market Restraints
- Copper and stainless steel input volatility:Fabrication cost exposure to commodity price swings compresses margin predictability for tank and coil manufacturers.
- Compressor supplier concentration:Dependence on specialized refrigeration component sources in Germany and Japan creates supply vulnerability during equipment redesign cycles.
- Legacy R404A dependency:Extended amortization periods for existing chillers delay regulatory compliance investments across smaller farm operations.
Strategic Opportunities
- Mobile collection networks:Portable chilling units address last-mile cold-chain gaps across East African pastoral dairy systems lacking fixed infrastructure.
- PLI scheme alignment:India's production-linked incentive framework for food processing equipment supports domestic manufacturing scale-up for export-ready chillers.
- CO2 subcritical convergence:Transcritical refrigeration cycles paired with solar thermal integration open off-grid deployment models for remote dairy clusters.
Industry Challenges
- Refrigeration technician scarcity:Specialized servicing capacity for next-generation low-GWP systems lags equipment deployment rates across emerging dairy regions.
- 3-A Sanitary Standards certification timelines:FDA Grade A Pasteurized Milk Ordinance compliance documentation extends product launch schedules for new market entrants.
- Legacy control system incompatibility:Integration friction between IoT-enabled monitoring platforms and existing farm management software delays smart chilling adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Chiller Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Portable, Integrated End User: Dairy Farms, Milk Processing Plants, Retail Outlets, Restaurants Technology: Direct Expansion, Water-Cooled, Air-Cooled, Refrigeration Cycle Capacity: 100L, 500L, 1000L, 5000L |
| Companies Covered | GEA Group, DeLaval, Paul Mueller Company, SERAP Group, Danfoss, Wedholms, Boumatic, Fabdec, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Chiller Market Trends and Innovations
Equipment intelligence and refrigerant chemistry are advancing in parallel, reshaping how cooling performance is monitored, optimized, and regulated across dairy supply chains.
Variable-speed compressor technology with predictive maintenance algorithms is converging with cloud-based milk quality tracking platforms. Large commercial dairies in the Netherlands and Denmark are deploying these integrated systems to synchronize chilling cycles with milking parlor throughput. The convergence is compressing equipment downtime windows while elevating energy benchmarking as a competitive differentiator in cooperative procurement tenders.
The EPA SNAP program's final rule on hydrofluorocarbon restrictions compels manufacturers to validate R513A and R450A performance in subcritical configurations. Equipment redesign costs are concentrating among mid-capacity chiller producers serving interstate commerce. California's Air Resources Board supplementary mandates are accelerating compliance investments ahead of federal deadlines, creating a regulatory lead market for low-GWP technology validation.
Service contract unbundling is fragmenting traditional supplier relationships. Dairy cooperatives in Wisconsin and Bavaria are separating equipment purchase from maintenance provision, awarding multi-year service agreements to independent refrigeration specialists. This pattern is most pronounced among operations with in-house technical staff seeking performance-guarantee structures rather than bundled warranty coverage.
Milk Chiller Market Segmentation
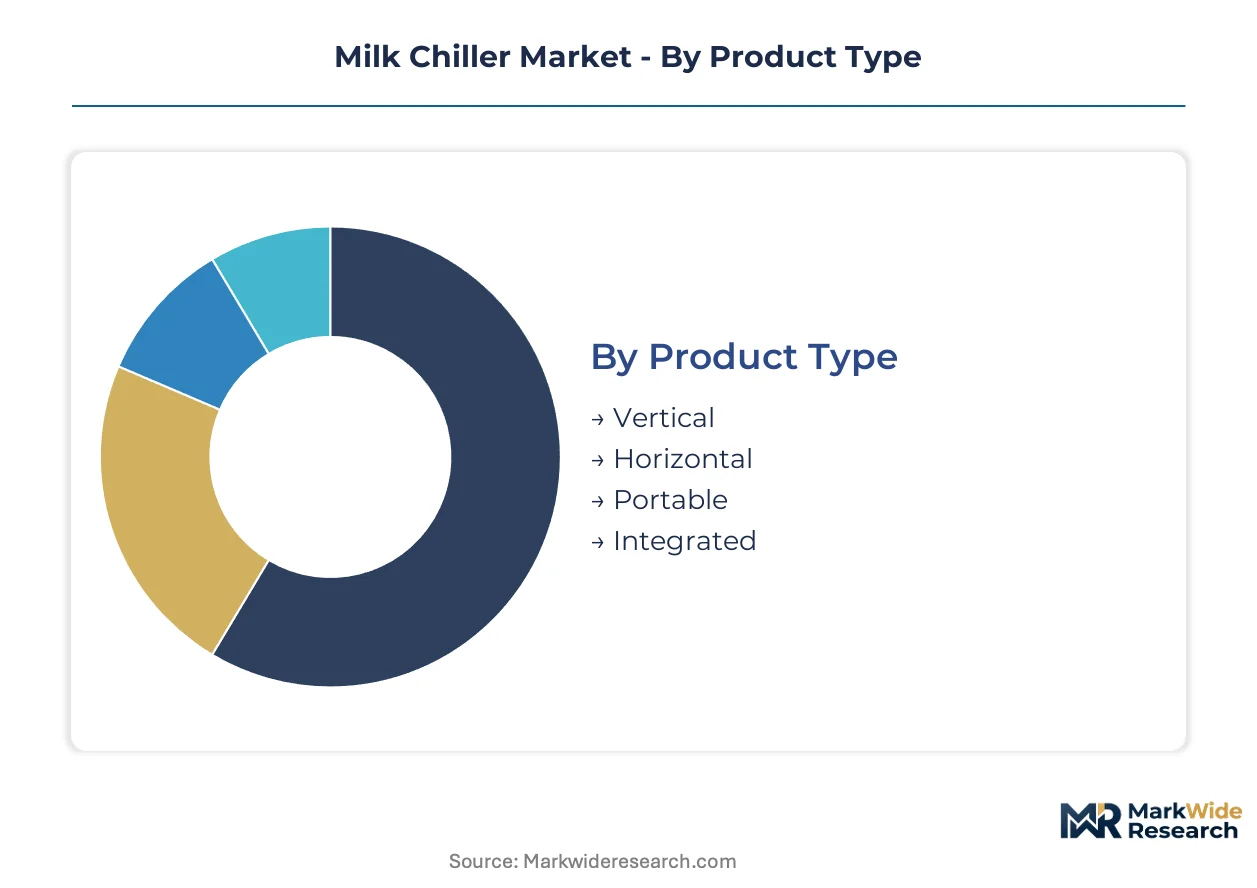
Procurement patterns in milk chilling equipment diverge sharply across operational scale and regulatory exposure. Buyers prioritize footprint efficiency, energy recovery potential, or mobility depending on whether they serve cooperative networks, processing plants, or dispersed pastoral systems.
Product Type:
Farm operators select configuration based on cleaning protocol intensity and parlor layout constraints rather than cooling performance alone.
- Vertical:Upright cylindrical vessels with top-mounted agitation systems dominate commercial dairy farm deployments. Demand concentrates across the Netherlands and Denmark where robotic milking installations require compact footprint integration with automated parlors. The EU F-Gas Regulation retrofit cycle is accelerating replacement demand as older vertical units lack compatibility with R513A compressor architectures.
- Portable:Mobile chilling units mounted on trailer chassis address last-mile cold-chain gaps. Procurement is climbing fastest across East African pastoral dairy systems in Kenya and Ethiopia where fixed infrastructure remains absent and collection routes cover dispersed catchments.
- Horizontal:Low-profile rectangular tanks suit retrofit installations with height restrictions in legacy barn structures. These configurations see steady replacement demand across Wisconsin dairy cooperatives.
- Integrated:Combined milking-to-chilling workflow systems serve large-scale operations seeking single-point accountability. Installations are expanding across New Zealand's consolidated farm estates.
Vertical configurations lead on installed base scale; portable units lead on expansion momentum.
End User:
Sanitary certification requirements and volume throughput determine equipment specification divergence across buyer categories.
- Dairy Farms:Raw milk cooling at point of production represents the core demand anchor. Farm-scale procurement across India drives bulk cooler installations through National Dairy Development Board-backed cooperative networks, with village-level chilling points requiring 500L-1000L capacity units.
- Milk Processing Plants:Large-capacity installations with heat recovery integration serve industrial pasteurization feedstock preparation. Water-cooled systems predominate here as thermal capture offsets operational expenditure.
- Retail Outlets:Small-volume display cooling and storage units serve farm-shop direct sales channels.
- Restaurants:Specialty dairy ingredient preservation drives niche demand for compact under-counter units.
Dairy farms anchor volume absorption; processing plants command margin concentration.
Technology:
Refrigerant chemistry and heat rejection method define both capital outlay and regulatory compliance trajectory.
- Direct Expansion:Refrigerant-to-milk heat exchange through immersed coils delivers rapid temperature pull-down. This architecture dominates mid-capacity farm installations where simplicity outweighs energy recovery priorities.
- Water-Cooled:Shell-and-tube or plate heat exchangers using recirculated water loops enable heat recovery for plant hot water systems. Large processing facilities in California are accelerating adoption ahead of state Air Resources Board mandates.
- Air-Cooled:Finned coil condensers eliminate water infrastructure requirements but sacrifice efficiency in high-ambient conditions. These systems prevail in water-scarce regions and smaller farm operations.
- Refrigeration Cycle:Generic compressor-based cooling without specification of heat rejection method captures legacy equipment and hybrid configurations.
Water-cooled systems command premium positioning; direct expansion maintains broadest penetration.
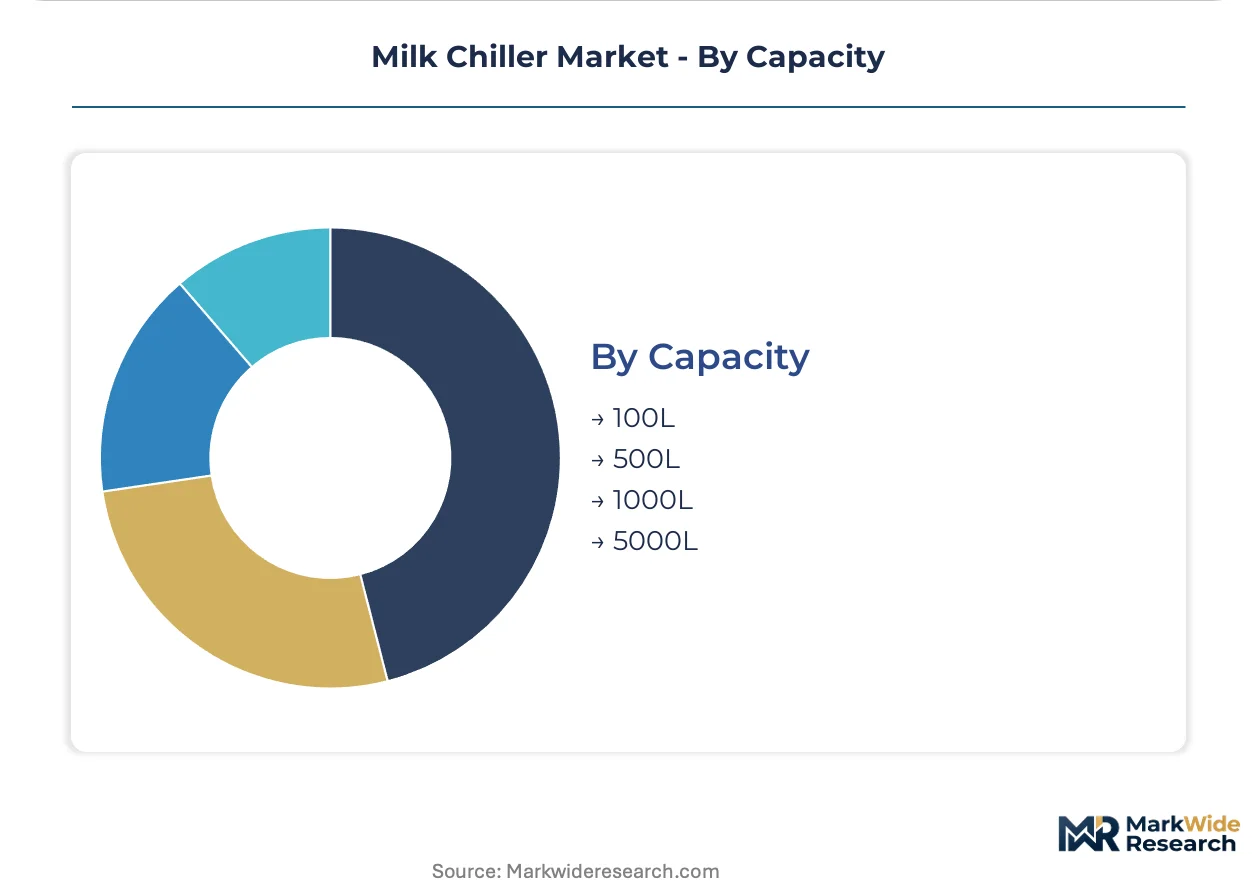
Capacity:
Scale economics and collection frequency determine optimal vessel sizing across operational models.
- 100L:Compact units serve smallholder cooperatives with twice-daily collection cycles. India's village-level dairy networks deploy these across Gujarat and Maharashtra procurement catchments.
- 500L:Mid-scale vessels balance capital efficiency with batch cooling requirements. This capacity tier sees strongest demand across expanding East African cooperative infrastructure.
- 1000L:Standard commercial farm units align with daily production volumes from 50-100 cow operations. Replacement cycles here are compressing under EPA SNAP program compliance pressure.
- 5000L:Large communal chilling centers serve multiple smallholders in clustered procurement zones. Installations are expanding across India's Amul cooperative federation network.
1000L units dominate transaction volume; 5000L systems are gaining share fastest in cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' dairy engineering corridor concentrates precision cooling innovation for robotic milking integration. European refrigerant mandates and Asian cooperative modernization programs are redrawing procurement geography across the sector.
United States
Wisconsin dairy cooperatives drive vertical tank replacement cycles as farms retrofit for EPA SNAP compliance. The FDA Grade A Pasteurized Milk Ordinance governs interstate equipment standards, extending 3-A Sanitary certification timelines. California's Central Valley processing plants accelerate water-cooled system adoption ahead of state Air Resources Board deadlines.
India
Gujarat and Maharashtra village-level networks expand bulk cooler installations through National Dairy Development Board programs. The PLI scheme for food processing equipment incentivizes domestic manufacturing scale-up. Amul cooperative federation clusters deploy 5000L communal chilling centers across Anand district procurement zones.
Germany
Bavarian dairy cooperatives face compressed equipment replacement cycles under EU F-Gas Regulation phasedown schedules. The REACH framework governs material compliance for stainless steel fabrication inputs. Lower Saxony's large farm estates integrate heat recovery systems with biogas operations for operational expenditure reduction.
Netherlands
Friesland's robotic milking density creates demand for compact vertical chillers with automated parlor synchronization. The EU Green Deal accelerates low-GWP refrigerant validation for subcritical compressor architectures. Wageningen University's dairy technology cluster supports predictive maintenance algorithm development for cloud-connected cooling systems.
Kenya
East African pastoral dairy systems deploy portable chilling units across dispersed Rift Valley collection routes. National agricultural development programs subsidize mobile cold-chain infrastructure for smallholder cooperatives. Nairobi's equipment distributors scale trailer-mounted unit leasing models for last-mile procurement networks.
Milk Chiller Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-thermal integration and off-grid deployment models. The supplier base consolidates around integrated system accountability as dairy operators reject fragmented procurement relationships. Three archetypes dominate: captive workflow integrators, refrigeration engineering specialists, and stainless steel fabrication premium-positioned players. Competitive moves concentrate on compressor system redesign partnerships and multi-year service contract unbundling.
Within the captive integration tier, DeLaval anchors workflow control from milking to chilling. GEA Group exemplifies refrigeration engineering heritage applied to energy efficiency benchmarking. Paul Mueller Company occupies premium positioning through stainless steel fabrication specialization for North American cooperatives.
| Leading Market Players |
|---|
| GEA Group |
| DeLaval |
| Paul Mueller Company |
| SERAP Group |
| Danfoss |
| Wedholms |
| Boumatic |
| Fabdec |
| Alfa Laval |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between 3-A Sanitary Standards-compliant premium vessels and basic-grade economy units manifests in both pricing architecture and supply chain sourcing patterns. Premium-tier producers captive-source stainless steel fabrication from North American and European mills to satisfy FDA interstate commerce requirements, while economy-tier assemblers draw from commodity coil suppliers in India and China to serve price-sensitive cooperative networks.
Pricing Analysis
Input-cost pass-through from copper and stainless steel commodity volatility compresses margin predictability for tank and coil manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from EU F-Gas Regulation compliance investments elevating equipment redesign costs. Dairy cooperatives in Wisconsin and Bavaria exhibit highest price sensitivity, separating equipment purchase from maintenance provision to extract performance guarantees.
Supply Chain Analysis
Direct-to-farm channels handle hyperscale cooperative demand across India's National Dairy Development Board networks, while distributor-led models serve fragmented East African pastoral systems. Manufacturing concentrates in Germany, Denmark, and the United States for precision compressor systems and stainless steel fabrication. Raw material dependencies center on copper refrigerant tubing, 304-grade stainless steel sheet, and specialized compressor castings. Single-source vulnerability in Japanese and German compressor component supply creates disruption exposure during regulatory redesign cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Europe run substantially above India's PLI-scheme subsidized manufacturing economics, creating divergent investment returns across regulatory jurisdictions.
For Market Incumbents: Anticipate refrigerant phase-down acceleration by deepening backward integration into compressor system design partnerships with German and Japanese component specialists. Consolidate service contract unbundling trends by acquiring independent refrigeration specialists in Wisconsin and Bavaria to capture multi-year performance-guarantee revenue streams.
For New Entrants and Emerging Players: The 500L-1000L capacity gap between premium integrated systems and basic village-level units offers white-space entry targeting East African cooperative networks. Portable chilling deployment models for Kenya's Rift Valley pastoral systems represent the most penetrable segment. Pursue solar-thermal CO2 subcritical integration as a differentiated go-to-market angle for off-grid dairy clusters.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-capacity chiller producers face disproportionate EPA SNAP program redesign costs relative to integrated workflow specialists. Long-term viability favors suppliers with captive control over milking-to-chilling workflow integration. Target acquisition archetypes include stainless steel fabricators with 3-A Sanitary Standards certification infrastructure. Monitor California Air Resources Board mandate acceleration as an inflection signal for low-GWP technology validation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Redesign Partnership | Validates R513A and R450A performance ahead of EPA SNAP final enforcement deadlines. |
| Backward Integration into Compressor Components | Reduces single-source vulnerability from German and Japanese specialized suppliers. |
| Heat Recovery System Integration | Captures operational expenditure reduction demand from California processing plants. |
| Portable Unit Leasing Model Deployment | Addresses last-mile cold-chain gaps across Kenya's dispersed Rift Valley collection routes. |
| 3-A Sanitary Certification Investment | Unlocks FDA Grade A Pasteurized Milk Ordinance compliance for interstate US commerce. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with dairy cooperative procurement managers, refrigeration engineering directors, stainless steel fabrication plant managers, and aftermarket service heads informed demand-side and supply-side perspectives. Secondary sources include SEC 10-K filings from listed equipment manufacturers, EU F-Gas Regulation implementation reports, National Dairy Development Board program documentation, and US dairy cooperative procurement tender databases. Bottom-up unit deployment estimates triangulated against top-down market value reconstructions.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product configuration, end-user operational scale, refrigerant technology architecture, and vessel capacity tier. CAGRs derived from regression analysis against dairy production growth, regulatory compliance investment cycles, and cooperative infrastructure modernization rates. Forecast inputs incorporate EU F-Gas phase-down schedules and India's PLI scheme disbursement trajectories.
The model assumes a particular technology adoption path; alternative pathways for CO2 transcritical refrigeration would alter the outlook. Forecasts reflect assumptions regarding refrigerant transition timelines, commodity price stabilization, and technician training capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Concentrated Whey Market