
 China Cloud Computing Market | 2026-2036
China Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
China Cloud Computing Market Insights
Premium sovereign cloud deployments is decoupling from commodity public compute tiers in China. Alibaba Cloud leverages its data center density across eastern provinces to dominate enterprise hybrid transitions. Huawei Cloud anchors government and state-owned enterprise contracts through deep hardware-software integration.
Cloud computing in China denotes the on-demand delivery of computing resources—spanning virtualized servers, container orchestration, and distributed storage—over IP-based networks with latency thresholds typically below 50 milliseconds for enterprise workloads. Its primary purpose centers on replacing capital-intensive on-premise IT infrastructure with elastic, metered services that scale with transaction volumes. Public cloud IaaS holds the largest revenue pool today, while PaaS and FaaS segments capture disproportionate margin expansion as developers migrate toward serverless architectures. Private cloud deployments serving financial services and healthcare retain premium pricing power due to compliance-driven customization requirements.
MIIT, SAMR, and the Cybersecurity Administration of China enforce data localization, cross-border transfer restrictions, and cloud service licensing that shape vendor market access and foreign participation limits. GB standards for cloud infrastructure security and reliability create mandatory certification gates that filter domestic and international providers. Stakeholders must track evolving classification rules for critical information infrastructure as these definitions determine compliance scope and procurement eligibility for cloud contracts.
Market Dynamics
MIIT's tightening cloud service licensing regime and GB standards certification requirements are forcing domestic and foreign providers to re-architect data residency and security compliance frameworks, reshaping competitive positioning across sovereign and hybrid deployment tiers.
Growth Catalysts
- Smart manufacturing mandates:Automotive and electronics producers in the Yangtze River Delta are migrating production workloads to edge-cloud hybrid stacks to meet real-time quality control latency thresholds.
- MIIT cloud computing standards:Mandatory reliability and security certifications under GB/T frameworks are filtering out subscale providers, consolidating procurement toward certified infrastructure vendors.
- State-owned enterprise digitalization:Central SASAC directives require SOEs to replace on-premise legacy systems with private cloud deployments by specified compliance deadlines.
Market Restraints
- Data localization hardware costs:Cybersecurity Law mandates for in-country data storage are inflating capex requirements for redundant storage clusters across eastern and western provinces.
- Cross-border transfer friction:CAC security assessment procedures for data export are extending contract negotiation timelines and complicating multinational enterprise hybrid architectures.
- Domestic chip supply concentration:Reliance on indigenous server processor yields from SMIC and Hua Hong Semiconductor creates capacity bottlenecks during fab ramp cycles.
Strategic Opportunities
- Western province expansion:Guizhou and Inner Mongolia data center clusters offer subsidized land and renewable energy tariffs for cold storage and batch compute workloads.
- Healthcare cloud migration:NMPA digital health record interoperability mandates are opening compliant private cloud contracts for tertiary hospital networks.
- Carbon-aware compute:Dual carbon goals are creating preferential grid access for facilities demonstrating verified renewable energy consumption above threshold levels.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Kubernetes and container security certifications lag behind deployment scale, forcing providers to absorb training costs or outsource platform engineering.
- Legacy mainframe integration complexity:Financial institutions maintaining IBM z/OS cores face extended middleware bridge development cycles for hybrid cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cloud Computing Market |
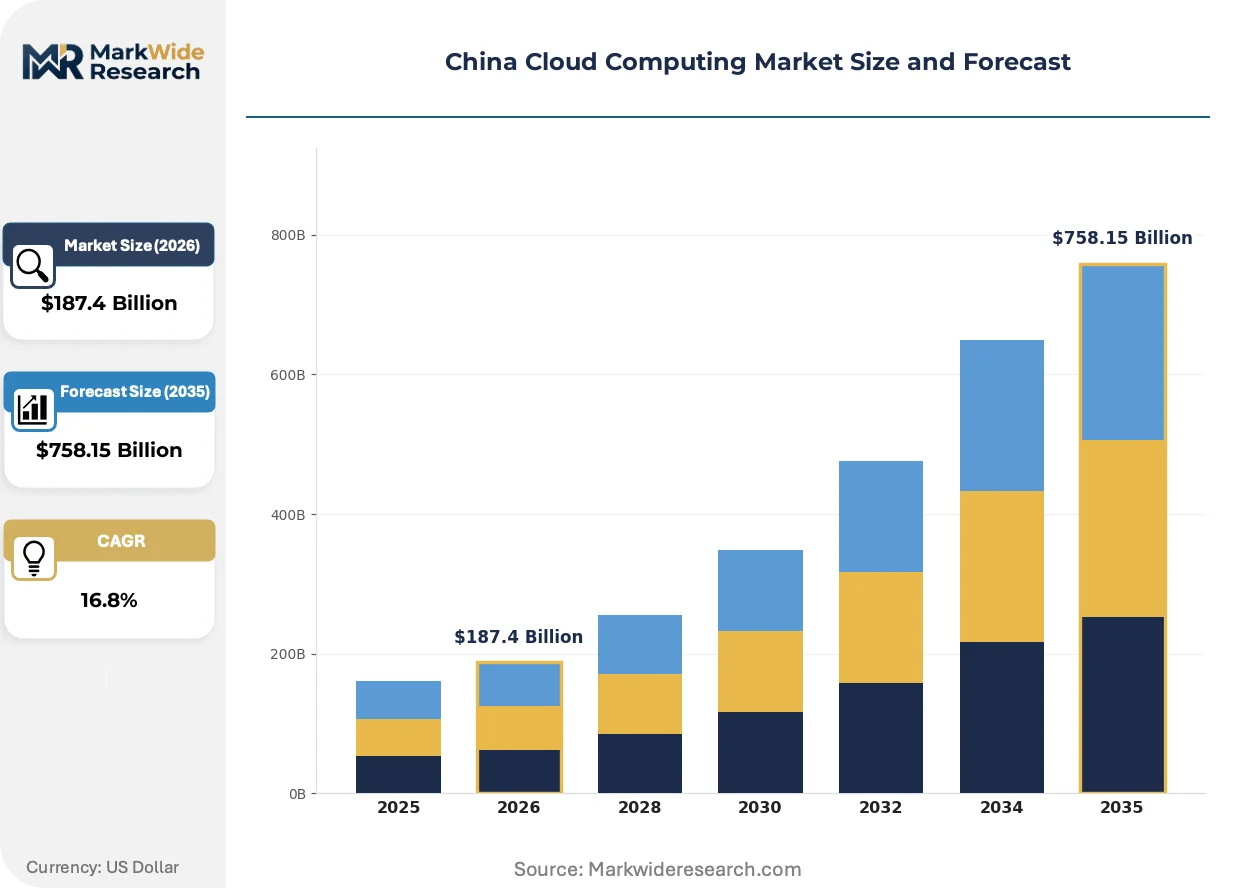
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, FaaS End User: SMEs, Large Enterprises, Government Entities, Educational Institutions Application: Data Storage, Disaster Recovery, Software Development, Analytics |
| Companies Covered | China Telecom Cloud, Baidu AI Cloud, Alibaba Cloud, China Unicom Cloud, ByteDance Volcengine, Huawei Cloud, China Mobile Cloud, Kingsoft Cloud, Tencent Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cloud Computing Market Trends and Innovations
Containerization and serverless architectures are compressing traditional IaaS margins while regulatory pressure on data sovereignty is spawning specialized compliance-as-a-service layers. These forces are fragmenting the unified public cloud model into vertically differentiated stacks.
Cloud-native observability platforms are unifying distributed tracing, metrics aggregation, and log analytics into single-pane infrastructure management consoles. Large manufacturing enterprises with multi-factory footprints are adopting these stacks fastest, compressing mean-time-to-resolution for production system failures from hours to minutes and reducing dependency on specialized site reliability engineering headcount.
SAMR's revised guidelines on algorithmic recommendation transparency are extending audit and explainability requirements to cloud-hosted AI inference services. Providers must now document model training data provenance and decision logic for customer-facing applications, with financial services and e-commerce platforms facing the steepest compliance re-engineering costs to maintain deployment licenses.
Enterprise buyers are consolidating vendor relationships around integrated infrastructure-security bundles rather than best-of-breed point solutions. Systems integrators and channel partners in Beijing and Shenzhen are restructuring compensation models to prioritize multi-year platform commitments over transactional license sales, with state-owned energy and transport groups driving the largest contract values.
China Cloud Computing Market Segmentation
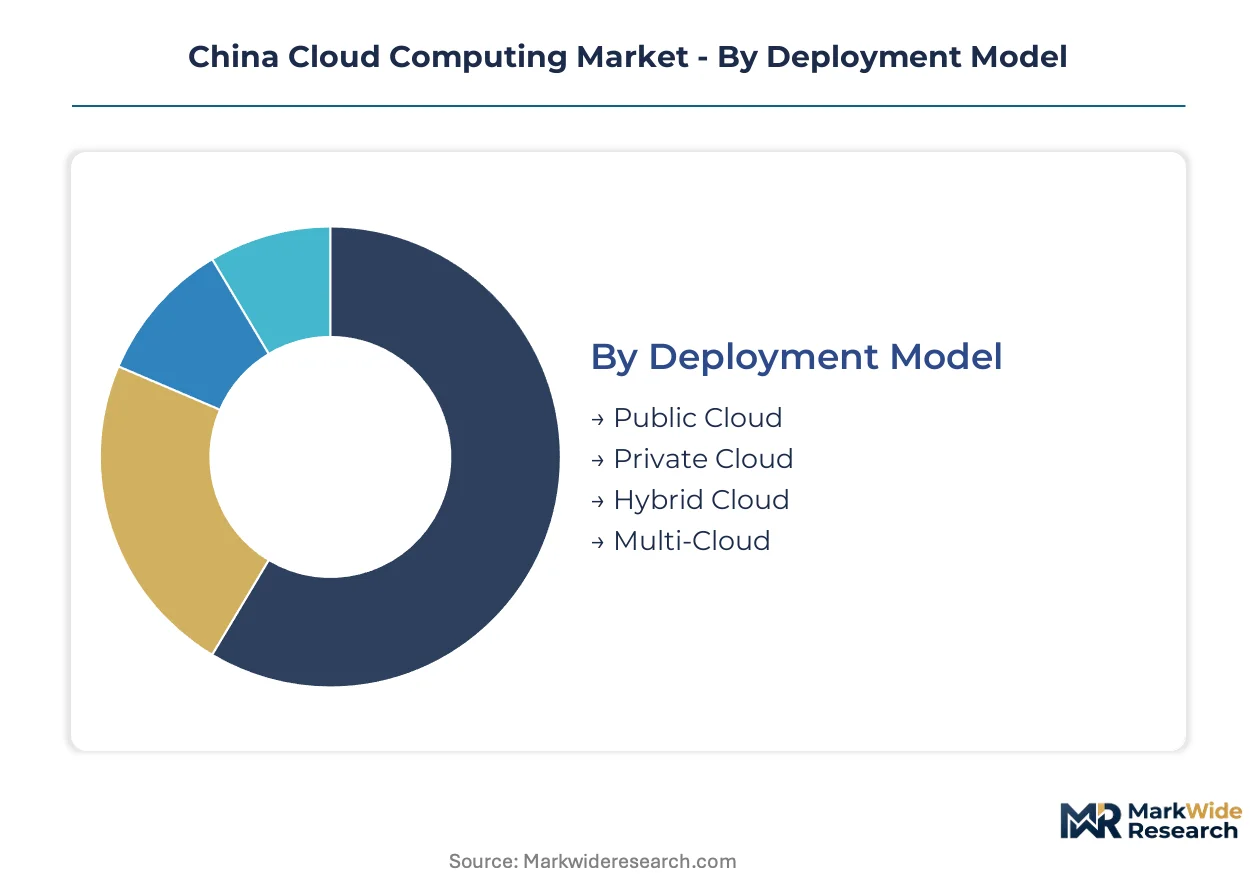
Segmentation in China's cloud market reveals how MIIT licensing tiers and data localization mandates fragment procurement patterns across deployment architectures. Each dimension carries distinct compliance burdens that reshape vendor eligibility and contract structures.
Deployment Model:
Public Cloud demands MIIT cross-border service licenses for foreign providers, while Private Cloud requires GB/T 31168 security certification for critical information infrastructure access. Hybrid and Multi-Cloud architectures face compound approval requirements spanning both regimes.
- Public Cloud:Shared infrastructure pools deliver virtualized compute, storage, and networking through metered consumption models. Demand concentrates among e-commerce platforms and fintech startups in Shanghai and Hangzhou clusters seeking elastic scaling without capital commitment. MIIT's tightened licensing regime since 2021 has reduced eligible foreign providers to a handful of joint-venture structures.
- Private Cloud:Single-tenant dedicated infrastructure deployed on-premise or in exclusive colocation facilities. State-owned banks and NMPA-regulated pharmaceutical manufacturers anchor procurement, driven by Cybersecurity Law mandates for core financial and health data segregation from public networks.
- Hybrid Cloud:Orchestrated workload portability between private and public pools with unified management planes. Manufacturing enterprises in the Yangtze River Delta adopt this model to keep proprietary design data on-premise while bursting simulation workloads to public tiers.
- Multi-Cloud:Distributed architectures spanning two or more independent provider platforms to mitigate concentration risk. Central SOEs with SASAC-mandated business continuity requirements are the primary adopters, though Kubernetes orchestration expertise scarcity constrains deployment velocity.
Public Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest as procurement teams diversify beyond single-vendor dependency.
Service Type:
Margin structures diverge sharply across this dimension, with infrastructure services commoditizing while platform and function layers capture premium pricing through developer productivity gains.
- IaaS:Virtualized server instances, block storage, and software-defined networking delivered through self-service portals. Price compression is accelerating as Alibaba Cloud and Huawei Cloud expand capacity in Guizhou and Inner Mongolia renewable energy clusters.
- PaaS:Managed application runtime environments including container orchestration, database services, and middleware integration. Smart manufacturing adopters in automotive electronics favor PaaS for rapid IoT application deployment without underlying infrastructure management.
- SaaS:End-user application software delivered through browser or mobile interfaces with multi-tenant architectures. NMPA digital health record mandates are opening compliant SaaS contracts for hospital network administrators seeking to replace legacy client-server systems.
- FaaS:Event-driven compute execution where code runs in ephemeral containers triggered by API calls or file uploads. Developer teams in Shenzhen and Beijing software parks are migrating batch processing and microservice backends to this model for granular cost optimization.
IaaS commands the largest revenue base, though FaaS is gaining share fastest among cloud-native development teams prioritizing operational expenditure reduction.
End User:
Procurement sophistication and compliance tolerance vary dramatically across buyer types, with government contracts requiring the most extensive certification documentation.
- SMEs:Businesses with under 500 employees and limited in-house IT infrastructure. Public Cloud IaaS and SaaS adoption dominates this segment, driven by minimal upfront capital requirements and rapid deployment timelines for e-commerce and digital marketing workloads.
- Large Enterprises:Multinational manufacturers and domestic conglomerates with complex legacy system estates. Hybrid Private-Public architectures prevail here, with extended middleware bridge development cycles for IBM z/OS mainframe integration creating implementation bottlenecks.
- Government Entities:Central ministries, provincial administrations, and municipal bureaus subject to Cybersecurity Law critical information infrastructure classification. Huawei Cloud and domestic state-affiliated providers dominate this segment through deep hardware-software integration and security clearance protocols.
- Educational Institutions:Universities and research institutes under Ministry of Education oversight. Subsidized access to western province data center capacity supports high-performance computing and AI training workloads with lower carbon intensity metrics.
Large Enterprises anchor current procurement value, with Government Entities expanding most quickly under SASAC-directed digitalization mandates.
Application:
Latency sensitivity and data gravity requirements reshape architectural choices across use cases, with real-time workloads demanding edge-cloud proximity.
- Data Storage:Object, block, and file storage services with tiered durability and retrieval latency guarantees. Cold archival demand is shifting toward Inner Mongolia and Guizhou facilities offering subsidized renewable energy tariffs for infrequently accessed datasets.
- Disaster Recovery:Replicated infrastructure and automated failover orchestration for business continuity compliance. Financial institutions under central bank operational risk guidelines drive premium pricing for synchronous replication across geographically separated availability zones.
- Software Development:Integrated development environments, CI/CD pipelines, and testing sandboxes delivered as managed services. Agile teams in Beijing and Shenzhen technology corridors favor PaaS-based DevOps stacks for accelerated release cycles.
- Analytics:Data warehouse, machine learning platform, and visualization services for business intelligence and predictive modeling. Manufacturing quality control applications in automotive supply chains require sub-50 millisecond latency thresholds that constrain viable deployment architectures.
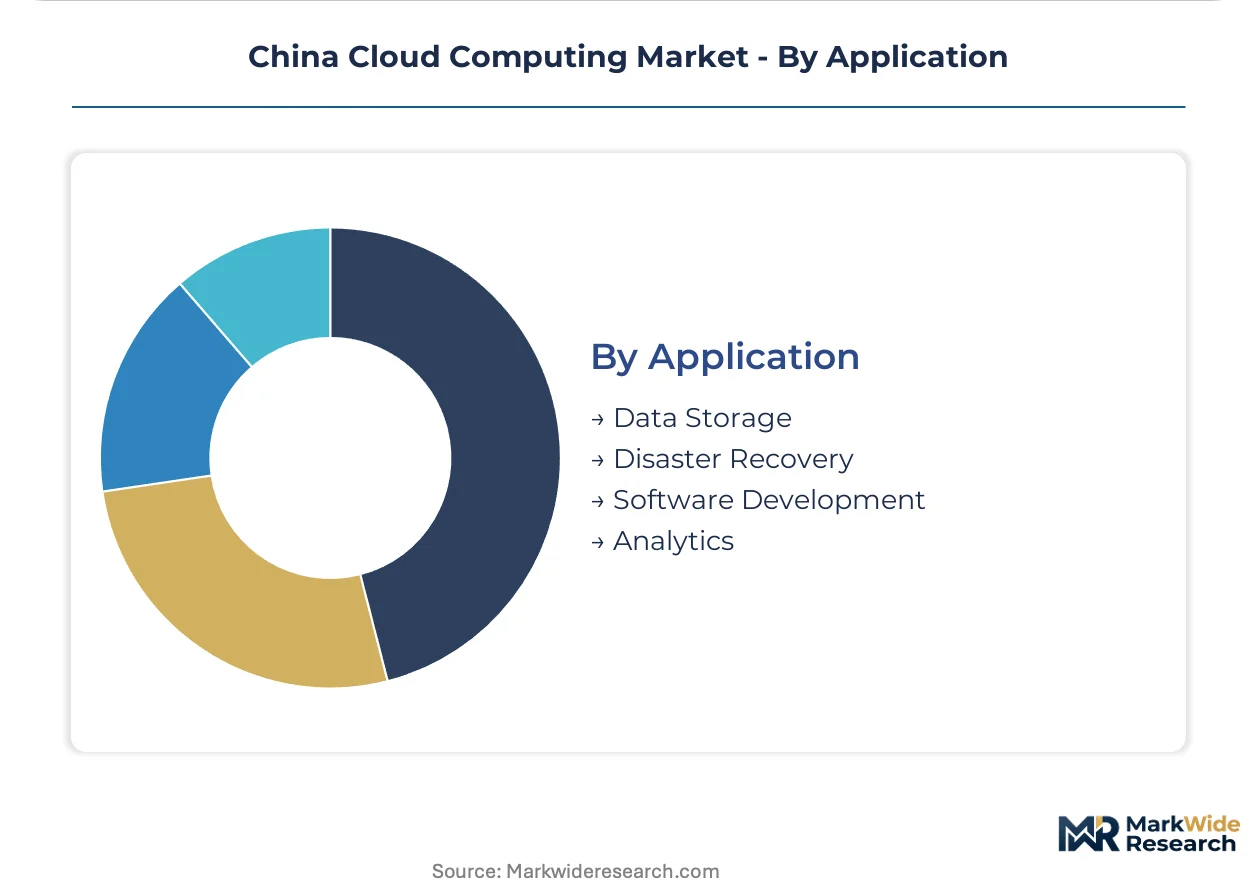
Data Storage leads by installed capacity, with Analytics expanding most quickly as SAMR algorithmic transparency requirements extend audit obligations to cloud-hosted inference services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud engineering talent concentrates in the Yangtze River Delta and Pearl River Delta corridors, anchoring infrastructure deployment velocity and platform innovation capacity across eastern provinces.
Yangtze River Delta
Smart manufacturing workloads from automotive and electronics producers drive demand for edge-cloud hybrid stacks. MIIT cloud computing standards mandate GB/T 31168 certification for critical infrastructure access. Shanghai and Hangzhou clusters host the densest data center capacity, with Alibaba Cloud leveraging this footprint for enterprise hybrid transitions.
Pearl River Delta
Fintech startups and cross-border e-commerce platforms seek elastic scaling without capital commitment. SAMR algorithmic transparency requirements extend audit obligations to cloud-hosted AI inference services. Shenzhen software parks are migrating microservice backends to FaaS models for granular cost optimization.
Beijing-Tianjin-Hebei
Central SOEs with SASAC-mandated business continuity requirements adopt multi-cloud architectures to mitigate concentration risk. Cybersecurity Law data localization mandates inflate capex for redundant storage clusters. Beijing technology corridors favor PaaS-based DevOps stacks for accelerated release cycles.
Western China
Cold storage and batch compute workloads shift toward subsidized renewable energy tariffs. Dual carbon goals create preferential grid access for facilities demonstrating verified clean energy consumption above threshold levels. Guizhou and Inner Mongolia data center clusters attract archival demand with lower carbon intensity metrics.
Sichuan-Chongqing
Educational institutions under Ministry of Education oversight access subsidized western province capacity for high-performance computing. NMPA digital health record interoperability mandates open compliant private cloud contracts for tertiary hospital networks. Chengdu anchors AI training workload migration from eastern hubs.
China Cloud Computing Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform specialists for enterprise workload placement. The vendor base consolidates around three tiers: state-affiliated carriers with spectrum and fiber assets, internet-origin hyperscalers with developer ecosystem density, and vertical specialists with compliance certification depth. Strategic moves center on western province capacity expansion and sovereign cloud certification acquisition.
Among carrier-affiliated operators, China Telecom Cloud and China Mobile Cloud anchor government and SOE procurement through deep network integration and security clearance protocols. Within the internet-origin tier, Alibaba Cloud exemplifies hyperscale density across eastern provinces, while Huawei Cloud occupies a position serving state-affiliated accounts through hardware-software integration. ByteDance Volcengine represents the emerging challenger archetype, leveraging video and AI workload optimization to capture developer mindshare in content-centric verticals.
| Leading Market Players |
|---|
| China Telecom Cloud |
| Baidu AI Cloud |
| Alibaba Cloud |
| China Unicom Cloud |
| ByteDance Volcengine |
| Huawei Cloud |
| China Mobile Cloud |
| Kingsoft Cloud |
| Tencent Cloud |
| Others |
Pricing and Supply Chain Analysis
MIIT cloud computing standards and GB/T certification mandates are compressing procurement timelines for enterprise buyers, forcing infrastructure providers to absorb compliance engineering costs and restructure service bundles around sovereign cloud tiers.
Pricing Analysis
Bundled infrastructure-security offerings dominate enterprise procurement, while unbundled commodity compute faces accelerating price compression. Three-tier pricing structure across premium sovereign, standard hybrid, and economy public tiers separates compliance-certified deployments from generic IaaS pools. Pricing pressure stems from Alibaba Cloud and Huawei Cloud capacity expansion in Guizhou renewable energy clusters. SMEs exhibit highest price sensitivity, while state-owned banks accept premium sovereign cloud rates for Cybersecurity Law compliance.
Supply Chain Analysis
Domestic-content mandates under China's Cybersecurity Law and MIIT localization requirements are reshaping server hardware sourcing toward indigenous SMIC and Hua Hong Semiconductor fabrication. Supply concentration centers on eastern province data center clusters, with critical dependencies on domestic server processor yields, lithium-ion backup power systems, and precision cooling equipment. Single-source vulnerability runs through indigenous chip supply during fab ramp cycles. Distribution feeds through systems integrators in Beijing and Shenzhen restructuring compensation around multi-year platform commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's cloud computing market operates as a regulatory compounder where MIIT licensing regimes and data localization mandates continuously expand compliant infrastructure demand.
For Market Incumbents: To counter margin erosion from commodity IaaS price compression, deepen hardware-software integration for government contract eligibility and accelerate western province capacity buildout in Guizhou renewable energy clusters to capture carbon-aware compute premiums. For New Entrants and Emerging Players: Begin with NMPA-compliant healthcare cloud contracts for tertiary hospital networks in Sichuan-Chongqing, where interoperability mandates outpace incumbent certification velocity. Target carbon-aware batch compute workloads in Inner Mongolia as the most penetrable geography, leveraging subsidized land and renewable energy tariffs against eastern hub cost structures. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists holding GB/T 31168 certification depth for critical information infrastructure access. Long-term viability favors providers with demonstrated sovereign cloud deployment scale across state-affiliated accounts. Watch MIIT classification rule expansions for critical information infrastructure as the primary inflection signal determining compliance scope and procurement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acquisition | GB/T 31168 certification unlocks critical infrastructure procurement from central SOEs under SASAC mandates. |
| Western Province Capacity Expansion | Guizhou and Inner Mongolia facilities capture carbon-aware compute demand with verified renewable energy consumption. |
| Healthcare Cloud Compliance Investment | NMPA digital health record interoperability mandates open private cloud contracts for tertiary hospital networks. |
| Hardware-Software Integration Deepening | Deep integration with domestic server processors satisfies Cybersecurity Law localization requirements for government accounts. |
| Multi-Cloud Orchestration Capability Buildout | Kubernetes and container security certifications address expertise scarcity constraining central SOE deployment velocity. |
Research Methodology
Direct dialogue with cloud platform engineering directors, enterprise IT procurement officers, MIIT regulatory affairs specialists, and systems integrator channel partners anchored qualitative findings, cross-referenced against hyperscaler capex disclosures, MIIT licensing registries, SASAC digitalization directives, and GB standards documentation. Bottom-up deployment scale estimates and top-down infrastructure investment flows underwent rigorous triangulation.
Model outputs span deployment architecture, service type, end-user scale, and application latency sensitivity across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating smart manufacturing adoption velocity, SOE digitalization mandate compliance deadlines, and renewable energy tariff subsidy phase-outs. Industry-specific inputs include MIIT certification timeline distributions and western province data center utilization trajectories.
Several conditions sit outside the modeled scope, including abrupt Cybersecurity Law enforcement escalations, semiconductor fabrication yield disruptions, and cross-border data transfer regime liberalization. Forecasts reflect documented assumptions around regulatory continuity and infrastructure investment execution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Cloud Management for the Openstack Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Commerce Cloud Market