
 Pharma E-Commerce Market | 2026-2036
Pharma E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma E-Commerce Market Analytics
Chronic care patient onboarding is restructuring how pharmacy platforms allocate fulfillment infrastructure. CVS Health leverages its retail footprint to sustain same-day delivery density in urban corridors. Amazon Pharmacy competes on automated refill algorithms and price transparency tools. DocMorris anchors cross-border prescription logistics within European regulatory corridors.
Pharma e-commerce denotes the digital sale and distribution of pharmaceutical products, medical devices, and health-related consumables through verified online platforms that integrate prescription validation, cold-chain logistics, and patient identity verification protocols. Its primary purpose is to expand medication access while reducing dispensing overhead and geographic barriers to care. Prescription drugs dominate transaction value, though subscription plans for chronic therapies capture the most predictable margin pools. Third-party platforms attract the highest customer acquisition volumes, while direct-to-consumer channels retain superior lifetime value through controlled patient data.
FDA digital pharmacy verification, EMA cross-border dispensing rules, and HIPAA data safeguards collectively determine platform licensure scope and patient trust architecture. India's CDSCO e-pharmacy draft regulations and Germany's BfArM mail-order pharmacy licensing impose additional operational compliance layers. Stakeholders must monitor evolving serialization mandates and telehealth prescribing authority shifts to anticipate which distribution models will retain legal clearance.
Market Dynamics
Chronic disease patient onboarding is restructuring how pharmacy platforms allocate fulfillment infrastructure. CVS Health leverages its retail footprint to sustain same-day delivery density in urban corridors. Amazon Pharmacy competes on automated refill algorithms and price transparency tools. DocMorris anchors cross-border prescription logistics within European regulatory corridors.
Growth Catalysts
- FDA digital pharmacy verification:Accelerates platform certification requirements and patient trust architecture for prescription drug dispensing.
- Chronic disease patients:Shift toward online prescription fulfillment, creating sustained demand for subscription-based medication management.
- Cold-chain logistics:Temperature-controlled distribution networks expand biologics access beyond traditional pharmacy catchment areas.
Market Restraints
- HIPAA data safeguards:Impose substantial compliance costs on patient identity verification protocols and platform architecture.
- EMA cross-border dispensing rules:Create regulatory friction for mail-order pharmacies operating across European member states.
- Serialized packaging mandates:Require capital-intensive track-and-trace infrastructure for counterfeit prevention.
Strategic Opportunities
- India's CDSCO e-pharmacy draft regulations:Pending framework creates first-mover positioning for compliant platform operators.
- Telehealth prescribing authority:Convergence with remote diagnostics enables integrated diagnosis-to-delivery service models.
- Germany's BfArM mail-order licensing:Regulatory clarity supports cross-border expansion within European corridors.
Industry Challenges
- Patient identity verification:Multi-factor authentication protocols create checkout friction and cart abandonment.
- Legacy pharmacy management systems:Integration complexity with real-time inventory APIs delays platform deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma E-Commerce Market |
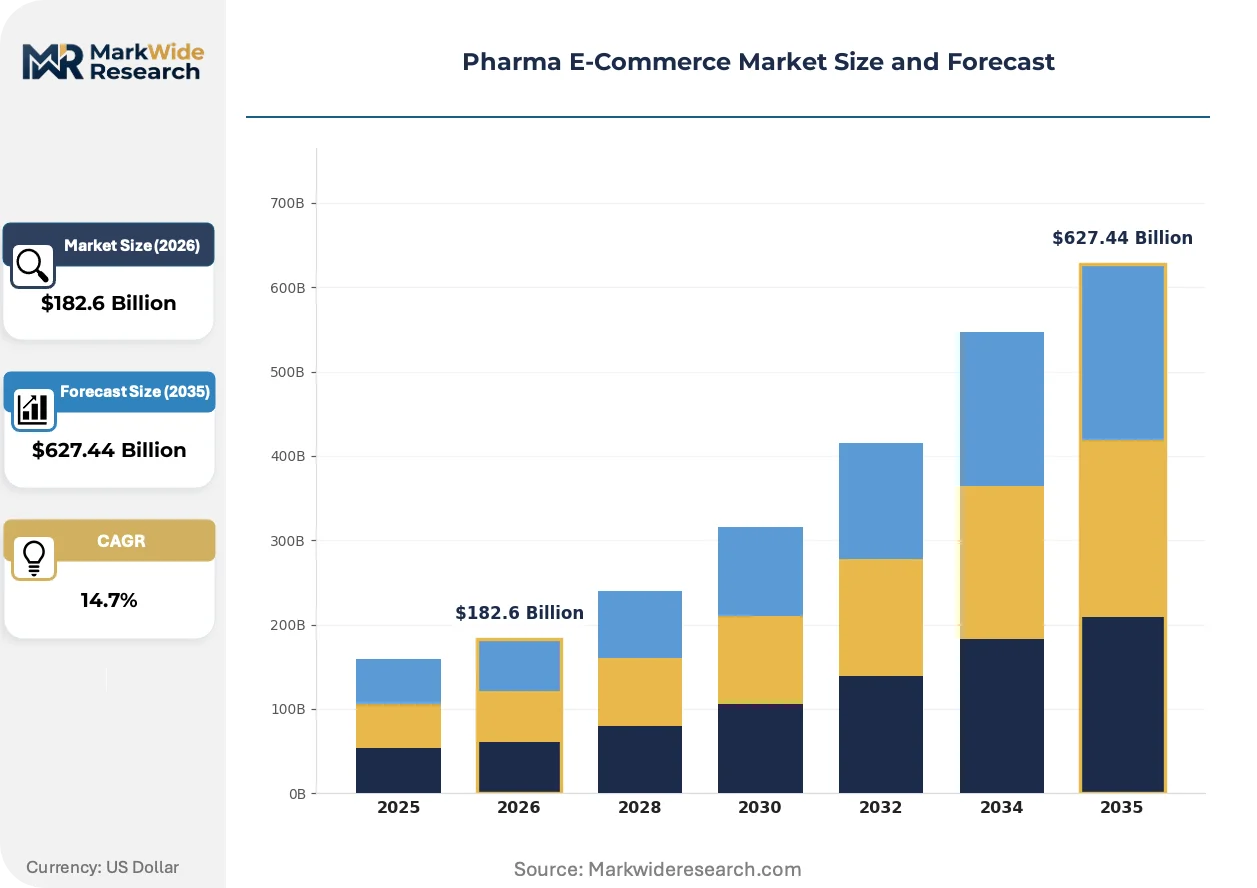
| Market Size in 2026 | $182.6 Billion |
| Market Size in 2035 | $627.44 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Nutraceuticals, Medical Devices Distribution Channel: Online Pharmacies, Direct-to-Consumer, Third-Party Platforms, Health Apps Customer Type: Individuals, Healthcare Professionals, Hospitals, Corporations Service Type: Delivery Services, Consultation Services, Subscription Plans, e-Prescribing |
| Companies Covered | CVS Health, Walgreens Boots Alliance, Amazon Pharmacy, Walmart Inc., Express Scripts, OptumRx, DocMorris, McKesson Corporation, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma E-Commerce Market Evolving Landscape
Digital health infrastructure is actively reshaping how pharmaceutical products reach end patients. Three interconnected developments are compressing traditional dispensing timelines and reconfiguring competitive positioning across verified online platforms.
Blockchain-enabled drug provenance tracking is electrifying supply chain transparency for high-value biologics and controlled substances. Hospital systems and specialty pharmacies in the United States adopt these verification layers to satisfy FDA DSCSA compliance deadlines. The technology is electrifying trust architectures between manufacturers and end patients, compressing the role of traditional wholesale intermediaries.
EMA's updated guidance on distance selling of medicinal products tightens patient consultation requirements for cross-border dispensaries. This regulatory recalibration forces platform operators to embed synchronous telehealth interfaces before prescription authorization. Mail-order pharmacies in Germany, the Netherlands, and Switzerland accelerate compliance investments to retain European market access.
Subscription-based chronic therapy management displaces transactional refill patterns among diabetes, hypertension, and cardiovascular patient cohorts. Automated dosing algorithms and predictive adherence monitoring replace periodic physician consultations in medication continuity. This behavioral pivot concentrates lifetime value capture in the United States, Germany, and India where insurance-integrated platforms dominate.
Pharma E-Commerce Market Segmentation
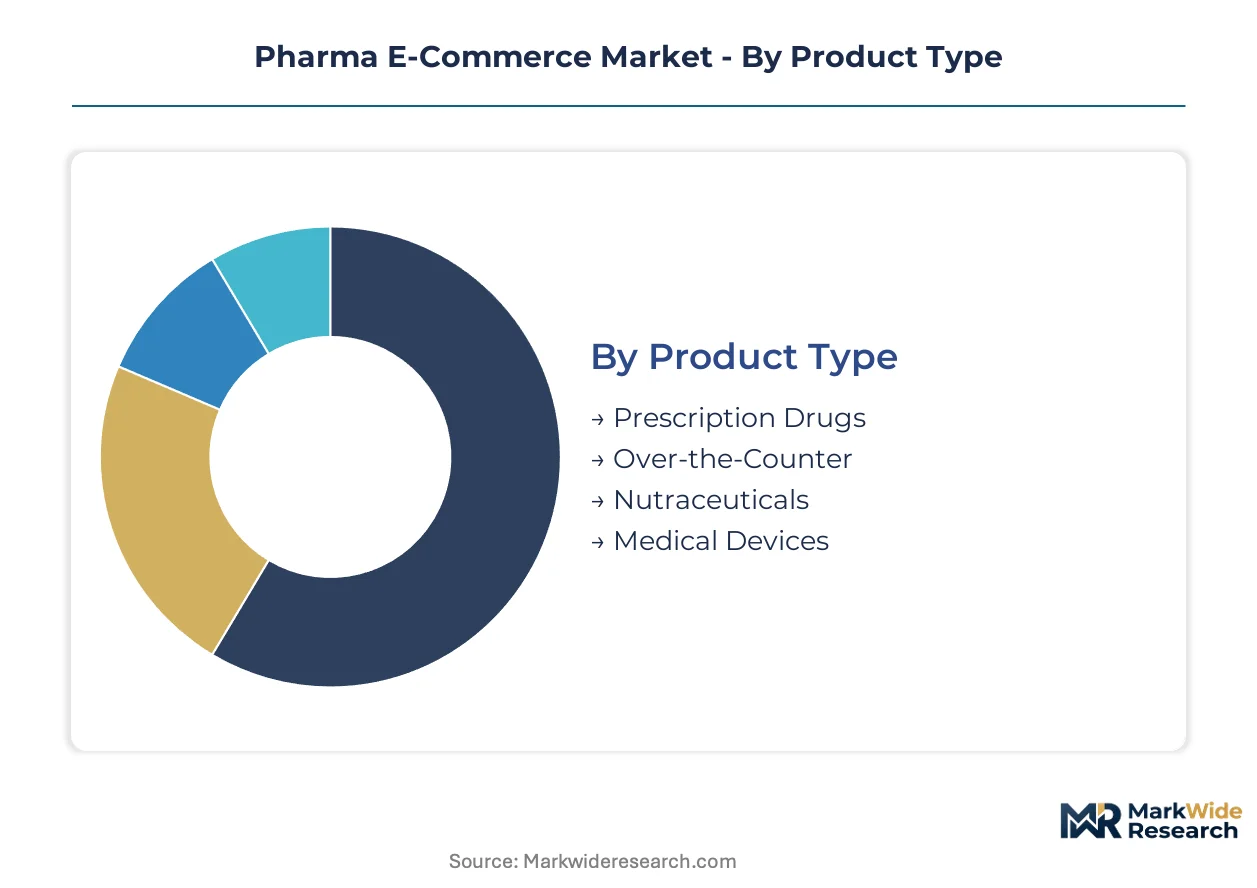
Pharma e-commerce segmentation reveals how capital allocation and regulatory compliance cluster around distinct operational models. Platform operators must align infrastructure investments with the specific verification, logistics, and reimbursement requirements of each segment category.
Product Type:
Supply concentration for temperature-sensitive and controlled substances shapes how fulfillment networks partition across product categories.
- Prescription Drugs:Temperature-controlled biologics and specialty therapies require validated cold-chain infrastructure and DEA-licensed dispensing facilities. Demand concentrates among chronic disease patients in the United States and Germany where insurance-integrated platforms dominate subscription-based fulfillment.
- Over-the-Counter:Non-prescription analgesics, antihistamines, and digestive remedies move through high-velocity distribution centers without prescription validation overhead. Volume clusters in urban corridors across India and the United States where same-day delivery density justifies automated warehouse investment.
- Nutraceuticals:Vitamin formulations and dietary supplements face lighter regulatory scrutiny but heavier margin pressure from private-label competition.
- Medical Devices:Continuous glucose monitors, blood pressure cuffs, and diagnostic kits integrate with telehealth platforms for remote patient monitoring.
Prescription drugs absorb the bulk of installed cold-chain capacity; nutraceuticals are expanding most quickly in emerging markets.
Distribution Channel:
Margin structure and patient data ownership diverge sharply between intermediary-dependent and direct-capture models.
- Online Pharmacies:Licensed digital dispensaries integrate prescription validation, insurance adjudication, and last-mile logistics under unified compliance frameworks. Demand concentrates among Medicare and Medicaid beneficiaries in the United States seeking cost transparency tools.
- Direct-to-Consumer:Manufacturer-owned platforms bypass wholesale intermediaries to capture patient adherence data and lifetime value. Growth is steepest in Germany and Switzerland where BfArM licensing clarity supports cross-border expansion.
- Third-Party Platforms:Marketplace aggregators attract highest customer acquisition volumes through price comparison engines.
- Health Apps:Mobile-first interfaces embed prescription fulfillment within chronic disease management workflows.
Third-party platforms command the highest transaction volumes; direct-to-consumer channels retain superior unit economics.
Customer Type:
Procurement authority and reimbursement pathways determine platform feature prioritization across buyer categories.
- Individuals:Chronic therapy patients drive subscription revenue through automated refill algorithms and predictive adherence monitoring. Demand concentrates in the United States and India where out-of-pocket cost sensitivity fuels price comparison behavior.
- Healthcare Professionals:Physician practices and clinics procure formulary-aligned therapies through GPO-integrated procurement portals. Volume clusters in hospital-affiliated networks seeking formulary compliance dashboards.
- Hospitals:Health system pharmacies source high-cost biologics through 340B-eligible channels.
- Corporations:Self-insured employers negotiate direct contracts for employee pharmacy benefits.
Individuals generate the highest transaction frequency; healthcare professionals anchor the steepest expansion trajectory for B2B platform modules.
Service Type:
Revenue predictability and regulatory exposure vary across fulfillment and advisory service lines.
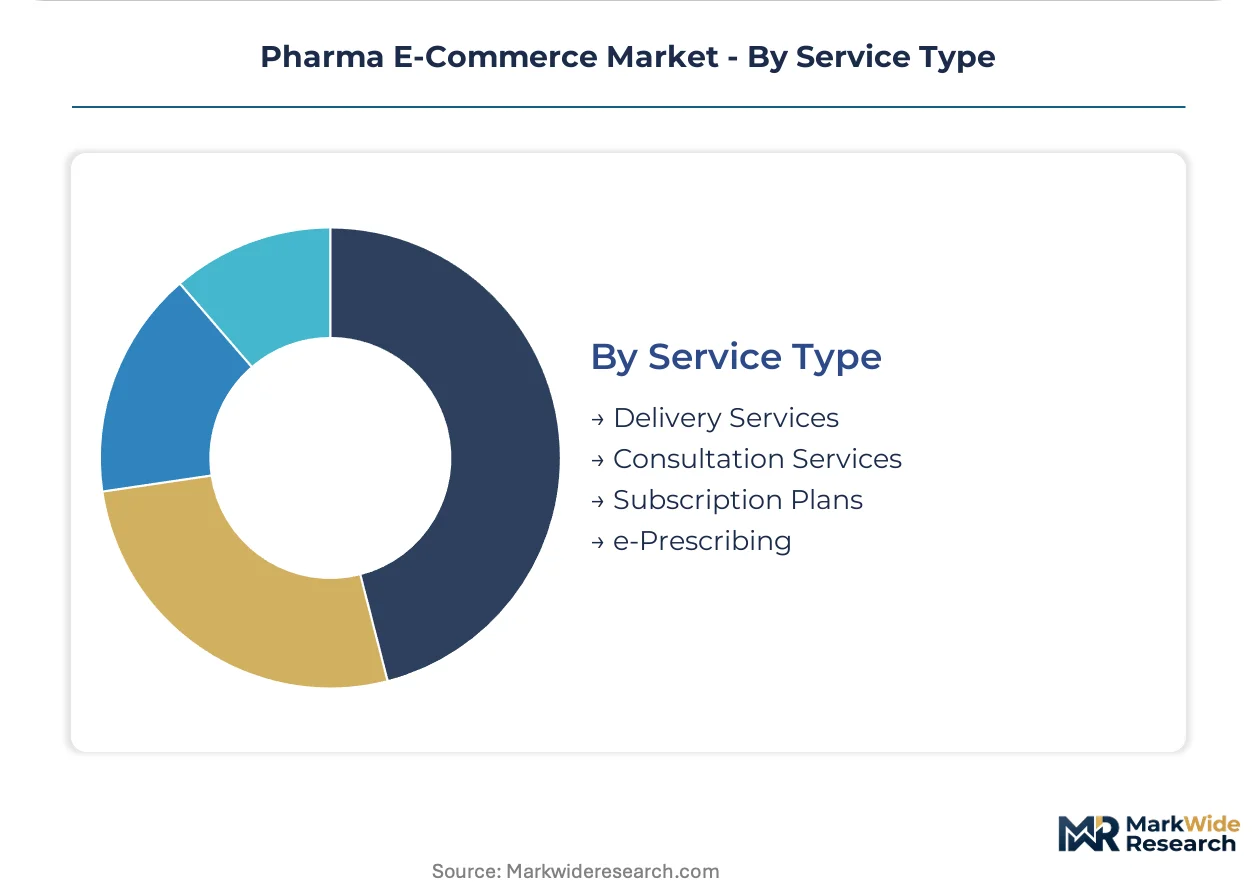
- Delivery Services:Same-day and scheduled courier networks compete on geographic coverage and temperature integrity guarantees. Demand concentrates in dense urban markets across the United States and Germany where retail pharmacy footprints support hybrid fulfillment models.
- Consultation Services:Synchronous telehealth interfaces satisfy EMA distance-selling consultation requirements for cross-border dispensing. Growth is fastest in the Netherlands and Switzerland where regulatory clarity enables integrated diagnosis-to-delivery workflows.
- Subscription Plans:Automated chronic therapy management displaces transactional refill patterns.
- e-Prescribing:Electronic prescription routing reduces dispensing errors and accelerates fulfillment timelines.
Delivery services absorb the bulk of logistics infrastructure investment; consultation services are climbing the fastest as regulatory mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity for pharmaceutical fulfillment infrastructure tilts toward established logistics corridors, while patient demand concentrates in aging populations with chronic disease burdens. Regulatory fragmentation across national borders forces platform operators to maintain parallel compliance architectures. Cold-chain capacity investments cluster where insurance-integrated reimbursement models sustain subscription economics.
United States
Medicare and Medicaid beneficiaries drive prescription volume through cost-transparency tools and automated refill platforms. FDA digital pharmacy verification mandates compress platform certification timelines while elevating patient trust requirements. The Northeast Corridor sustains same-day delivery density through hybrid retail-fulfillment networks anchored by urban pharmacy footprints.
Germany
BfArM mail-order pharmacy licensing provides regulatory clarity for cross-border expansion into neighboring European markets. EMA distance-selling consultation requirements force synchronous telehealth integration before prescription authorization. The Rhine-Ruhr metropolitan cluster concentrates fulfillment infrastructure for temperature-sensitive biologics distribution.
India
Out-of-pocket cost sensitivity fuels price-comparison behavior among chronic therapy patients seeking subscription-based medication management. CDSCO e-pharmacy draft regulations create first-mover positioning opportunities for compliant platform operators. Maharashtra and Karnataka anchor startup formation for health-tech platforms targeting tier-2 and tier-3 city penetration.
United Kingdom
NHS Digital prescription routing integration accelerates electronic fulfillment timelines while reducing dispensing errors. MHRA post-Brexit regulatory autonomy recalibrates cross-border dispensing protocols with European counterparts. The Greater London area concentrates same-day courier networks for urgent medication delivery to aging urban populations.
Switzerland
Swissmedic licensing requirements for distance selling impose stringent patient consultation protocols on platform operators. Private insurance reimbursement models sustain premium pricing for integrated diagnosis-to-delivery service workflows. The Zurich-Geneva corridor anchors specialized logistics for high-value biologics requiring validated cold-chain integrity.
Pharma E-Commerce Market Competitive Landscape
Top-tier vendors anchor integrated health system ecosystems, while mid-tier specialists compete on niche fulfillment capabilities or geographic density. The competitive structure stratifies across three distinct tiers: retail pharmacy chains with physical footprints, technology-native platforms with automated logistics, and wholesale distributors with formulary integration. Consolidation pressures intensify as M&A activity accelerates platform certification capabilities and strategic partnerships expand cross-border regulatory coverage.
Within the integrated health system tier, CVS Health and Walgreens Boots Alliance occupy positions that exemplify retail-anchored fulfillment density, while Amazon Pharmacy represents the technology-native archetype competing on algorithmic automation and price transparency. DocMorris anchors cross-border prescription logistics within European regulatory corridors, demonstrating how specialized licensing compliance creates defensible market positioning against generalized competitors.
| Leading Market Players |
|---|
| CVS Health |
| Walgreens Boots Alliance |
| Amazon Pharmacy |
| Walmart Inc. |
| Express Scripts |
| OptumRx |
| DocMorris |
| McKesson Corporation |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Medicare and Medicaid beneficiary demand for cost transparency tools is forcing platform operators to absorb prescription validation overhead while maintaining competitive delivery guarantees, compressing margins on generic fulfillment tiers and widening spreads between insurance-integrated and cash-pay channels.
Pricing Analysis
Lead-time-driven pricing stratification separates same-day urban delivery premiums from scheduled rural discounts, with CVS Health and Walgreens extracting geographic rent through hybrid retail-fulfillment density. Price differentiation hinges on cold-chain certification tier and insurance adjudication integration, with HIPAA-compliant platforms commanding service premiums over cash-pay alternatives. Cost compression in generic prescription tiers is intensifying due to Amazon Pharmacy's algorithmic price-matching engines. Individual chronic therapy patients exhibit highest price sensitivity, while hospital 340B-eligible procurement shows lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with temperature-controlled biologics manufacturing concentrated in the United States, Germany, and Switzerland, where Swissmedic and FDA validation requirements create captive supplier relationships. Active pharmaceutical ingredient sourcing draws from Indian and Chinese chemical synthesis hubs, with DEA-licensed domestic facilities handling final formulation and packaging. Tariff exposure on cross-border API shipments threatens margin stability for subscription-based chronic therapy platforms. Distribution runs through hybrid retail-fulfillment networks anchored by urban pharmacy footprints, with last-mile courier partnerships extending coverage into suburban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled drug provenance tracking is displacing legacy paper-based verification systems, creating first-mover advantages for platforms that integrate DSCSA-compliant serialization before FDA enforcement deadlines.
For Market Incumbents: Deploy synchronous telehealth interfaces to satisfy EMA distance-selling consultation mandates before prescription authorization, insulating cross-border European revenue streams from regulatory suspension. Deepen cold-chain capacity in the Rhine-Ruhr and Northeast Corridor metropolitan clusters to defend same-day delivery density against Amazon Pharmacy's algorithmic automation threat. Pursue BfArM licensing reciprocity agreements to streamline mail-order expansion across German-speaking European markets. For New Entrants and Emerging Players: Launch via health app-embedded prescription fulfillment targeting India's tier-2 and tier-3 cities, where CDSCO regulatory clarity remains pending and first-mover positioning is achievable. Exploit white-space in corporate self-insured employer pharmacy benefit contracts, where formulary-integrated procurement portals remain underdeveloped. Capture chronic therapy subscription revenue through automated adherence monitoring differentiated from transactional refill incumbents. For Investors and Strategic Acquirers: The window for entry favors technology-native platforms with validated cold-chain infrastructure over retail-anchored legacy operators facing fulfillment density constraints. Long-term viability centers on patient data ownership architectures that sustain lifetime value capture through direct-to-consumer channels. Monitor telehealth prescribing authority convergence with remote diagnostics as the inflection signal for integrated diagnosis-to-delivery service model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | FDA DSCSA compliance deadlines electrify supply chain transparency investments for high-value biologics verification. |
| Synchronous Telehealth Embedding | EMA distance-selling mandates force consultation interface investments before cross-border prescription authorization. |
| Cold-Chain Capacity Expansion | Rhine-Ruhr and Northeast Corridor metropolitan density supports same-day temperature-sensitive delivery guarantees. |
| Subscription Platform Development | Automated chronic therapy management displaces transactional refill patterns in diabetes and cardiovascular cohorts. |
| Direct-to-Consumer Channel Buildout | Manufacturer-owned platforms capture patient adherence data and lifetime value through controlled data architectures. |
Research Methodology
Document review covered FDA digital pharmacy verification guidance, EMA distance-selling consultation requirements, CDSCO draft e-pharmacy regulations, and CMS Medicare prescription data, complemented by interviews with pharmacy benefit managers, cold-chain logistics directors, telehealth platform engineers, and hospital formulary directors. Secondary validation drew from FDA DSCSA compliance filings, BfArM mail-order licensing records, clinical trial registries, and insurance adjudication platform disclosures. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level demand estimates.
Segmentation outputs across product type, distribution channel, customer archetype, and service category were projected across the analysis window using patient population growth, chronic disease prevalence shifts, and regulatory authorization timelines as primary demand drivers. CAGRs were derived from fitted growth curves applied to insurance penetration rates and telehealth adoption elasticities. Forecast inputs incorporated FDA digital pharmacy certification velocity, EMA cross-border dispensing rule evolution, and cold-chain infrastructure investment cycles.
The model assumes a particular technology adoption path for blockchain-enabled drug provenance tracking; alternative verification pathways for DSCSA compliance would alter the outlook for supply chain transparency investments. Forecasts reflect assumptions regarding telehealth prescribing authority expansion and CDSCO regulatory finalization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
E-Tailing Market