
 Hybrid Cloud Services Market | 2026-2036
Hybrid Cloud Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cloud Services Market Outlook
North American hyperscaler capacity expansion is fragmenting competitive dynamics across the hybrid cloud landscape. Amazon Web Services leverages its GovCloud regions to anchor public-sector workloads requiring air-gapped environments. Microsoft Azure sustains enterprise loyalty through deep integration with on-premises Active Directory and Windows Server estates. IBM Cloud differentiates via mainframe connectivity and financial-services compliance tooling that bridges legacy infrastructure with containerized platforms.
Hybrid cloud services orchestrate compute, storage, and networking resources across both privately operated data centers and third-party public infrastructure, typically employing Kubernetes federation, software-defined networking, and encrypted inter-cloud transit to maintain workload portability and data consistency. The architecture serves organizations that must retain sensitive data on premises while bursting transactional peaks to elastic public capacity. Infrastructure as a Service dominates current spending as enterprises replatform virtual machines onto hybrid-compatible stacks, yet Security Solutions command expanding margin pools as attack surface complexity multiplies across environments. Disaster Recovery as a segment accelerates fastest among service types, driven by board-level mandates for operational resilience against ransomware and regional outages.
FCC data-localization guidance, EU GDPR territorial scope rules, and China's Cybersecurity Law collectively shape where providers must site infrastructure and how they architect cross-border data flows. ISO 27017 cloud-security certification and the EU Cybersecurity Act's certification frameworks now function as de facto market-access requirements for enterprise procurement. Stakeholders must monitor evolving sovereign-cloud mandates that could bifurcate global platforms into nationally ring-fenced instances with incompatible APIs.
Market Dynamics
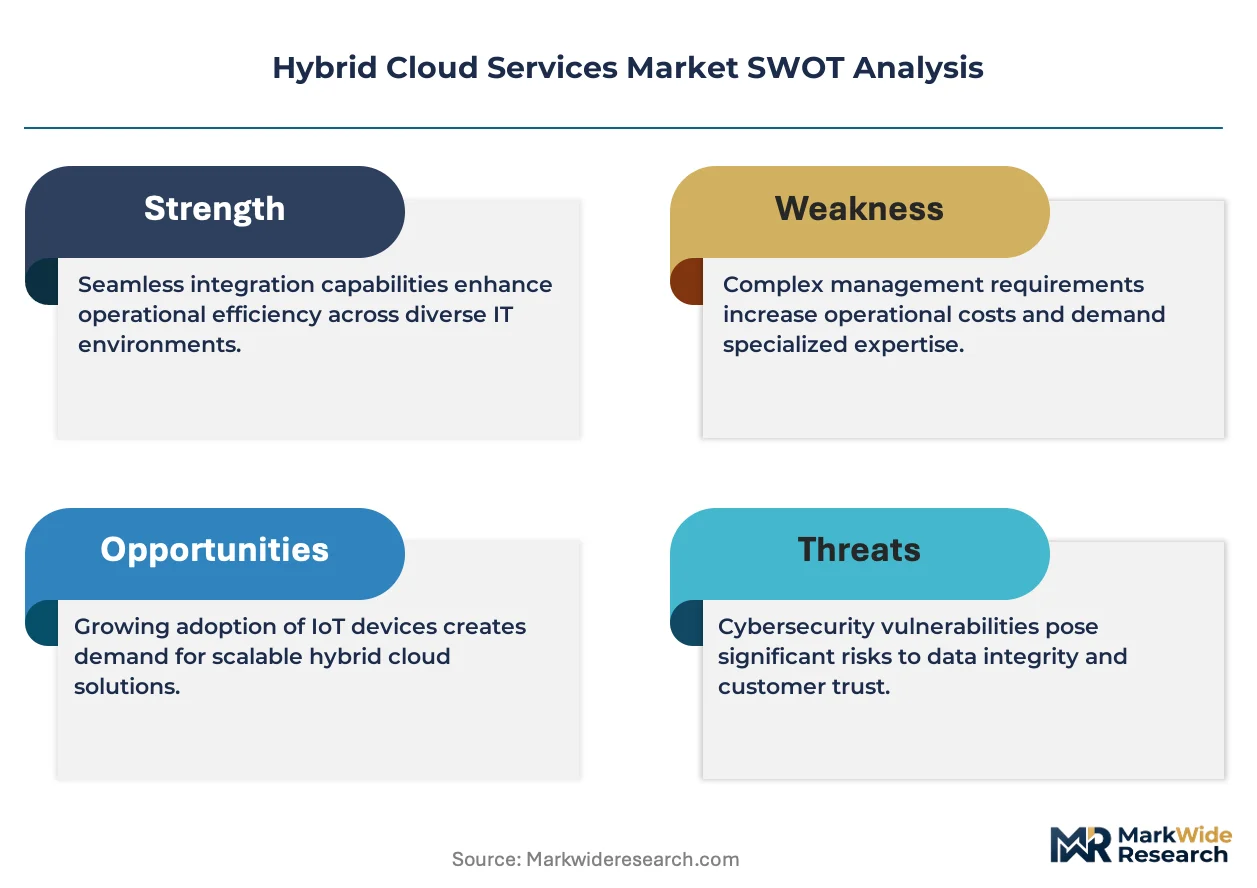
Workload portability requirements are fragmenting infrastructure procurement patterns across enterprises, forcing providers to engineer seamless federation between sovereign on-premises stacks and hyperscaler capacity.
Growth Catalysts
- EU AI Act compliance deadlines:European financial institutions must maintain audit trails and data residency controls that hybrid architectures uniquely satisfy, accelerating replatforming timelines.
- Industrial IoT data gravity:German automotive and machinery manufacturers generate terabyte-scale operational telemetry that cannot egress cost-effectively, anchoring private cloud investment.
- Kubernetes federation maturation:Cross-cluster orchestration tooling now enables genuine workload mobility without vendor lock-in, reducing migration friction for conservative IT estates.
Market Restraints
- Specialized talent scarcity:Site reliability engineers with hybrid networking and security credentials command premium compensation, constraining deployment velocity for mid-market buyers.
- Cross-border data friction:China's Cybersecurity Law mandates local storage for personal information, complicating unified management plane architectures for multinational corporations.
- Legacy mainframe integration costs:Financial services incumbents face seven-figure refactoring expenses to containerize COBOL workloads for hybrid portability.
Strategic Opportunities
- Sovereign cloud mandates in France:ANSM and CNIL guidance on health data localization creates demand for nationally ring-fenced infrastructure with EU-controlled encryption key escrow.
- Edge-to-cloud orchestration convergence:5G network slicing combined with distributed Kubernetes is enabling real-time manufacturing quality control with centralized model training.
- US Inflation Reduction Act incentives:Domestic semiconductor and battery manufacturers qualify for tax credits contingent on US-sited data infrastructure, favoring hybrid over pure-public deployments.
Industry Challenges
- Multi-environment security posture management:CISOs struggle to maintain consistent zero-trust policies across on-premises VMware estates, AWS GovCloud regions, and Azure sovereign instances with divergent IAM implementations.
- ISO 27017 certification timelines:Cloud service providers face 12-18 month audit cycles to achieve cross-border recognition, delaying market entry for regional challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cloud Services Market |
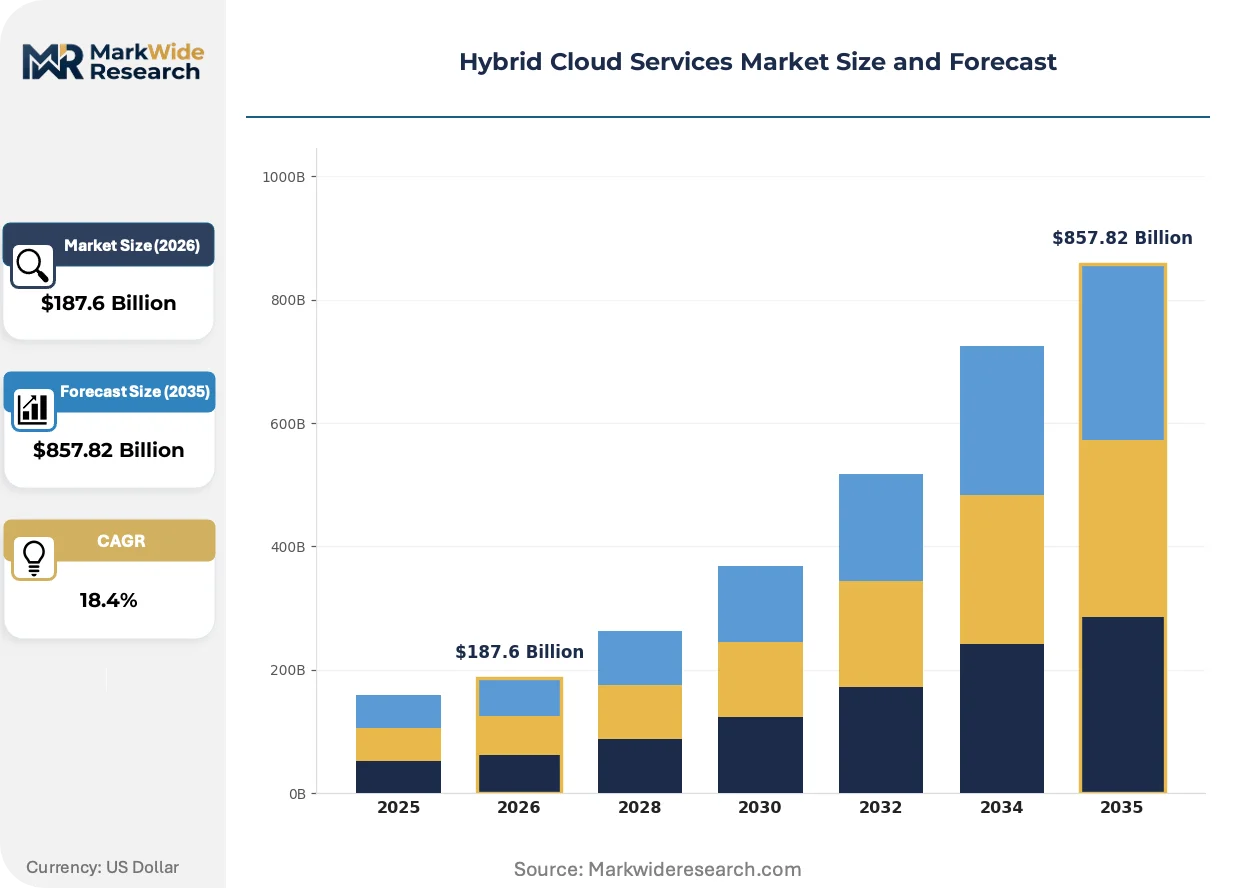
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Solution: Backup Solutions, Security Solutions, Integration Tools, Monitoring Tools |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, VMware, IBM Cloud, Hewlett Packard Enterprise, Dell Technologies, Cisco Systems, Nutanix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cloud Services Market Strategic Shifts
Platform engineering disciplines are replacing traditional IT operations, embedding self-service infrastructure provisioning into developer workflows and collapsing the boundary between software and infrastructure teams.
Immutable infrastructure patterns using container-optimized operating systems like Bottlerocket and Flatcar Linux are rendering obsolete conventional patch-management cycles for virtual machine fleets. Federal agencies and defense contractors operating air-gapped environments adopt these images to minimize attack surface maintenance burden. The shift compresses operational overhead budgets while accelerating security compliance velocity for regulated workloads.
REACH chemical substance restrictions and the EU F-Gas Regulation are pressuring data center operators to phase out sulfur hexafluoride switchgear and high-GWP refrigerants in cooling systems. Hyperscalers must retrofit or replace existing mechanical infrastructure to maintain European operational permits. German and Dutch facility operators lead retrofit investment, driving demand for liquid cooling and natural refrigerant architectures.
Consumption-based committed use contracts are displacing traditional reserved instance purchasing for hybrid cloud capacity. Enterprise procurement teams negotiate flexible spend agreements spanning private colocation and public burst resources through unified billing frameworks. Japanese automotive manufacturers pioneered this structure, and it now spreads to North American pharmaceutical supply chain operations seeking operational expenditure predictability.
Hybrid Cloud Services Market Segmentation
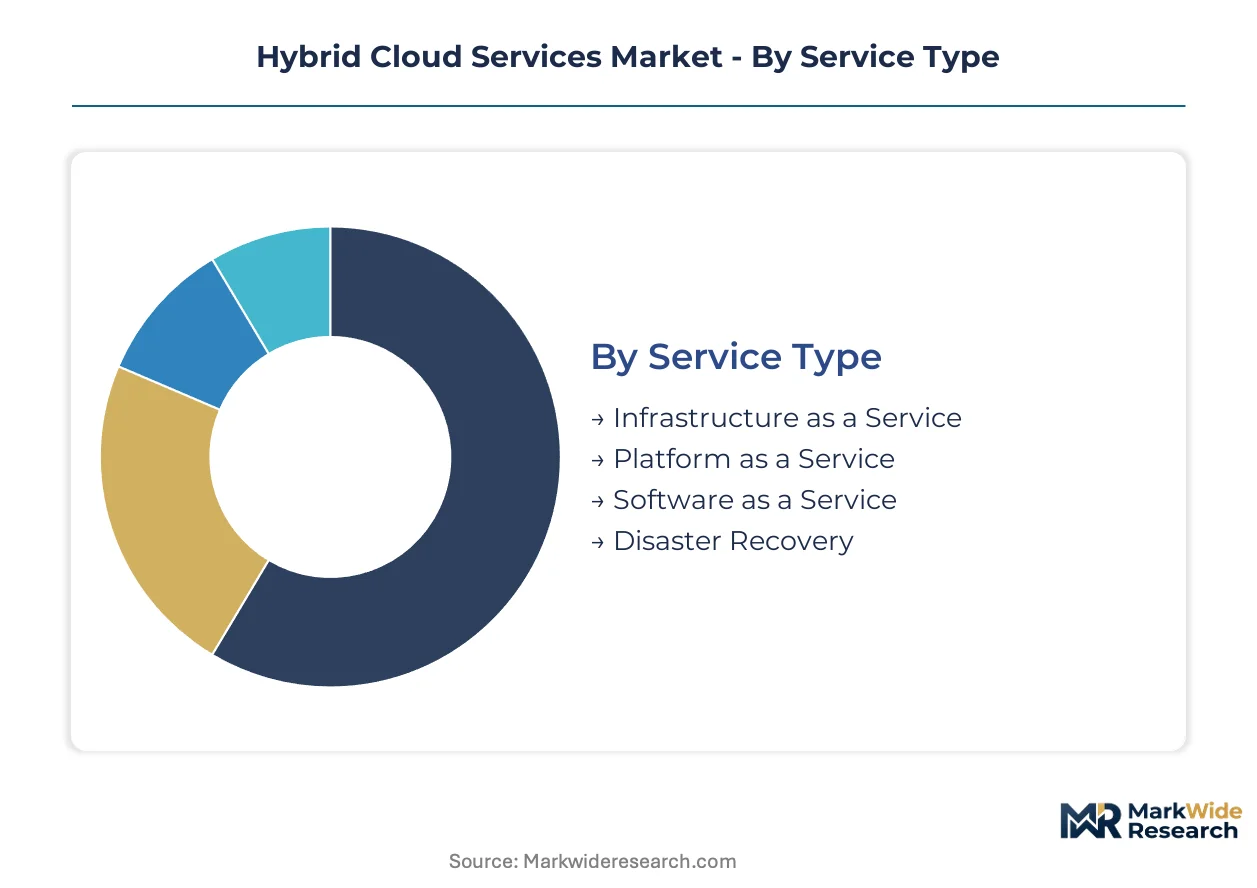
Segmentation in hybrid cloud services reveals distinct procurement rhythms and margin architectures across service tiers. Buyers with regulated workloads prioritize control planes over cost optimization, while cloud-native entrants favor consumption elasticity over sovereignty guarantees.
Service Type:
Infrastructure as a Service turns over fastest as enterprises replatform virtual machines onto hybrid-compatible stacks, while Disaster Recovery contracts lock in longest due to board-level resilience mandates.
- Infrastructure as a Service:Delivers compute, storage, and networking resources via virtualized abstraction layers that bridge on-premises VMware estates with hyperscaler capacity. German automotive manufacturers anchor demand here for factory-floor simulation workloads that burst to elastic public infrastructure during peak design cycles.
- Disaster Recovery:Orchestrates failover replication across geographically distributed environments with encrypted inter-cloud transit and sub-hour recovery point objectives. Financial services firms in France drive expansion under ANSM and CNIL guidance requiring health data localization with EU-controlled encryption key escrow.
- Platform as a Service:Abstracts Kubernetes federation and container runtime management for developer self-service provisioning.
- Software as a Service:Delivers application-layer functionality via subscription models with hybrid data residency options.
Infrastructure as a Service dominates installed base. Disaster Recovery is where expansion concentrates.
Deployment Model:
Cost tier stratification separates sovereign private deployments from commodity public capacity, with multi-cloud architectures commanding premium professional services attach rates.
- Private Cloud:Operates dedicated infrastructure within enterprise-controlled data centers or single-tenant colocation facilities with hardware-level isolation. Industrial IoT data gravity in German machinery manufacturing anchors investment here, as terabyte-scale operational telemetry cannot egress cost-effectively to public infrastructure.
- Multi-Cloud:Federates workloads across heterogeneous hyperscaler environments using software-defined networking and encrypted transit gateways. US semiconductor manufacturers qualifying for Inflation Reduction Act tax credits favor this model to satisfy domestic data infrastructure requirements while retaining vendor portability.
- Public Cloud:Delivers shared infrastructure via hyperscaler regions with standardized APIs and consumption-based billing.
- Community Cloud:Serves consortia of organizations with common compliance requirements, such as defense contractors sharing air-gapped GovCloud-equivalent environments.
Private Cloud retains the deepest installed base concentration. Multi-Cloud is climbing the fastest as procurement teams negotiate unified billing frameworks spanning colocation and burst capacity.
End User:
Application context distinguishes regulated entities with audit trail obligations from volume buyers prioritizing operational expenditure predictability.
- Large Enterprises:Maintain dedicated platform engineering teams embedding self-service infrastructure provisioning into developer workflows. Japanese automotive manufacturers pioneered consumption-based committed use contracts now spreading to North American pharmaceutical supply chain operations.
- Government:Requires air-gapped environments with FedRAMP or equivalent certification for classified and controlled unclassified information. FCC data-localization guidance shapes infrastructure siting decisions for federal agencies operating hybrid architectures.
- SMEs:Depend on managed service providers for hybrid orchestration due to specialized talent scarcity in site reliability engineering.
- Educational Institutions:Leverage community cloud and grant-funded public sector pricing tiers for research computing workloads.
Large Enterprises dominate current spending. Government is where compliance-driven expansion concentrates.
Solution:
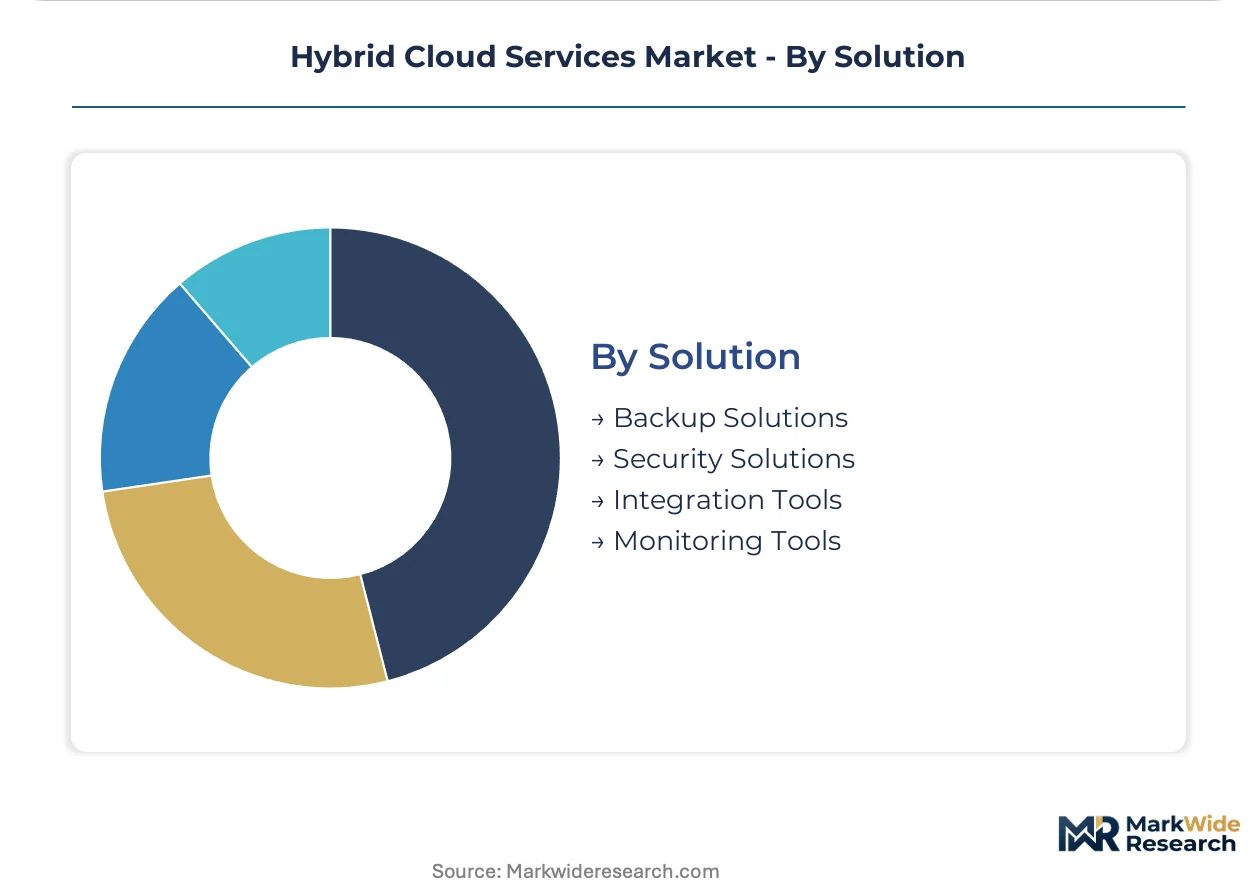
Margin pools concentrate in security posture management as attack surface complexity multiplies across on-premises VMware estates, sovereign cloud instances, and hyperscaler regions.
- Security Solutions:Delivers zero-trust policy enforcement, identity and access management federation, and encrypted inter-cloud transit across divergent IAM implementations. CISOs in European financial institutions drive demand here under EU AI Act compliance deadlines requiring audit trails and data residency controls.
- Integration Tools:Provides API gateways, event streaming, and data synchronization across heterogeneous environments. German and Dutch facility operators lead retrofit investment here as REACH chemical substance restrictions and EU F-Gas Regulation pressure data center operators to phase out sulfur hexafluoride switchgear.
- Backup Solutions:Automates snapshot replication and immutable storage for ransomware recovery scenarios.
- Monitoring Tools:Delivers unified observability across on-premises, edge, and public cloud infrastructure with centralized logging.
Security Solutions commands expanding margin pools. Integration Tools is gaining share fastest as platform engineering disciplines collapse boundaries between software and infrastructure teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC data-localization guidance anchors infrastructure siting decisions for federal agencies operating hybrid architectures across the United States. Regulatory fragmentation across jurisdictions is forcing providers to engineer nationally ring-fenced instances with divergent compliance requirements.
United States
Domestic semiconductor and battery manufacturers qualify for IRA tax credits contingent on US-sited data infrastructure, favoring hybrid over pure-public deployments. FCC guidance shapes air-gapped GovCloud procurement for defense contractors. Greater Boston and Pacific Northwest clusters concentrate platform engineering talent for Kubernetes federation tooling.
Germany
Industrial IoT data gravity from automotive and machinery manufacturers anchors private cloud investment as terabyte-scale operational telemetry cannot egress cost-effectively. EU F-Gas Regulation pressures data center operators to phase out sulfur hexafluoride switchgear. Baden-Württemberg facility operators lead retrofit investment for liquid cooling architectures.
France
ANSM and CNIL guidance on health data localization creates demand for nationally ring-fenced infrastructure with EU-controlled encryption key escrow. EU AI Act compliance deadlines accelerate replatforming timelines for financial institutions. Île-de-France hosts sovereign cloud capacity serving pharmaceutical supply chain operations.
Japan
Automotive manufacturers pioneered consumption-based committed use contracts now spreading to North American pharmaceutical operations. METI industrial policy supports edge-to-cloud orchestration for manufacturing quality control. Kanto region clusters concentrate self-service infrastructure provisioning expertise for developer workflows.
United Kingdom
Financial services firms accelerate hybrid adoption to balance data sovereignty with scalability for post-Brexit regulatory alignment. GDPR territorial scope rules shape cross-border data flow architectures. London/Southeast concentrates enterprise procurement teams negotiating unified billing frameworks spanning colocation and burst capacity.
Hybrid Cloud Services Market Competitive Environment
Hyperscale public cloud divisions and legacy enterprise infrastructure vendors split the market along workload portability requirements. Amazon Web Services, Microsoft Azure, and Google Cloud anchor the public-capacity tier with sovereign region deployments, while VMware, IBM Cloud, and Hewlett Packard Enterprise bridge on-premises estates with containerized platforms. The competitive dynamic centers on federation tooling maturity and compliance certification velocity rather than raw infrastructure scale.
Within the hyperscaler tier, Amazon Web Services and Microsoft Azure exemplify divergent anchoring strategies for regulated workloads, with the former leveraging GovCloud regions for air-gapped environments and the latter sustaining enterprise loyalty through Active Directory integration. IBM Cloud occupies a position bridging mainframe connectivity with financial-services compliance tooling. Dell Technologies and Hewlett Packard Enterprise sit within the infrastructure hardware tier supplying converged systems for private cloud deployment. Nutanix represents the hyperconverged specialist archetype enabling mid-market buyers to consolidate compute and storage without specialized site reliability engineering talent.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| VMware |
| IBM Cloud |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Cisco Systems |
| Nutanix |
| Others |
Value Chain & Pricing Dynamics
Regulatory chokepoint exposure around EU sovereign cloud mandates determines both pricing tier spreads and supply chain shape, as compliance certification velocity separates premium providers from commodity competitors while forcing infrastructure localization investments that fragment procurement patterns across member states.
Pricing Analysis
Geographic price spreads between Frankfurt and Singapore data center markets exceed threefold for equivalent compute tiers, reflecting divergent compliance certification costs and local labor premiums. Three-tier pricing structure across premium sovereign-certified, standard enterprise-grade, and economy burst-capacity levels dominates contract negotiations, with ISO 27017 certification status and domestic encryption key escrow capabilities as primary differentiation drivers. Pricing pressure stems from hyperscaler capacity expansion in secondary European markets, compressing margins for regional colocation operators. Large financial institutions exhibit lowest price sensitivity due to board-level resilience mandates, while mid-market manufacturers prioritize operational expenditure predictability over sovereignty guarantees.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for semiconductor-dependent server hardware, constraining hardware refresh cycles for private cloud deployments. Supply concentrates in Taiwan for advanced processors, Malaysia for memory modules, and Mexico for edge computing enclosures, creating single-source vulnerability for x86 architectures. Raw material dependencies span rare earth elements for magnetic storage, high-purity silicon for photonics, and copper for liquid cooling infrastructure. Distribution runs through direct hyperscaler procurement for public capacity and systems integrator channels for on-premises converged infrastructure, with Japanese automotive manufacturers pioneering unified billing frameworks now spreading to pharmaceutical supply chain operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer power is concentrating through procurement team consolidation, as Japanese automotive manufacturers and North American pharmaceutical operations negotiate unified consumption-based contracts spanning colocation and burst capacity, shifting leverage toward volume purchasers with multi-year committed use structures.
For Market Incumbents: Insulate GovCloud and sovereign region franchises by accelerating FedRAMP and EU Cybersecurity Act certification timelines ahead of compliance deadline clustering, while embedding Kubernetes federation tooling deeper into Active Directory estates to raise switching costs for Microsoft Azure-anchored workloads. Vertical integration into liquid cooling hardware addresses EU F-Gas Regulation retrofit demand from German facility operators. For New Entrants and Emerging Players: Mid-market German machinery manufacturers lacking site reliability engineering talent represent the most penetrable entry point, as terabyte-scale operational telemetry gravity anchors private cloud investment but specialized skills scarcity constrains deployment velocity. French health data localization requirements under ANSM guidance create adjacent sovereign cloud demand with EU-controlled encryption key escrow specifications. Go-to-market through managed service provider channels bypasses direct enterprise sales friction. For Investors and Strategic Acquirers: The market sits at a compliance-driven fragmentation phase that favors platform engineering specialists with Kubernetes federation expertise and cross-environment security posture management capabilities. Long-term viability hinges on federation tooling maturity rather than raw infrastructure scale, positioning hyperconverged infrastructure vendors and immutable infrastructure image providers as acquisition targets. Monitor sovereign cloud mandate proliferation across G7 economies as inflection indicator for API compatibility risk and nationally ring-fenced instance demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acceleration | EU Cybersecurity Act frameworks now function as de facto market-access requirements for enterprise procurement. |
| Kubernetes Federation Platform Integration | Cross-cluster orchestration tooling enables genuine workload mobility without vendor lock-in for conservative IT estates. |
| Edge-to-Cloud Orchestration Partnership | 5G network slicing combined with distributed Kubernetes enables real-time manufacturing quality control with centralized model training. |
| Liquid Cooling Infrastructure Investment | REACH chemical restrictions and EU F-Gas Regulation pressure German and Dutch facility operators to phase out sulfur hexafluoride switchgear. |
| Consumption-Based Contract Structuring | Japanese automotive manufacturers pioneered flexible spend agreements now spreading to North American pharmaceutical supply chain operations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cloud architects, platform engineering directors, CISOs, and enterprise procurement officers across financial services and manufacturing verticals, combined with secondary validation against hyperscaler capex disclosures, SEC filings, EU regulatory guidance documents, and ISO certification registries. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure spend tracking.
Forecast inputs span service type, deployment model, organization size, vertical industry, and regional regulatory cluster across the analysis window. CAGRs derive from segment-level growth trajectory analysis incorporating compliance deadline clustering effects, industrial IoT data gravity projections, and sovereign cloud mandate proliferation patterns. Kubernetes federation maturity curves and site reliability engineering talent availability index forecast inputs.
Practitioners should monitor EU AI Act enforcement timelines, China Cybersecurity Law cross-border data friction escalation, and hyperscaler sovereign region buildout announcements for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Philippines ICT Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Public Cloud Market