
 South Korea Coffee Roaster Market | 2026-2036
South Korea Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Coffee Roaster Market Insights
The capital-intensity divergence between automated drum-system manufacturers and manual specialty-equipment producers is reorganizing competitive tiers across South Korea. Probat leverages German engineering heritage to dominate industrial-capacity installations for franchise roasteries. Compose Coffee anchors its expansion through vertical integration into roasting operations, controlling bean sourcing and in-house production simultaneously. Starbucks competes on brand-driven equipment standardization across its Korean store network.
A coffee roaster is a thermal processing machine that applies controlled heat (typically 180–240°C) to green coffee beans through conductive, convective, or radiant energy transfer, inducing Maillard reactions and pyrolysis to develop flavor compounds and volatile aromatics for commercial beverage preparation. Commercial roasters occupy the largest installed base due to nationwide franchise expansion, while specialty roasters capture expanding margin pools as Seoul's Gangnam and Hongdae districts concentrate third-wave cafe openings. Drum technology leads current shipments, though fluid bed systems gain traction among home users seeking reduced smoke emissions and faster roast profiles.
MFDS enforces food contact material and electrical safety standards for commercial roasting equipment, while KTL certification mandates electromagnetic compatibility testing for automated control systems. The Korea Energy Agency's efficiency labeling program pressures manufacturers to reduce per-batch power consumption. Stakeholders must monitor evolving carbon accounting rules and decide whether to prioritize energy recovery systems or modular capacity scaling in upcoming equipment procurement cycles.
Market Dynamics
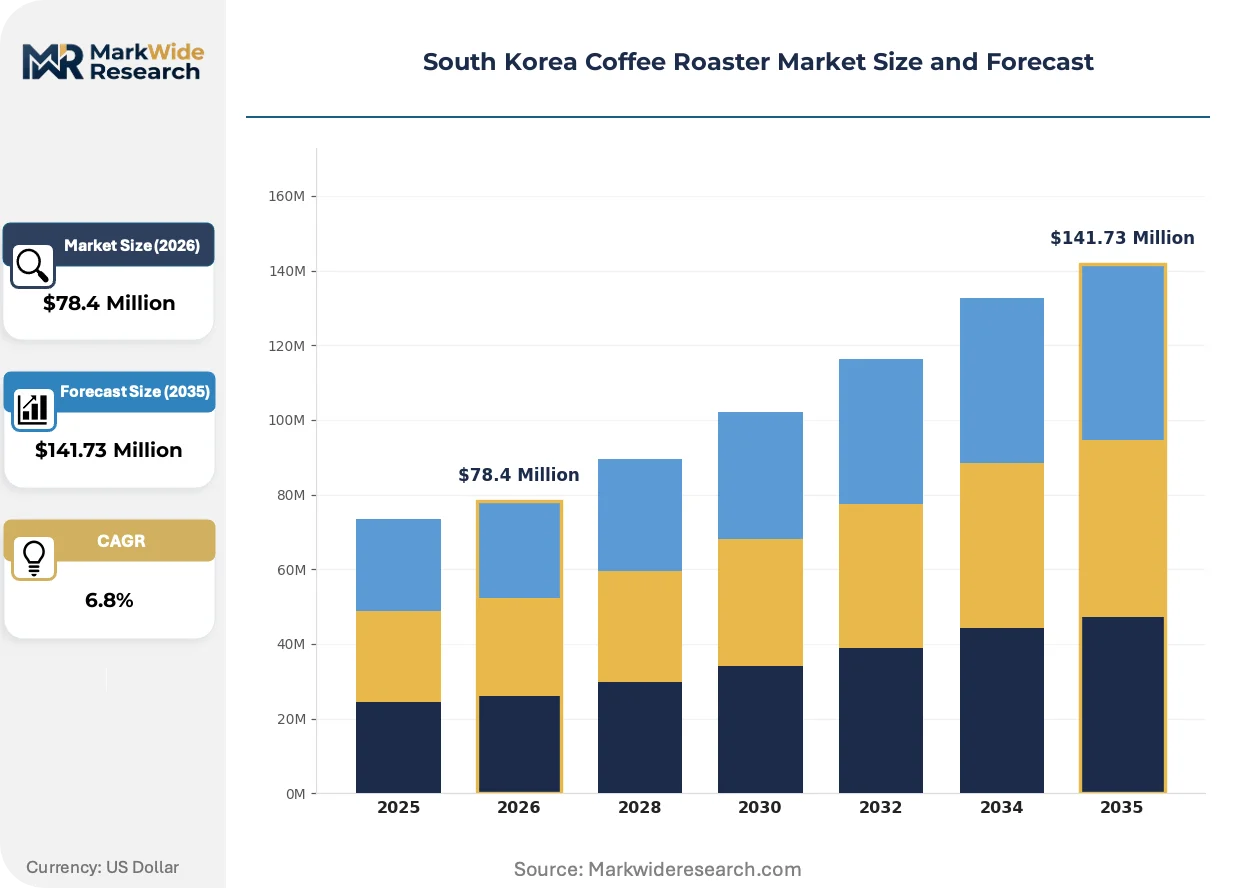
MFDS food safety enforcement and Korea Energy Agency efficiency mandates are compressing equipment design cycles while specialty roasting demand pulls capacity toward smaller-batch systems. This dual pressure is restructuring supplier tiers around certification capability and modular power scaling.
Growth Catalysts
- Third-wave cafe proliferation:Gangnam and Hongdae districts concentrate independent roasting operations demanding precision-controlled drum systems. Equipment vendors capture recurring calibration service contracts.
- MFDS food contact material standards:Mandatory stainless-steel certification for roasting surfaces accelerates replacement cycles in older franchise installations. Compliance documentation becomes a procurement gate.
- Energy efficiency labeling:The Korea Energy Agency's per-batch consumption grading pushes roasteries toward heat-recovery drum designs. Premium ratings unlock utility rebate eligibility.
Market Restraints
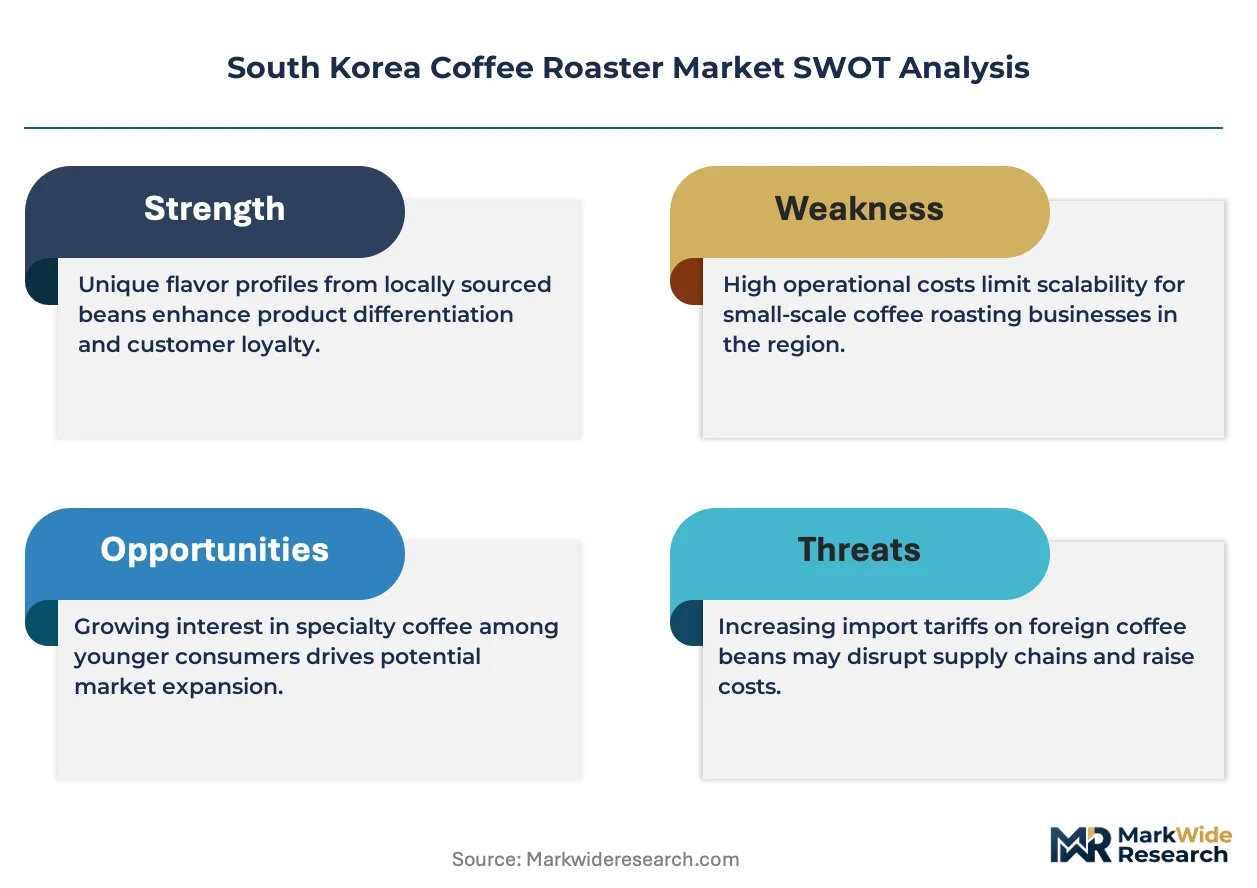
- Specialty green bean price volatility:Ethiopian and Colombian arabica auction fluctuations compress roasting margins. Operators defer capacity expansion during supply squeezes.
- Automated control system import dependency:German and Italian PLC suppliers dominate precision temperature regulation modules. Domestic assemblers face currency exposure and extended lead times.
- Fluid bed system smoke emission limits:Seoul municipal air quality ordinances restrict residential-zone roasting operations. Home-use segment growth hits regulatory ceilings.
Strategic Opportunities
- Busan specialty coffee corridor:Marine City and Haeundae districts underpenetrated versus Seoul saturation. Early equipment positioning captures district-level roasting cooperatives.
- Carbon accounting integration:Korea Exchange KRX disclosure requirements for listed food-service chains create demand for roast-cycle emissions tracking. Sensor-embedded drum systems enable Scope 3 reporting.
- Direct-to-roastery green bean platforms:Digital procurement bypassing traditional importers reshapes equipment financing. Roaster vendors bundle machines with origin-sourcing subscriptions.
Industry Challenges
- Roast master skill scarcity:Artisan profile development requires 2,000+ hour apprenticeship pipelines. Training program throughput latches below cafe opening rates.
- Legacy drum retrofit complexity:Pre-2020 installations lack IoT connectivity for predictive maintenance. Upgrade economics favor full replacement over modular sensor grafting.
- MFDS electrical safety recertification timelines:Annual control system inspections disrupt peak-season roasting schedules. Compliance backlog extends equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Coffee Roaster Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Roasters, Specialty Roasters, Home Roasters, Sample Roasters End User: Cafes, Restaurants, Retailers, Home Users Technology: Hot Air, Drum, Fluid Bed, Infrared Capacity: Small Batch, Medium Batch, Large Batch, Industrial |
| Companies Covered | Mega Coffee, Tim Hortons, Starbucks, Peet's Coffee, Intelligentsia Coffee, Nestle SA, Compose Coffee, Probat, JDE Peets NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Coffee Roaster Market Trends and Innovations
Roasting automation is bifurcating between artisan precision and industrial throughput, with software-defined profile control emerging as the decisive capability differentiator. Equipment architecture is converging on sensor-integrated platforms that bridge manual craft and data-driven repeatability.
Artisan-scale electric drum roasters with sub-5kg batch capacity are fragmenting the entry-level equipment tier. Independent cafe operators in Seoul's Seongsu-dong cluster adopt these systems for menu differentiation. The technology is fragmenting traditional distributor relationships as manufacturers sell direct through origin-trip bundled offerings.
Korea Energy Agency efficiency labeling expansion to commercial kitchen equipment tightens per-roast kilowatt-hour ceilings. Drum insulation and exhaust heat exchanger integration become mandatory design features. Medium-capacity franchise roasteries in Gyeonggi-do province face the steepest retrofit obligations.
Roastery operators now specify equipment through origin-trip participation rather than distributor showroom visits. Guatemala and Ethiopia sourcing journeys bundle machine trials with green bean selection. This behavioral shift concentrates purchase authority with head roasters rather than procurement departments, compressing traditional equipment sales cycles.
South Korea Coffee Roaster Market Segmentation
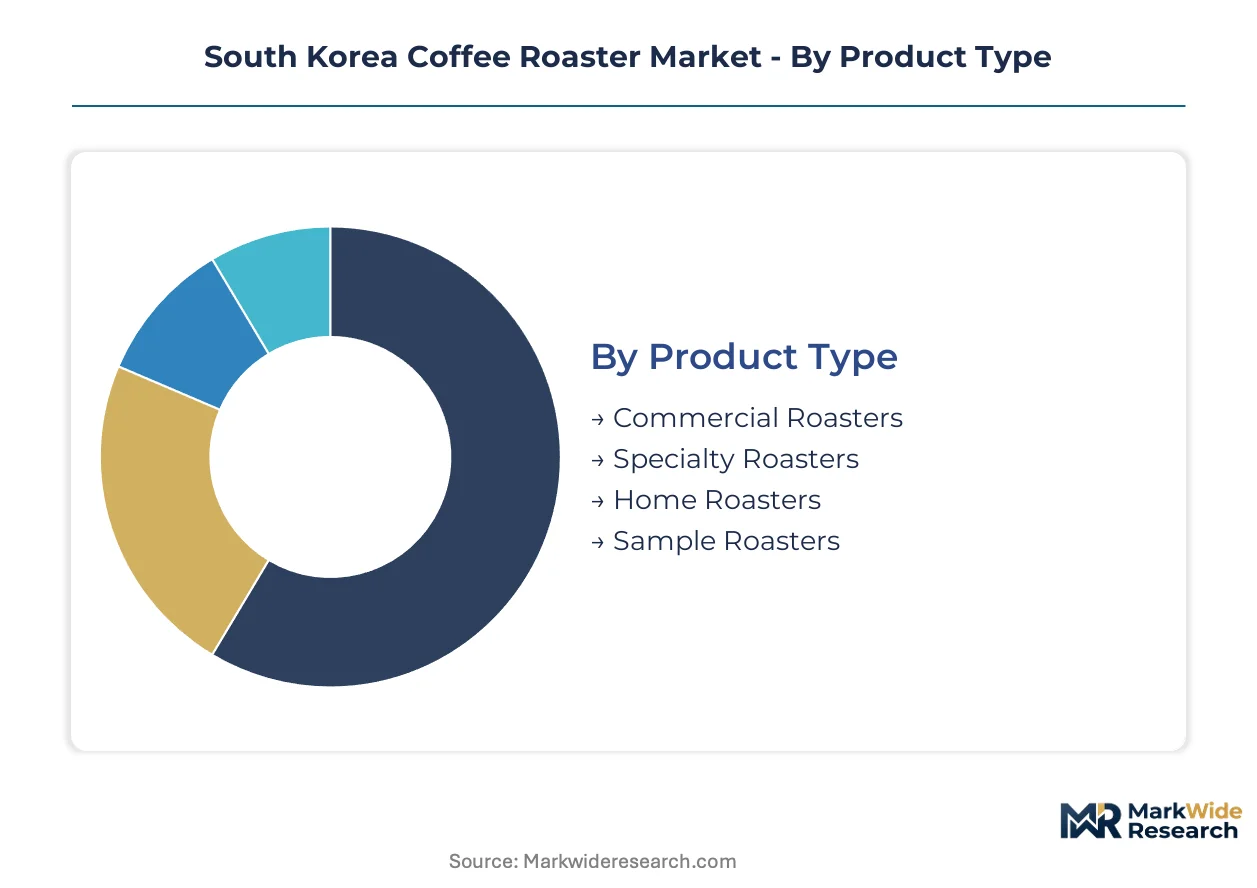
Roaster equipment segmentation in South Korea reflects divergent compliance burdens across installation scales. MFDS certification requirements and Korea Energy Agency efficiency tiers fragment procurement patterns between franchise chains and independent operators.
Product Type:
MFDS food contact material standards impose stainless-steel surface mandates that escalate with batch capacity, creating tiered compliance cost structures.
- Commercial Roasters:Industrial-grade drum systems with 30-120kg batch capacity dominate franchise roastery installations. Seoul-based chains like Ediya and Mega Coffee specify these for centralized production facilities serving 500+ store networks under MFDS annual electrical safety recertification.
- Specialty Roasters:Precision-controlled 5-30kg systems enable profile-repeatability for third-wave cafes. Demand clusters in Gangnam and Hongdae districts where Compose Coffee and independent operators pursue menu differentiation through single-origin roasting programs.
- Home Roasters:Sub-1kg electric drum units target enthusiast consumers. Seoul municipal smoke emission ordinances restrict residential-zone operation, capping segment expansion.
- Sample Roasters:100-500g laboratory-grade systems support green bean procurement decisions. Importers and roasting cooperatives deploy these for pre-purchase cupping validation.
Commercial Roasters handles the majority of throughput; Specialty Roasters is the fastest mover on share.
End User:
Cafe density gradients between Seoul saturation and Busan underpenetration reshape equipment deployment priorities.
- Cafes:Franchise chains and independent third-wave operators drive drum system demand. Gangnam district alone accounts for concentrated specialty equipment installations as operators compete on freshness claims.
- Restaurants:Hotel and fine-dining establishments adopt compact 3-5kg systems for post-meal coffee service. Busan's Marine City hospitality corridor shows emerging demand as tourism infrastructure expands.
- Retailers:Supermarket chains and department stores install medium-capacity roasters for in-store freshness theater. Lotte and Shinsegae specifications emphasize energy efficiency labeling compliance.
- Home Users:Enthusiast segment constrained by ventilation requirements and apartment-dwelling demographics. Online communities drive fluid bed system preference for reduced smoke output.
Cafes deploy the largest installed base; Retailers are expanding most quickly as grocery freshness competition intensifies.
Technology:
Heat transfer mechanism selection trades off between roast profile control precision and regulatory emission compliance.
- Drum:Conductive-convective rotating barrel systems remain the Korean market standard. Probat and domestic assemblers dominate with MFDS-certified stainless-steel contact surfaces and integrated heat recovery for efficiency labeling compliance.
- Fluid Bed:Hot air suspension roasting reduces smoke emissions and enables faster roast cycles. Home users and small cafes in Seoul's dense districts favor these for municipal air quality ordinance compliance.
- Hot Air:Convective-only systems occupy entry-tier positioning. Limited temperature control precision restricts adoption beyond price-sensitive initial equipment purchases.
- Infrared:Radiant heat transfer enables rapid profile modulation. Niche adoption among artisan roasters pursuing experimental processing methods.
Drum technology commands dominant share; Fluid Bed systems gain share fastest on regulatory tailwinds.
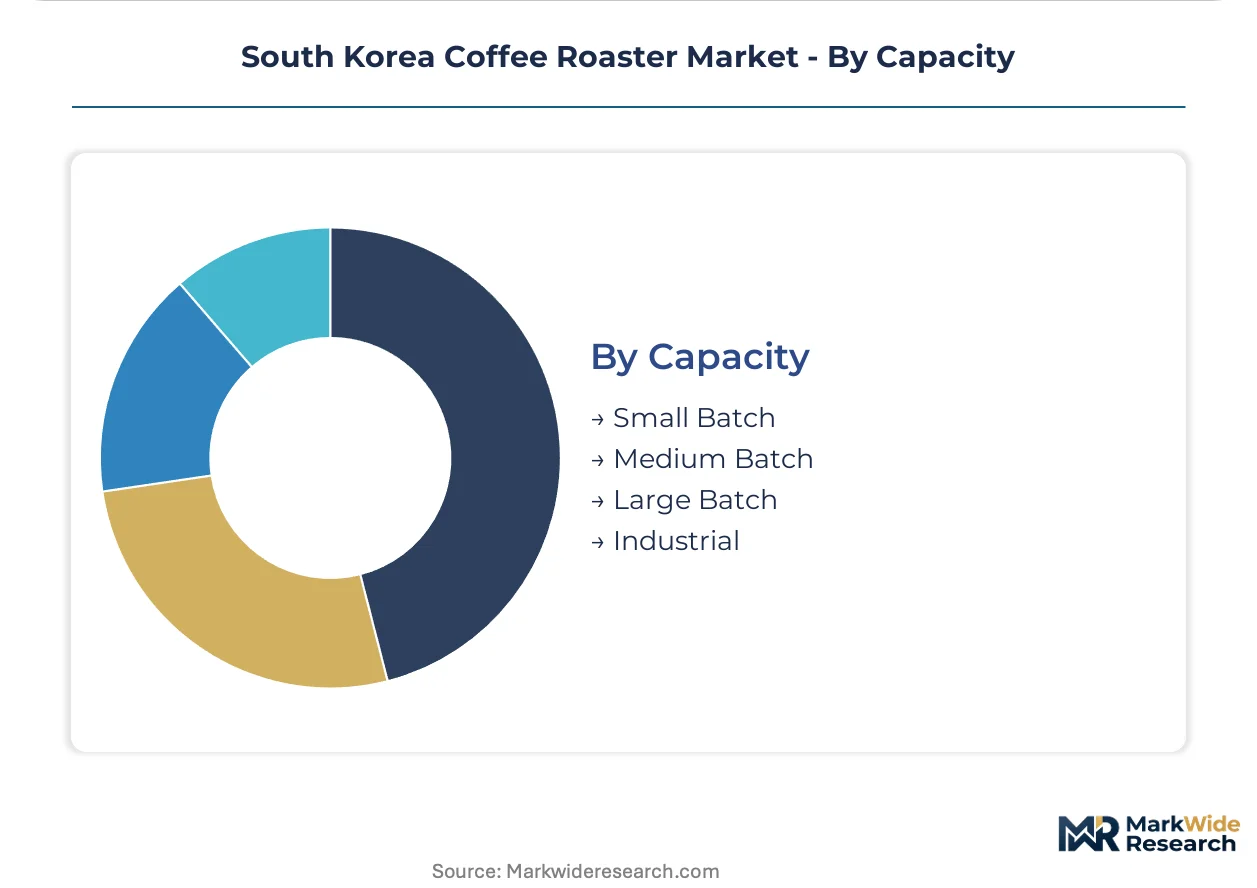
Capacity:
Korea Energy Agency per-batch consumption grading creates divergent retrofit economics across scale tiers.
- Large Batch:60-120kg systems serve centralized production for national franchise networks. Gyeonggi-do province hosts concentrated installations where efficiency labeling mandates drive heat exchanger retrofits.
- Medium Batch:15-60kg range captures regional roastery and large independent cafe demand. Steepest efficiency compliance burden as pre-2020 installations face replacement economics.
- Small Batch:1-15kg systems enable location-specific roasting for single-store operators. Seongsu-dong cluster shows dense adoption for menu differentiation.
- Industrial:120kg+ continuous-flow systems for export-oriented processing. Limited domestic demand given Korean market consumption orientation.
Medium Batch capacity carries the heaviest regulatory compliance load; Small Batch shows the steepest expansion trajectory on cafe proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Seoul's saturated cafe corridors show low price elasticity for precision equipment, while regional franchise operators in secondary metros remain highly sensitive to per-unit capital outlays. This demand-elasticity contrast shapes divergent equipment procurement patterns across South Korea's sub-regional markets.
Seoul Capital Area
Gangnam and Hongdae districts concentrate third-wave cafe openings demanding sub-5kg precision drum systems. MFDS food contact material standards enforce stainless-steel certification for all roasting surfaces. Seongsu-dong's artisan cluster anchors direct-to-manufacturer procurement, bypassing traditional distributor channels.
Busan-Ulsan
Marine City and Haeundae hospitality corridors show underpenetrated specialty coffee infrastructure versus Seoul saturation. Korea Energy Agency efficiency labeling applies uniformly, yet compliance timelines lag 12-18 months behind capital-region adoption. Busan's roasting cooperatives favor medium-batch heat-recovery systems for district-level supply.
Daegu-Gyeongbuk
Regional franchise networks drive commercial roaster demand with price-sensitive procurement criteria. MFDS electrical safety recertification creates operational downtime pressures during peak harvest seasons. Daegu's industrial zones host concentrated pre-2020 drum installations facing steep retrofit economics.
Daejeon-Sejong
Government district proximity elevates carbon accounting transparency requirements for cafe chains. Korea Exchange KRX disclosure rules for listed food-service operators extend to Scope 3 roast-cycle emissions tracking. Sejong's emerging cafe density favors sensor-embedded equipment enabling regulatory reporting.
Gwangju-Honam
Agricultural hinterland positioning supports green bean storage and pre-processing infrastructure. Honam region's lower commercial rent structures attract roasting cooperatives seeking cost-advantaged production. Gwangju's cafe market remains nascent, with equipment demand concentrated in sample-roaster categories for importer validation.
South Korea Coffee Roaster Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with franchise-owned roasting operations controlling centralized capacity while independent equipment vendors fragment across artisan-scale segments. The competitive structure bifurcates between industrial-scale drum system providers and precision-focused specialty manufacturers. Three archetypes dominate: German-engineering heritage brands, domestic cafe chains with captive roasting operations, and Korean equipment assemblers sourcing control systems abroad. M&A activity concentrates on vertical integration into green bean sourcing, while technology licensing agreements proliferate for automated profile control modules.
Among heritage European manufacturers, Probat anchors the industrial-capacity tier with engineering credibility for franchise-scale installations. Within Korea's integrated cafe segment, Compose Coffee exemplifies backward integration into roasting operations, controlling bean sourcing and in-house production simultaneously. Starbucks occupies a position defined by brand-driven equipment standardization across its Korean store network.
| Leading Market Players |
|---|
| Mega Coffee |
| Tim Hortons |
| Starbucks |
| Peet's Coffee |
| Intelligentsia Coffee |
| Nestle SA |
| Compose Coffee |
| Probat |
| JDE Peets NV |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for German-engineered control modules from Siemens and Beckhoff concentrate pricing power with European PLC suppliers, while domestic assemblers absorb currency exposure through inventory pre-positioning. This temporal compression rewards roasteries that lock annual service contracts before Won-Euro volatility spikes.
Pricing Analysis
After-sales service contracts covering calibration, spare parts, and predictive maintenance software generate lifetime value exceeding initial equipment margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels segments by automation grade and MFDS certification tier. Pricing pressure stems from Korean equipment assemblers undercutting European heritage brands on upfront capital outlays. Franchise chains show lowest price sensitivity for precision-controlled systems, while independent cafe operators in secondary metros defer purchases during green bean price squeezes.
Supply Chain Analysis
Inventory pre-positioning for 12-16 week PLC lead times strains working capital for domestic assemblers sourcing temperature regulation modules from Germany and Italy. Stainless steel contact surfaces draw from POSCO's domestic mills, while precision bearings and heating elements feed from Japanese and German suppliers. Single-source vulnerability concentrates in automated profile control software licensing. Distribution runs through manufacturer-direct channels for artisan-scale equipment and authorized distributor networks for industrial-capacity installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea coffee roaster market functions as a defensive-moat story anchored in MFDS regulatory entrenchment, where certification documentation creates procurement gates that incumbent suppliers exploit to lock out unqualified competitors.
For Market Incumbents: Secure recurring calibration service contracts before Won-Euro volatility intensifies, locking multi-year relationships that compound switching costs for franchise operators. Deepen backward integration into green bean sourcing platforms to capture margin pools that emerging roastery cooperatives threaten. Prioritize heat-recovery drum retrofits for Gyeonggi-do's pre-2020 installed base, converting compliance burdens into captive upgrade revenue.
For New Entrants and Emerging Players: Lead with sensor-embedded drum systems enabling KRX carbon disclosure compliance, targeting Sejong's government-district cafe chains where regulatory reporting creates urgent procurement windows. Capture Busan's Marine City hospitality corridor before efficiency labeling timelines converge with Seoul standards, exploiting 12-18 month compliance lag for first-mover positioning. Bundle equipment trials with origin-trip participation to displace traditional distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because MFDS certification requirements and Korea Energy Agency efficiency mandates compound incumbent advantages faster than artisan demand fragments the market. Target domestic equipment assemblers with established KTL electromagnetic compatibility testing relationships and scalable sensor-integration capabilities. Watch fluid bed system share acceleration in Seoul's dense districts as the signal for whether municipal air quality enforcement will reshape technology mix.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery System Integration | Korea Energy Agency premium ratings unlock utility rebates for Gyeonggi-do franchise operators. |
| Sensor-Embedded Drum Retrofit | Scope 3 emissions tracking satisfies KRX disclosure requirements for listed food-service chains. |
| Origin-Trip Bundled Procurement | Guatemala and Ethiopia sourcing journeys compress equipment sales cycles through head roaster authority. |
| Calibration Service Contract Expansion | Recurring revenue streams compound switching costs for Ediya and Mega Coffee franchise networks. |
| Fluid Bed System Regulatory Positioning | Seoul municipal smoke ordinances create technology substitution windows for residential-zone operators. |
Research Methodology
The analysis maps commercial drum systems, specialty precision roasters, fluid bed alternatives, and sample laboratory units, each validated through head roasters at franchise chains, independent cafe operators, equipment procurement managers, and MFDS compliance officers. Primary fieldwork combined structured interviews with secondary validation against Korea Energy Agency efficiency labeling databases, MFDS electrical safety certification registries, and customs import records for German and Italian control modules. Bottom-up equipment shipment tallies triangulated against top-down cafe opening rates and franchise network expansion disclosures.
Consistency checks validated volume and value outputs against external benchmarks including roastery capacity utilization surveys and green bean import volume correlations. The analytical framework modeled segmentation across product type, end user category, heat transfer technology, and batch capacity tier throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and third-wave cafe penetration rates in Gangnam and Hongdae districts.
Forecasts assume regulatory continuity in MFDS food contact material standards and Korea Energy Agency efficiency labeling regimes; material policy shifts would require re-modeling. Specific risks include Ethiopian and Colombian arabica supply squeezes deferring capacity expansion, and Won-Euro volatility compressing margins for PLC-dependent domestic assemblers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee and Tea Capsule Market
Coffee
High Protein Coffee Market
Coffee
Portable Espresso Machines Market
Coffee
Organic Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Canned Coffee Market
Coffee
Singapore Coffee Roaster Market
Coffee
Chewable Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Coffee Bags Market
Coffee
Reusable Coffee Cup Market
Coffee
Coffee Premixes Market
Coffee
US Instant Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Germany Coffee Market