
 Ready to Drink (RTD) Coffee Market | 2026-2036
Ready to Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink (RTD) Coffee Market Intelligence
Vietnam is reshaping raw coffee sourcing dynamics through aggressive arabica and robusta processing expansion. Nestlé S.A. leverages its Nescafé manufacturing footprint across multiple continents to sustain cost advantages in soluble-based RTD lines. Starbucks Corporation anchors premium positioning through its chilled espresso portfolio in North American grocery channels. The Coca-Cola Company competes via its Costa Coffee acquisition integration and fountain-style RTD distribution muscle.
Ready to Drink (RTD) Coffee denotes pre-brewed, packaged coffee beverages preserved through pasteurization, aseptic filling, or refrigeration, typically containing 75–200 mg caffeine per serving and shelf lives ranging from 21 days for refrigerated products to 12 months for ambient-stable formulations. Cold Brew dominates product type segments due to smoother acidity profiles and extended shelf stability, while Nitro Coffee captures fastest-growing status through nitrogen-infusion texture differentiation. Cans lead packaging type segments by volume owing to aluminum recyclability and chilled logistics compatibility, though Tetra Paks command margin pools in Asian ambient-distribution corridors.
FDA governs caffeine disclosure and GRAS additive thresholds for US-formulated RTD coffee, while EU Green Deal packaging mandates and REACH chemical compliance shape European material sourcing decisions. Japan's Ministry of Health, Labour and Welfare sets residual pesticide limits on imported coffee extracts that directly affect supplier qualification protocols. Stakeholders must monitor evolving sugar-tax jurisdictions and deposit-return scheme expansions to anticipate reformulation investments and packaging redesign cycles.
Market Dynamics
Refrigerated supply chain densification is compressing distribution economics for ambient-stable RTD coffee formats. Cold chain infrastructure investments by convenience retailers are tilting shelf allocation toward chilled single-serve units.
Growth Catalysts
- EU Green Deal packaging mandates:Aluminum can recyclability quotas accelerate material substitution from plastic bottles in European retail channels.
- Vending machine network expansion:Japan's urban office corridors sustain high-velocity consumption through automated point-of-sale density.
- Cold Brew processing technology:Extended ambient shelf stability without thermal degradation reduces logistics costs for ambient distribution networks.
Market Restraints
- Arabica price volatility:Brazilian weather shocks transmit directly to formulation cost structures for premium RTD lines.
- Vietnamese robusta concentration:Single-origin dependency for soluble coffee extracts creates geographic supply risk.
- FDA added sugar disclosure rules:Reformulation timelines compress product development cycles for sweetened variants.
Strategic Opportunities
- Indian urban convenience retail:Organized grocery expansion in Mumbai and Delhi creates channel access for chilled RTD entrants.
- Nitrogen-infusion technology:Texture differentiation commands price premiums in North American specialty coffee segments.
- Japan's residual pesticide limits:Supplier qualification barriers create first-mover advantage for certified clean-label extractors.
Industry Challenges
- Aseptic filling technician scarcity:Specialized pasteurization equipment operation requires training pipelines that outpace labor market supply.
- Dual certification complexity:Organic and Fair Trade simultaneous qualification extends procurement timelines by 8-14 months.
- Legacy ERP integration:Cold chain traceability modules conflict with ambient-distribution software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink (RTD) Coffee Market |
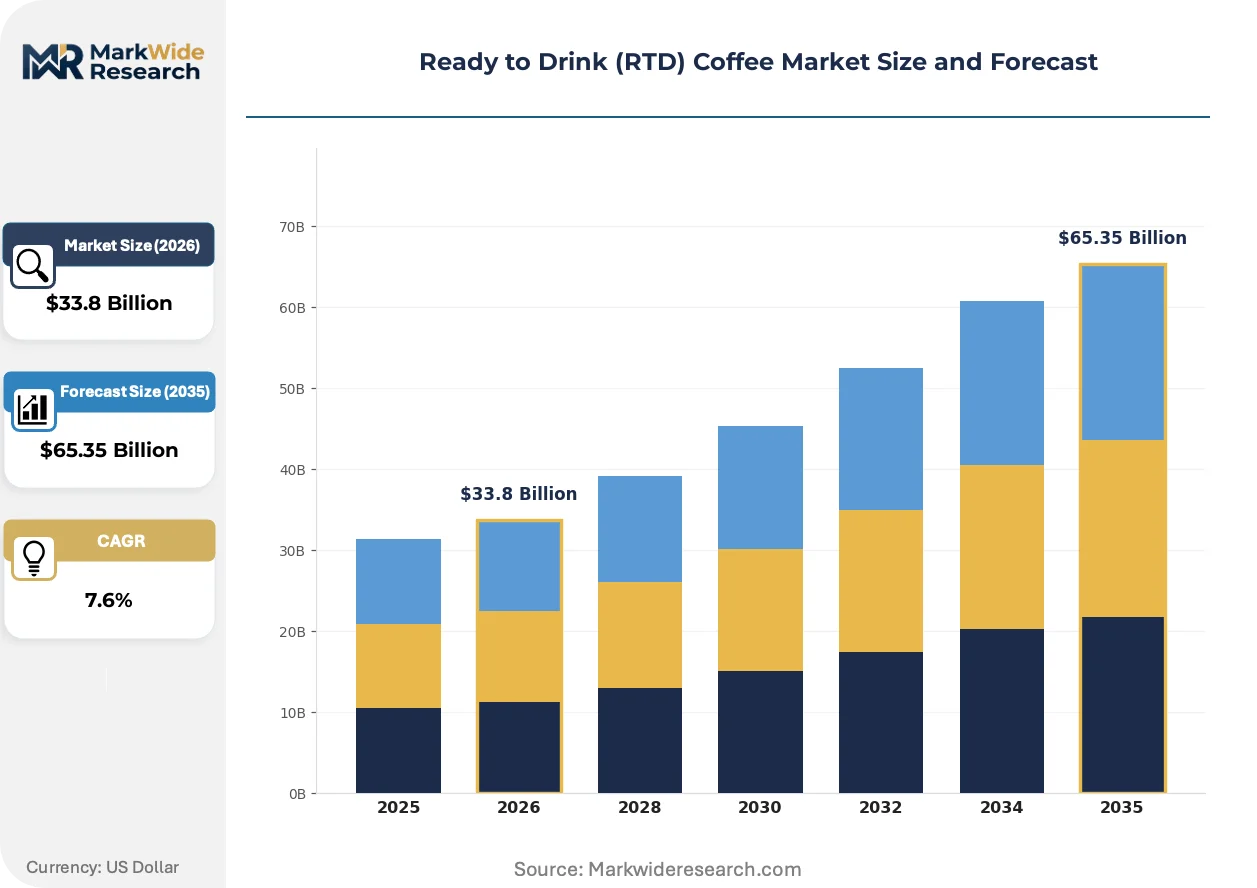
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $65.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Brew, Espresso, Nitro Coffee, Iced Latte Packaging Type: Cans, Bottles, Tetra Paks, Cartons Flavor Profile: Vanilla, Mocha, Caramel, Hazelnut Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Cafes |
| Companies Covered | Suntory Beverage & Food Limited, Danone S.A., Nestlé S.A, Starbucks Corporation, Asahi Group Holdings, The Coca-Cola Company, Keurig Dr Pepper Inc., UCC Ueshima Coffee Co., PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink (RTD) Coffee Market Strategic Shifts & Innovations
Formulation science is converging with packaging engineering to extend shelf life without sacrificing sensory quality. This convergence is compressing the traditional trade-off between convenience and taste authenticity.
Nitrogen-infusion systems for canned coffee is hybridizing texture engineering with ambient stability protocols. Premium buyers in Japanese convenience channels are adopting nitrogenated formats at triple the rate of standard cold brew. This hybridization is enabling price stratification that separates commodity RTD from specialty-tier positioning.
REACH chemical compliance for can linings is forcing coating reformulation across European manufacturing footprints. Bisphenol-A replacement candidates face migration testing delays that extend new product introduction timelines. Ready-to-drink brands with established EU supply partnerships are absorbing compliance costs faster than import-dependent competitors.
Subscription direct-to-home replenishment is displacing impulse grocery purchases for habitual RTD consumers. North American urban millennials are consolidating monthly coffee procurement into curated delivery boxes. This channel rotation is most visible in Seattle and Austin metro clusters where delivery density supports cold chain unit economics.
Ready to Drink (RTD) Coffee Market Segmentation
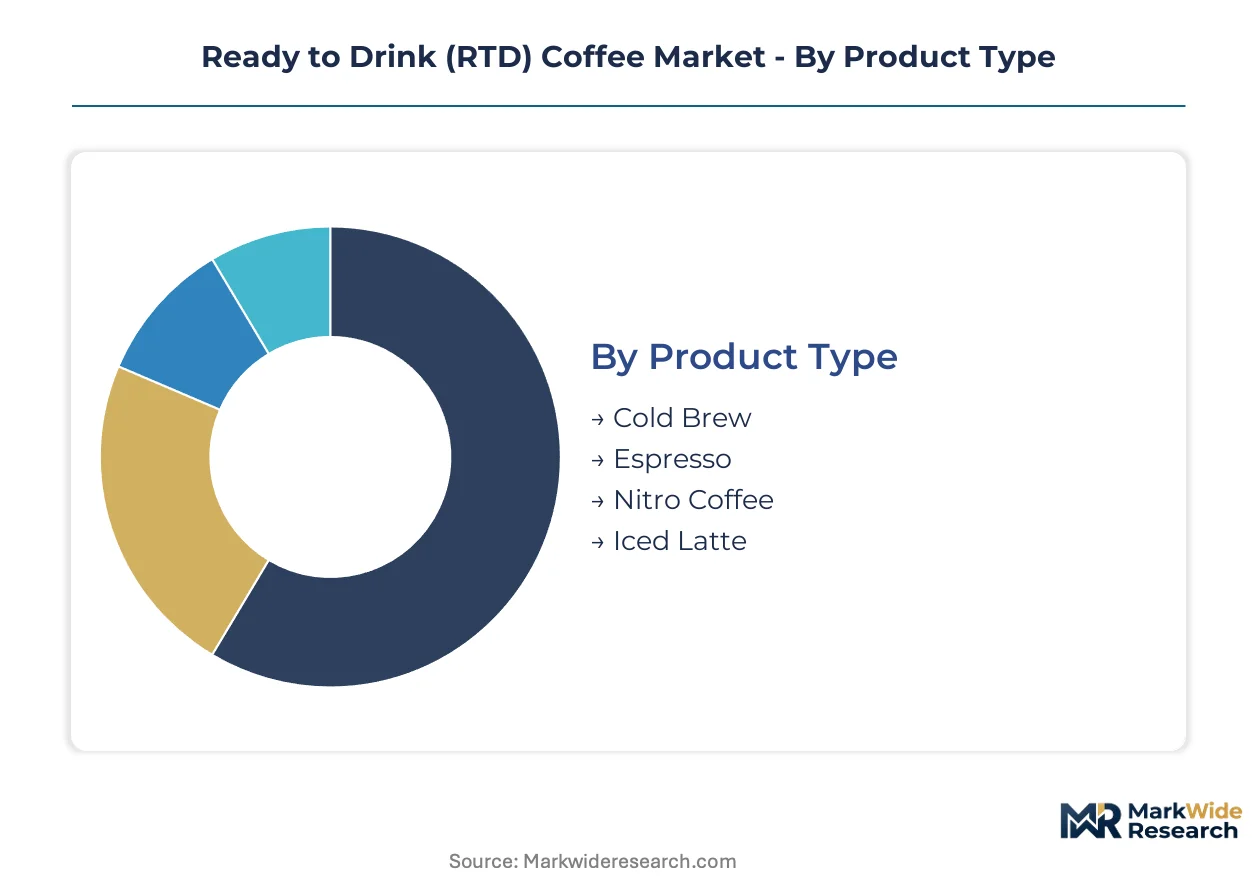
RTD coffee segmentation reflects divergent velocity economics across temperature-controlled versus ambient-stable supply chains. Cold chain density in urban corridors favors formats with shorter shelf lives and premium positioning, while ambient distribution networks reward extended stability protocols that compress logistics costs.
Product Type:
Cold Brew commands the longest production cycle at 12-24 hours steep time, while Espresso formats turn fastest through thermal extraction systems that complete batch processing in minutes.
- Cold Brew:Extended ambient steeping at refrigerated temperatures extracts lower-acidity compounds that reduce bitterness perception. Japanese vending networks and North American convenience chains concentrate demand for shelf-stable variants that bypass refrigeration requirements. Cold Brew dominates installed base. Nitro Coffee is where expansion concentrates.
- Nitro Coffee:Nitrogen gas infusion at 30-40 psi creates cascading micro-bubble texture that differentiates from standard carbonation. Specialty grocers in Austin and Seattle metro clusters are adopting nitrogenated cans at triple the velocity of conventional cold brew.
- Espresso:Thermal pressure extraction preserves crema-equivalent mouthfeel through emulsion stabilization in UHT processing lines.
- Iced Latte:Dairy or alternative protein integration requires aseptic blending protocols that extend formulation complexity but capture habitual milk-coffee consumers.
Espresso dominates installed base. Nitro Coffee is where expansion concentrates.
Packaging Type:
Cost tier stratification separates aluminum can commodity positioning from Tetra Pak premium corridors in ambient Asian distribution.
- Cans:Aluminum recyclability aligns with EU Green Deal mandates that accelerate material substitution from plastic substrates. European retailers are consolidating shelf allocation behind can formats that satisfy deposit-return scheme compliance. Cans dominate installed base. Tetra Paks are where expansion concentrates.
- Tetra Paks:Aseptic carton technology enables 12-month ambient stability without refrigeration infrastructure. Southeast Asian ambient-distribution corridors concentrate margin capture for Tetra Pak formats that bypass cold chain investments.
- Bottles:PET and glass substrates retain visibility in café fountain dispensing systems where consumption is immediate.
- Cartons:Gable-top refrigerated cartons serve institutional foodservice channels with bulk-format economics.
Cans dominate installed base. Tetra Paks are where expansion concentrates.
Flavor Profile:
Application context drives flavor selection — vanilla and caramel anchor habitual daily consumption, while mocha and hazelnut concentrate in indulgence-oriented occasions.
- Vanilla:Natural and synthetic vanillin formulations balance cost against clean-label positioning demands. FDA added sugar disclosure rules are compressing reformulation timelines for vanilla-sweetened variants that dominate volume.
- Mocha:Cocoa solids integration requires dual-supplier qualification for coffee and chocolate extract sourcing that extends procurement cycles.
- Caramel:Maillard-reaction flavor systems create color stability challenges under UV exposure in transparent packaging.
- Hazelnut:Nut allergen labeling requirements in US and EU jurisdictions add compliance layer to formulation documentation.
Vanilla dominates installed base. Mocha is where expansion concentrates.
Distribution Channel:
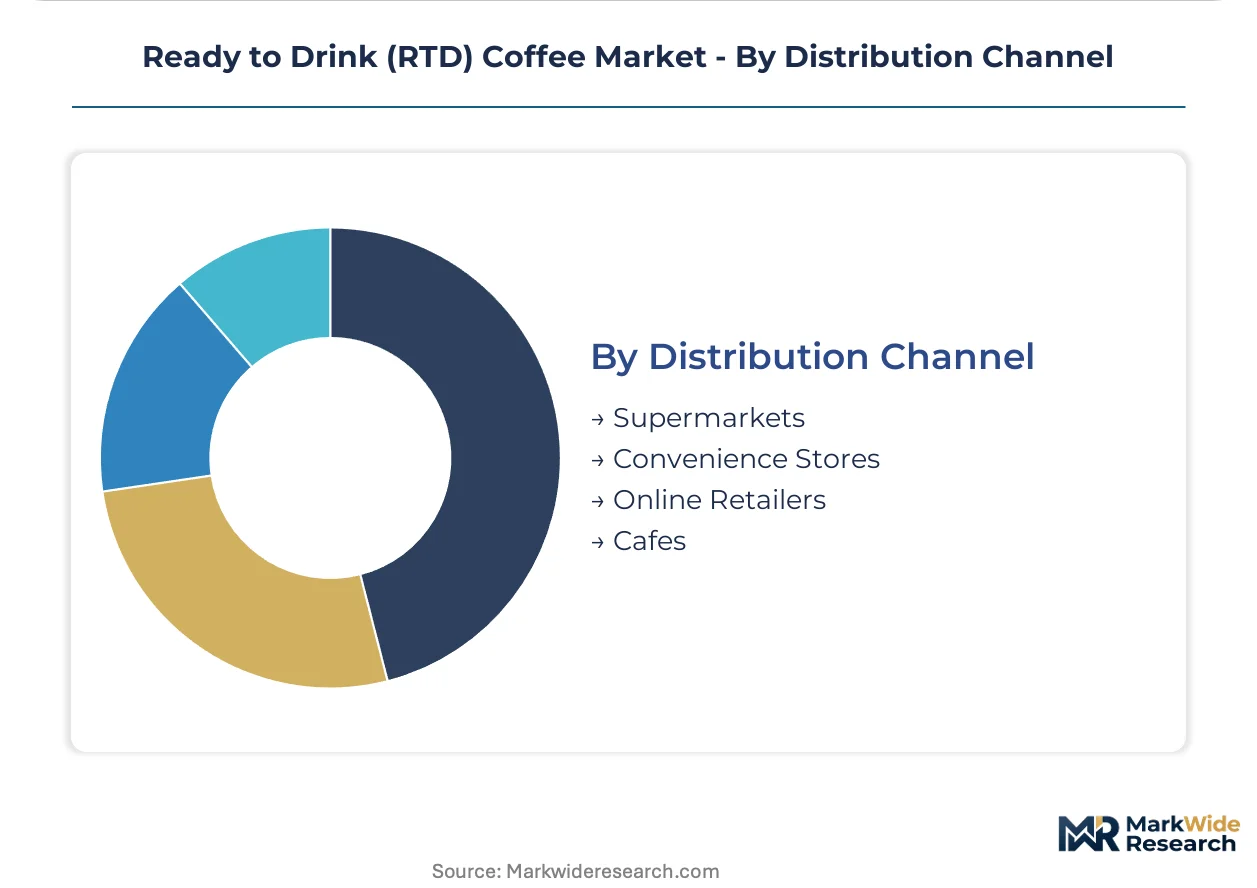
Customer type stratification separates impulse convenience purchasers from subscription-driven habitual replenishment patterns.
- Convenience Stores:Chilled single-serve unit velocity depends on cold chain infrastructure density that tilts shelf allocation toward refrigerated formats. 7-Eleven and Lawson chains across Japan and the US are expanding cooler door space for RTD coffee.
- Online Retailers:Direct-to-home subscription consolidation among North American urban millennials displaces impulse grocery procurement. Seattle and Austin delivery density supports cold chain unit economics for curated monthly boxes.
- Supermarkets:Grocery channel concentration favors multi-pack formats that optimize household stock-up economics.
- Cafes:Immediate-consumption fountain dispensing captures premium per-ounce pricing through experiential preparation theater.
Supermarkets dominate installed base. Online Retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese robusta processing expansion and Japanese vending machine density concentrate raw material flows and consumption velocity in distinct regional poles. Brazil's arabica belt transmits weather volatility directly into formulation cost structures worldwide. Cold chain infrastructure investments in North American convenience retail and European aluminum recyclability mandates reshape distribution economics across temperate zones.
United States
Convenience store chains expand refrigerated shelf space for single-serve chilled units, with 7-Eleven and regional operators densifying cooler door allocation. FDA added sugar disclosure rules compress reformulation timelines for sweetened vanilla and caramel variants. Seattle and Austin metro clusters anchor subscription direct-to-home replenishment velocity among urban millennials.
Japan
Office corridor vending machine networks sustain high-velocity consumption through automated point-of-sale density unmatched elsewhere. Ministry of Health, Labour and Welfare residual pesticide limits on imported coffee extracts create supplier qualification barriers for clean-label extractors. Tokyo and Osaka metropolitan areas concentrate demand for nitrogen-infusion texture differentiation in convenience channels.
Germany
EU Green Deal aluminum can recyclability quotas accelerate material substitution from plastic substrates across retail channels. REACH chemical compliance for can linings forces coating reformulation across manufacturing footprints, extending new product introduction timelines. Bavaria and North Rhine-Westphalia industrial corridors absorb compliance costs faster than import-dependent competitors.
Vietnam
Aggressive arabica and robusta processing expansion reshapes raw coffee sourcing dynamics for soluble-based RTD lines. Central Highlands growing regions concentrate single-origin dependency risk for global extract supply. Da Nang and Ho Chi Minh City processing clusters scale capacity to capture downstream value from commodity bean exports.
India
Organized grocery expansion in Mumbai and Delhi creates channel access for chilled RTD entrants targeting urban convenience retail. FSSAI labeling requirements for caffeine content and additive thresholds shape domestic formulation standards. Karnataka's coffee-growing regions supply raw material inputs while metropolitan consumption concentrates in Western and Southern urban corridors.
Ready to Drink (RTD) Coffee Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in extract processing and aseptic filling equipment. The vendor base stratifies across beverage conglomerates with multi-continent manufacturing footprints, regional coffee specialists with origin-controlled supply relationships, and private-label contractors serving retail channel exclusives. Three archetypes dominate: soluble-based scale players, cold brew premium differentiators, and vending-network operators. Competitive moves concentrate on vertical integration into raw material sourcing and nitrogen-infusion technology licensing.
Among Japan-based beverage conglomerates, Suntory Beverage & Food Limited and UCC Ueshima Coffee Co., Ltd. exemplify the vending-network operator archetype through decades of automated point-of-sale infrastructure deployment. Swiss-domiciled Nestlé S.A. occupies a position representing soluble-based scale players with multi-continent manufacturing footprints. Within the North American premium tier, Starbucks Corporation anchors specialty positioning through chilled espresso portfolio development. Atlanta-based The Coca-Cola Company sits within the beverage conglomerate archetype following Costa Coffee acquisition integration.
| Leading Market Players |
|---|
| Suntory Beverage & Food Limited |
| Danone S.A. |
| Nestlé S.A |
| Starbucks Corporation |
| Asahi Group Holdings |
| The Coca-Cola Company |
| Keurig Dr Pepper Inc. |
| UCC Ueshima Coffee Co. |
| PepsiCo, Inc. |
| Others |
Cost & Logistics Intelligence
Brazilian arabica price volatility determines both pricing tier spreads and supply chain shape, compressing margins for premium cold brew lines while accelerating Vietnamese robusta sourcing for soluble-based economy tiers. This commodity exposure forces simultaneous reformulation investments and geographic diversification across the three-tier pricing structure.
Pricing Analysis
FDA added sugar disclosure rules dictate the pricing tier structure across sweetened RTD variants, separating clean-label premium positioning from reformulation-delayed standard tiers. Three-tier pricing structure across premium, standard, and economy levels rests on certification grade and cold chain density as primary differentiation drivers. Cost compression in the standard tier is intensifying because vanilla and caramel reformulation timelines compress product development cycles. Subscription-driven urban millennials exhibit lowest price sensitivity, while convenience store impulse purchasers in price-competitive corridors show highest elasticity.
Supply Chain Analysis
EU REACH chemical compliance for can linings restricts coating technology flows, forcing Bisphenol-A replacement candidates through extended migration testing protocols. Raw coffee extraction draws from Vietnam, Brazil, and Colombia as primary geographic concentrations, with soluble-grade robusta and premium arabica as core input dependencies. Single-source vulnerability concentrates in Vietnamese robusta processing for Nestlé-scale soluble operations. Distribution runs through chilled convenience retail networks in North America and ambient-stable Tetra Pak corridors across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitrogen-infusion technology represents a high-growth disruption, with texture differentiation commanding price premiums that justify equipment investment despite compressed development timelines.
For Market Incumbents: Insulate premium positioning through captive supply of certified clean-label extracts that satisfy Japan's residual pesticide limits. Accelerate backward integration into Central Highlands growing regions to hedge Vietnamese robusta concentration risk. Channel control through exclusive 7-Eleven and Lawson cooler door contracts defends velocity against private-label encroachment.
For New Entrants and Emerging Players: Pursue white-space opportunity in Indian organized grocery expansion across Mumbai and Delhi metropolitan corridors. Nitro Coffee texture differentiation in North American specialty channels offers the most penetrable premium tier entry point. Direct-to-home subscription bundling with Austin and Seattle delivery density provides defensible go-to-market economics.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors aseptic filling equipment specialists with nitrogen-infusion licensing capabilities. Long-term viability hinges on cold chain infrastructure densification outpacing ambient-stable format cost advantages. Watch EU Green Deal aluminum recyclability quota acceleration as the inflection signal for material substitution investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Nitrogen-Infusion Technology Licensing | Texture differentiation commands triple-velocity adoption in Japanese convenience channels. |
| Backward Integration into Vietnamese Processing | Captive robusta supply hedges geographic concentration risk for soluble extractors. |
| Clean-Label Certification Investment | Japan's Ministry of Health residual pesticide limits create first-mover supplier barriers. |
| Cold Chain Distribution Expansion | 7-Eleven and Lawson cooler door densification tilts shelf allocation toward chilled units. |
| Direct-to-Consumer Subscription Launch | Seattle and Austin delivery density supports curated replenishment box economics. |
Research Approach
The analysis maps cold brew, nitro coffee, espresso, and iced latte sub-sectors, each validated through formulation scientists, aseptic filling technicians, and convenience retail category buyers. Primary interviews with supply chain planners and nitrogen-infusion equipment specialists combined with secondary validation from FDA labeling guidance, EU REACH compliance databases, and Nielsen retail audit data. Bottom-up volume triangulation across packaging formats and top-down value reconciliation anchored the segmentation framework.
Assumption sets held cold chain infrastructure investment rates and arabica futures volatility bands fixed across the projection horizon while varying regulatory enforcement timelines and vending machine network expansion scenarios. Segmentation dimensions modeled include product type, packaging substrate, flavor profile, and distribution channel temperature requirements. CAGRs derived from velocity-weighted shelf space allocation trends and subscription channel penetration curves, with nitrogen-infusion adoption rates and Tetra Pak ambient corridor expansion as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates and EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding convenience retail cooler door expansion and Japanese vending network density. Material shifts in FDA added sugar disclosure enforcement timelines or REACH chemical compliance acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Mushroom Coffee Market
Coffee
Coffee Extracts Market
Coffee
Global Coffee Machine Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
Adaptogen Coffee Market
Coffee
Coffee Syrup Market
Coffee
Coffee and Tea Capsule Market
Coffee
Coffee Beans Market
Coffee
Coffee Crystal Market
Coffee
Coffee Fruit Extract Market
Coffee
Roast to Order Coffee Market
Coffee
Espresso Powder Market
Coffee
Freeze Dried Coffee Market