
 Global Coffee Market | 2026-2036
Global Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coffee Market Analysis
Brazil's Cerrado mechanization is rewriting arabica supply economics for the decade ahead. Nestlé S.A. anchors its position through backward integration into agronomy services across Minas Gerais. Starbucks Corporation extends its vertical control via farmer support centers in Rwanda and Costa Rica. JDE Peet's Coffee and Tea leverages dual roasting networks across Amsterdam and São Paulo to sustain European freshness standards.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora (Robusta) species, typically processed through wet or dry milling to achieve 10-12% moisture content prior to roasting at 180-220°C for flavor development. Arabica commands premium positioning in specialty retail due to complex acidity profiles, while Robusta dominates instant coffee manufacturing and espresso blending for crema stability. The HoReCa end user segment captures the highest margin pools as out-of-home consumption commands per-cup premiums unattainable in supermarket channels. Online distribution is displacing traditional grocery velocity for subscription specialty roasters, though supermarkets retain volume leadership in emerging markets.
The EU Deforestation Regulation and FDA food safety standards collectively tighten traceability requirements from farm to roast. EUDR geolocation mandates force exporters to document polygon coordinates for all supplying plots, raising compliance costs for smallholder-dependent origins. REACH chemical residue thresholds affect post-harvest processing inputs across European import channels. Stakeholders must decide whether to absorb traceability investments or redirect sourcing toward certified cooperative structures that pre-consolidate farm-level data.
Market Dynamics
The EU Deforestation Regulation is forcing a fundamental reconfiguration of sourcing protocols across the entire value chain, compelling exporters to abandon fragmented smallholder networks in favor of certified cooperative structures that can deliver polygon-level geolocation data.
Growth Catalysts
- Specialty HoReCa Expansion:Barista culture penetration in Middle Eastern and Southeast Asian urban centers is creating premium per-cup revenue pools that supermarket channels cannot replicate.
- Mechanized Harvesting:Robotic selective picking systems in Vietnam's Central Highlands are compressing labor costs while expanding Robusta output capacity for espresso blending applications.
- EU Deforestation Regulation:Compliance mandates are accelerating consolidation toward certified origins, inadvertently advantaging large-scale estate producers with pre-existing traceability infrastructure.
Market Restraints
- Input Cost Volatility:Natural gas and fertilizer price swings directly impact wet-milling energy requirements and agronomic input costs across Latin American origins.
- Supply Concentration Risk:Brazil's Cerrado and Vietnam's Central Highlands together account for the majority of global arabica and Robusta volumes, creating correlated weather exposure.
- Regulatory Friction:REACH chemical residue thresholds restrict post-harvest processing inputs for European import channels, complicating traditional fermentation protocols.
Strategic Opportunities
- Underpenetrated Origins:Rwanda and Burundi specialty arabica sectors remain below capacity utilization, offering traceable single-origin positioning for premium roasters.
- Regulatory Tailwind:FDA food safety modernization is creating first-mover advantage for exporters investing in HACCP-certified wet-milling infrastructure ahead of enforcement deadlines.
- Channel Innovation:Direct-to-consumer subscription models are capturing lifetime value through recurring revenue, bypassing traditional grocery velocity dependence.
Industry Challenges
- Geolocation Compliance Timeline:Smallholder-dependent cooperatives face 18-month system implementation cycles to meet EUDR polygon documentation requirements.
- Capex Intensity:Solar-drying infrastructure and moisture-controlled storage facilities demand substantial upfront investment that fragments producer competitive position.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coffee Market |
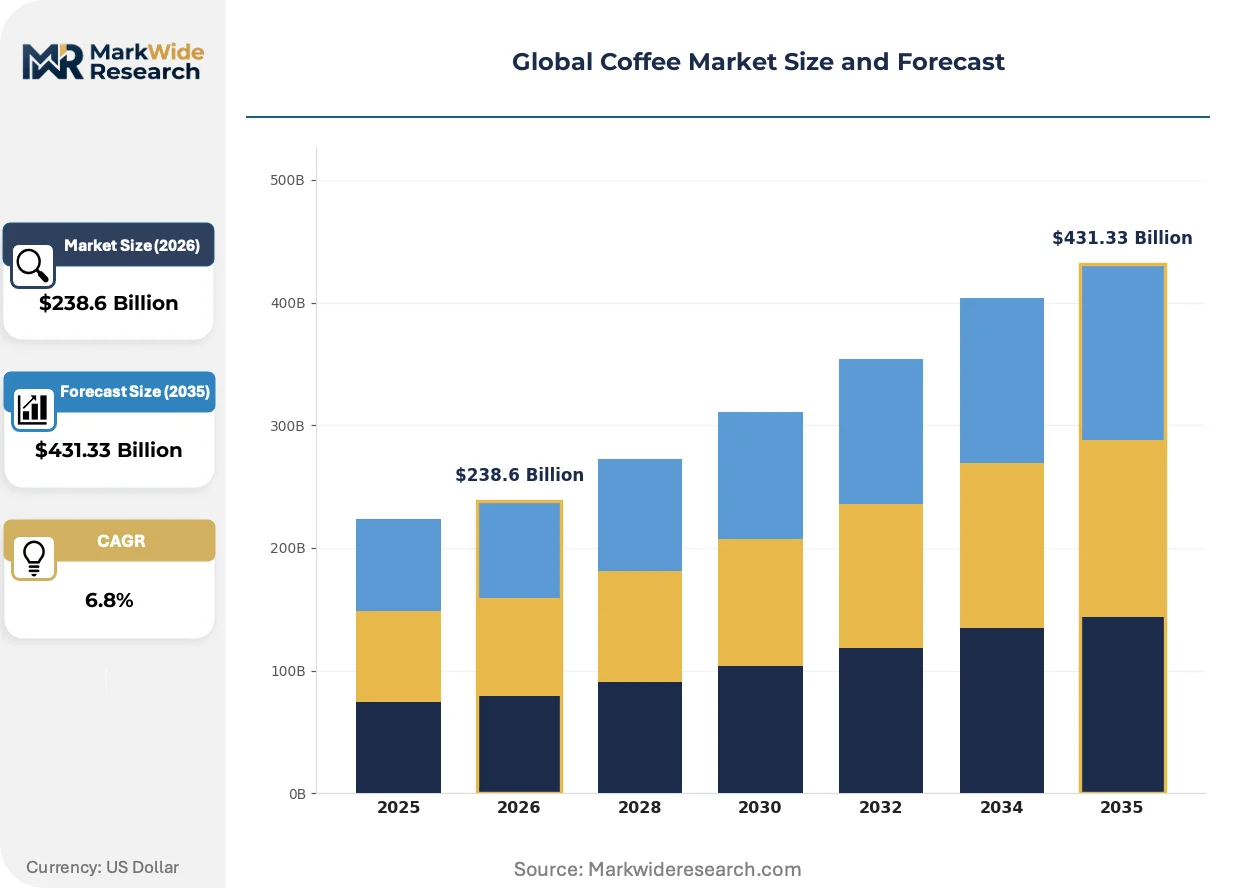
| Market Size in 2026 | $238.6 Billion |
| Market Size in 2035 | $431.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Blended, Specialty Distribution Channel: Online, Supermarkets, Coffee Shops, Convenience Stores End User: Household, Commercial, HoReCa, Office Origin: South America, Africa, Asia, Central America |
| Companies Covered | JDE Peet's Coffee and Tea, The J. M. Smucker Company, Nestlé S.A., UCC Ueshima Coffee Co., The Kraft Heinz Company, Starbucks Corporation, Luigi Lavazza S.p.A., Massimo Zanetti Beverage Group SpA, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coffee Market Emerging Trajectories
Digital traceability infrastructure is virtualizing traditional supply chain intermediation, while regulatory mandates and consumption-pattern shifts are compressing legacy procurement timelines across all major importing regions.
Blockchain-enabled lot tracking is virtualizing chain-of-custody documentation from farm gate to roast. Specialty roasters in North American and European markets are mandating real-time provenance verification as a procurement prerequisite. This technology is compressing the role of traditional export intermediaries while enabling premium pricing for verified single-origin lots.
REACH chemical residue thresholds are tightening post-harvest processing protocols for European import channels. Wet-mill operators must now substitute synthetic fermentation accelerators with controlled microbial inoculants to maintain market access. East African arabica exporters are responding fastest, leveraging existing organic certification infrastructure to pivot processing chemistry.
Subscription-based procurement is displacing spot-market purchasing among specialty roasters with predictable volume requirements. This model locks in origin relationships through multi-year offtake agreements, bypassing the London and New York futures price discovery mechanisms. The shift is most visible in Scandinavian and Australian markets where direct trade relationships already dominate premium segment positioning.
Global Coffee Market Segmentation
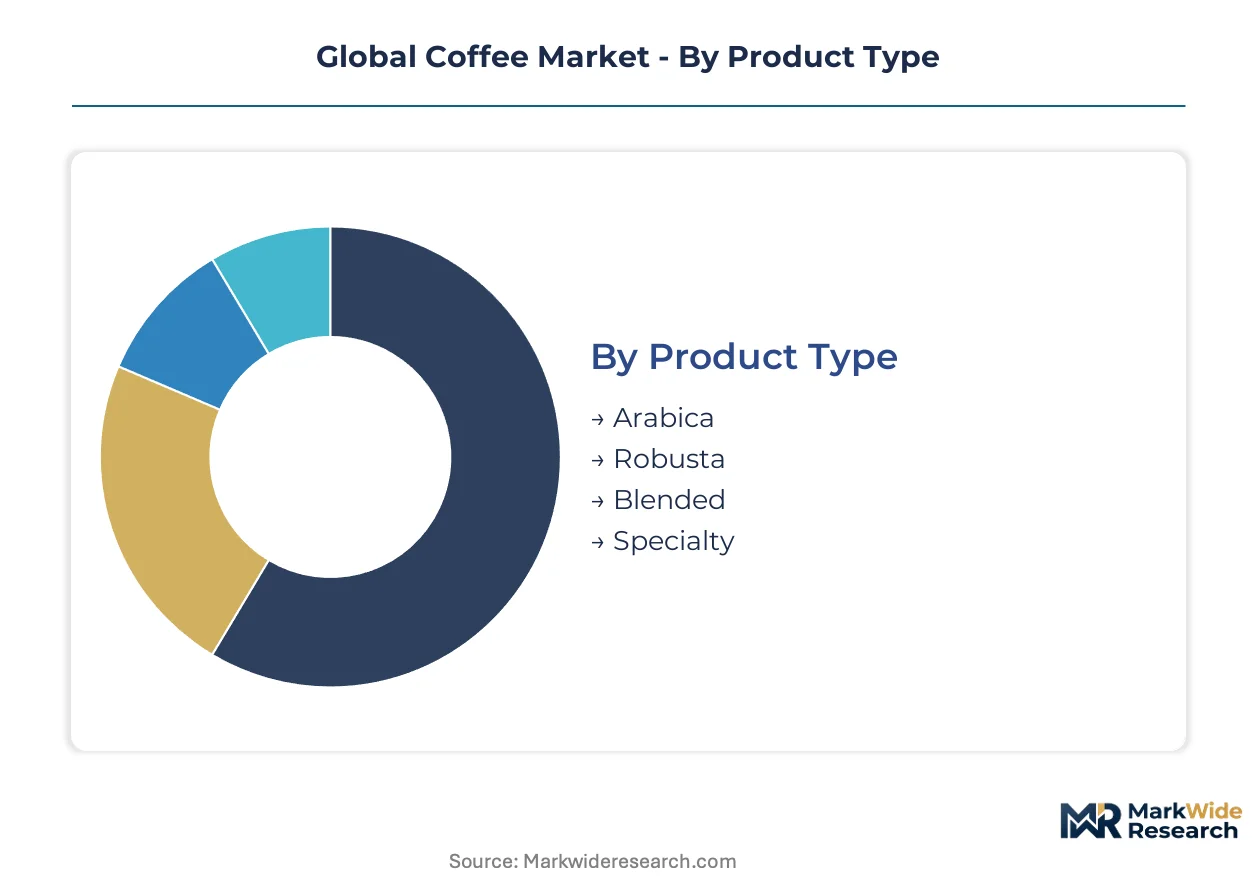
Coffee market segmentation reveals divergent margin structures across product grades and channel formats. Cycle times vary dramatically from daily retail transactions to multi-year plantation maturation, creating distinct capital intensity profiles.
Product Type:
Inventory velocity separates commodity grades from specialty lots, with processing complexity and certification requirements creating tiered turnover economics.
- Arabica:Higher-altitude cultivation between 600-2,000 meters yields complex acidity profiles prized in specialty roasting. Brazilian Minas Gerais and Colombian Huila departments concentrate arabica demand for espresso-forward HoReCa applications where per-cup premiums justify origin-specific procurement.
- Robusta:Hardier canephora species thrives at lower elevations with higher caffeine content and crema-stabilizing lipids. Vietnam's Central Highlands mechanized harvesting is compressing unit costs while supplying instant coffee manufacturers and Italian-style espresso blenders seeking body and bitterness balance.
- Blended:Combines arabica aromatics with robusta structure for cost-optimized volume production.
- Specialty:Micro-lot arabica scoring 80+ on SCAA cupping protocols commands auction premiums through direct trade relationships.
Blended products dominate installed base. Specialty is where expansion concentrates.
Distribution Channel:
Channel selection dictates margin capture, with direct formats preserving value that intermediated retail sacrifices to slotting fees and distributor markups.
- Online:Subscription models lock recurring revenue through roasted-to-order fulfillment, bypassing grocery velocity dependence. Scandinavian and Australian specialty roasters pioneered direct-to-consumer platforms that now capture lifetime value through multi-year offtake agreements.
- Supermarkets:Mass-market volume leadership persists in emerging markets where brand recognition drives purchase decisions.
- Coffee Shops:Out-of-home consumption commands per-cup premiums unattainable in retail channels.
- Convenience Stores:Grab-and-go formats capture impulse traffic with ready-to-drink and single-serve pod offerings.
Supermarkets dominate installed base. Online is expanding most quickly.
End User:
User type determines specification requirements, from household convenience to commercial equipment compatibility and HoReCa presentation standards.
- Household:Single-serve pods and pre-ground retail formats prioritize convenience over origin transparency. European and North American households are shifting toward subscription specialty roasters that deliver freshness through shortened supply chains.
- HoReCa:Hotels, restaurants, and cafés demand consistent extraction performance and traceable provenance for menu storytelling. This segment captures the highest margin pools as out-of-home consumption commands premiums supermarket channels cannot replicate.
- Commercial:Food service and institutional buyers prioritize volume pricing and equipment reliability.
- Office:Workplace coffee programs balance cost control with employee satisfaction metrics.
Household dominates installed base. HoReCa is where expansion concentrates.
Origin:
Geographic sourcing shapes regulatory exposure and flavor positioning, with EUDR traceability mandates favoring consolidated supply bases over fragmented smallholder networks.
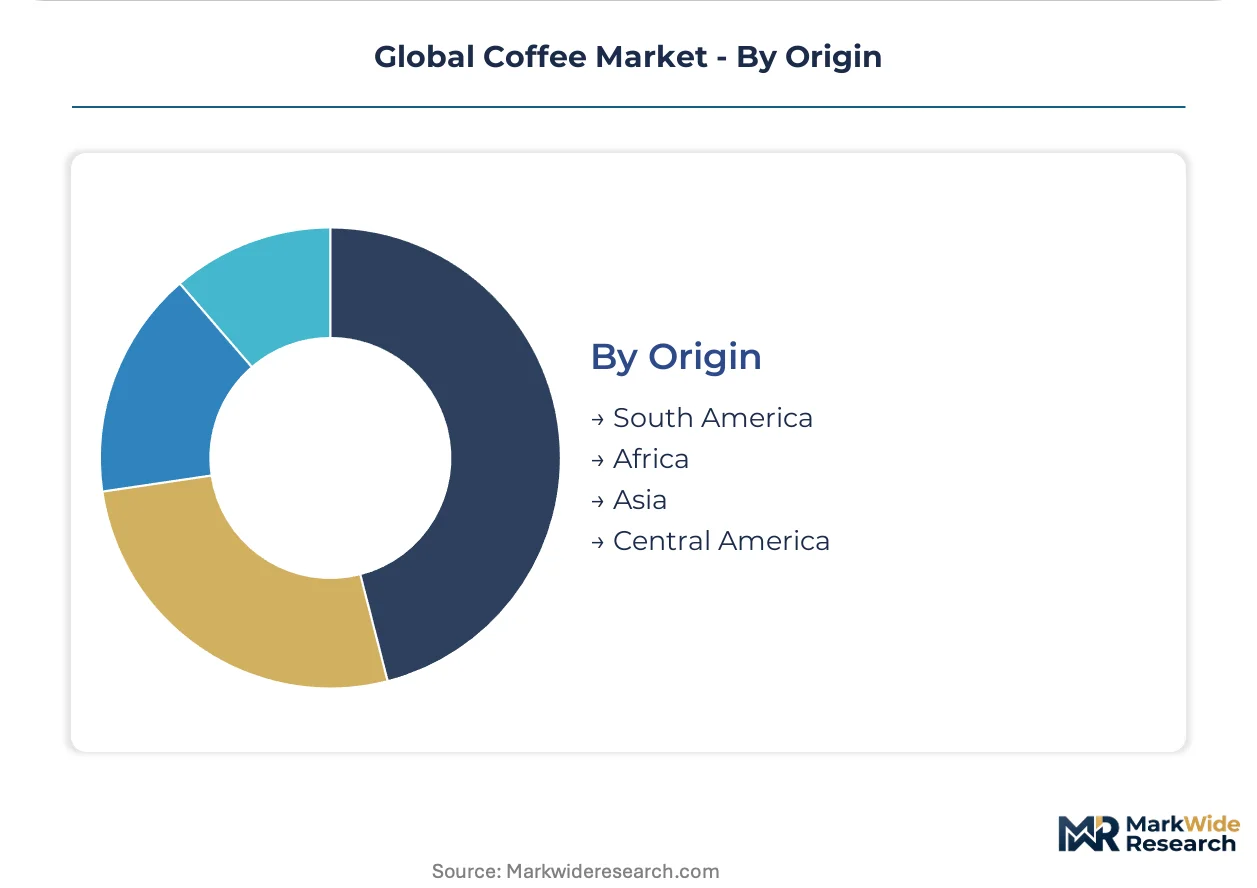
- South America:Brazil's Cerrado mechanization and Colombia's mountain corridor anchor global arabica volume. Brazilian estate producers with pre-existing geolocation infrastructure gain advantage under EU Deforestation Regulation compliance timelines.
- Asia:Vietnam's Central Highlands and Indonesia's Sumatra island concentrate robusta and wet-hulled arabica production respectively. Indonesian smallholders face steepest EUDR adaptation costs due to fragmented land tenure documentation.
- Africa:Ethiopia's Yirgacheffe and Kenya's Nyeri regions supply floral, berry-forward arabica to specialty roasters. Rwandan and Burundi sectors remain below capacity utilization, offering traceable single-origin positioning.
- Central America:Costa Rica's Tarrazú and Guatemala's Antigua regions maintain reputation for clean, bright cup profiles.
South America dominates installed base. Africa is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Food Safety Authority anchors the most stringent import requirements through EUDR geolocation mandates, forcing exporters to reconfigure sourcing protocols across all major producing origins. This regulatory gravity is redistributing competitive advantage toward consolidated supply bases with pre-existing traceability infrastructure.
Brazil
Minas Gerais estates and Cerrado mechanized operations supply the majority of global arabica volume for espresso-forward HoReCa applications. The Brazilian Ministry of Agriculture's traceability certification programs align with EUDR compliance timelines, advantaging large-scale producers. São Paulo-based roasting clusters and Santos port logistics anchor South American export capacity.
Vietnam
Central Highlands mechanized harvesting is compressing Robusta unit costs while supplying instant coffee manufacturers and Italian-style espresso blenders. The country's national agricultural regulator is accelerating farm-level geolocation documentation to maintain European market access. Dak Lak and Lam Dong provinces concentrate mechanized output capacity for crema-stabilizing applications.
United States
Specialty subscription roasters in Seattle and Portland are capturing lifetime value through direct-to-consumer platforms that bypass traditional grocery velocity dependence. FDA food safety modernization is creating first-mover advantage for exporters investing in HACCP-certified infrastructure. California's Bay Area and Brooklyn roasting clusters drive premium single-origin procurement patterns.
Germany
Hamburg and Bremen port infrastructure anchors European import logistics for green coffee consolidation and re-export across the continent. The country's federal environmental regulator enforces REACH chemical residue thresholds that restrict post-harvest processing inputs. Berlin and Munich specialty roasting scenes are driving demand for verified provenance and shortened supply chains.
Ethiopia
Yirgacheffe and Sidama regions supply floral, berry-forward arabica to specialty roasters seeking traceable single-origin positioning. The Ethiopian Coffee and Tea Authority is consolidating fragmented smallholder networks into cooperative structures capable of polygon-level documentation. Addis Ababa export logistics and emerging washing station infrastructure in Guji are expanding specialty-grade output capacity.
Global Coffee Market Vendor Landscape
Capability concentration sits with integrated agronomy-service providers; scale advantage sits with multinational roasters with dual-hemisphere processing networks. The market structures around three tiers: estate-backed origin controllers, brand-differentiated retail roasters, and private-label volume suppliers. Strategic moves center on backward integration into farm-level data systems and multi-year offtake agreements that bypass futures price discovery.
Within the integrated multinational tier, Nestlé S.A. and Starbucks Corporation exemplify divergent approaches to upstream control—one through agronomy services in Brazilian origins, the other through farmer support centers in African and Central American highlands. JDE Peet's Coffee and Tea occupies a position between these models, leveraging transcontinental roasting networks to balance freshness requirements with scale economics. These three anchors demonstrate how regulatory compliance investments are becoming competitive differentiators rather than cost burdens.
| Leading Market Players |
|---|
| JDE Peet's Coffee and Tea |
| The J. M. Smucker Company |
| Nestlé S.A. |
| UCC Ueshima Coffee Co. |
| The Kraft Heinz Company |
| Starbucks Corporation |
| Luigi Lavazza S.p.A. |
| Massimo Zanetti Beverage Group SpA |
| Keurig Dr Pepper |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East African washing stations is compressing farmgate premiums while Brazilian estate overcapacity erodes arabica differentials, forcing suppliers to absorb traceability costs or exit European channels entirely.
Pricing Analysis
Geographic price spreads between Vietnamese Central Highlands Robusta and Ethiopian Yirgacheffe specialty arabica exceed threefold multiples, with grade differentiation anchored by SCAA cupping scores and EUDR certification status. Subscription-based procurement is displacing spot-market purchasing among North American and Scandinavian roasters, locking in multi-year offtake agreements that bypass futures price discovery. Cost compression in commodity-grade segments stems from mechanized harvesting expansion, while specialty tiers maintain pricing power through direct trade relationships. HoReCa buyers exhibit lowest price sensitivity due to per-cup premium capture, whereas instant coffee manufacturers face acute margin pressure from input volatility.
Supply Chain Analysis
Extended payment terms from Hamburg and Bremen port consolidators are squeezing liquidity for Addis Ababa exporters, accelerating consolidation toward cooperative structures with supply-chain finance facilities. Green coffee sourcing draws from Brazil's Minas Gerais, Vietnam's Central Highlands, and Colombia's Huila department, with wet-milling capacity concentrated in origin countries. Fertilizer and natural gas price volatility constitutes the dominant supply chain risk, directly impacting wet-milling energy requirements and agronomic input costs. Distribution runs through Santos, Dak Lak, and Mombasa port clusters for intercontinental shipment to European and North American roasting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational roasters with dual-hemisphere processing networks, fragmenting supplier negotiating position as EUDR compliance mandates favor consolidated estate producers over smallholder cooperatives.
For Market Incumbents: Entrench position through captive wet-milling infrastructure in Rwanda and Burundi, securing polygon-level geolocation data ahead of enforcement deadlines. Nestlé S.A.'s agronomy service model in Minas Gerais demonstrates how backward integration into farm-level data systems neutralizes traceability cost pressure from EU Deforestation Regulation mandates. For New Entrants and Emerging Players: Pursue underpenetrated specialty arabica origins in Ethiopia's Guji zone and Kenya's Nyeri region, where washing station capacity utilization remains below threshold. Direct-to-consumer subscription platforms offer the most penetrable channel, bypassing grocery slotting fees through roasted-to-order fulfillment models pioneered in Scandinavian markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HACCP-certified wet-milling infrastructure, favoring acquisition targets with pre-existing compliance architecture over greenfield development. Over a multi-year horizon, vertically integrated estate producers with EUDR-aligned traceability systems represent the most defensible acquisition profile. The signal to monitor is consolidation velocity among Ethiopian cooperative unions as geolocation documentation deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Data Systems | Polygon-level geolocation capture satisfies EUDR mandates while locking origin relationships. |
| Multi-Year Offtake Agreement Execution | Subscription procurement bypasses London and New York futures price discovery mechanisms. |
| HACCP-Certified Wet-Milling Investment | FDA food safety modernization creates first-mover advantage for compliant exporters. |
| Direct-to-Consumer Platform Launch | Scandinavian and Australian roasters demonstrate lifetime value capture through recurring revenue. |
| Certified Cooperative Structure Consolidation | Pre-consolidated farm-level data reduces EUDR compliance cost for smallholder-dependent origins. |
Methodological Framework
A standing panel of green coffee traders, wet-mill operators, specialty roasting procurement leads, and EU regulatory compliance officers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews captured sourcing protocol evolution, EUDR implementation timelines, and channel margin structures. Secondary sources comprised customs and trade data from Santos and Hamburg port authorities, FDA food safety filings, EUDR guidance documents from the European Commission, and SEC 10-K disclosures from listed roasting companies. Bottom-up volume triangulation across origin-country production data was cross-referenced with top-down import statistics from European and North American customs databases.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated adoption pathways for mechanized harvesting and digital traceability infrastructure. Segmentation modeling incorporated product type, distribution channel, end user, and geographic origin dimensions. CAGRs were derived from weighted average growth across these segments, with inputs including plantation maturation cycles, roasting capacity expansion schedules, and regulatory enforcement timelines. Coffee-specific forecast drivers encompassed rainfall patterns across Brazil's Cerrado, Vietnamese Central Highlands labor cost trajectories, and European specialty consumption elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive traceability investment by Brazilian estate producers or accelerated cooperative consolidation in East Africa would shift competitive outcomes. Macroeconomic deviation in fertilizer and energy markets, regulatory enforcement intensity variation, or technological disruption in robotic harvesting would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Automatic Coffee Machines Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
China Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Ground Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Green Coffee Market
Coffee
Bioactive Proteins in Coffee Market