
 Robusta Coffee Beans Market | 2026-2036
Robusta Coffee Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Robusta Coffee Beans Market Insights
Rainforest Alliance certification is bifurcating the competitive landscape between compliant and non-compliant suppliers. Nestlé leverages its vertical integration from farm to retail to secure certified volumes at scale. Lavazza sustains its position through R&D intensity in roasting profiles tailored to Robusta's higher chlorogenic acid content. JDE Peet's Coffee and Tea anchors European demand through long-term offtake agreements with Vietnamese cooperatives.
Robusta coffee beans, derived from Coffea canephora, contain approximately 2.2–2.7% caffeine by dry weight and exhibit greater pest resistance and yield consistency than Arabica counterparts, making them indispensable for espresso blends and soluble coffee manufacturing. Instant coffee dominates value extraction due to its conversion efficiency and shelf stability, while whole beans command premium positioning in specialty channels. Ground coffee competes on convenience in household segments, though margin pools concentrate in single-origin and certified product lines.
The EU Deforestation Regulation and FDA food safety standards govern import eligibility and residue limits, compelling exporters to invest in geolocation traceability and laboratory testing infrastructure. Vietnam's Ministry of Agriculture and Rural Development enforces national quality standards that align with ISO 17025 laboratory protocols for export certification. Stakeholders must monitor evolving sustainability mandates and origin verification technologies to preserve market access in regulated jurisdictions.
Market Dynamics
The EU Deforestation Regulation is compressing market access timelines for non-compliant suppliers while concentrating procurement power among vertically integrated processors capable of geolocation traceability at farm-gate level.
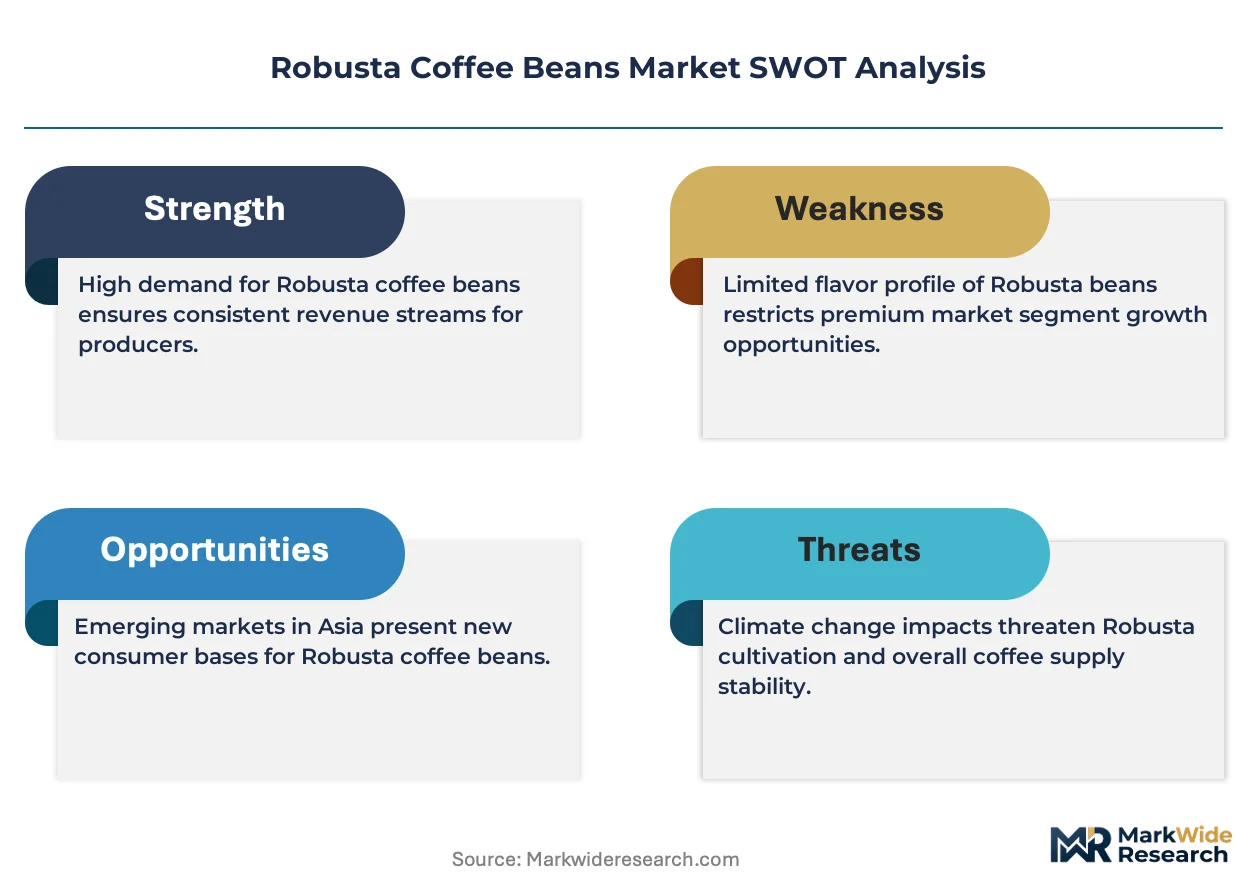
Growth Catalysts
- High-caffeine variety demand:Instant coffee manufacturers in Southeast Asia are expanding procurement of premium Robusta grades for soluble extraction efficiency.
- EUDR compliance infrastructure:The EU Deforestation Regulation is creating competitive moats for early adopters of satellite-based origin verification systems.
- Espresso blend formulation:Roasters are increasing Robusta inclusion rates for crema stability and caffeine intensity in commercial espresso segments.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings in Vietnam directly compress farm-gate margins and export parity calculations.
- Supply concentration risk:Vietnam's dominance in global Robusta exports creates single-origin vulnerability to climate shocks and policy shifts.
- Regulatory friction:The EU Deforestation Regulation's geolocation and due diligence requirements impose capital burdens on smallholder-dependent supply chains.
Strategic Opportunities
- Certified segment white space:Rainforest Alliance and organic certified volumes remain underpenetrated relative to Arabica, offering premium positioning potential.
- Indonesia cultivation expansion:Sumatra and Sulawesi regions present untapped acreage for disease-resistant Robusta varietals with lower input intensity.
- Blockchain traceability convergence:Integration of distributed ledger technology with mobile payment systems is enabling direct farmer-roaster contracting models.
Industry Challenges
- ISO 17025 laboratory capacity:Vietnam's export certification infrastructure faces bottlenecks in pesticide residue and moisture testing throughput.
- Geolocation data integration:Smallholder farm polygon mapping and polygon verification against satellite imagery requires field-level coordination at scale.
- Roasting profile R&D:Chlorogenic acid management in high-Robusta blends demands specialized equipment and sensory calibration investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robusta Coffee Beans Market |
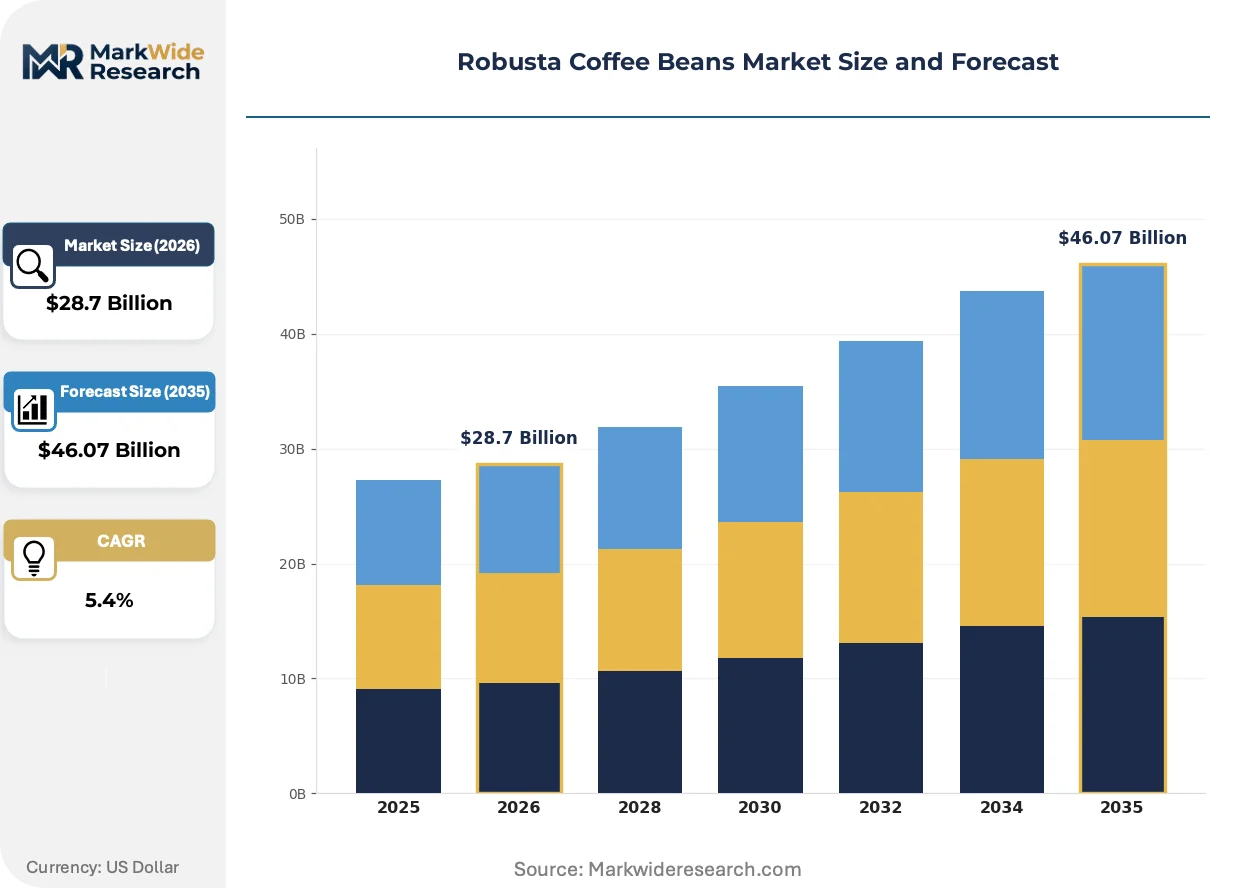
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Ground Coffee, Instant Coffee, Coffee Pods End User: Households, Cafes, Restaurants, Retailers Processing Method: Washed, Natural, Semi-Washed, Monsooned Distribution Channel: Online, Supermarkets, Specialty Stores, Others |
| Companies Covered | Nestlé, Lavazza, illycaffè, Massimo Zanetti Beverage, JDE Peet's Coffee and Tea, Keurig Dr Pepper, Starbucks Coffee Company, Death Wish Coffee, Strauss Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robusta Coffee Beans Market Trends and Innovations
Processing technology and regulatory compliance systems are reshaping value capture patterns, with automation and traceability infrastructure determining margin retention across the supply chain.
Near-infrared spectroscopy is displacing traditional cupping and physical grading for rapid moisture, density, and defect detection at receiving stations. Large soluble coffee processors in Vietnam and Indonesia are deploying inline NIR systems for lot segregation. This technology is displacing manual quality assessment labor and compressing price discovery timelines from days to hours.
The EU Deforestation Regulation mandates geolocation traceability to farm-gate level for all coffee imports into European Union markets. Compliance requires polygon mapping, risk assessment protocols, and annual third-party audits. European instant coffee manufacturers and roast-and-ground brands are most affected, with many restructuring procurement toward vertically integrated Vietnamese exporters with captive farm networks.
Direct trade contracting between roasters and Vietnamese cooperative federations is compressing traditional intermediary layers. Specialty coffee buyers in Germany and Italy are establishing multi-year offtake agreements with Dak Lak and Lam Dong province cooperatives. This pattern is most visible in certified organic and Rainforest Alliance segments where price premiums justify relationship management overhead.
Robusta Coffee Beans Market Segmentation
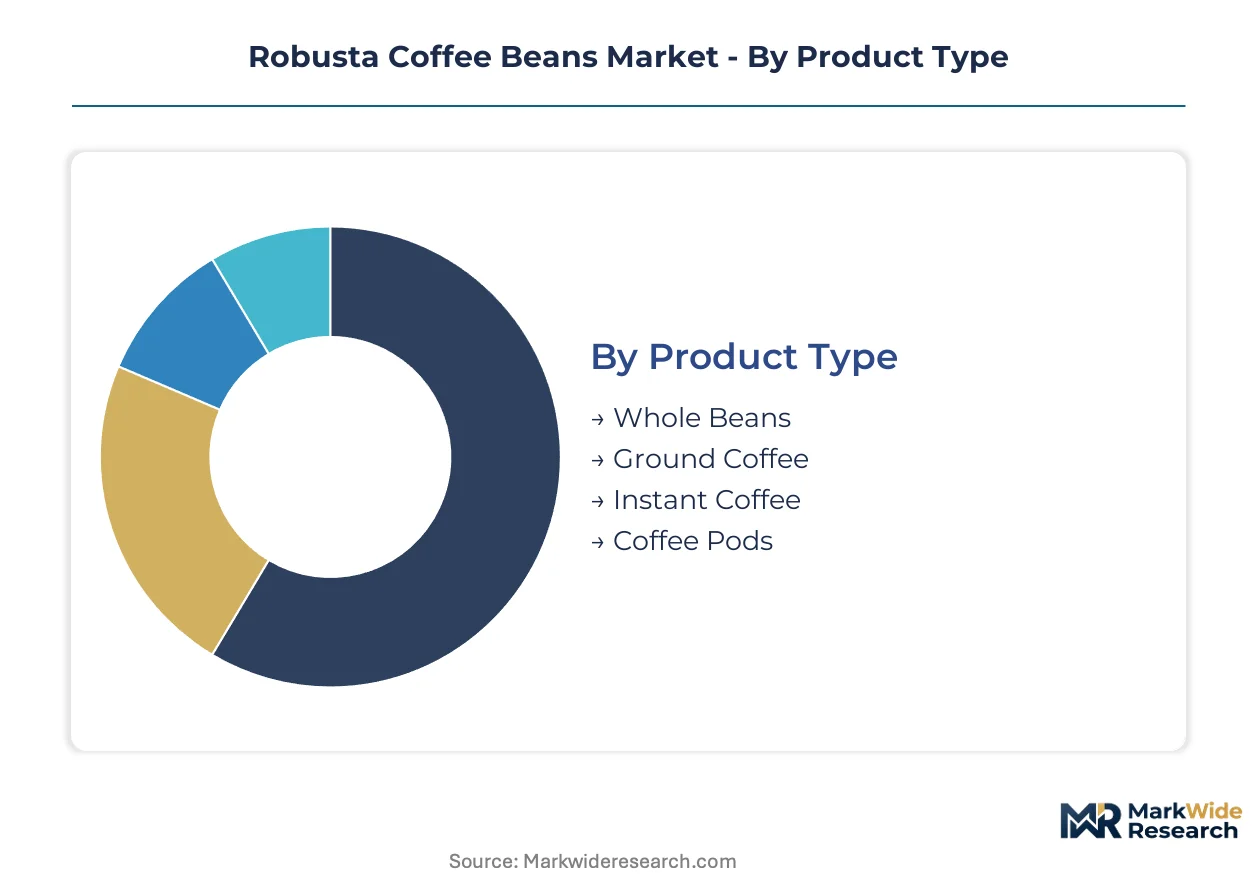
Segmentation in the Robusta coffee beans market reveals how value migrates across processing stages and buyer categories. Product form determines margin capture, while distribution channels dictate geographic reach and certification requirements.
Product Type:
Whole beans dominate export volumes from Vietnam and Indonesia, while processed formats concentrate demand in European and North American consumer markets.
- Whole Beans:Unroasted green beans with 10-12% moisture content serve as the raw material for industrial roasters and specialty buyers. Vietnamese exporters in Dak Lak and Lam Dong provinces ship the majority of certified organic and Rainforest Alliance volumes to German and Italian roasters seeking provenance documentation.
- Instant Coffee:Spray-dried and freeze-dried extracts deliver conversion efficiency of 2.5-3.0 kg green bean per kg soluble product. Nestlé and JDE Peet's anchor procurement in Ho Chi Minh City processing zones, where EUDR-compliant traceability systems command premium sourcing contracts.
- Ground Coffee:Pre-ground Robusta blends target household convenience segments with medium-fine particle sizes optimized for drip and moka pot preparation.
- Coffee Pods:Single-serve capsules in aluminum and compostable formats embed Robusta for crema density in espresso-style systems.
Instant coffee holds the largest share; momentum sits with whole beans in certified specialty channels.
End User:
Cost tier segmentation separates commodity volume buyers from premium-positioned segments willing to pay for origin verification and roasting customization.
- Households:Retail packaged formats in 250-500g bags drive recurring purchase frequency. German and Italian consumers demonstrate highest per-capita soluble coffee consumption, while Vietnamese domestic markets favor traditional phin-filter preparation with locally roasted Robusta.
- Cafes:Espresso blend formulation demands consistent crema stability and caffeine intensity. Ho Chi Minh City and Hanoi cafe chains specify high-chlorogenic-acid Robusta varieties from Lam Dong for traditional Vietnamese coffee preparations.
- Restaurants:Foodservice procurement prioritizes volume pricing and supply reliability over single-origin positioning.
- Retailers:Private-label development by European supermarket chains requires EUDR-compliant documentation and flexible lot sizing.
Households generate the highest absolute volume; cafes are climbing the fastest on specialty beverage menu expansion.
Processing Method:
Processing technique determines flavor profile, defect rates, and suitability for specific end-use applications across export and domestic markets.
- Washed:Fully wet-processed beans with mucilage removal deliver cleaner cup profiles and lower defect counts. Central Highlands washing stations in Vietnam supply European instant coffee manufacturers requiring consistent moisture and density specifications for extraction efficiency.
- Natural:Dry-processed cherries with intact fruit fermentation develop heavier body and lower acidity. Brazilian and Indonesian naturals compete on cost for commercial roast-and-ground blends.
- Semi-Washed:Hybrid honey processing reduces water consumption while moderating fermentation intensity.
- Monsooned:Exposure to moist monsoon winds in Malabar coast warehouses creates distinctive pale color and reduced acidity for niche European markets.
Washed processing holds the largest share; natural processing is gaining share fastest on water scarcity adaptation.
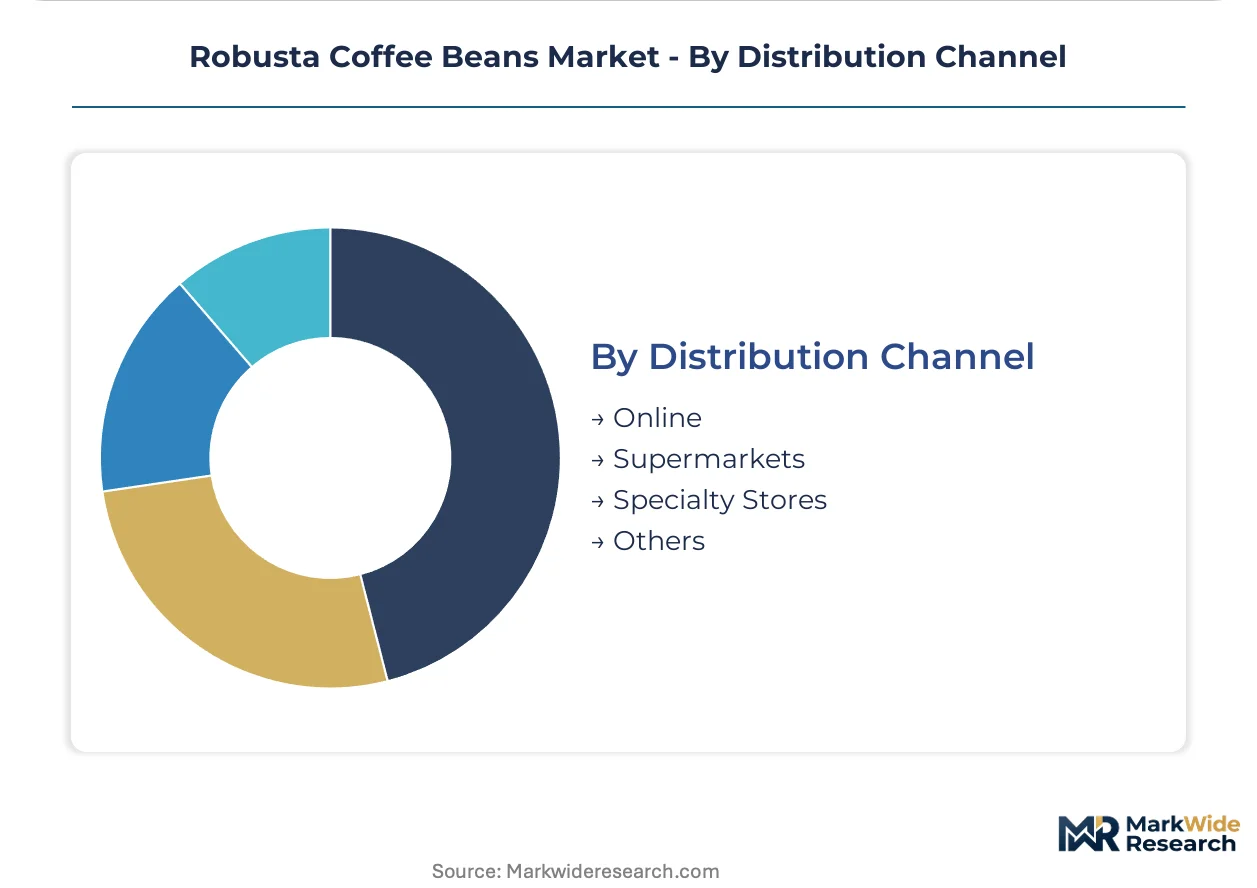
Distribution Channel:
Channel selection determines margin retention, with direct trade models compressing traditional intermediary layers for certified segments.
- Supermarkets:Mass retail chains in Germany, Italy, and France consolidate procurement through centralized buying offices. EUDR documentation requirements favor vertically integrated Vietnamese exporters with captive farm networks and ISO 17025 laboratory certification.
- Online:Direct-to-consumer platforms enable specialty roasters to establish multi-year offtake agreements with Vietnamese cooperative federations. Blockchain traceability integration supports premium positioning for Rainforest Alliance-certified lots.
- Specialty Stores:Independent retailers in Milan, Berlin, and Paris curate single-origin offerings with farm-gate geolocation data.
- Others:Foodservice distributors and institutional catering supply contracts.
Supermarkets hold the largest share; online channels show the steepest expansion trajectory on traceability technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers at instant coffee manufacturers concentrate purchasing power across four origin markets, with traceability compliance now filtering supplier eligibility before price negotiations commence.
Vietnam
The Ministry of Agriculture and Rural Development enforces ISO 17025-aligned export certification that underpins Ho Chi Minh City processing zones. Dak Lak and Lam Dong province cooperatives ship Rainforest Alliance-certified volumes to German and Italian roasters seeking EUDR-compliant documentation.
Indonesia
Sumatra and Sulawesi smallholders supply disease-resistant varietals to soluble coffee extractors prioritizing lower input intensity. The national agricultural regulator mandates moisture and defect testing at regional collection points before export clearance.
Germany
Retail chains in Hamburg and Berlin consolidate procurement through centralized buying offices demanding geolocation traceability. The EU Deforestation Regulation compels supermarket private-label developers to restructure sourcing toward vertically integrated Vietnamese exporters.
Italy
Milan-based roasters formulate espresso blends with elevated Robusta inclusion for crema stability. The national food safety authority enforces residue limits that favor suppliers with captive laboratory testing infrastructure.
United States
FDA food safety standards govern import eligibility for specialty coffee buyers in Seattle and Portland. Direct trade contracting with Vietnamese cooperative federations is compressing traditional intermediary layers for certified organic segments.
Robusta Coffee Beans Market Competitive Landscape
Player mix skews toward vertically integrated food conglomerates with captive farm networks and specialty roasters competing on provenance documentation. Three strategic archetypes dominate: multinational processors with laboratory certification infrastructure, regional roasting houses with direct trade relationships, and private-label developers serving supermarket chains. Competitive moves concentrate on backward integration into origin sourcing and strategic partnerships with cooperative federations for certified volume lock-in.
Within the multinational processor tier, Nestlé and JDE Peet's Coffee and Tea exemplify scale-driven compliance investment, while Lavazza occupies a position bridging commercial volume and specialty positioning. These entities anchor procurement restructuring toward EUDR-compliant supply chains.
| Leading Market Players |
|---|
| Nestlé |
| Lavazza |
| illycaffè |
| Massimo Zanetti Beverage |
| JDE Peet's Coffee and Tea |
| Keurig Dr Pepper |
| Starbucks Coffee Company |
| Death Wish Coffee |
| Strauss Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Vietnamese cooperative federations and European instant coffee manufacturers lock in multi-year supply access while providing farm-gate price visibility indexed to ICE Robusta futures. These contracts insulate processors from spot volatility while compelling upstream investment in EUDR-compliant traceability infrastructure.
Pricing Analysis
Cost-plus contracts with London International Financial Futures and Options Exchange indexation dominate Vietnamese export pricing, linking farm-gate settlements to monthly settlement averages. Price differentiation separates Rainforest Alliance-certified lots from conventional grades, with organic premiums commanding additional spreads. Pricing pressure stems from fertilizer cost inflation in the Central Highlands, compressing processor margins on fixed-price retail contracts. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while vertically integrated multinationals absorb volatility through captive inventory buffers.
Supply Chain Analysis
Vietnam and Indonesia anchor global Robusta production, with Dak Lak and Lam Dong provinces supplying the majority of export-grade washed processing volumes. Supply chains draw from urea fertilizer imports, diesel fuel for drying operations, and jute bagging materials for ocean freight. Single-origin concentration risk intensifies vulnerability to Central Highlands drought cycles and Ministry of Agriculture policy shifts. Distribution runs through Ho Chi Minh City processing zones for European bulk shipment, with specialty channels bypassing intermediaries via direct cooperative contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as EUDR compliance deadlines force procurement restructuring toward certified supply bases. Inventory restocking by European instant coffee manufacturers drives near-term demand inflection.
For Market Incumbents: Consolidate procurement relationships with Lam Dong and Dak Lak cooperative federations through multi-year offtake commitments. Expand ISO 17025 laboratory capacity in Ho Chi Minh City processing zones to capture EUDR-mandated testing revenue from smaller exporters lacking captive infrastructure. Lock in Rainforest Alliance-certified volume ahead of 2025 compliance deadlines when spot premiums for documented origin will widen. For New Entrants and Emerging Players: Rainforest Alliance certification fast-track programs offer the most penetrable entry vector for Indonesian smallholders in Sumatra and Sulawesi regions with untapped disease-resistant acreage. Target certified organic segments where direct trade contracting with German and Italian specialty roasters commands relationship-based premiums unavailable to commodity traders. Deploy blockchain-integrated mobile payment systems to enable farm-gate price transparency and bypass traditional intermediary layers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated Vietnamese exporters with captive farm networks and EUDR-compliant traceability systems already operational. Long-term viability hinges on backward integration depth rather than trading scale, with five-to-ten-year value creation tied to sustainability certification lock-in. Watch for Ministry of Agriculture enforcement actions on geolocation polygon verification as the signal for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure Investment | Geolocation traceability systems at farm-gate level preserve European market access for Vietnamese exporters. |
| Rainforest Alliance Certification Expansion | Certified volume lock-in commands sourcing premiums from Nestlé and JDE Peet's restructuring procurement. |
| Near-Infrared Spectroscopy Deployment | Inline NIR systems at Ho Chi Minh City receiving stations compress quality assessment timelines from days to hours. |
| Direct Trade Cooperative Contracting | Multi-year agreements with Dak Lak federations eliminate intermediary margins for German and Italian specialty roasters. |
| Indonesian Cultivation Expansion | Sumatra and Sulawesi acreage development diversifies supply concentration risk away from Vietnam dominance. |
Research Methodology
Operator-level perspectives from instant coffee procurement managers, cooperative federation directors, ISO 17025 laboratory technicians, and European supermarket private-label developers anchored the qualitative base. Primary interviews across these stakeholder categories combined with secondary validation from Vietnam Customs export statistics, ICO production databases, and EUDR implementation guidance documents. Bottom-up volume modeling from provincial shipment data triangulated against top-down consumption estimates from European retail audit sources.
Sensitivity analysis tested forecast outputs against fertilizer price volatility scenarios and EUDR enforcement timing variations across the projection horizon. Segmentation modeling incorporated product form, processing method, certification tier, and end-user channel dimensions. CAGRs derived from trend extrapolation of historical trade flows adjusted for regulatory compliance cost absorption and certified premium persistence. Forecast inputs included Ministry of Agriculture export clearance data and ICE Robusta futures curve structure.
Underlying assumptions cover EUDR geolocation mandate adherence rates, Central Highlands yield stability, and European instant coffee demand elasticity, with deviation risk concentrated in climate shock frequency and regulatory enforcement intensity. Recalibration cycles align with material shifts in EU sustainability mandate implementation and Vietnamese agricultural policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Portable Espresso Machines Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
High Protein Coffee Market
Coffee
Green Coffee Extract Market
Coffee
Global Coffee Machine Market
Coffee
Latin America Coffee Market
Coffee
Decaf Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Out-Of-Home Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Roast to Order Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Coffee Extracts Market