
 Coffee and Tea Capsule Market | 2026-2036
Coffee and Tea Capsule Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee and Tea Capsule Market Insights
Modular variety-pack configurations is decoupling bulk purchasing from single-flavor commitment, letting households trial multiple profiles without inventory risk. Nestlé leverages its Nespresso system architecture to sustain direct-to-consumer channel control and captive pod ecosystems. Keurig Dr Pepper anchors North American office and hospitality penetration through licensed K-Cup partnerships with roasters. JDE Peet's competes across European retail shelves with multi-brand capsule portfolios spanning price tiers.
Coffee and tea capsules are sealed, pre-portioned containers—typically aluminum or multi-layer polymer—engineered to deliver pressurized extraction at standardized temperature and pressure parameters, primarily serving household and away-from-home beverage preparation with consistency and speed. Single-serve formats dominate volume while organic certification commands premium shelf positioning and margin expansion in Western European retail. Dual-serve configurations show structural growth as households seek flexibility between espresso and larger cup formats without multiple machine investments.
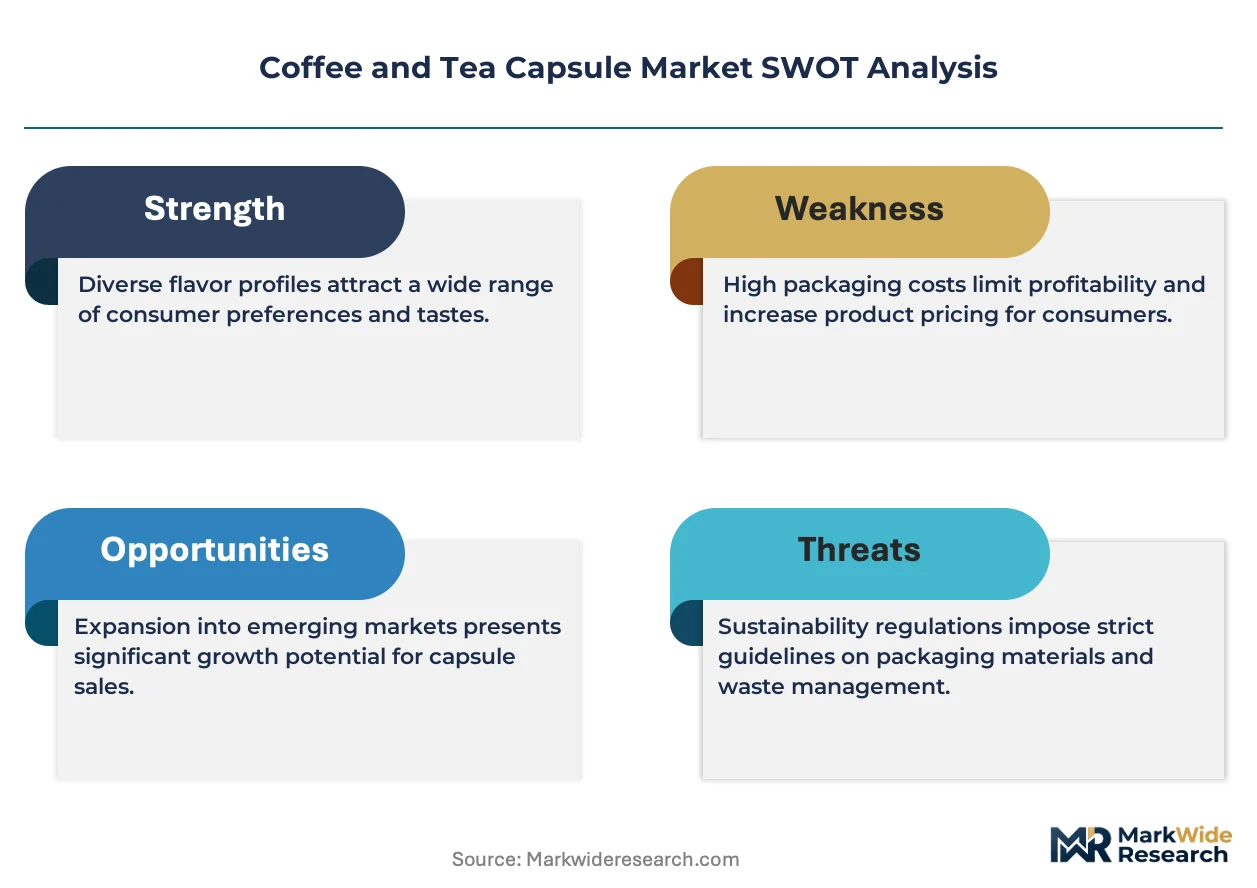
FDA food-contact regulations in the United States, EU REACH restrictions on per- and polyfluoroalkyl substances, and EFSA migration limits on aluminum into acidic beverages collectively constrain material choices and accelerate compostable barrier development. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established testing protocols and reformulation pipelines. Stakeholders must monitor evolving extended-producer-responsibility mandates as these will determine which packaging formats retain distribution access across major retail channels.
Market Dynamics
EU F-Gas Regulation and REACH compliance on aluminum and plastic barrier layers are forcing European manufacturers toward compostable alternatives, while hospitality chains accelerate single-serve adoption across premium lodging and quick-service formats.
Growth Catalysts
- Dual-serve machine architecture:Households in Germany and France are adopting dual-serve configurations that deliver both espresso and larger cup formats without multiple machine investments, expanding addressable use cases.
- EU F-Gas Regulation:This framework is accelerating R&D into plant-based barrier films and aluminum-free seals, creating first-mover advantages for compliant European producers.
- Hospitality procurement consolidation:Premium lodging chains and quick-service formats in Italy are standardizing on capsule systems for consistency and labor reduction, locking in recurring pod demand.
Market Restraints
- Aluminum price volatility:Input cost swings for aluminum sheet and foil constrain margin predictability for producers dependent on traditional barrier materials.
- Compostable film technical limits:Current bio-based barrier layers exhibit oxygen permeability rates that shorten shelf life versus multi-layer polymer alternatives, limiting premium coffee applications.
- EPR mandate fragmentation:Extended-producer-responsibility schemes vary across German, Italian, and French retail channels, complicating pan-European packaging standardization.
Strategic Opportunities
- Organic certification premiumization:Western European retail channels are allocating expanded shelf space to certified organic capsules, commanding margin expansion through differentiated positioning.
- Direct-to-consumer subscription models:Nespresso-style captive pod ecosystems demonstrate how machine-plus-pod bundling locks in recurring revenue outside traditional retail.
- Office channel penetration:North American workplace beverage programs represent underpenetrated volume for licensed K-Cup partnerships, displacing batch brew equipment.
Industry Challenges
- Migration testing timelines:EFSA aluminum migration limits for acidic beverages require 12-18 month validation cycles for new barrier formulations, delaying product launches.
- Compostable certification complexity:Industrial versus home composting standards differ across French, German, and Italian waste infrastructure, forcing region-specific SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee and Tea Capsule Market |
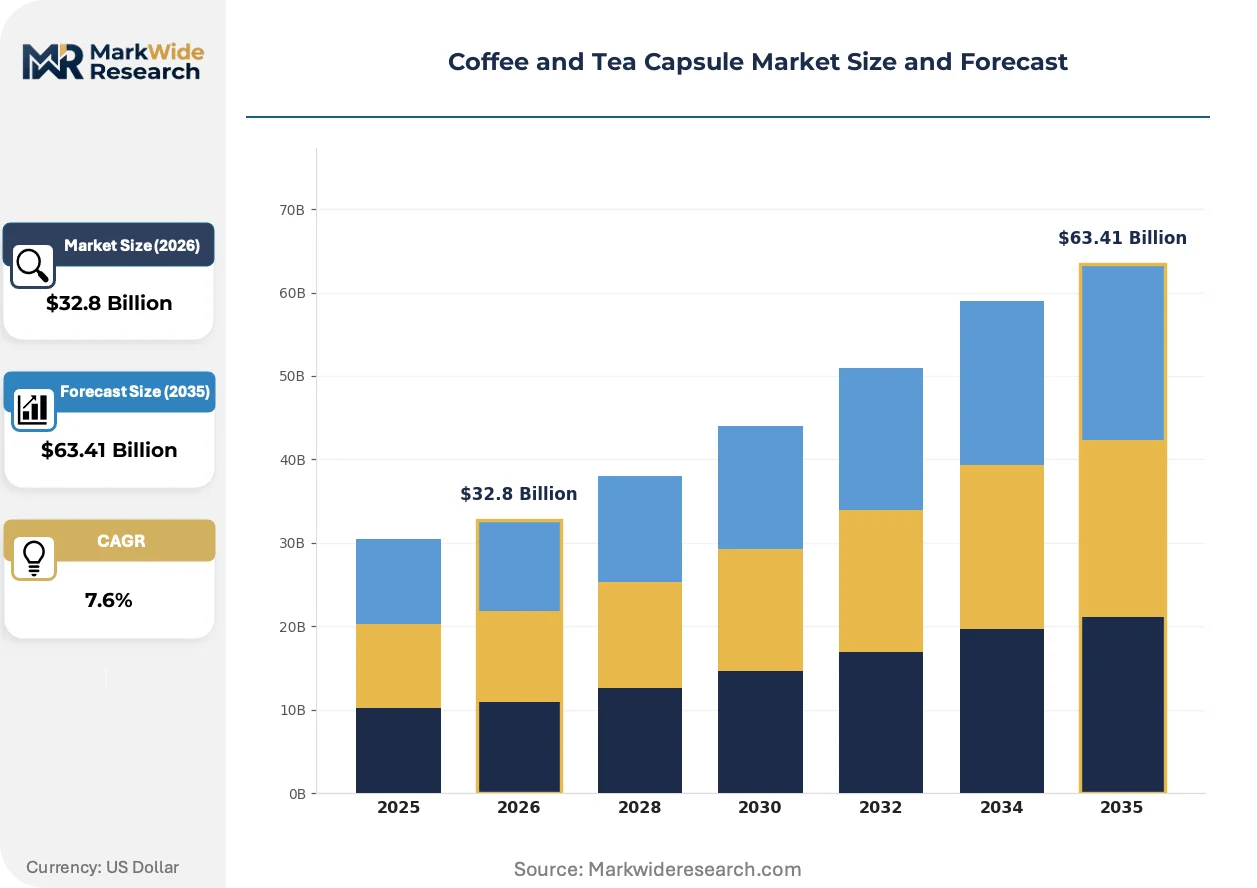
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Serve, Dual Serve, Variety Packs, Organic Brewing Method: Espresso, Drip, French Press, Cold Brew Flavor Profile: Citrus, Nutty, Floral, Spicy Packaging Type: Bags, Pods, Tins, Boxes |
| Companies Covered | Nestlé, Keurig Dr Pepper, JDE Peet's, Starbucks Corporation, Lavazza, The J.M. Smucker Company, Luigi Lavazza, Dualit, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee and Tea Capsule Market Trends and Innovations
Material science breakthroughs and regulatory pressure on fluorinated compounds are converging to reshape capsule construction, while procurement models shift toward flexible variety configurations.
Paper-based barrier laminates with bio-derived coatings are electrifying the transition away from aluminum and multi-layer polymer constructions. German retail buyers are piloting these formats for private-label lines, compressing the cost gap between conventional and sustainable alternatives within two production cycles.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from European manufacturing. This prohibition forces reformulation of heat-seal layers and accelerates investment in polysaccharide-based alternatives, with Italian producers facing the steepest compliance curves due to concentrated espresso capsule volumes.
Modular variety-pack configurations are decoupling bulk purchasing from single-flavor commitment. German and French households are trialing multiple roast profiles without inventory risk, shifting volume from standard 10-count boxes toward curated 30-40 pod assortments that rotate seasonally.
Coffee and Tea Capsule Market Segmentation
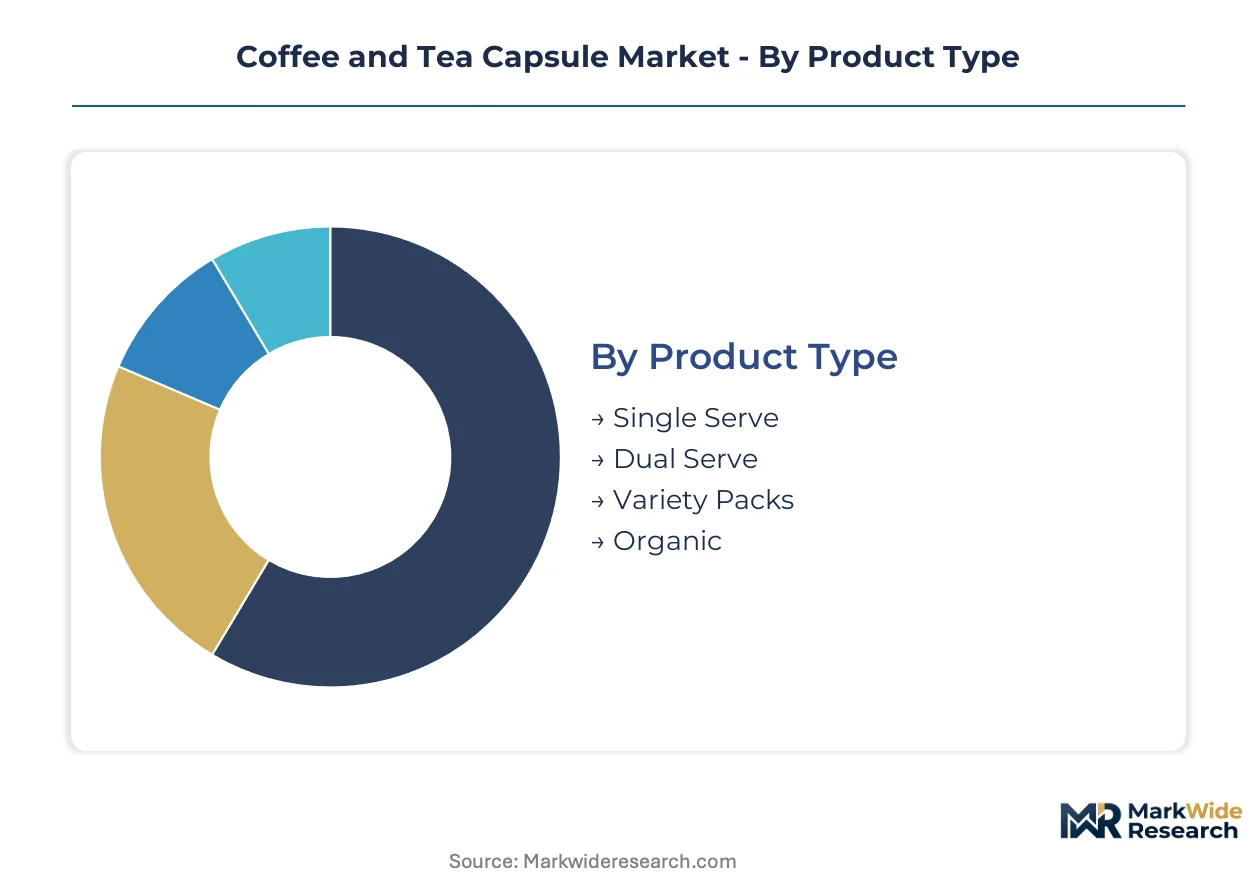
Capsule buyers differ sharply in their willingness to trade convenience against flexibility, with machine architecture and certification preferences creating distinct purchasing cohorts. Manufacturers must align R&D and channel strategy to these divergent demand profiles rather than treating the category as monolithic.
Product Type:
Cost tier separates households seeking entry-level convenience from those investing in premium flexibility systems.
- Single Serve:Aluminum or polymer pods engineered for one-cup extraction at standardized pressure parameters. German and Italian households dominate volume through established espresso machine penetration, though shelf-life constraints from compostable barrier adoption are compressing margins for value-tier offerings.
- Dual Serve:Modular machine architectures accommodate both espresso and larger cup formats through interchangeable brewing chambers. French retail channels are driving fastest adoption as households seek to consolidate countertop appliances without sacrificing drink variety.
- Variety Packs:Curated assortments of 30-40 pods spanning multiple roast profiles in seasonal rotations. German buyers are shifting volume from standard 10-count boxes toward these configurations to reduce inventory risk.
- Organic:Certified cultivation pods commanding premium shelf positioning in Western European retail. EFSA migration testing requirements for aluminum barriers extend launch timelines but justify margin expansion through differentiated positioning.
Single Serve leads volumes today; Dual Serve is gaining share fastest.
Brewing Method:
Application context—home ritual versus workplace speed—determines which extraction technology buyers prioritize.
- Espresso:High-pressure systems delivering concentrated extraction through 9-bar standardized parameters. Italian manufacturing clusters anchor production capacity, with REACH fluorinated compound restrictions forcing reformulation of heat-seal layers for domestic producers.
- Drip:Gravity-fed filtration producing larger cup volumes at lower pressure. North American office channels represent underpenetrated volume as licensed K-Cup partnerships displace batch brew equipment.
- French Press:Immersion brewing without pressure mechanics, typically requiring coarser grind compatibility. Niche positioning in premium hospitality procurement for manual ritual emphasis.
- Cold Brew:Extended steeping at ambient temperatures yielding lower-acidity extraction. Seasonal demand concentration in French and German summer retail cycles.
Espresso commands installed base dominance; Cold Brew shows steepest expansion trajectory.
Flavor Profile:
Margin structure varies dramatically across sensory positioning, with origin-specific premiums justifying dedicated SKU proliferation.
- Citrus:Bright acidity profiles associated with East African and Central American arabica origins. Premium lodging chains in Italy are standardizing on these capsules for breakfast service differentiation.
- Nutty:Low-acidity, caramelized sugar notes typical of Brazilian and Indonesian sourcing. Volume concentration in German private-label retail through cost-optimized blending.
- Floral:Delicate aromatic compounds requiring rapid packaging to preserve volatile oils. Limited shelf-life compatibility with current compostable barrier oxygen permeability rates.
- Spicy:Bold, peppery profiles from Indian and Yemeni heritage varieties. Niche positioning in direct-to-consumer subscription models for enthusiast segmentation.
Nutty profiles anchor mainstream volumes; Citrus is climbing the fastest in premium channels.
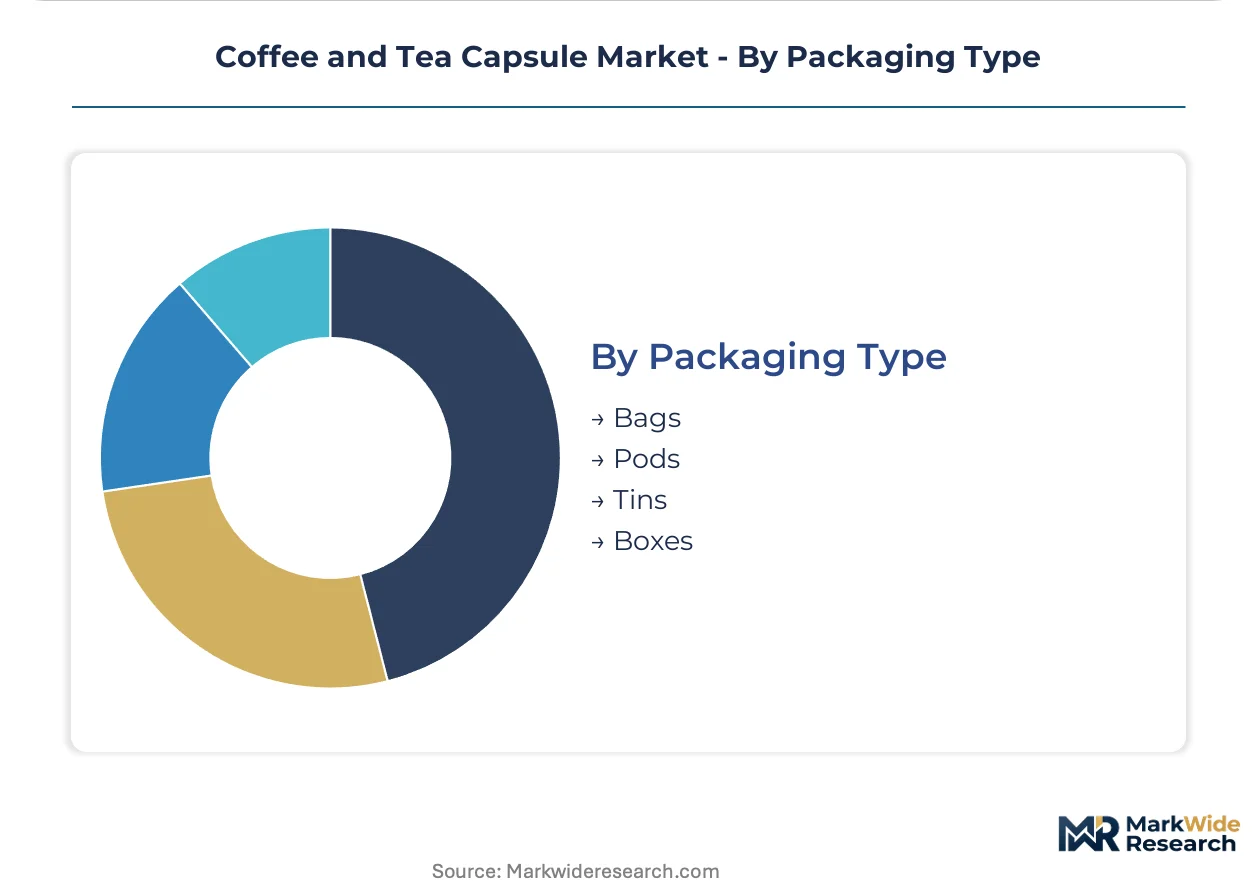
Packaging Type:
Supply concentration in aluminum and multi-layer polymer production is forcing geographic divergence in format availability.
- Pods:Pre-portioned sealed containers for single-serve machine compatibility. German and Italian manufacturing clusters dominate production, with EU F-Gas Regulation accelerating plant-based barrier R&D investment.
- Bags:Flexible film pouches for bulk loose-leaf or ground product. French retail buyers are piloting paper-based barrier laminates for private-label lines.
- Tins:Rigid metal containers for whole-bean preservation and gift positioning. Premium hospitality procurement in Italy favors these for minibar presentation.
- Boxes:Secondary cartoning for multi-unit retail presentation. Extended-producer-responsibility mandate fragmentation across German, Italian, and French channels complicates pan-European standardization.
Pods dominate unit economics today; Bags are expanding most quickly in sustainable packaging transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-serve coffee systems first achieved commercial scale in Italy during the 1980s, establishing the espresso capsule format that would later diffuse across Western Europe and North America. Manufacturing clusters now concentrate in specific metropolitan areas where aluminum forming expertise and flavor formulation capabilities co-locate.
Germany
Dual-serve machine adoption is accelerating in German households seeking appliance consolidation without sacrificing drink variety. ECHA REACH enforcement on per- and polyfluoroalkyl substances is eliminating fluorinated grease barriers from heat-seal layer formulations. Hamburg anchors private-label production capacity, where retail buyers are piloting paper-based barrier laminates for compostable line extensions.
Italy
Espresso capsule volumes concentrate in Italian manufacturing due to entrenched household machine penetration and premium hospitality procurement. EU F-Gas Regulation compliance deadlines are accelerating plant-based barrier R&D investment among domestic producers. Turin and Milan production clusters face the steepest reformulation curves given concentrated espresso capsule output and legacy fluorinated compound dependencies.
France
Modular variety-pack configurations are shifting French retail volume from standard 10-count boxes toward curated 30-40 pod seasonal assortments. Extended-producer-responsibility mandates vary across French retail channels, complicating pan-European packaging standardization for multinational suppliers. Paris-based hospitality chains are standardizing on capsule systems for breakfast service consistency and labor reduction.
United States
Licensed K-Cup partnerships are penetrating North American workplace beverage programs, displacing batch brew equipment in office channels. FDA food-contact regulations constrain material choices for aluminum migration into acidic beverages, elevating compliance costs for new entrants. Seattle and San Francisco anchor specialty coffee subscription models that lock in recurring pod demand outside traditional retail.
United Kingdom
Organic certification is commanding expanded shelf space in British retail, justifying margin expansion through differentiated positioning. CSRD reporting requirements are elevating transparency expectations for packaging sustainability claims across London-headquartered roasters. Birmingham and Manchester distribution hubs are consolidating pan-European logistics for compostable format trials.
Coffee and Tea Capsule Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and machine-system exclusivity, with organic and dual-serve formats capturing superior returns versus standard single-serve offerings. The vendor base organizes around three strategic archetypes: captive ecosystem operators controlling machine-plus-pod bundling, licensed format specialists supplying compatible pods across retail channels, and private-label fabricators serving retailer-owned brands. Dominant competitive moves include strategic partnerships between roasters and machine manufacturers, plus portfolio diversification into compostable barrier formats ahead of regulatory deadlines.
Among Swiss and Dutch-anchored conglomerates, Nestlé and JDE Peet's exemplify divergent ecosystem strategies—one through direct-to-consumer channel control, the other through multi-brand retail shelf presence. Keurig Dr Pepper occupies a position in the North American licensed-format tier, anchoring office and hospitality penetration through partnership architectures. These three entities collectively represent the spectrum of competitive positioning available to participants: captive vertical integration, horizontal multi-brand coverage, and licensed format ubiquity.
| Leading Market Players |
|---|
| Nestlé |
| Keurig Dr Pepper |
| JDE Peet's |
| Starbucks Corporation |
| Lavazza |
| The J.M. Smucker Company |
| Luigi Lavazza |
| Dualit |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
EU extended-producer-responsibility mandates gate qualified supply and premium-tier pricing access by forcing manufacturers to absorb end-of-life packaging costs, compressing margins for non-compliant producers while rewarding incumbents with established recycling infrastructure and certified compostable formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified capsules with EFSA-compliant aluminum barriers from conventional polymer pods and private-label value offerings. Price differentiation hinges on certification grade and machine-system exclusivity, with Nespresso-compatible formats commanding royalty-embedded premiums. Cost compression in economy tiers is intensifying because Hamburg and Turin private-label fabricators are absorbing REACH reformulation expenses without passing through aluminum volatility. Quick-service hospitality buyers exhibit highest price sensitivity, while direct-to-consumer subscribers show lowest elasticity due to machine-plus-pod bundling lock-in.
Supply Chain Analysis
Capsule return and aluminum recovery flows through Nespresso's dedicated collection infrastructure demonstrate how reverse logistics economics can subsidize virgin material costs for participating manufacturers. Raw material dependencies center on aluminum sheet from German rolling mills, bio-derived barrier films from Italian polymer specialists, and coffee bean sourcing from Brazilian and Vietnamese cooperatives. Single-source vulnerability concentrates in Turin and Milan heat-seal layer formulation, where REACH fluorinated compound prohibitions have eliminated qualified alternative suppliers. Distribution runs through Hamburg and Paris retail consolidation hubs for European grocery channels, with Seattle and San Francisco anchoring North American direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder because recurring pod consumption generates predictable revenue streams once machine installation achieves household or workplace lock-in.
For Market Incumbents: Cement ecosystem control by deepening backward integration into compostable barrier film production ahead of EU F-Gas Regulation deadlines, and acquire regional roasters in France and Germany to secure organic-certified bean supply. Threats from paper-based laminate startups in Hamburg require preemptive capacity commitments to industrial composting certification bodies.
For New Entrants and Emerging Players: The gap between premium organic capsules and economy private-label pods creates entry space for mid-tier certified sustainable formats without machine-system royalty burdens. North American office channels remain underpenetrated by non-K-Cup architectures, offering white-space for dual-serve system licensing. Go-to-market through workplace beverage management platforms bypasses retail slotting fee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional roasters with established organic certification and compostable format pipelines because EFSA migration testing timelines create 12-18 month competitive moats against new formulations. Target acquisition archetypes include Italian espresso specialists with Turin production assets and French variety-pack assemblers with Paris retail relationships. Monitor EPR mandate harmonization progress across German, Italian, and French channels as inflection signal for pan-European packaging standardization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Barrier R&D Investment | EU F-Gas Regulation compliance deadlines in Italy and Germany reward first-mover plant-based film producers with retained retail access. |
| Dual-Serve Machine Architecture Launch | French household adoption of espresso-plus-drip consolidation expands addressable use cases without multiple countertop investments. |
| Direct-to-Consumer Subscription Model | Seattle and San Francisco specialty roasters demonstrate recurring revenue capture outside traditional grocery slotting constraints. |
| Licensed K-Cup Partnership Expansion | North American office channel penetration displaces batch brew equipment through Keurig Dr Pepper partnership architectures. |
| Organic Certification Pipeline Buildout | Western European retail buyers allocate expanded shelf space to certified capsules, justifying margin expansion through differentiated positioning. |
Research Methodology
Bottom-up hospitality and household consumption modeling reconciled against top-down aluminum and polymer supply tracking forms the analytical core of this study. Primary interviews with roaster procurement directors, retail category buyers, machine manufacturer platform engineers, and ECHA compliance officers combined with secondary validation from EU F-Gas Regulation filings, EFSA migration limit documentation, REACH substance restriction updates, and customs trade data for aluminum sheet and coffee bean imports. Triangulation across these sources ensures demand-side projections align with supply-side capacity constraints.
Historical trendline analysis of single-serve versus dual-serve machine shipments, organic certification adoption curves, and compostable format penetration rates established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product architecture, brewing method, flavor profile, packaging format, and regional regulatory cluster. CAGRs derive from curve-fitting against installed base expansion and per-household consumption intensity trajectories, with specific inputs for EPR mandate implementation timelines and REACH reformulation completion schedules.
Caveats apply where aluminum price volatility, compostable film oxygen permeability technical limits, or EPR scheme fragmentation across French, German, and Italian channels could materially shift the outlook. Practitioners should monitor EFSA migration testing backlog durations and industrial composting infrastructure buildout rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Green Coffee Extract Market
Coffee
Global Coffee Shop Market
Coffee
Coffee Fruit Extract Market
Coffee
Roast to Order Coffee Market
Coffee
Instant Coffee Market
Coffee
Ethiopia Coffee Market
Coffee
South America Coffee Market
Coffee
Global Coffee Market
Coffee
Cafix Market
Coffee
Global Portable Coffee Makers Market
Coffee
UK Coffee Roaster Market
Coffee
Europe Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Coffee Pods Market