
 United States Coffee Pods and Capsules Market | 2026-2036
United States Coffee Pods and Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
United States Coffee Pods and Capsules Market Outlook
The gap between premium specialty pods and mass-market commodity capsules is broadening as consumers splinter into convenience-driven bulk buyers and experience-oriented craft drinkers. Keurig Dr Pepper dominates the installed base of brewing systems through its K-Cup ecosystem and controls shelf placement across mass retail channels. Nestlé leverages its Nespresso brand to anchor the super-premium aluminum capsule segment with dedicated boutique distribution. J.M. Smucker Company competes in the mid-tier licensed coffee segment through Folgers and Dunkin'-branded pod offerings.
Coffee pods and capsules are pre-portioned, sealed containers—typically constructed from plastic, aluminum, or compostable fiber laminates—designed for single-use extraction in compatible brewing machines at standardized pressure and temperature parameters. Their primary commercial purpose is to deliver consistent beverage quality with minimal preparation time across household, office, and foodservice environments. Single-Serve Pods retain the largest volume share within the product type dimension, though Capsules command disproportionate margin pools due to aluminum recycling premiums and brand exclusivity. The HoReCa consumer type generates faster growth than Household as independent cafes adopt private-label pod programs to reduce barista labor costs.
FDA food-contact substance notifications govern pod material safety, while California's SB 54 extended producer responsibility law and Oregon's Plastic Pollution and Recycling Modernization Act reshape packaging compliance costs for manufacturers. The USDA organic certification and Fair Trade USA standards increasingly filter into consumer purchase decisions, particularly among premium buyers. Stakeholders must monitor how state-level packaging mandates cascade through supply chains and whether compostable material innovations achieve cost parity with conventional multilayer laminates.
Market Dynamics
California's SB 54 extended producer responsibility law and Oregon's Plastic Pollution and Recycling Modernization Act are forcing manufacturers to redesign multilayer pod laminates and absorb compliance costs that reshape margin structures across the value chain.
Growth Catalysts
- Remote-work office procurement programs:Employers in Sun Belt metropolitan areas are consolidating beverage purchases through centralized vending contracts that favor single-serve pod systems over traditional brewing equipment.
- Compostable fiber laminate R&D:Material scientists at USDA-certified facilities are advancing cellulose-based barrier coatings that meet FDA food-contact substance notifications while reducing aluminum dependency.
- Urban coastal household concentration:Single-person households in Seattle, San Francisco, and Boston generate disproportionate per-capita pod consumption due to space constraints and time-compressed morning routines.
Market Restraints
- Aluminum price volatility:Nespresso-format capsule producers face margin compression when London Metal Exchange aluminum futures spike, given the material constitutes 40-50% of super-premium product cost structures.
- Multilayer laminate recycling infrastructure gaps:Municipal materials recovery facilities in secondary Midwest markets lack optical sorting capability for plastic-aluminum hybrid pods, diverting volumes to landfill despite manufacturer collection pledges.
- K-Cup patent expiration saturation:The 2012 Keurig patent cliff enabled generic pod proliferation that commoditized the plastic pod segment and eroded brand loyalty switching costs.
Strategic Opportunities
- Private-label HoReCa penetration:Independent cafes in Texas and Florida are adopting white-label aluminum capsule programs to reduce barista labor costs while maintaining espresso-quality output consistency.
- USDA organic certification tiering:Premium roasters can command shelf placement premiums by securing organic supply chain verification that satisfies ESG procurement mandates from corporate foodservice buyers.
- Direct-to-subscription channel development:Roasters bypass mass retail slotting fees through proprietary capsule subscription models that lock in recurring revenue and capture first-party consumption data.
Industry Challenges
- Compostable certification timeline compression:Manufacturers pursuing BPI or CMA compostable validation face 18-24 month testing cycles that lag behind state packaging mandate effective dates.
- Brewing system interoperability IP:Keurig's DRM-enabled 2.0 brewer authentication and Nespresso's centrifusion patent thickets create legal barriers for third-party capsule entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Coffee Pods and Capsules Market |
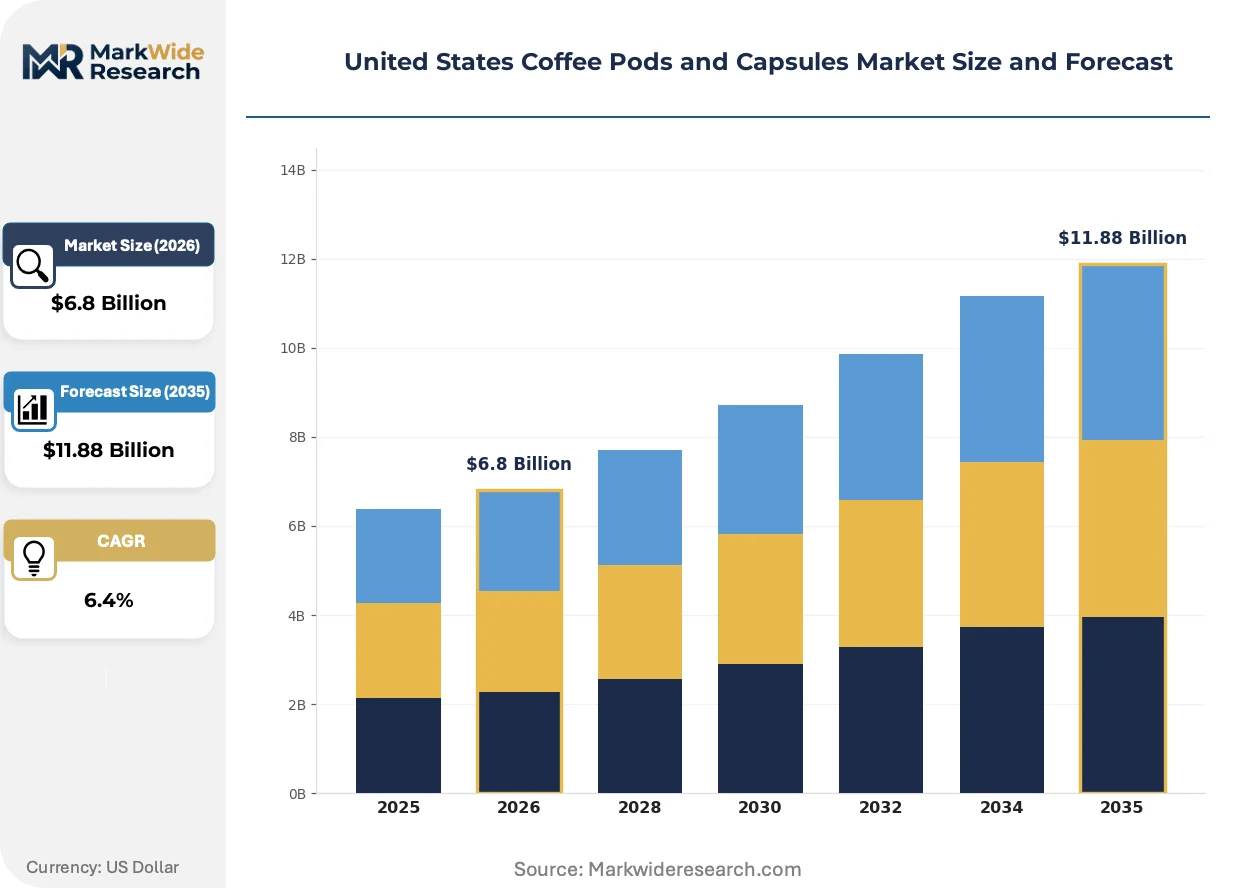
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve Pods, Capsules, Ground Coffee, Instant Coffee Consumer Type: Household, Office, Retail, HoReCa Flavor Profile: Dark Roast, Medium Roast, Light Roast, Flavored Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bulk Suppliers |
| Companies Covered | Keurig Dr Pepper, Nestlé, Starbucks Corporation, J.M. Smucker Company, The Kraft Heinz Company, JDE Peet's, Inspire Brands, Peet's Coffee, Hiline Coffee Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Coffee Pods and Capsules Market Strategic Shifts
Material science breakthroughs and state-level packaging mandates are converging to accelerate compostable pod development while regulatory pressure fragments compliance requirements across jurisdictions.
Compostable fiber laminates with polylactic acid barrier layers are expanding into the premium household segment as Whole Foods and regional co-op chains prioritize shelf placement for BPI-certified alternatives. Early adoption concentrates in Pacific Northwest and Northeast urban markets where municipal composting infrastructure supports end-of-life claims. This material transition is compressing aluminum capsule margin premiums and forcing incumbents to dual-source supply chains.
California's SB 54 mandates 30% post-consumer recycled content in plastic packaging by 2028 and establishes producer responsibility organizations that internalize end-of-life collection costs. The law compels manufacturers to redesign multilayer structures or absorb fees that scale with non-recyclable material tonnage. Small and mid-tier pod producers in the plastic segment face disproportionate compliance burden relative to vertically integrated market leaders with dedicated sustainability engineering teams.
Corporate procurement departments are unbundling beverage service contracts from broad facilities management agreements and negotiating direct relationships with roasters for branded office pod programs. Foodservice distributors that historically captured this spend through bundled vending contracts are losing volume to manufacturer-direct subscription models. This disintermediation is most visible in Austin, Denver, and Raleigh-Durham technology corridors where hybrid office footprints concentrate decision-making authority with workplace experience managers rather than traditional procurement functions.
United States Coffee Pods and Capsules Market Segmentation
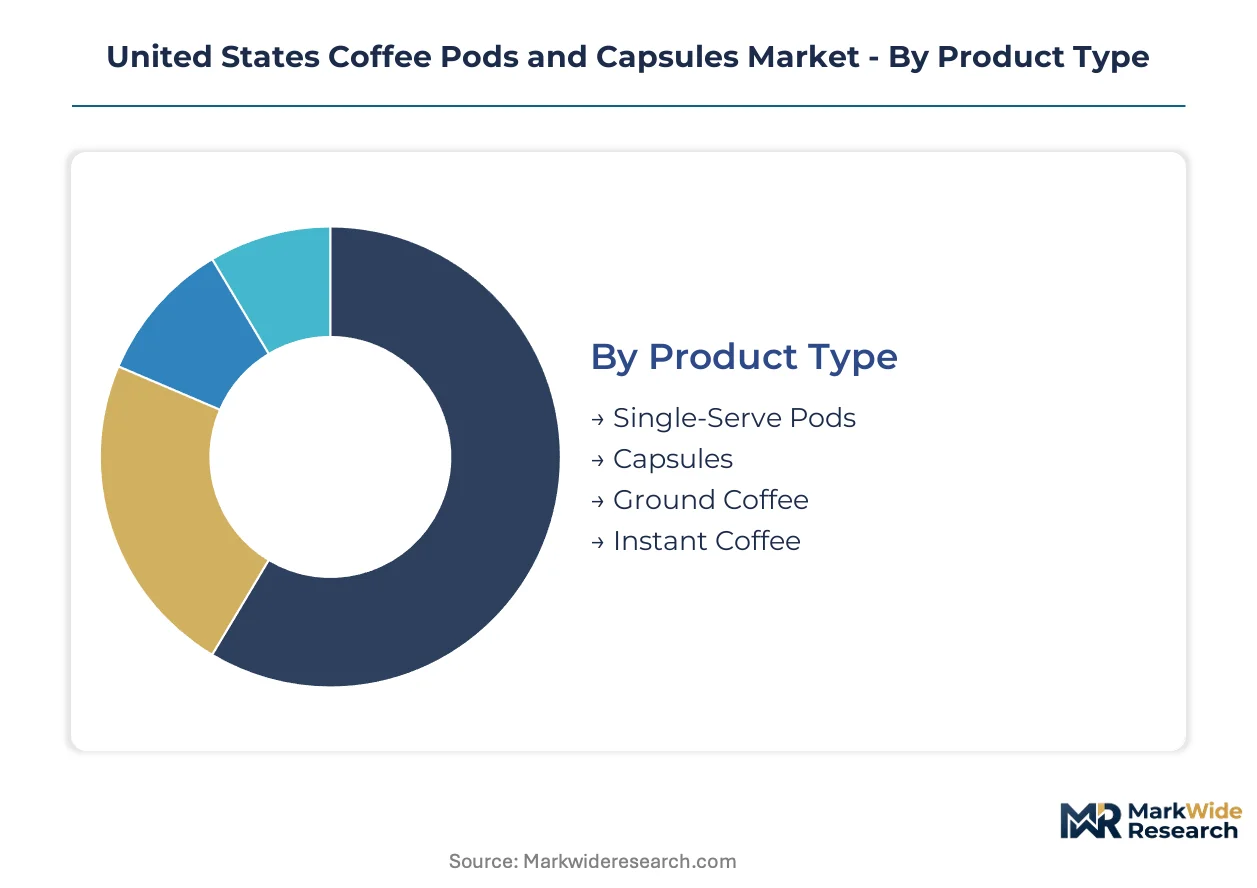
Coffee pod and capsule segmentation reveals how material science, consumption context, and procurement authority fragment demand across distinct margin pools. Each dimension carries specific regulatory exposure and channel access requirements that shape competitive positioning.
Product Type:
Customization dominates the premium aluminum capsule tier while standardization drives plastic pod commoditization across mass retail.
- Single-Serve Pods:Multilayer plastic laminates with paper filter elements engineered for Keurig-compatible pressure systems. Demand concentrates in Sun Belt suburban households and remote-work office installations where brewing speed outweighs extraction precision. K-Cup patent expiration saturated this segment with private-label entrants.
- Capsules:Precision-formed aluminum shells with hermetic seals designed for 19-bar espresso extraction in Nespresso-compatible systems. Coastal urban professionals and independent Texas cafes drive adoption for crema quality and recycling program participation. Aluminum price volatility compresses margins when London Metal Exchange futures spike.
- Ground Coffee:Bulk-format roasted beans packaged for traditional drip brewing equipment. Price-conscious Midwest households and institutional foodservice buyers favor this format where pod system capital costs prove prohibitive.
- Instant Coffee:Spray-dried or freeze-dried soluble granules requiring no brewing infrastructure. Camping supply retailers and emergency preparedness distributors sustain niche demand despite quality perception deficits.
Leading the category by volume: Single-Serve Pods. Expanding most quickly: Capsules.
Consumer Type:
Procurement authority migration from facilities managers to workplace experience teams reshapes volume allocation across this dimension.
- Household:Individual consumption units purchasing through retail or subscription channels. Single-person Seattle and Boston apartments generate disproportionate per-capita pod consumption due to space constraints and time-compressed morning routines.
- Office:Employer-funded beverage programs centralized through vending contracts or direct roaster relationships. Austin, Denver, and Raleigh-Durham technology corridors drive fastest growth as hybrid work models consolidate procurement decisions with workplace experience managers.
- Retail:Resale through grocery, convenience, and club channels where slotting fees and promotional calendars govern shelf placement. Mass-market velocity depends on licensed brand recognition and seasonal promotional intensity.
- HoReCa:Hotels, restaurants, and cafes adopting pod systems for labor cost reduction and output consistency. Florida and Texas independent cafes lead private-label aluminum capsule adoption to maintain espresso quality without barista training investment.
Dominant by procurement volume: Office. Steepest expansion trajectory: HoReCa.
Flavor Profile:
Roast intensity preference maps to regional taste formation and morning consumption timing patterns.
- Dark Roast:Extended roasting profiles producing bold, low-acidity extraction favored by traditional coffee drinkers. Midwest and Southern states sustain highest per-capita consumption where palate preference formed around diner-style brewing.
- Medium Roast:Balanced acidity and body positioning for mass-market acceptance. Default selection in office procurement programs where compromise across employee taste distribution governs purchasing decisions.
- Light Roast:Shorter roasting preserving origin-specific acidity and fruit notes. Pacific Northwest and Northeast urban markets concentrate demand among third-wave coffee converts seeking terroir expression.
- Flavored:Added natural or artificial flavoring agents targeting dessert-coffee occasions and seasonal consumption. Holiday promotional calendars and single-serve gift assortments sustain this segment despite specialty coffee stigma.
Highest volume share: Medium Roast. Gaining share fastest: Light Roast.
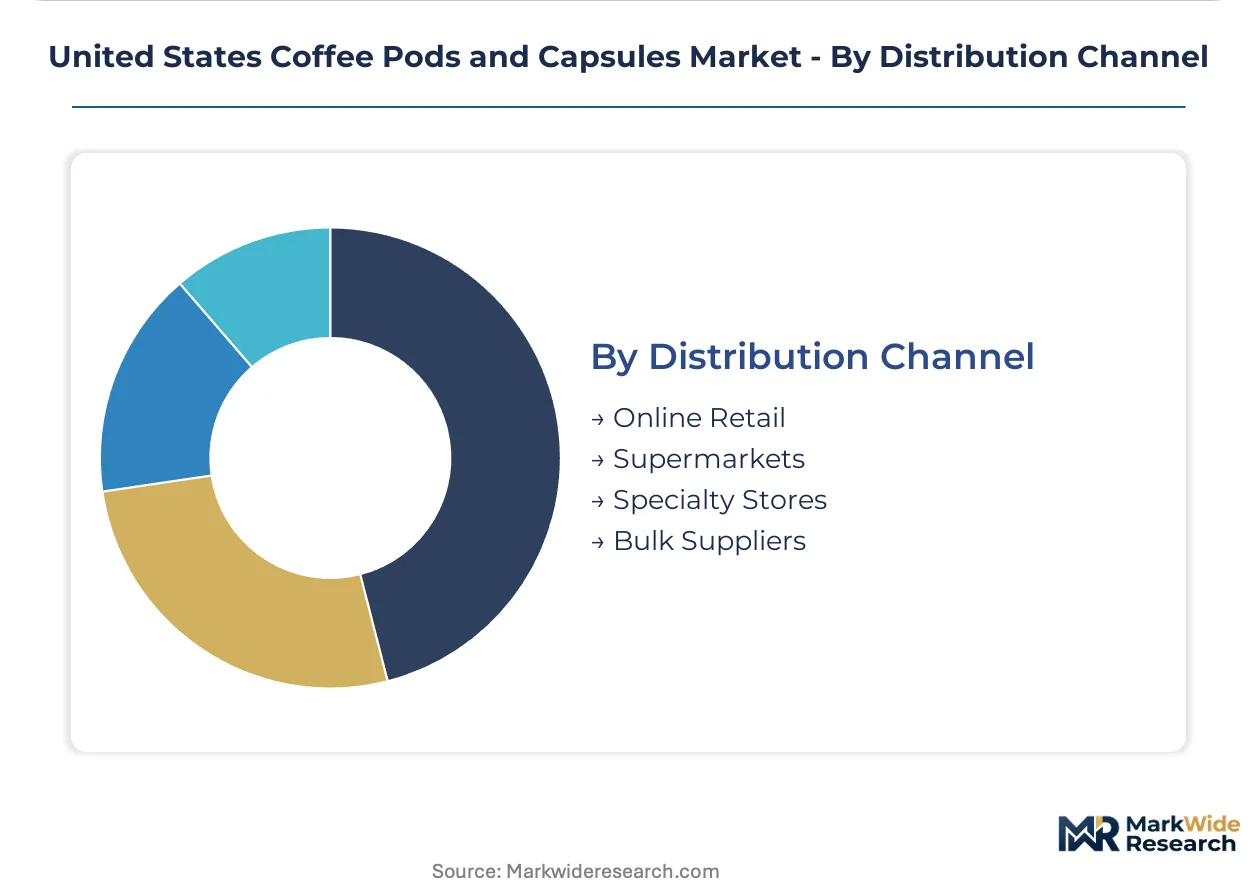
Distribution Channel:
Channel selection determines margin capture, data access, and compliance burden for pod and capsule manufacturers.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription lock-in and first-party consumption data capture. Roasters bypass mass retail slotting fees through proprietary capsule subscription models targeting recurring revenue.
- Supermarkets:Mass-market grocery and club stores where Keurig Dr Pepper controls shelf placement through K-Cup ecosystem dominance. California SB 54 compliance costs for plastic packaging reshape supplier economics in this channel.
- Specialty Stores:Whole Foods and regional co-op chains prioritizing BPI-certified compostable alternatives. Pacific Northwest and Northeast urban markets concentrate demand where municipal composting infrastructure supports end-of-life claims.
- Bulk Suppliers:Foodservice distributors and vending operators historically capturing office beverage spend through bundled contracts. Disintermediation accelerates as workplace experience managers negotiate direct roaster relationships.
Largest volume channel: Supermarkets. Most rapid structural shift: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors national consumption intensity with the highest per-capita pod adoption among major metropolitan areas, driven by single-person household density and remote-work office penetration across Puget Sound technology corridors.
California
Los Angeles and San Francisco Bay Area households generate disproportionate premium capsule demand through space-constrained apartment living and third-wave coffee culture. SB 54 mandates 30% post-consumer recycled content in plastic packaging by 2028, compelling manufacturers to redesign multilayer laminates or absorb producer responsibility fees. San Diego's biotech office clusters are consolidating procurement through direct roaster relationships rather than traditional vending contracts.
Texas
Austin and Dallas-Fort Worth technology corridors drive fastest office segment growth as hybrid work models concentrate decision authority with workplace experience managers. State environmental regulations lag federal FDA food-contact standards, creating compliance clarity for manufacturers. Houston's independent cafe sector leads private-label aluminum capsule adoption to reduce barista labor costs while maintaining espresso output consistency.
Florida
Miami and Tampa metropolitan areas concentrate HoReCa expansion as hotels and restaurants adopt pod systems for labor cost reduction. State recycling infrastructure gaps divert plastic-aluminum hybrid pods to landfill despite manufacturer collection pledges. Orlando's hospitality sector procurement favors medium-roast licensed brands for guest room amenities and foodservice operations.
Pacific Northwest
Portland and Seattle households sustain highest compostable pod adoption rates where municipal composting infrastructure supports BPI-certified end-of-life claims. Oregon's Plastic Pollution and Recycling Modernization Act reshapes packaging compliance costs for manufacturers serving the region. Microsoft's Redmond headquarters exemplifies corporate procurement unbundling from facilities management contracts toward direct roaster subscription models.
Northeast Corridor
Boston and New York City single-person apartments generate concentrated per-capita consumption due to time-compressed morning routines and premium coffee culture. State-level extended producer responsibility frameworks in neighboring jurisdictions create regulatory anticipation effects. Brooklyn's roasting collective movement is pioneering direct-to-subscription capsule channels that bypass mass retail slotting fees.
United States Coffee Pods and Capsules Market Competitive Environment
Premium-margin players sit above commodity-margin players across material format and distribution channel dimensions, with aluminum capsule specialists capturing disproportionate returns while plastic pod producers face patent-expiration saturation and generic competition. The installed base of brewing systems locks in recurring pod demand through proprietary format ecosystems. Three archetypes dominate: vertically integrated beverage conglomerates with captive roasting and distribution infrastructure; licensed brand marketers leveraging third-party manufacturing capacity; and specialty roasters pursuing direct subscription channels. Capacity expansion in compostable material lines and strategic partnerships for municipal composting infrastructure access represent the dominant competitive moves.
Within the vertically integrated tier, Keurig Dr Pepper and Nestlé anchor opposing ends of the premium-commodity spectrum. Keurig Dr Pepper exemplifies ecosystem lock-in through K-Cup format dominance and mass retail shelf placement control. Nestlé occupies the super-premium aluminum capsule position with Nespresso-brand boutique distribution and recycling program participation. J.M. Smucker Company represents the licensed brand marketing archetype, occupying mid-tier positioning through Folgers and Dunkin'-branded pod offerings without captive manufacturing infrastructure.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Nestlé |
| Starbucks Corporation |
| J.M. Smucker Company |
| The Kraft Heinz Company |
| JDE Peet's |
| Inspire Brands |
| Peet's Coffee |
| Hiline Coffee Company |
| Others |
Value Chain & Pricing Dynamics
Aluminum futures volatility on the London Metal Exchange transmits directly through super-premium capsule cost structures, with 40-50% material exposure forcing dual-sourcing strategies that stratify pricing across compostable fiber and conventional multilayer laminates.
Pricing Analysis
Extraction precision and crema quality anchor value-based pricing for Nespresso-format capsules, commanding shelf placement premiums against Keurig-compatible plastic pods where brand commoditization erodes switching costs. Three-tier pricing structure across premium aluminum, standard plastic, and economy private-label segments reflects certification grade differentiation—USDA organic and BPI compostable tiers capture procurement mandate compliance from corporate foodservice buyers. Cost compression in the plastic pod segment intensifies as California SB 54 producer responsibility fees internalize end-of-life collection expenses. Office procurement programs demonstrate lowest price sensitivity due to centralized workplace experience budgets, while Sun Belt suburban households exhibit highest elasticity to generic pod alternatives.
Supply Chain Analysis
Freight cost inflation from Vietnam and Indonesia coffee origin points compresses roasting margin structures for Pacific Northwest and Northeast urban distributors serving specialty retail channels. Raw material flows draw from Brazilian arabica estates, Colombian highland cooperatives, and Guatemalan single-origin micro-lots for premium capsule lines, with aluminum sheet sourcing concentrated in domestic smelters and Canadian rolling mills. Single-source vulnerability in compostable fiber laminate supply—where BPI-certified barrier coating capacity concentrates at USDA-certified R&D facilities—creates qualification bottlenecks for state mandate compliance. Distribution runs through mass retail slotting fee networks for Keurig Dr Pepper ecosystem lock-in, while direct-to-subscription channels bypass traditional foodservice distributor markups for Austin and Denver technology corridor offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over compostable material R&D and municipal composting infrastructure access determines regulatory compliance cost absorption capacity.
For Market Incumbents: Acquire BPI-certified compostable laminate production capacity to internalize 18-24 month certification timelines that lag California and Oregon mandate effective dates. Consolidate direct roaster subscription relationships with Austin, Denver, and Raleigh-Durham workplace experience managers before foodservice distributors recover disintermediated volume. Patent-thicket enforcement around brewing system interoperability IP remains essential to defend against generic capsule erosion in the plastic pod segment. For New Entrants and Emerging Players: The premium-economy price gap in HoReCa aluminum capsules creates white-space opportunity for private-label programs serving Texas and Florida independent cafes seeking barista labor cost reduction without espresso quality compromise. Target Pacific Northwest and Northeast urban household segments through specialty store placement of BPI-certified alternatives where municipal composting infrastructure validates end-of-life claims. Launch with direct-to-subscription channel development to capture first-party consumption data and bypass mass retail slotting fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier licensed brand marketers with Folgers and Dunkin'-branded pod portfolios in Sun Belt metropolitan areas where remote-work office procurement concentrates volume growth. Long-term viability hinges on compostable material cost parity achievement with conventional multilayer laminates across the analysis window. Monitor London Metal Exchange aluminum futures trajectory as margin compression inflection indicator for super-premium capsule producers.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Material R&D Investment | USDA-certified cellulose barrier coatings reduce aluminum dependency for California SB 54 compliance. |
| Direct-to-Subscription Channel Development | Proprietary capsule models capture recurring revenue from Austin and Denver workplace experience managers. |
| Private-Label HoReCa Penetration | White-label aluminum programs reduce barista labor costs for Texas independent cafes. |
| Brewing System Interoperability IP Defense | Keurig DRM authentication and Nespresso centrifusion patents block generic capsule entrants. |
| Municipal Composting Infrastructure Partnership | BPI-certified end-of-life claims require Pacific Northwest and Northeast urban compost facility access. |
Study Parameters
Document review covered FDA food-contact substance notification databases, California SB 54 and Oregon Plastic Pollution Act regulatory filings, and London Metal Exchange aluminum futures records, complemented by interviews with specialty roaster supply chain directors, workplace experience managers at Austin and Denver technology firms, Whole Foods category buyers, and BPI certification program administrators. Secondary validation drew from USDA organic certification registries, Fair Trade USA supply chain disclosures, and municipal composting infrastructure capacity reports. Bottom-up pod consumption modeling triangulated against top-down retail velocity data from Nielsen and Circana audits.
Segmentation outputs across product type, consumer type, flavor profile, and distribution channel dimensions were projected across the modeling period using elasticity-adjusted volume trajectories. CAGRs were derived from regression analysis of historical pod adoption curves correlated with single-person household formation rates and remote-work office penetration indices. Industry-specific forecast inputs included compostable material R&D pipeline milestones, state extended producer responsibility implementation timelines, and brewing system installed base replacement cycles.
Inputs from FDA notification databases and state regulatory filings were available through the study window; gaps in proprietary roaster subscription revenue data and private-label HoReCa contract terms introduce uncertainty bands around direct channel growth assumptions. Forecasts reflect documented assumptions regarding aluminum price stabilization and compostable certification timeline compression. Stakeholders should weight assumptions against their own operating context and procurement mandate exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Flavored Cold-Brew Coffee Market
Coffee
High Protein Coffee Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Coffee Roaster Machine Market
Coffee
Specialty Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Coffee Decoction Maker Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Ground Coffee Market
Coffee
US Coffee Roaster Market
Coffee
Coffee Crystal Market
Coffee
Ethiopia Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Coffee and Tea Capsule Market