
 Vanilla Oleoresin Market | 2026-2036
Vanilla Oleoresin Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Oleoresin Market Analytics
Flavor house service revenue is tilting from commodity vanilla extract supply toward tailored oleoresin formulation partnerships for beverage and dairy clients. Symrise AG leverages its Madagascar sourcing infrastructure to secure consistent vanilla bean supply for oleoresin distillation. Givaudan SA anchors its competitive position through advanced extraction technology that preserves volatile aromatic compounds. McCormick & Company, Inc. competes in retail-grade segments while extending its industrial oleoresin portfolio for processed food manufacturers.
Vanilla oleoresin is a concentrated solvent-extracted resinoid containing vanillin, vanillic acid, and p-hydroxybenzaldehyde, typically standardized to specific fold strengths for consistent flavor intensity in commercial applications. The Food & Beverage application segment dominates volume consumption, while the Cosmetics application segment commands premium pricing due to stringent purity requirements for dermal use. Organic Grade product types are gaining share as clean-label procurement policies at cosmetic brands and flavor houses tighten ingredient traceability standards.
EU REACH and EFSA frameworks mandate comprehensive allergen and residue documentation for botanical extracts entering European flavor and fragrance supply chains. FDA regulations in the United States enforce identity standards for vanilla-derived products under 21 CFR 169, directly shaping labeling requirements and import compliance costs. Stakeholders must monitor vanilla orchid crop yields in Madagascar and alternative origin developments in Uganda and Papua New Guinea to anticipate supply-driven price volatility and secure forward contracting positions.
Market Dynamics
Madagascar's concentration of vanilla orchid cultivation creates acute supply vulnerability as cyclone frequency intensifies, forcing flavor houses and fragrance manufacturers to restructure procurement around forward-contracting and alternative origin development.
Growth Catalysts
- EU REACH Documentation Mandates:Clean-label procurement policies at European cosmetic brands tighten purity requirements for dermal-grade oleoresin, accelerating premium product substitution.
- Carbon Dioxide Extraction:Supercritical CO2 technology preserves heat-sensitive volatile compounds, enabling higher-fold standardization for beverage and dairy applications.
- Madagascar Infrastructure Investment:Curing facility upgrades and farmer cooperative consolidation reduce post-harvest vanillin degradation losses.
Market Restraints
- Cyclone-Driven Crop Volatility:Madagascar's SAVA region accounts for the majority of global vanilla orchid output, concentrating weather-related supply disruption risk.
- Ethanol Solvent Cost Exposure:Oleoresin production depends on food-grade ethanol pricing, which fluctuates with agricultural commodity markets.
- Synthetic Vanillin Substitution:Guaiacol-derived and lignin-based vanillin alternatives capture cost-sensitive processed food segments.
Strategic Opportunities
- Uganda Origin Development:Central African vanilla cultivation expansion offers supply diversification with shorter maritime freight routes to European ports.
- Pharmaceutical Excipient Applications:High-purity oleoresin grades meet USP standards for oral dosage flavor masking in pediatric formulations.
- EU Green Deal Bio-Based Mandates:Renewable sourcing requirements in personal care formulations favor natural oleoresin over petrochemical-derived alternatives.
Industry Challenges
- Skilled Distillation Technician Shortage:Solvent extraction and resinoid purification require specialized expertise scarce outside traditional producing regions.
- Multi-Jurisdiction Certification Timelines:Organic and Fair Trade audits for Madagascar-origin material extend lead times for clean-label product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Oleoresin Market |
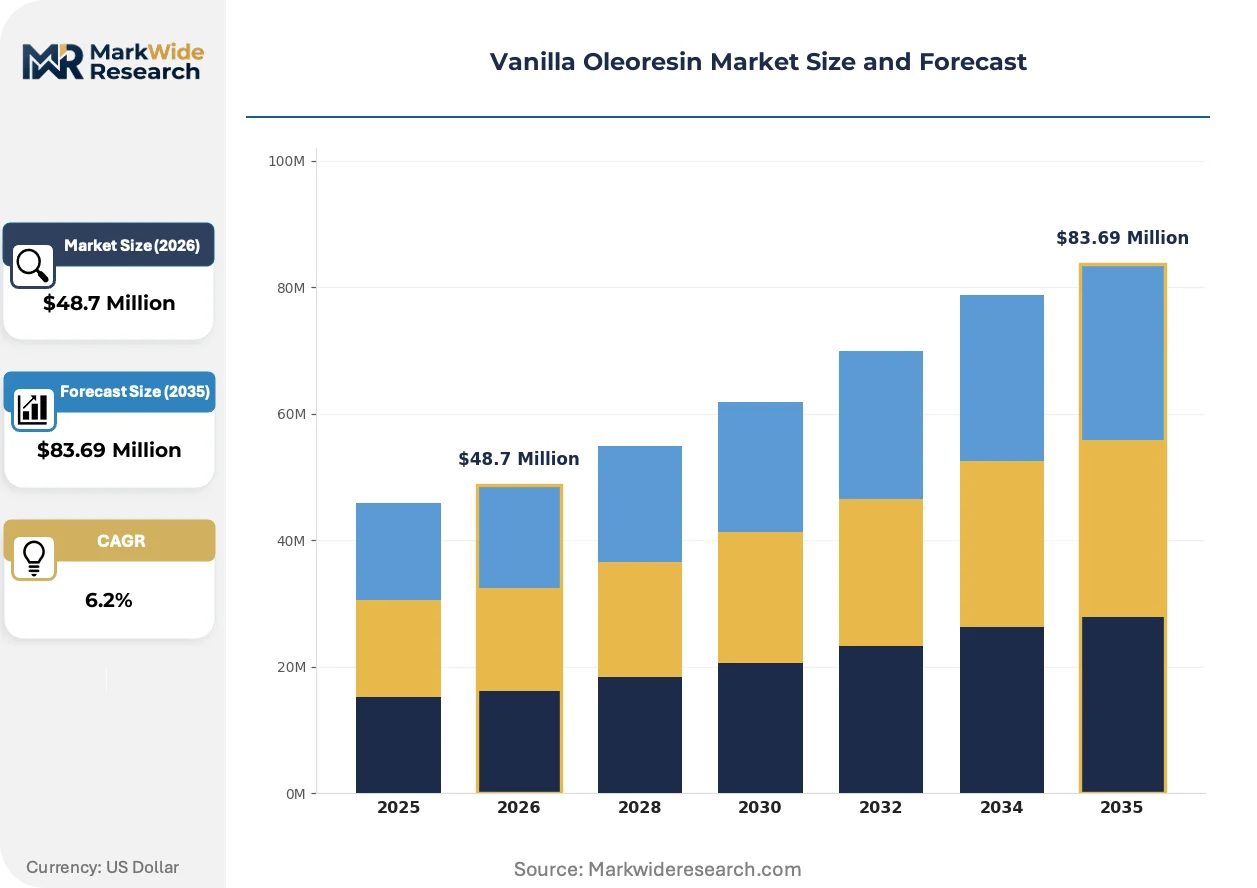
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extract, Synthetic Compound, Organic Grade, Food Grade Application: Food & Beverage, Cosmetics, Pharmaceuticals, Fragrance End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Flavor Houses Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Symrise AG, Givaudan SA, International Flavors & Fragrances Inc., McCormick & Company, Inc., Nielsen-Massey Vanillas, Inc., dsm-firmenich, Sensient Technologies Corporation, Eurovanille, Synthite Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Oleoresin Market Evolving Landscape
Extraction technology convergence with sustainability mandates is compressing traditional supply chain configurations while fragmenting procurement models across end-use verticals.
Supercritical carbon dioxide extraction equipment is virtualizing conventional solvent-based oleoresin production by eliminating ethanol recovery stages and thermal degradation pathways. Premium fragrance houses in France adopt CO2-derived resinoids for haute parfumerie formulations requiring intact aromatic complexity. This virtualization is compressing the premiumization gap between conventional and advanced extraction outputs.
EU REACH and EFSA allergen documentation frameworks mandate comprehensive residue testing for botanical extracts entering European flavor supply chains. Industrial consequence includes mandatory supply chain digitization for batch traceability from orchid harvest to finished oleoresin. Cosmetic and fragrance segments bear the highest compliance burden, with formulators demanding third-party certified documentation packages.
Direct-origin contracting is displacing spot-market vanilla bean purchases among mid-scale flavor houses seeking price stability. Beverage manufacturers in North America and Europe negotiate multi-year agreements with Madagascar cooperatives, bypassing traditional commodity traders. This behavioral shift concentrates volume commitments among vertically integrated processors while marginalizing speculative intermediaries.
Vanilla Oleoresin Market Segmentation
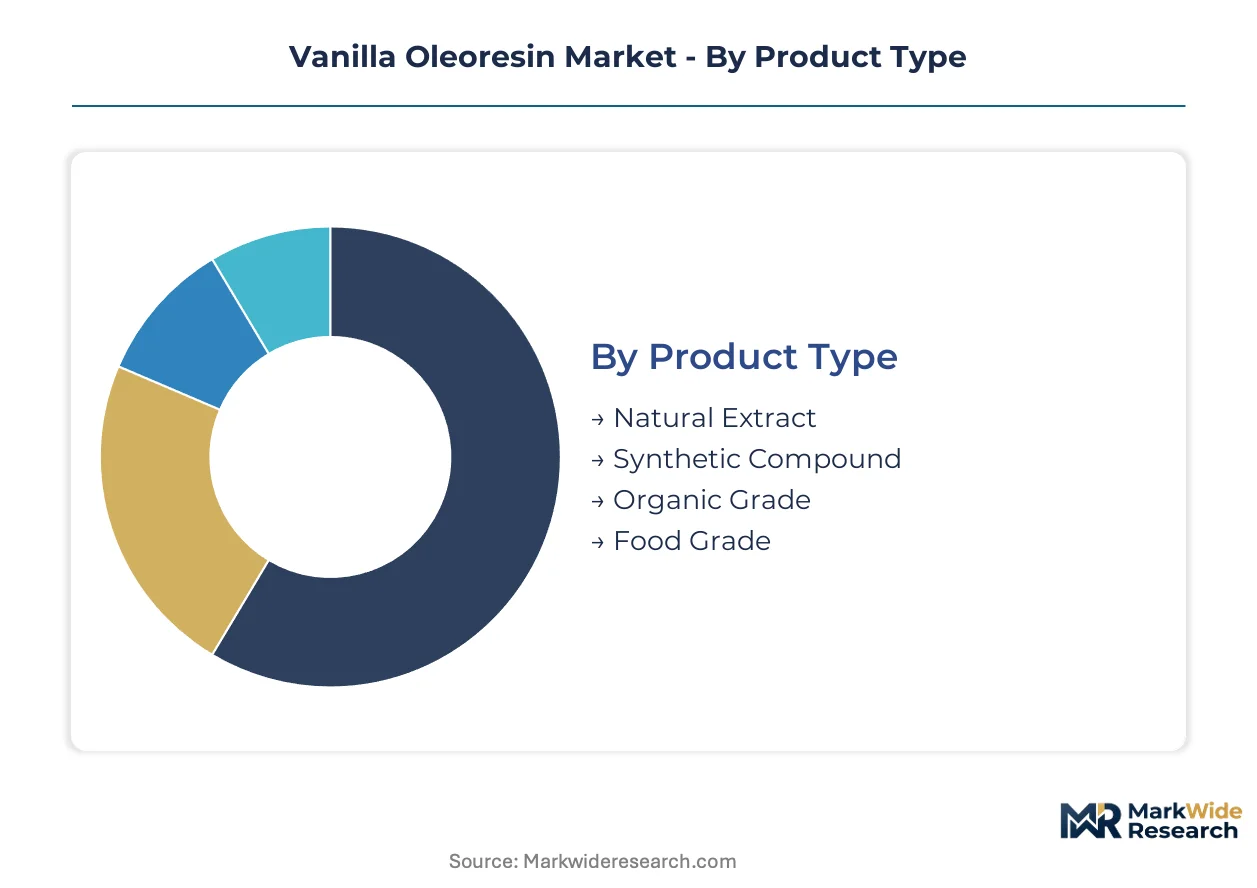
Segmentation in vanilla oleoresin markets reveals how extraction grade, application purity, and channel configuration determine margin capture. Technical specifications diverge sharply between food-grade bulk supply and pharmaceutical-grade traceability requirements.
Product Type:
After-sales service intensity varies dramatically across extraction grades, with organic and pharmaceutical-grade products demanding batch-specific technical support and certification documentation.
- Organic Grade:Certified solvent-free extraction meets EU organic regulation 2018/848 and NSF/ANSI 305 standards for cosmetic and food applications. Clean-label procurement policies at French fragrance houses and German natural cosmetics brands concentrate demand here, though multi-jurisdiction certification extends lead times.
- Natural Extract:Solvent-derived resinoid standardized to specific fold strengths, typically 5X to 20X concentration for consistent vanillin content. Beverage manufacturers in North America and premium ice cream producers in Italy anchor volume procurement, with Madagascar-origin material commanding traceability premiums.
- Synthetic Compound:Guaiacol-derived or lignin-based vanillin alternatives standardized for cost-sensitive processed food segments.
- Food Grade:FDA 21 CFR 169 compliant extract for commercial bakery and confectionery applications with lower purity thresholds.
Natural Extract holds the largest share; momentum sits with Organic Grade.
Application:
Cost tier stratification separates commodity flavor dosing from premium fragrance formulation, with purity documentation burden scaling directly with dermal exposure risk.
- Fragrance:Haute parfumerie formulations in France require intact aromatic complexity preserved through supercritical CO2 extraction. EU REACH allergen documentation mandates comprehensive residue testing, compressing supplier bases to vertically integrated Madagascar processors with in-house analytical capabilities.
- Cosmetics:Dermal-grade oleoresin demands USP or ISO 16128 compliant purity with heavy metal and pesticide screening. Premium pricing reflects this documentation burden, with German and Swiss natural cosmetics brands driving specification tightening.
- Food & Beverage:Volume-dominant segment spanning vanilla-flavored dairy, baked goods, and beverage applications with standardized fold strengths.
- Pharmaceuticals:High-purity grades for oral dosage flavor masking meeting USP-NF monograph requirements.
Food & Beverage generates the highest volume; Fragrance commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with flavor houses and pharmaceutical companies negotiating multi-year forward agreements while cosmetic brands prioritize spot flexibility for limited-edition launches.
- Flavor Houses:Symrise AG and Givaudan SA anchor procurement through direct Madagascar cooperative contracts, bypassing commodity traders. Technical service requirements include customized fold strength formulation and application-specific stability testing for beverage and dairy clients.
- Cosmetic Brands:L'Oréal and Estée Lauder procurement policies mandate Fair Trade and organic certification, concentrating supply among audited Madagascar cooperatives with transparent farmer pricing.
- Food Manufacturers:Industrial bakery and confectionery processors purchasing standardized food-grade extract through distributor networks.
- Pharmaceutical Companies:Pediatric formulation specialists requiring USP-grade material with validated supply chain documentation.
Flavor Houses hold the largest share; momentum is concentrating with Cosmetic Brands.
Distribution Channel:
Supply concentration in Madagascar SAVA region shapes channel configuration, with direct sales dominating high-volume procurement and distributors serving fragmented mid-scale buyers.
- Direct Sales:Multi-year forward contracts between Madagascar cooperatives and European fragrance houses or North American flavor houses. Price stability and traceability documentation justify the administrative burden for buyers above 10-ton annual volume thresholds.
- Distributors:Regional chemical and specialty ingredient distributors stock standard food-grade material for mid-scale food manufacturers lacking procurement infrastructure.
- Wholesalers:Commodity traders aggregating spot-market vanilla bean supply for smaller processors.
- Online Retail:E-commerce platforms serving artisanal food producers and natural cosmetics startups with small-batch organic certified material.
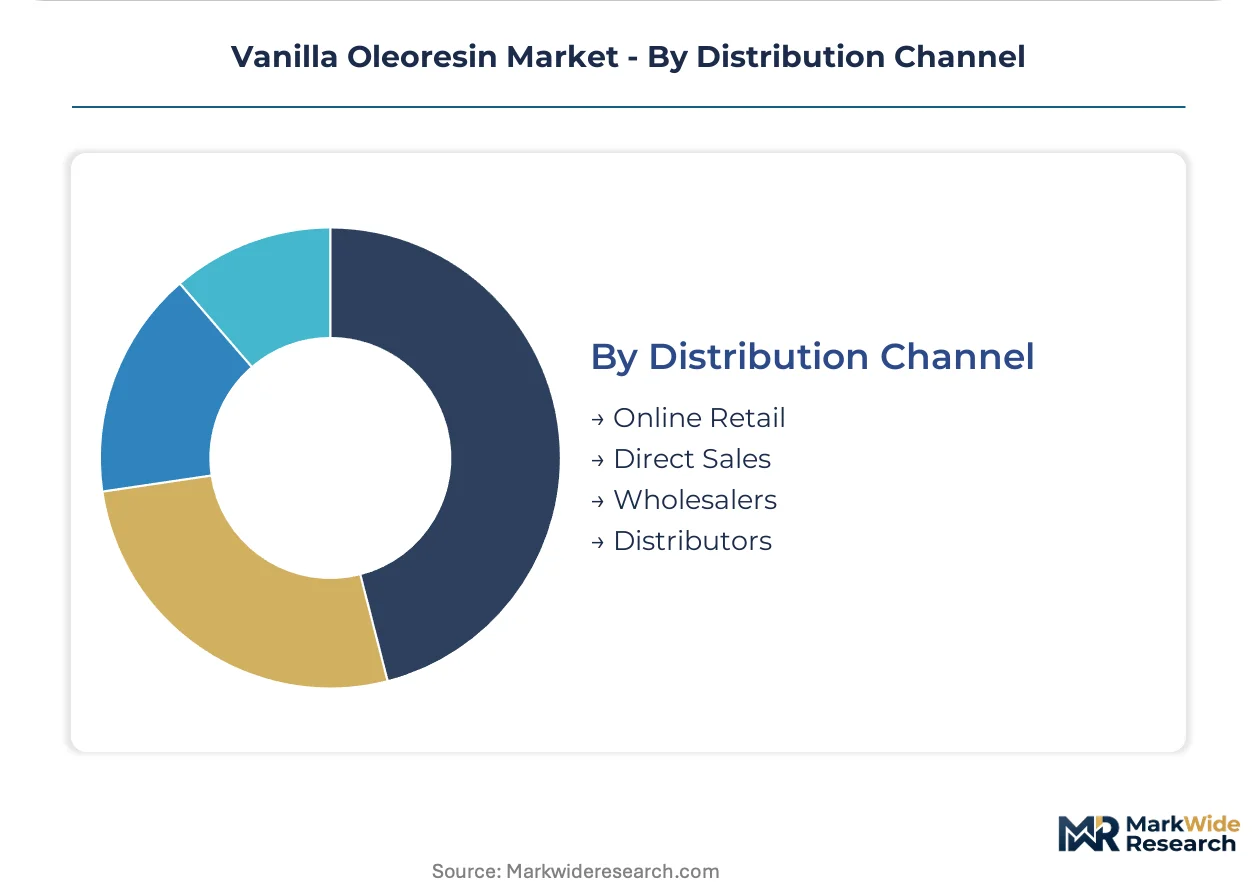
Direct Sales dominates value capture; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consuming regions. European fragrance houses absorb Madagascar-origin premiums with minimal volume contraction, while North American food manufacturers shift toward synthetic alternatives when spot prices spike above contract thresholds.
France
Haute parfumerie houses in Paris and Grasse drive dermal-grade oleoresin procurement at 20-30% price premiums over food-grade material. ANSM enforces EU REACH documentation for allergen traceability, compressing supplier bases to vertically integrated Madagascar processors. The Grasse fragrance cluster concentrates formulation R&D for CO2-extracted resinoids requiring intact aromatic complexity.
Germany
Natural cosmetics brands in Hamburg and Munich mandate Fair Trade and organic certification under BDIH and COSMOS standards. ECHA compliance costs for botanical extract residue documentation run 12-18% above baseline import expenses. Bavaria's food technology institutes partner with Madagascar cooperatives on vanillin stability research for dairy applications.
United States
Beverage manufacturers in California and Wisconsin negotiate multi-year forward contracts directly with SAVA region cooperatives. FDA 21 CFR 169 identity standards govern vanilla-derived product labeling, shaping import documentation requirements. Chicago-area flavor houses anchor industrial oleoresin formulation services for processed food clients seeking standardized fold strengths.
India
Domestic ice cream and confectionery processors in Maharashtra and Gujarat import Madagascar-origin material through Mumbai port infrastructure. FSSAI food safety standards align with CODEX guidelines for vanilla extract purity thresholds. Kerala-based spice trading houses are developing Uganda-origin alternative supply channels to reduce Madagascar dependency.
Madagascar
SAVA region cultivation accounts for the majority of global vanilla orchid output, with Antalaha and Sambava hosting primary curing and extraction infrastructure. Cyclone frequency in the Mozambique Channel disrupts harvest cycles at 3-5 year intervals. Government-backed farmer cooperative consolidation programs aim to standardize post-harvest processing quality for export-grade oleoresin.
Vanilla Oleoresin Market Competitive Landscape
Capability concentration sits with specialized extraction technology holders; scale advantage sits with diversified flavor and fragrance conglomerates. The market structures around three tiers: Madagascar-origin processors with captive bean supply, European fragrance houses with proprietary CO2 extraction assets, and commodity traders aggregating spot-market volume. Dominant competitive moves include backward integration into Madagascar cooperative equity stakes and technology licensing agreements for supercritical extraction equipment.
Within the diversified flavor house tier, Symrise AG and Givaudan SA exemplify procurement strategies built on direct Madagascar cooperative relationships. McCormick & Company, Inc. occupies a position bridging retail-grade extract distribution with industrial oleoresin supply to North American food manufacturers. These three entities represent distinct archetypes: European fragrance-integrated processors, diversified taste-and-nutrition conglomerates, and vertically oriented spice specialists.
| Leading Market Players |
|---|
| Symrise AG |
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| McCormick & Company, Inc. |
| Nielsen-Massey Vanillas, Inc. |
| dsm-firmenich |
| Sensient Technologies Corporation |
| Eurovanille |
| Synthite Industries Ltd |
| Others |
Value Network & Pricing Analysis
Undercapacity in Madagascar's SAVA region curing facilities during post-cyclone recovery periods concentrates pricing power among cooperatives with functional infrastructure, forcing flavor houses to accept steeper forward-contract premiums or sacrifice volume commitments.
Pricing Analysis
Long-term offtake agreements between European fragrance houses and Madagascar cooperatives anchor the pricing architecture, with spot-market purchases commanding 15-25% premiums during supply disruptions. Price differentiation rests on organic certification tier and supercritical CO2 extraction capability, with dermal-grade material bearing heavier documentation costs. Pricing pressure stems from synthetic vanillin substitution in cost-sensitive processed food segments, compressing natural extract margins. North American beverage manufacturers exhibit highest price sensitivity, while French haute parfumerie houses absorb Madagascar-origin premiums with minimal volume contraction.
Supply Chain Analysis
Extraction capacity concentrates among Symrise AG and Givaudan SA's Madagascar cooperative networks, with secondary processing clusters in France and Germany serving pharmaceutical-grade refinement. Raw material dependencies center on Madagascar vanilla orchid pods, food-grade ethanol solvents, and supercritical CO2 equipment components. Single-source vulnerability in the SAVA region creates acute disruption risk from cyclone damage to curing infrastructure. Distribution runs through direct sales contracts for volume buyers above 10-ton thresholds, with regional distributors serving fragmented mid-scale food manufacturers lacking procurement infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification documentation services and application-specific formulation partnerships are expanding faster than commodity extract supply, creating recurring-revenue layers that stabilize margin profiles across volatile bean price cycles.
For Market Incumbents: Insulate core Madagascar supply positions through cooperative equity stakes and curing facility infrastructure investment, countering emerging Uganda-origin entrants. Prioritize supercritical CO2 extraction technology licensing to preserve aromatic complexity premiums against solvent-based competitors. Lock in multi-year pharmaceutical excipient contracts before USP-grade capacity expansion saturates that tier.
For New Entrants and Emerging Players: Establish a beachhead in online retail channels serving artisanal cosmetics startups with small-batch organic certified material, bypassing entrenched distributor relationships. Target German natural cosmetics brands with BDIH-compliant documentation packages, as established players underinvest in mid-scale customer technical service. Differentiate through rapid-turnaround certification timelines that compress clean-label product launch cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across supercritical extraction equipment as Chinese manufacturers enter the specialist equipment tier, compressing technology-holder margins. Acquisition candidates with captive Madagascar cooperative relationships and in-house EU REACH documentation capabilities offer defensible positioning through the projection horizon. Monitor cyclone frequency indices and Antalaha infrastructure damage assessments as supply-driven pricing inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Madagascar Cooperatives | Secures bean supply priority during cyclone-disrupted harvest cycles. |
| Supercritical CO2 Extraction Licensing | Preserves volatile aromatic compounds for haute parfumerie formulations. |
| Pharmaceutical USP-Grade Certification | Opens pediatric formulation flavor masking applications. |
| EU REACH Documentation Digitization | Compresses batch traceability timelines for cosmetic brand procurement. |
| Uganda Origin Development Partnership | Diversifies supply geography with shorter European freight routes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across extraction technology providers, Madagascar cooperative managers, European fragrance house procurement directors, and North American flavor house formulation chemists. Secondary validation drew from ECHA REACH guidance documents, FDA 21 CFR 169 standards, FAO trade statistics, and Madagascar Ministry of Agriculture crop reports. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down consumption data from end-use industry associations.
Calibration across historical price volatility periods and cyclone disruption events anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include extraction grade tier, application purity requirement, end-user contract structure, and regional regulatory cluster. CAGRs were derived from normalized growth trajectory analysis across these dimensions, with specific inputs from vanilla orchid yield projections and synthetic vanillin substitution elasticity estimates.
Stress conditions across SAVA region cyclone frequency, ethanol commodity price spikes, and EU documentation requirement tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Madagascar infrastructure investment continuity and alternative origin development pace. Quarterly review of Antalaha curing facility operational status and Uganda cultivation expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Carvone Market