
 Global Paprika Oleoresin Market | 2026-2036
Global Paprika Oleoresin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paprika Oleoresin Market Outlook
Supercritical CO2 extraction is fragmenting the traditional solvent-based production landscape across paprika oleoresin supply chains. Synthite Industries Ltd. leverages its Kerala processing infrastructure to dominate bulk conventional output. AVT Natural Products anchors organic-grade supply through certified farm partnerships in southern India. Sensient Technologies Corporation competes on color stability patents for beverage applications.
Paprika oleoresin is a lipophilic extract derived from Capsicum annuum fruits, containing carotenoid pigments—principally capsanthin and capsorubin—at standardized color values between 40,000 and 100,000 CU, produced via solvent extraction or supercritical CO2 methods for use as a natural colorant in food, cosmetic, and pharmaceutical matrices. The conventional product type still occupies the largest volume share, though organic certification is accelerating fastest among European and North American buyers who navigate stricter additive disclosure rules. Supercritical CO2 extraction commands premium positioning as solvent-free labeling aligns with EFSA and FDA clean-label guidance, while steam distillation retains cost advantages in commodity-grade Asian markets.
EFSA coloring additive standards, FDA GRAS self-affirmation pathways, and India BIS spice extract specifications collectively shape formulation choices and cross-border shipment compliance burdens. EU REACH chemical registration requirements further constrain synthetic paprika colorant entrants seeking European market access. Stakeholders must monitor extraction technology cost curves against evolving natural-claim enforcement thresholds in major import jurisdictions.
Market Dynamics
Supercritical CO2 extraction technology is compressing margins for solvent-based processors while EFSA clean-label mandates force European food manufacturers to audit supply chains for residual hexane and acetone traces.
Growth Catalysts
- EFSA additive transparency mandates:EU Regulation 1333/2008 revisions compel packaged food producers to disclose extraction methods, accelerating procurement of solvent-free oleoresin grades for sauces and seasonings.
- Capsanthin stability patents:Encapsulation technologies for beverage color retention unlock carbonated soft drink and ready-to-drink cocktail applications previously closed to paprika derivatives.
- Kerala cluster infrastructure:Concentrated drying and milling capacity within 50 kilometers of Kochi port reduces raw material transit losses for exporters serving Rotterdam and Hamburg.
Market Restraints
- Capsicum annuum harvest volatility:Monsoon timing variations across Guntur and Warangal districts create 15-30% annual price swings for dried paprika feedstock.
- Supercritical equipment capex thresholds:500-liter CO2 extraction vessels require $2-4 million upfront investment, excluding mid-tier Indian processors from premium-grade certification.
- Synthetic carotenoid substitution:DSM and BASF astaxanthin and beta-carotene formulations compete on cost-per-color-unit for processed meat and poultry skin applications.
Strategic Opportunities
- USDA Organic certification gaps:Fewer than twelve Indian extraction facilities hold NOP organic accreditation, creating first-mover advantage for compliant entrants targeting Whole Foods and Sprouts procurement networks.
- Cosmetic matrix compatibility:Liposomal delivery systems for capsorubin integration into sun care and color cosmetics remain underdeveloped relative to food-grade applications.
- Japan MHLW positive list expansion:Pending inclusion of paprika oleoresin in quasi-drug colorant registers would open dermocosmetic channels through Shiseido and Kao supply chains.
Industry Challenges
- Supercritical CO2 technician scarcity:Indian chemical engineering programs produce fewer than 200 graduates annually with pressure-system operation credentials required for 300-bar extraction environments.
- Batch-to-batch color standardization:Natural capsanthin degradation curves vary by harvest moisture content, forcing processors to hold 90-day inventory buffers for CU testing completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paprika Oleoresin Market |
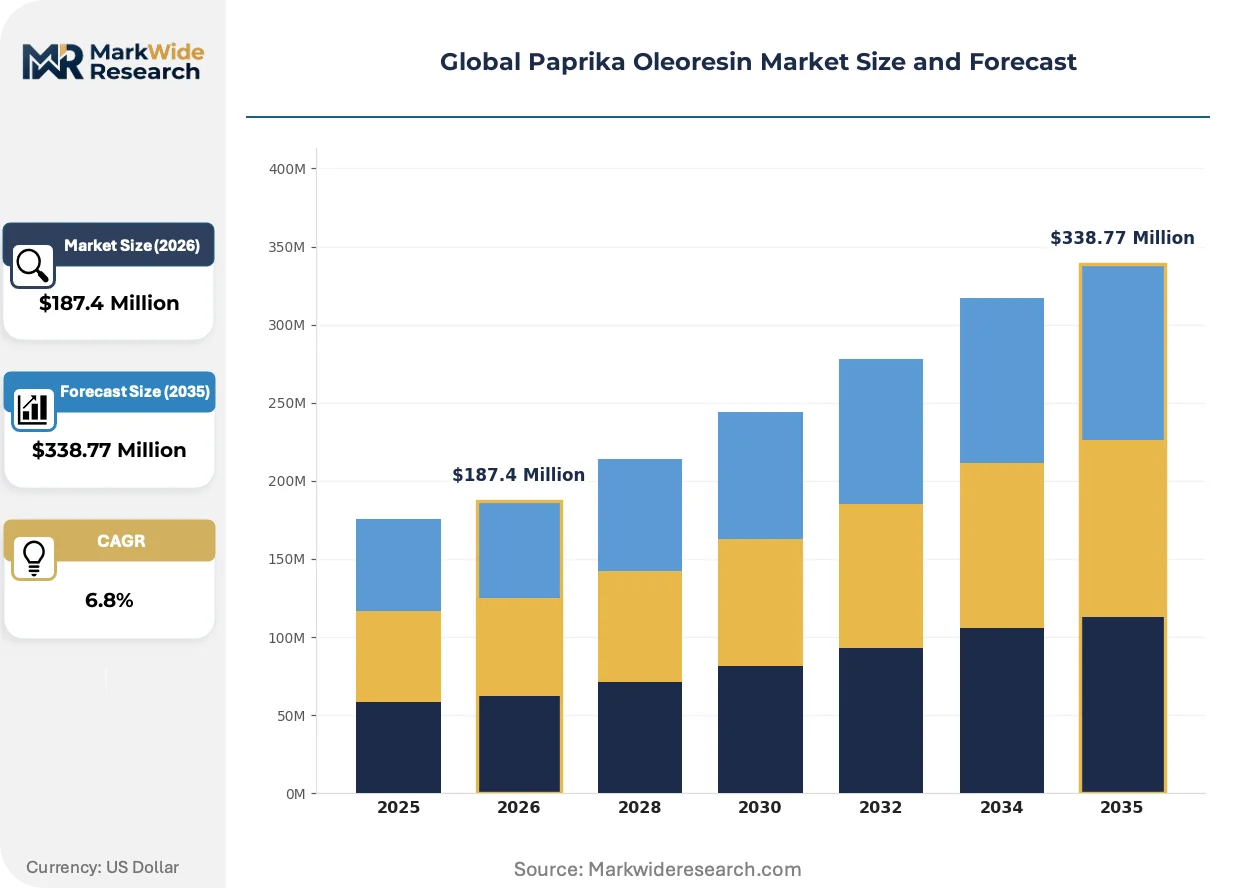
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Organic, Natural, Synthetic Extraction Method: Solvent Extraction, Steam Distillation, Cold Pressing, Supercritical CO2 Extraction Application: Food Industry, Cosmetic Industry, Pharmaceutical Industry, Nutraceuticals Form: Powder, Liquid, Granulated, Paste |
| Companies Covered | Sensient Technologies Corporation, AVT Natural Products, Kalsec, Inc., Universal Oleoresins, Givaudan, Synthite Industries Ltd., Plant Lipids Private Limited, Akay Group Ltd., Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paprika Oleoresin Market Strategic Shifts
Clean-label enforcement is fragmenting procurement specifications across European retail channels while extraction technology costs compress the viable processor base to capital-intensive specialists.
Supercritical CO2 systems with integrated online spectrophotometric monitoring enable real-time color value adjustment during extraction runs. Premium sauce manufacturers in France and Germany now specify CO2-only certificates of analysis, rendering obsolete hexane-extracted oleoresin for private-label contracts. This technological divide is splitting the supplier base into solvent-free certified tier and commodity solvent processors.
EU REACH Annex XVII updates now require full supply chain disclosure for food-contact substances derived from botanical extraction. Specialty ingredient distributors in the Netherlands and Belgium are consolidating procurement through single-source CO2-certified suppliers to minimize SVHC screening costs. The regulatory burden falls heaviest on small-scale Spanish and Italian importers lacking in-house compliance teams.
Direct contracting between European end-users and Kerala processing clusters is displacing layered trading house intermediaries. Large meat processors in Germany now negotiate annual offtake agreements with Synthite and AVT for specified CU grades, bypassing Hamburg spice traders. This channel compression is most advanced in sausage casing and processed poultry applications where color consistency carries brand risk.
Global Paprika Oleoresin Market Segmentation
Paprika oleoresin procurement specifications diverge sharply across end-use matrices, with extraction method and certification grade serving as the primary commercial sorting mechanisms. Formulators in beverage and cosmetic applications impose distinct stability and solubility requirements that reshape supplier qualification criteria.
Product Type:
Mature commodity grades anchor volume throughput while emerging certification tiers capture margin expansion in premium channels.
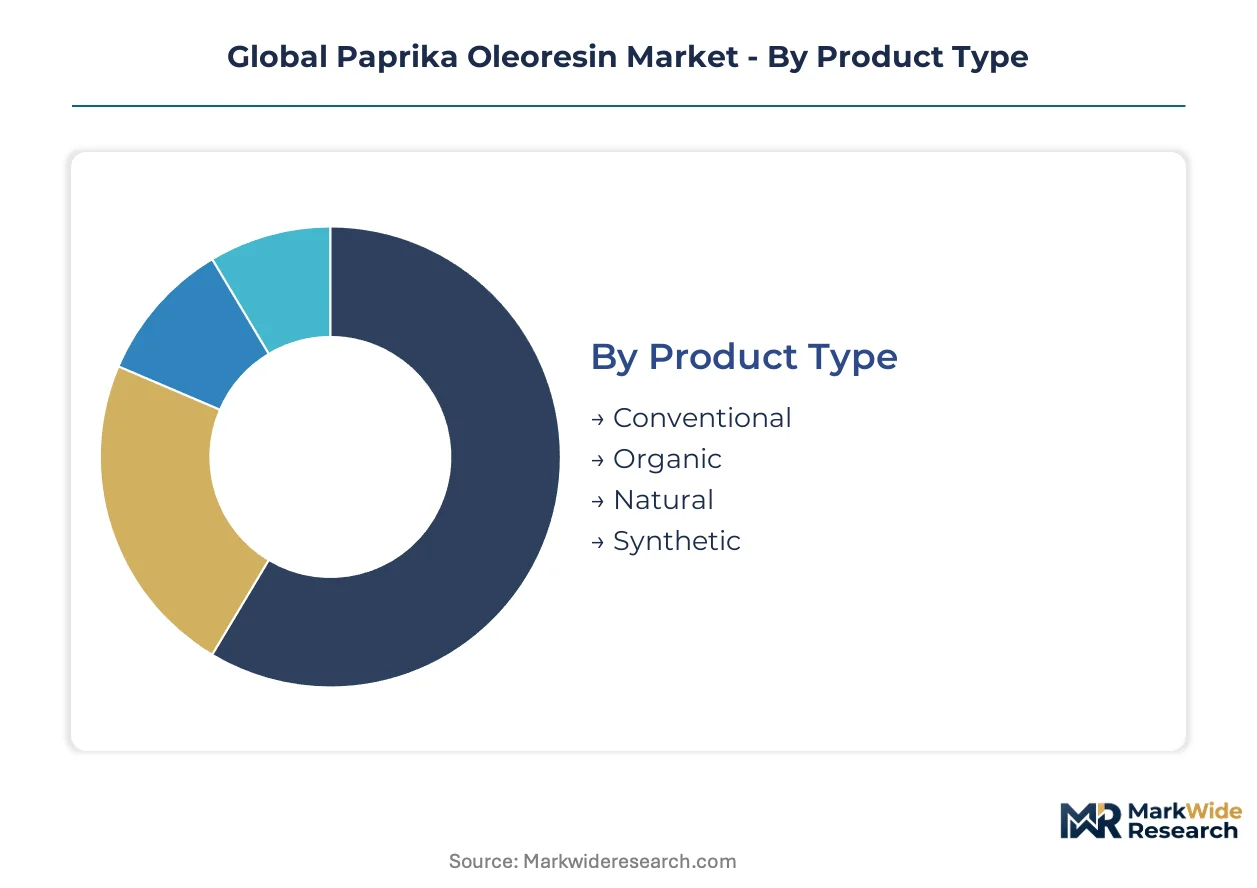
- Conventional:Hexane-extracted oleoresin standardized at 40,000–100,000 CU dominates processed meat, snack seasoning, and institutional foodservice procurement. Indian processors in Kerala and Guntur supply bulk contracts to European sausage manufacturers under BIS spice extract specifications, though EFSA disclosure mandates now pressure residual solvent documentation.
- Organic:NOP-accredited and EU Organic-certified grades command 40–60% price premiums in North American natural retail channels. Fewer than twelve Indian extraction facilities hold dual accreditation, creating supply bottlenecks for Whole Foods and Sprouts procurement networks seeking clean-label colorant security.
- Natural:Non-certified but solvent-free claims target mid-tier private-label manufacturers navigating between commodity pricing and full organic compliance.
- Synthetic:Laboratory-synthesized carotenoid mimics face REACH registration barriers and clean-label substitution pressure across European retail.
Conventional retains volume leadership; Organic holds the steepest expansion curve.
Extraction Method:
Capital intensity stratifies processor capabilities into equipment-constrained tiers with divergent certification access.
- Solvent Extraction:Hexane and acetone-based processing remains cost-advantaged for commodity-grade output serving Asian markets with less stringent residual solvent thresholds. Synthite Industries leverages Kochi-port proximity to minimize feedstock transit losses for bulk export contracts.
- Supercritical CO2 Extraction:300-bar pressure systems yield solvent-free oleoresin qualifying for EFSA clean-label disclosure exemptions. $2–4 million vessel capex excludes mid-tier Indian processors from premium-grade certification, concentrating supply among capital-intensive specialists.
- Steam Distillation:Lower equipment thresholds preserve competitiveness in price-sensitive Asian food manufacturing segments.
- Cold Pressing:Mechanical extraction without thermal degradation targets high-end cosmetic applications requiring unoxidized capsanthin integrity.
Solvent extraction retains volume leadership; Supercritical CO2 extraction holds the steepest expansion curve.
Application:
End-use technical requirements fragment procurement specifications across stability, regulatory pathway, and matrix compatibility dimensions.
- Food Industry:Sauces, seasonings, and processed meat applications consume the majority of standardized CU grades. Encapsulation patents for beverage color retention now unlock carbonated soft drink and ready-to-drink cocktail segments previously closed to paprika derivatives.
- Cosmetic Industry:Liposomal delivery systems for capsorubin integration into sun care and color cosmetics remain underdeveloped relative to food-grade applications, presenting formulation partnership opportunities.
- Pharmaceutical Industry:Excipient-grade specifications for tablet coating and capsule coloration require GMP-compliant extraction documentation.
- Nutraceuticals:Capsanthin antioxidant claims in dietary supplements face varying substantiation requirements across FDA GRAS self-affirmation and Japan MHLW quasi-drug pathways.
Food Industry retains volume leadership; Cosmetic Industry holds the steepest expansion curve.
Form:
Physical state selection depends on manufacturing integration requirements and shelf-stability specifications in target matrices.
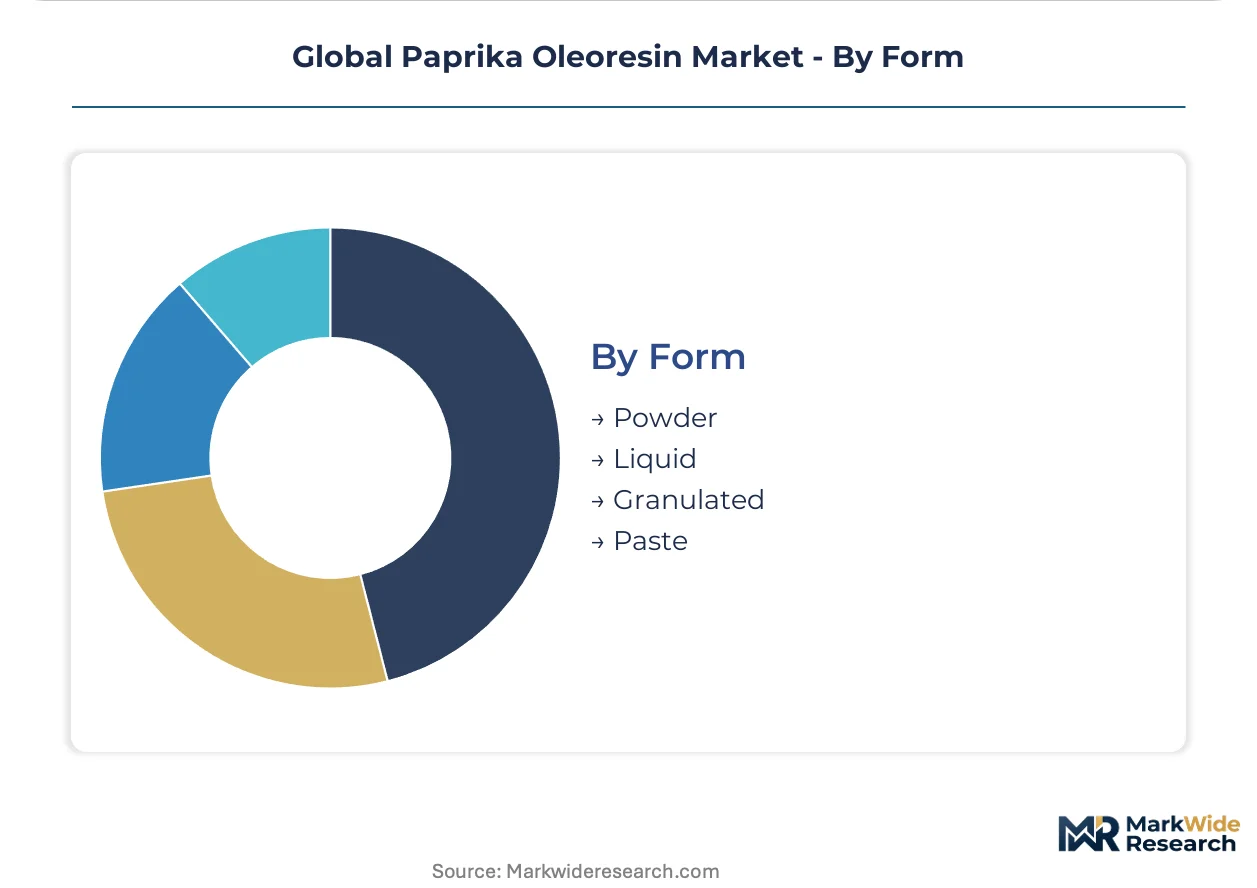
- Powder:Spray-dried encapsulated formats dominate seasoning blends and dry mix applications requiring extended shelf stability.
- Liquid:Oil-dispersed oleoresin serves wet sauce manufacturing and direct beverage dosing with simplified handling protocols.
- Granulated:Free-flowing agglomerated forms reduce dusting issues in high-speed meat processing lines.
- Paste:High-concentration semi-solid formats target artisanal sausage casing and specialty condiment producers.
Powder retains volume leadership; Liquid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian processors in Kerala ship bulk oleoresin consignments to Rotterdam and Hamburg under BIS spice extract specifications, while EFSA disclosure mandates reshape European procurement patterns toward solvent-free certified grades.
Germany
Sausage casing manufacturers and processed poultry processors drive standardized CU grade demand. EFSA Regulation 1333/2008 revisions compel extraction method disclosure on packaged food labels. Direct annual offtake agreements between meat processors and Kerala exporters now bypass Hamburg spice traders entirely.
United States
Natural retail channels and clean-label beverage formulators seek NOP-accredited organic grades. FDA GRAS self-affirmation pathways govern capsanthin antioxidant claims in dietary supplements. Whole Foods and Sprouts procurement networks face supply bottlenecks from fewer than twelve dual-accredited Indian extraction facilities.
India
Kerala spice belt concentration anchors global extraction capacity near Kochi port infrastructure. BIS spice extract specifications align with EU export requirements while FSSAI domestic standards govern local food manufacturing. Synthite Industries and AVT Natural Products dominate bulk conventional and organic-grade output respectively from Guntur and Warangal feedstock zones.
Netherlands
Specialty ingredient distributors consolidate procurement through single-source CO2-certified suppliers to minimize SVHC screening costs under EU REACH Annex XVII. Rotterdam port handling facilities serve as the primary European entry point for Indian oleoresin shipments. Dutch trading houses face margin compression from direct contracting trends between end-users and Kerala processors.
Japan
Cosmetic formulators await MHLW quasi-drug colorant register expansion for dermocosmetic applications. METI industrial standards influence excipient-grade specifications for pharmaceutical tablet coating. Shiseido and Kao supply chains represent prospective channels pending regulatory pathway clarification for capsorubin liposomal delivery systems.
Global Paprika Oleoresin Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated supplier base. The market structure stratifies between capital-intensive supercritical CO2 operators and solvent-based commodity processors. Three archetypes dominate: Kerala-anchored bulk extractors with port-proximate infrastructure, North American patent-holders on color stability technologies, and European flavor houses with integrated distribution networks. Competitive moves concentrate on direct annual offtake contracting and organic certification acquisition.
Within the Kerala-based extraction tier, Synthite Industries Ltd. and AVT Natural Products occupy positions as volume anchors serving European meat processors and North American natural retail channels respectively. Sensient Technologies Corporation exemplifies the patent-driven stability specialist archetype. Among diversified flavor and fragrance conglomerates, Givaudan and Döhler GmbH represent integrated solution providers with cross-portfolio colorant capabilities.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| AVT Natural Products |
| Kalsec, Inc. |
| Universal Oleoresins |
| Givaudan |
| Synthite Industries Ltd. |
| Plant Lipids Private Limited |
| Akay Group Ltd. |
| Döhler GmbH |
| Others |
Value Chain & Pricing Dynamics
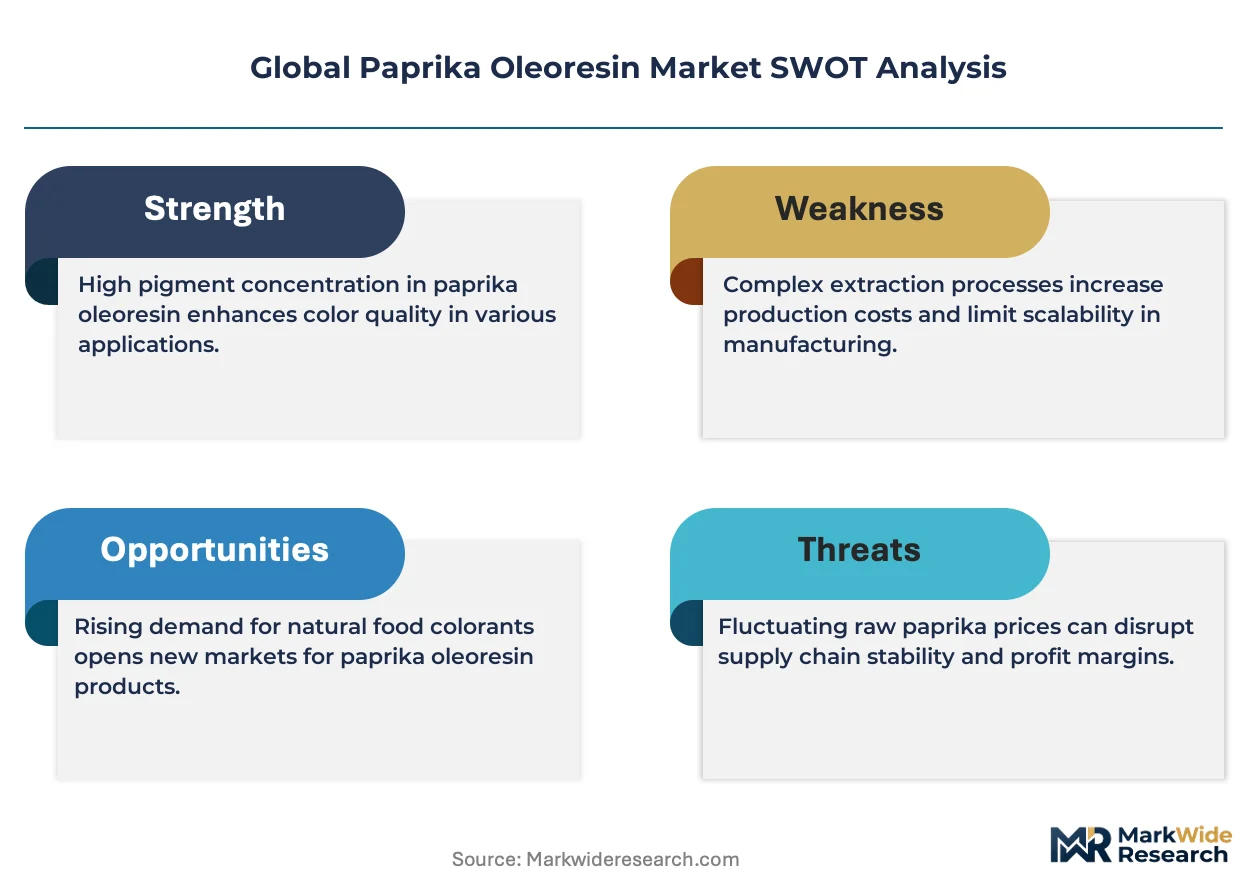
Monsoon-driven feedstock volatility across Guntur and Warangal districts compresses margin buffers for solvent-based processors while simultaneously widening the premium commanded by CO2-certified grades. This climate risk vector determines both the steepness of price spreads between conventional and organic tiers and the geographic clustering of extraction capacity around Kerala port infrastructure.
Pricing Analysis
The solvent-to-supercritical technology-generation pricing gap stratifies procurement tiers across European meat processors and North American natural retail channels. Three-tier pricing structure across premium CO2-certified, standard solvent-extracted, and economy-grade Asian commodity levels reflects extraction equipment capex thresholds and certification audit costs. Pricing pressure stems from synthetic carotenoid substitution by DSM and BASF formulations in processed meat applications. Institutional foodservice buyers exhibit highest price sensitivity, while clean-label beverage formulators accept substantial premiums for solvent-free documentation.
Supply Chain Analysis
Capsicum annuum harvests from Guntur and Warangal districts in India feed concentrated drying and milling clusters within 50 kilometers of Kochi port. Raw material sourcing draws from monsoon-dependent agricultural zones, hexane and acetone solvent supplies, and imported supercritical CO2 extraction vessel components. Single-source vulnerability concentrates in Kerala-based processing infrastructure serving Rotterdam and Hamburg entry points. Distribution runs through direct annual offtake agreements between German meat processors and Indian exporters, displacing layered Dutch and Belgian trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service models for organic and CO2-grade compliance represent the fastest-expanding recurring revenue layer, outpacing commodity oleoresin volume growth as European retailers demand audit-ready supply chain documentation.
For Market Incumbents: Insulate margin position by acquiring dual NOP-EU Organic accreditation ahead of Whole Foods and Sprouts procurement network expansion, while deploying backward integration into Guntur feedstock drying infrastructure to buffer monsoon price volatility. Synthite Industries and AVT Natural Products demonstrate the defensive value of Kerala port-proximate capacity clusters. For New Entrants and Emerging Players: USDA Organic certification gaps among Indian extraction facilities represent the most penetrable entry point, with fewer than twelve dual-accredited suppliers currently serving North American natural retail channels. Cosmetic matrix compatibility for capsorubin liposomal delivery systems offers formulation partnership angles with Shiseido and Kao supply chains pending Japan MHLW quasi-drug register expansion. For Investors and Strategic Acquirers: EFSA Regulation 1333/2008 disclosure mandate implementation reshapes the acquisition landscape toward solvent-free certified processor targets with established European meat processor relationships. Long-term viability hinges on supercritical CO2 technician pipeline development and 300-bar extraction equipment operational track records. Monitor Japan MHLW positive list expansion timelines as dermocosmetic channel inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Organic Certification Acquisition | NOP-EU Organic accreditation unlocks Whole Foods and Sprouts procurement network access. |
| Backward Integration into Feedstock Drying | Guntur and Warangal drying infrastructure buffers monsoon-driven price volatility. |
| Supercritical CO2 Capacity Expansion | 300-bar extraction systems qualify for EFSA clean-label disclosure exemptions. |
| Cosmetic Formulation Partnership | Capsorubin liposomal delivery development targets Shiseido and Kao supply chains. |
| Direct Annual Offtake Contracting | Bypassing Rotterdam and Hamburg trading houses captures margin from channel compression. |
Study Parameters
Operator-level perspectives from extraction plant managers, European meat processor procurement leads, Kerala spice trading house executives, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from BIS spice extract specifications, EU REACH Annex XVII updates, FDA GRAS self-affirmation filings, and India FSSAI domestic standards. Bottom-up volume modeling across extraction facilities triangulated against top-down demand aggregation from end-use industries.
Scenario-bracketing around monsoon variability and regulatory enforcement intensity framed the projection horizon. Segmentation dimensions modeled include product certification tier, extraction method, application matrix, and regional regulatory cluster. CAGRs derived from facility capacity expansion announcements cross-referenced against EFSA and FDA guidance trajectory assumptions. Capsanthin stability patent filings and supercritical equipment import records informed technology adoption curve calibration.
Practitioners should monitor India Meteorological Department monsoon forecasts and EFSA enforcement action disclosures for early signals requiring forecast reassessment. Cross-checking against Rotterdam port oleoresin shipment manifests and Hamburg spice trader inventory reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Global Artichoke Extract Market