
 1-Decanol Market | 2026-2036
1-Decanol Market Size, Share, and Industry Trends Forecast 2026-2036
1-Decanol Market Analysis
The gap between pharmaceutical-grade and industrial-grade 1-decanol is rebalancing as purity premiums widen and commodity margins compress. Sasol leverages its Fischer-Tropsch synthesis expertise to anchor supply of high-purity material for regulated applications. KLK OLEO competes through backward integration into Malaysian palm kernel oil streams, while Emery Oleochemicals differentiates via oleochemical specialization across North American and European facilities.
1-Decanol is a ten-carbon primary fatty alcohol with a molecular weight of 158.28 g/mol, typically derived from natural fats and oils through hydrogenolysis or petrochemical routes via hydroformylation, serving as a versatile intermediate for surfactants, plasticizers, and lubricant additives. Industrial grade dominates volume flows into chemical processing and solvent applications, whereas pharmaceutical and cosmetic grades command concentrated margin pools due to stringent impurity limits. The surfactant application segment leads absolute consumption, while emulsifier demand within personal care end users exhibits the fastest structural expansion.
EPA standards under the Toxic Substances Control Act and REACH registration requirements in Europe shape product specifications and market access conditions for imported 1-decanol. FDA oversight of cosmetic and pharmaceutical-grade material further segments compliance obligations across end-use categories. Stakeholders must monitor evolving bio-based content mandates and feedstock traceability rules that will determine competitive positioning in specialty versus commodity tiers.
Market Dynamics
Feedstock proximity in Southeast Asian palm oil clusters is compressing supply chains for natural-route 1-decanol while Fischer-Tropsch producers defend margin pools through purity differentiation in regulated end uses.
Growth Catalysts
- REACH registration tiering:ECHA's updated substance evaluation protocols are accelerating pharmaceutical-grade qualification timelines for European importers.
- Surfactant formulation expansion:Personal care manufacturers in Southeast Asia are scaling emulsifier applications for skin-care and hair-care product lines.
- Malaysian palm kernel oil concentration:Proximity to integrated oleochemical processing infrastructure is shortening feedstock-to-alcohol conversion cycles.
Market Restraints
- Crude palm oil price volatility:Natural-route producers face margin compression when CPO benchmarks spike above synthetic paraffin alternatives.
- Indonesian export licensing concentration:A narrow base of approved bulk chemical exporters creates bottleneck risk for spot-market buyers.
- Technical impurity floors:Hydrogenolysis processes struggle to achieve sub-50 ppm heavy-metal specifications required for injectable-grade applications.
Strategic Opportunities
- Brazilian bio-based mandates:ANVISA's forthcoming green chemistry incentives will open import channels for certified-sustainable fatty alcohols.
- Biodegradable lubricant additives:Convergence of ester chemistry and 1-decanol backbone modification is creating new synthetic base-stock formulations.
- Direct-to-compounder distribution:Bypassing traditional distributor networks allows producers to capture formulation-specification premiums in North American specialty chemical markets.
Industry Challenges
- Specialized hydrogenation engineering talent:The shortage of process engineers experienced in high-pressure catalytic hydrogenolysis is extending plant commissioning timelines.
- Multi-jurisdiction certification sequencing:Simultaneous FDA, REACH, and ISO 16128 filings for cosmetic-grade material create administrative bottlenecks.
- Legacy ERP integration with batch-traceability systems:Retrofitting palm oil provenance tracking into existing manufacturing execution platforms demands significant capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Decanol Market |
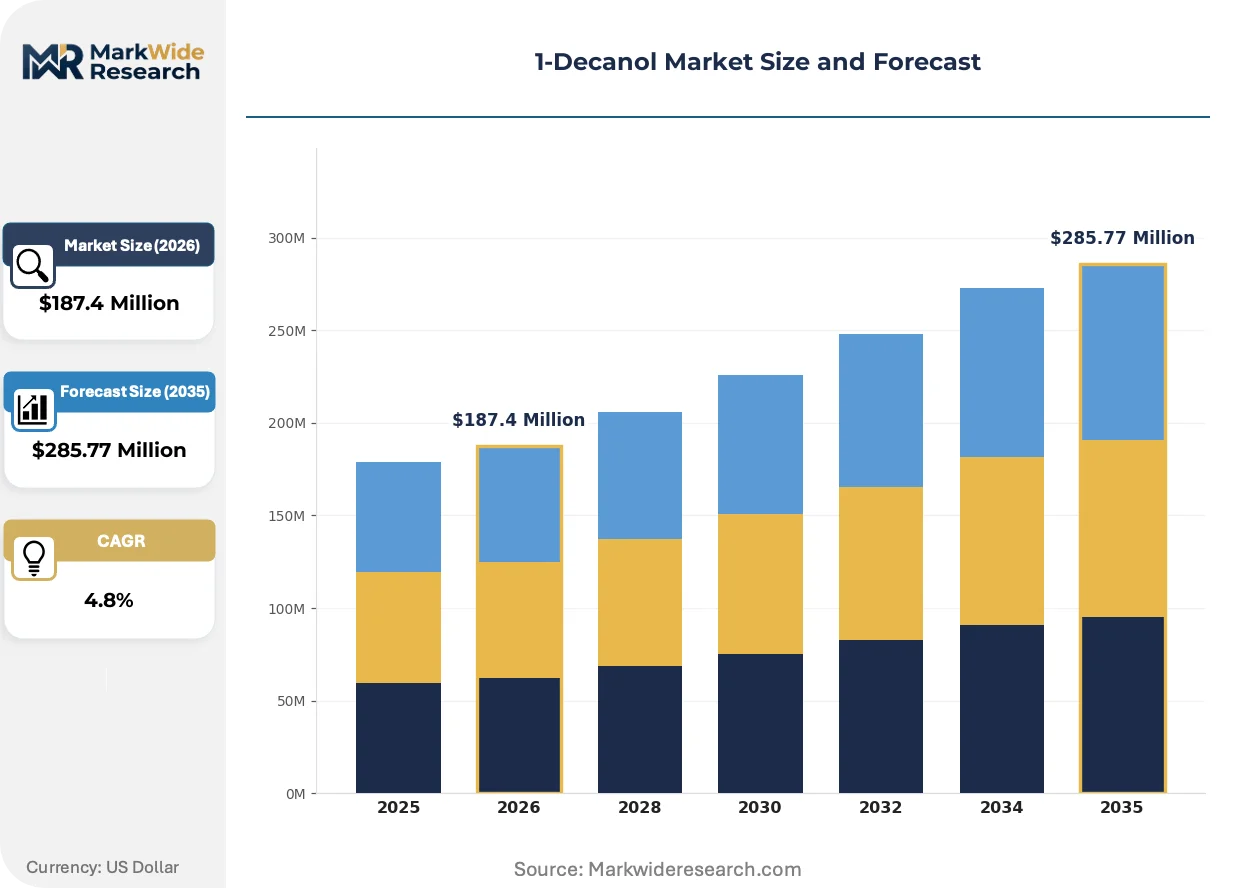
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Food Grade Application: Surfactants, Solvents, Emulsifiers, Lubricants End User: Personal Care, Pharmaceuticals, Food & Beverage, Chemicals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Wilmar International, Musim Mas Group, Sasol, VVF LLC, Godrej Industries, Emery Oleochemicals, KLK OLEO, BASF SE, IOI Oleochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Decanol Market Emerging Trajectories
Process intensification and regulatory data transparency are restructuring how 1-decanol producers compete on specification documentation and supply-chain verification rather than commodity volume alone.
Continuous-flow hydrogenolysis reactor technology is automating temperature and pressure control in fatty alcohol conversion. European specialty chemical producers are retrofitting batch plants with skid-mounted continuous units to reduce catalyst consumption per ton. This automation is compressing unit economics for mid-scale producers competing against integrated palm oil refiners.
EPA's forthcoming modernization of Toxic Substances Control Act Section 8 reporting will mandate enhanced substance identity disclosure for imported fatty alcohols. Chemical importers must now maintain granular compositional data across carbon-chain distribution profiles. Personal care formulators sourcing US-bound material are restructuring supplier qualification protocols to preempt compliance gaps.
Specification-driven procurement now dominates surfactant buyer behavior in European and North American markets. Large personal care multinationals are consolidating supplier panels around producers offering bundled certification packages spanning REACH, RSPO, and ISO 16128. This concentration is most visible in German and French cosmetic manufacturing clusters where formulation houses face retailer pressure for single-source traceability documentation.
1-Decanol Market Segmentation
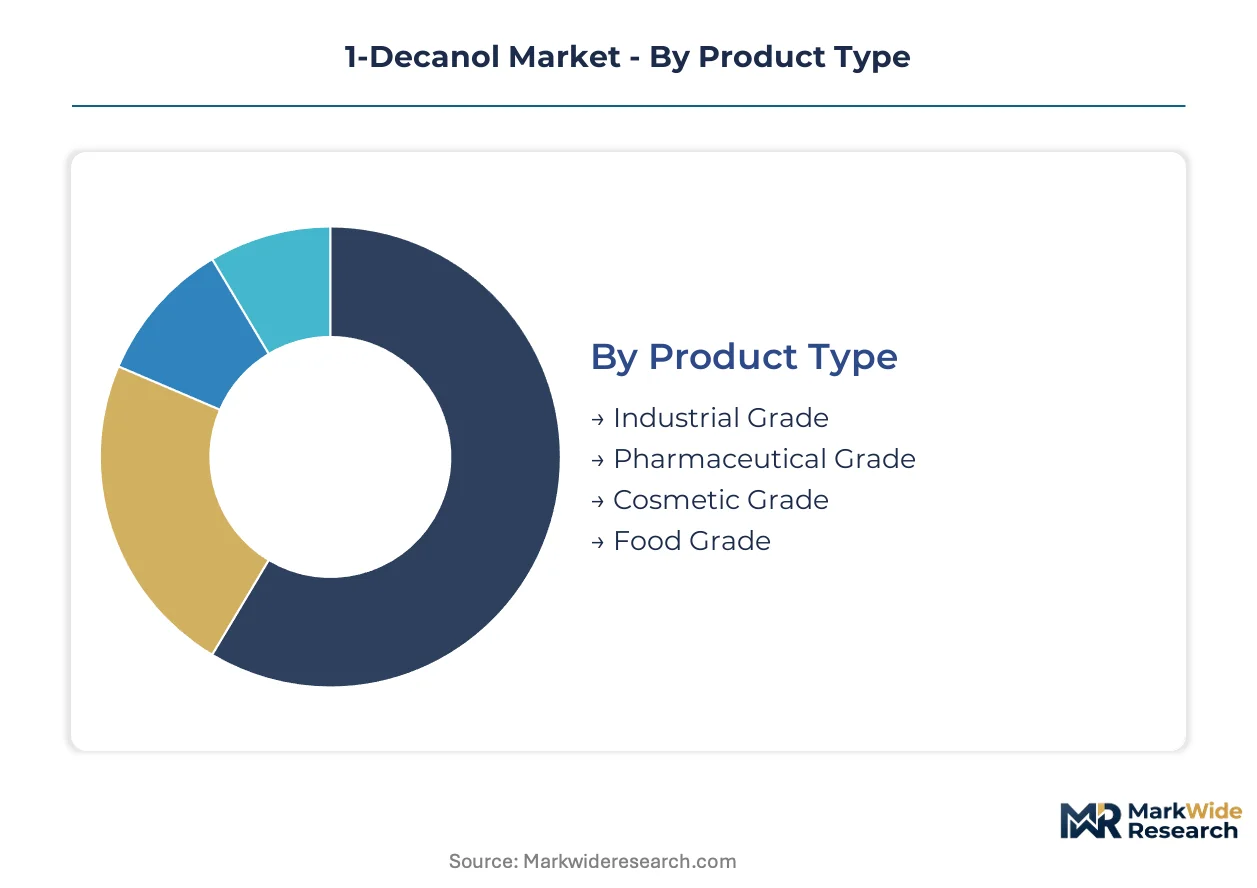
Grade purity tiers and application chemistry define competitive positioning in 1-decanol procurement. Specification differentiation separates commodity volume plays from margin-rich specialty supply.
Product Type:
Specification thresholds determine regulatory pathways and end-use access for each grade tier.
- Industrial Grade:Standard purity specifications (typically 95-98%) serve chemical processing and solvent applications where heavy metal tolerances exceed 100 ppm. Demand concentrates in Southeast Asian oleochemical clusters, particularly Malaysian palm kernel oil refiners serving bulk surfactant manufacturers, constrained by crude palm oil price volatility compressing natural-route margins.
- Pharmaceutical Grade:Sub-50 ppm heavy metal limits and documented carbon-chain distribution satisfy FDA injectable and API excipient requirements. German and Swiss pharmaceutical compounders drive qualification timelines, with ECHA substance evaluation protocols accelerating REACH registration tiering for European importers.
- Cosmetic Grade:ISO 16128 compliance with batch-level RSPO traceability documentation addresses personal care formulator procurement panels.
- Food Grade:FSSAI and FDA food additive specifications govern flavor carrier and food processing aid applications.
Industrial Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
Functional chemistry requirements reshape procurement specifications across downstream formulation categories.
- Surfactants:Alkoxylated 1-decanol derivatives dominate anionic and non-ionic detergent formulations. Personal care manufacturers in Indonesia and Malaysia scale emulsifier applications for skin-care product lines, with specification-driven procurement consolidating supplier panels around bundled certification packages.
- Emulsifiers:HLB value tuning for oil-water stability drives cosmetic and pharmaceutical formulation demand. North American specialty chemical compounders capture formulation-specification premiums through direct-to-compounder distribution channels bypassing traditional networks.
- Solvents:Hydrocarbon compatibility and evaporation rate control serve industrial cleaning and coating applications.
- Lubricants:Ester backbone modification with 1-decanol creates biodegradable synthetic base-stocks for environmentally compliant metalworking fluids.
Surfactants anchor volume flows; Emulsifiers expand most quickly.
End User:
Regulatory jurisdiction density determines compliance cost allocation across customer categories.
- Personal Care:German and French cosmetic manufacturing clusters face retailer pressure for single-source traceability documentation spanning REACH, RSPO, and ISO 16128. Large multinationals restructure supplier qualification protocols to preempt EPA Section 8 reporting gaps.
- Pharmaceuticals:Injectable-grade specifications demand sub-50 ppm heavy metal floors that hydrogenolysis processes struggle to achieve, creating capability scarcity for high-purity supply.
- Chemicals:Bulk surfactant and solvent intermediate demand flows through Southeast Asian palm oil processing infrastructure.
- Food & Beverage:Flavor carrier and processing aid applications require national food safety regulator compliance across import markets.
Chemicals dominate tonnage; Personal Care commands premium pricing power.
Distribution Channel:
Channel economics reflect specification complexity and customer scale fragmentation.
- Direct Sales:Large-volume personal care and pharmaceutical multinationals negotiate formulation-specification premiums through producer relationships. North American specialty chemical markets show fastest channel shift toward direct procurement.
- Distributors:Regional chemical distributors serve mid-scale compounders with consolidated logistics and certification documentation bundling.
- Online Sales:Digital procurement platforms gain traction for standard-grade industrial volumes with transparent specification sheets.
- Retail:Small-laboratory and research-scale packaging serves formulation development and analytical reference standard demand.
Distributors maintain broadest reach; Direct Sales captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrogenation engineers cluster in German chemical corridors and Malaysian oleochemical zones, anchoring regional capability pools for high-purity fatty alcohol production. Their concentration shapes where pharmaceutical-grade qualification timelines compress and where natural-route feedstock conversion achieves scale.
United States
Personal care formulators in New Jersey and California drive specification-driven procurement for emulsifier-grade material. EPA's forthcoming TSCA Section 8 modernization mandates enhanced substance identity disclosure, forcing importers to maintain granular carbon-chain distribution data. Houston-Gulf Coast petrochemical infrastructure supports Fischer-Tropsch derived supply for industrial solvent applications.
Germany
Pharmaceutical compounders in Ludwigshafen and Leverkusen anchor European demand for sub-50 ppm heavy metal specifications. ECHA's updated REACH substance evaluation protocols accelerate registration tiering for imported fatty alcohols. The Rhine-Ruhr chemical corridor concentrates hydrogenolysis engineering talent that European producers compete to retain.
Malaysia
Palm kernel oil refiners in Klang Valley and Pasir Gudang shorten feedstock-to-alcohol cycles through backward integration into oleochemical processing. The country's national standards body enforces traceability documentation that RSPO-certified producers leverage for cosmetic-grade market access. Johor Bahru clusters integrated natural-route capacity serving Southeast Asian surfactant manufacturers.
Indonesia
Surfactant formulators in Jakarta and Surabaya scale emulsifier applications for regional skin-care product lines. Export licensing concentration among approved bulk chemical exporters creates procurement bottlenecks for spot-market buyers. Medan palm oil processing infrastructure feeds integrated fatty alcohol production for industrial-grade volume flows.
Brazil
Specialty chemical compounders in São Paulo and Campinas position for ANVISA's forthcoming green chemistry incentives. The national health regulator's certified-sustainable import channels will open for bio-based fatty alcohols meeting forthcoming traceability standards. The São Paulo state chemical belt hosts formulation houses developing biodegradable lubricant additives.
1-Decanol Market Vendor Landscape
Capital-heavy producers compete with asset-light formulators across distinct margin pools in the 1-decanol market. Integrated oleochemical groups with captive palm kernel oil supply anchor the natural-route tier, while Fischer-Tropsch specialists defend premium positioning through purity differentiation. Three archetypes dominate: Southeast Asian integrated refiners, European petrochemical-derived purists, and Indian subcontinent mid-scale compounders. Capacity expansion and direct-to-compounder distribution channel shifts represent the dominant competitive moves reshaping procurement relationships.
Among integrated Southeast Asian producers, Wilmar International and KLK OLEO exemplify the backward-integrated archetype leveraging Malaysian and Indonesian palm oil proximity. Sasol occupies a position representing Fischer-Tropsch synthesis expertise for regulated pharmaceutical and cosmetic applications. These three anchors illustrate how feedstock control versus process specialization splits competitive positioning across grade tiers.
| Leading Market Players |
|---|
| Wilmar International |
| Musim Mas Group |
| Sasol |
| VVF LLC |
| Godrej Industries |
| Emery Oleochemicals |
| KLK OLEO |
| BASF SE |
| IOI Oleochemical |
| Others |
Supply Flow & Price Mechanics
Specialized hydrogenation engineers clustered in Germany's Rhine-Ruhr corridor and Malaysia's Klang Valley anchor labor-cost differentials that widen pricing spreads between pharmaceutical-grade and industrial-grade tiers. Their scarcity compresses commissioning timelines for high-purity facilities, forcing cost premiums that separate bundled certification packages from unbundled commodity supply.
Pricing Analysis
Bundled certification packages versus unbundled base-material supply splits buyer procurement behavior. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grade levels reflects purity thresholds and documentation burdens. Price differentiation rests on REACH registration tiering and RSPO traceability certification. Cost compression in industrial-grade flows intensifies because crude palm oil volatility erodes natural-route margins. Spot-market buyers in Southeast Asia exhibit highest price sensitivity; pharmaceutical compounders in Germany and Switzerland show lowest sensitivity due to injectable-grade specification rigidity.
Supply Chain Analysis
Domestic-content mandates in Brazil's forthcoming ANVISA green chemistry framework are reshaping sourcing patterns for certified-sustainable fatty alcohols. Geographic supply concentrates in Malaysia, Indonesia, and Germany. Raw material dependencies draw from palm kernel oil, petrochemical paraffin, and Fischer-Tropsch synthetic streams. Single-source vulnerability runs through Indonesian export licensing concentration among approved bulk chemical exporters. Distribution runs through direct-to-compounder channels capturing formulation-specification premiums in North American specialty markets alongside traditional regional distributor networks serving mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Southeast Asian feedstock-proximity advantages and European regulatory-premium capture, with ECHA substance evaluation timelines compressing faster than Malaysian palm oil infrastructure expansion.
For Market Incumbents: To counter hydrogenolysis engineering talent scarcity extending plant commissioning timelines, anchor defensive positioning through captive palm kernel oil supply in Malaysian processing clusters and accelerate FDA pre-submission pathways for injectable-grade qualification. Certification bundling across REACH, RSPO, and ISO 16128 creates switching costs that lock personal care multinationals into long-term offtake relationships. For New Entrants and Emerging Players: Capture Brazilian bio-based mandate windows ahead of ANVISA's certified-sustainable import channel formalization. The most penetrable white-space sits in biodegradable lubricant additive formulations for North American metalworking fluid compounders. Direct-to-compounder distribution bypassing traditional networks offers the sharpest go-to-market angle for specification-premium capture. For Investors and Strategic Acquirers: Integrated personal care chemical groups are the most active acquirer in this space, seeking Fischer-Tropsch synthesis capabilities to complement natural-route oleochemical assets. Long-term viability favors producers with dual-route flexibility across petrochemical and bio-based feedstocks. Watch for EPA TSCA Section 8 modernization implementation timing as the critical inflection signal for importer qualification cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Oil | KLK OLEO's Malaysian supply control shortens feedstock-to-alcohol conversion cycles. |
| Continuous-Flow Hydrogenolysis Retrofit | European producers reduce catalyst consumption per ton against integrated Southeast Asian refiners. |
| REACH Registration Tiering Acceleration | ECHA protocols compress pharmaceutical-grade qualification timelines for European importers. |
| Direct-to-Compounder Distribution | North American specialty channels capture formulation-specification premiums bypassing distributors. |
| Biodegradable Lubricant Additive Development | São Paulo formulation houses leverage ester chemistry convergence for synthetic base-stock demand. |
Methodological Framework
Direct dialogue with plant managers at Malaysian and Indonesian oleochemical facilities, procurement leads at German pharmaceutical compounders, REACH registration consultants, and RSPO certification auditors grounded qualitative findings. Secondary validation drew from ECHA substance evaluation databases, FDA drug master file listings, Malaysian Palm Oil Board trade statistics, and SEC filings of listed oleochemical groups. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates.
Bottom-up unit economics analysis across grade tiers anchored value projections over the projection horizon. Segmentation dimensions spanned purity grade, application chemistry, end-use regulatory jurisdiction, and regional production hub concentration. CAGRs derived from weighted average of feedstock cost trajectories, capacity expansion announcements, and end-use demand elasticity by customer category. Industry-specific inputs included crude palm oil futures curve shape and hydrogenolysis yield-rate assumptions.
Crude palm oil price spikes, Indonesian export licensing disruptions, and EPA TSCA Section 8 implementation delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on feedstock conversion yields and regulatory timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Dairy Flavors Market