
 Yeast Based Savory Flavors Market | 2026-2036
Yeast Based Savory Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Based Savory Flavors Market Analytics
Subscription-based flavor formulation services is shifting how yeast savory flavor suppliers monetize relationships beyond commodity sales. Lallemand leverages its global fermentation infrastructure to secure long-term supply contracts with multinational food manufacturers. Kerry Group anchors its competitive stance through deep backward integration into yeast cultivation and downstream flavor compounding. Angel Yeast differentiates via specialized nutritional yeast portfolios targeting plant-based meat analog producers.
Yeast based savory flavors comprise hydrolyzed yeast proteins, nucleotides, and Maillard-reaction compounds that deliver umami depth while enabling sodium reduction in processed foods. Autolyzed and hydrolyzed yeast extracts typically contain 5-12% glutamic acid equivalents by dry weight, functioning as natural flavor potentiators in low-sodium formulations. Powdered yeast extracts lead volume consumption due to extended shelf stability and ease of dry-blending into seasoning matrices, while liquid pastes capture premium positioning in sauce and ready-meal applications. Food manufacturers represent the dominant end-user channel, though restaurant chains and contract caterers are expanding direct procurement of customized savory yeast bases.
EFSA evaluates novel yeast strains and fermentation-derived flavor compounds under the EU Food Improvement Agent framework, while FDA GRAS self-determination governs US market entry for autolyzed yeast ingredients. REACH compliance constrains solvent use in extraction processes, pushing producers toward aqueous enzymatic hydrolysis methods. Stakeholders must monitor evolving clean-label definitions and regional sodium-reduction mandates to align R&D pipelines with tightening formulation standards.
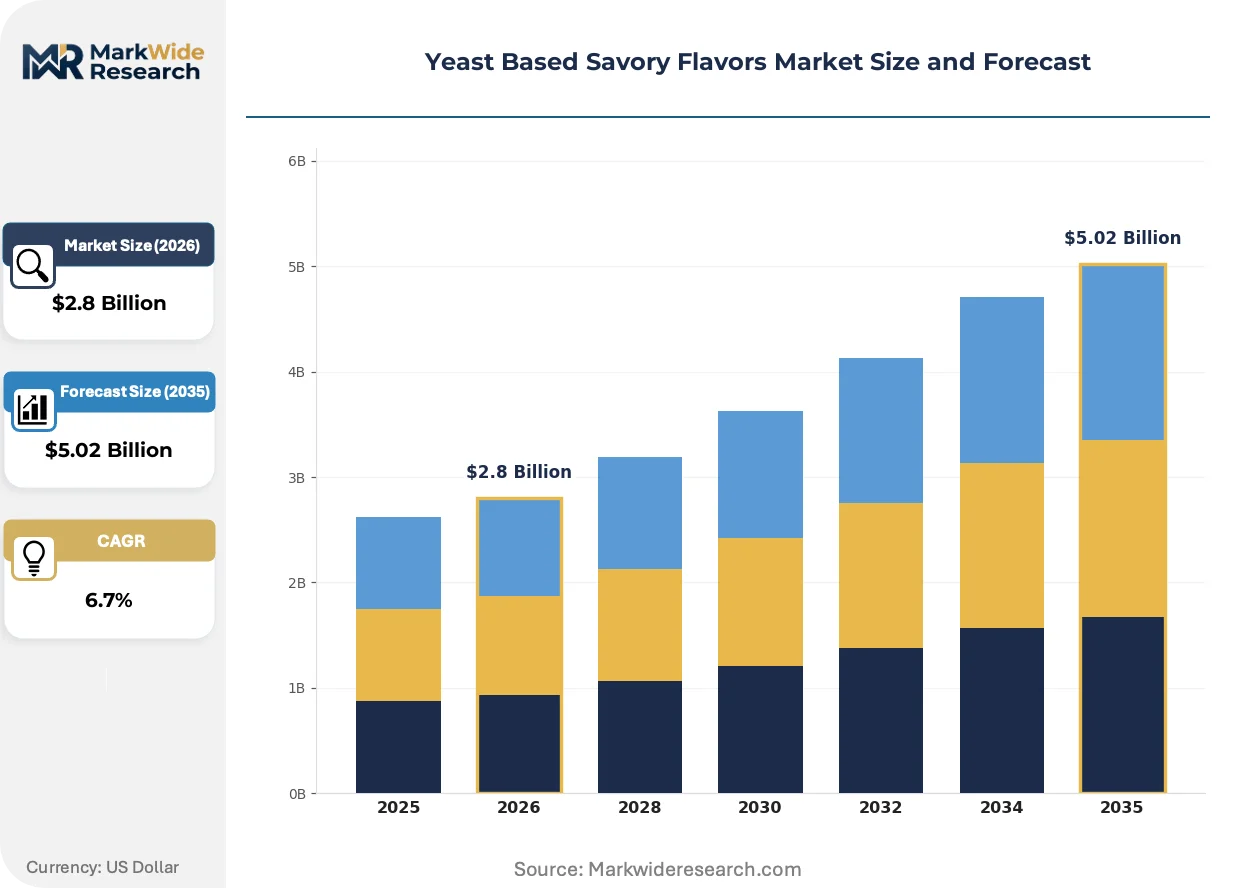
Market Dynamics
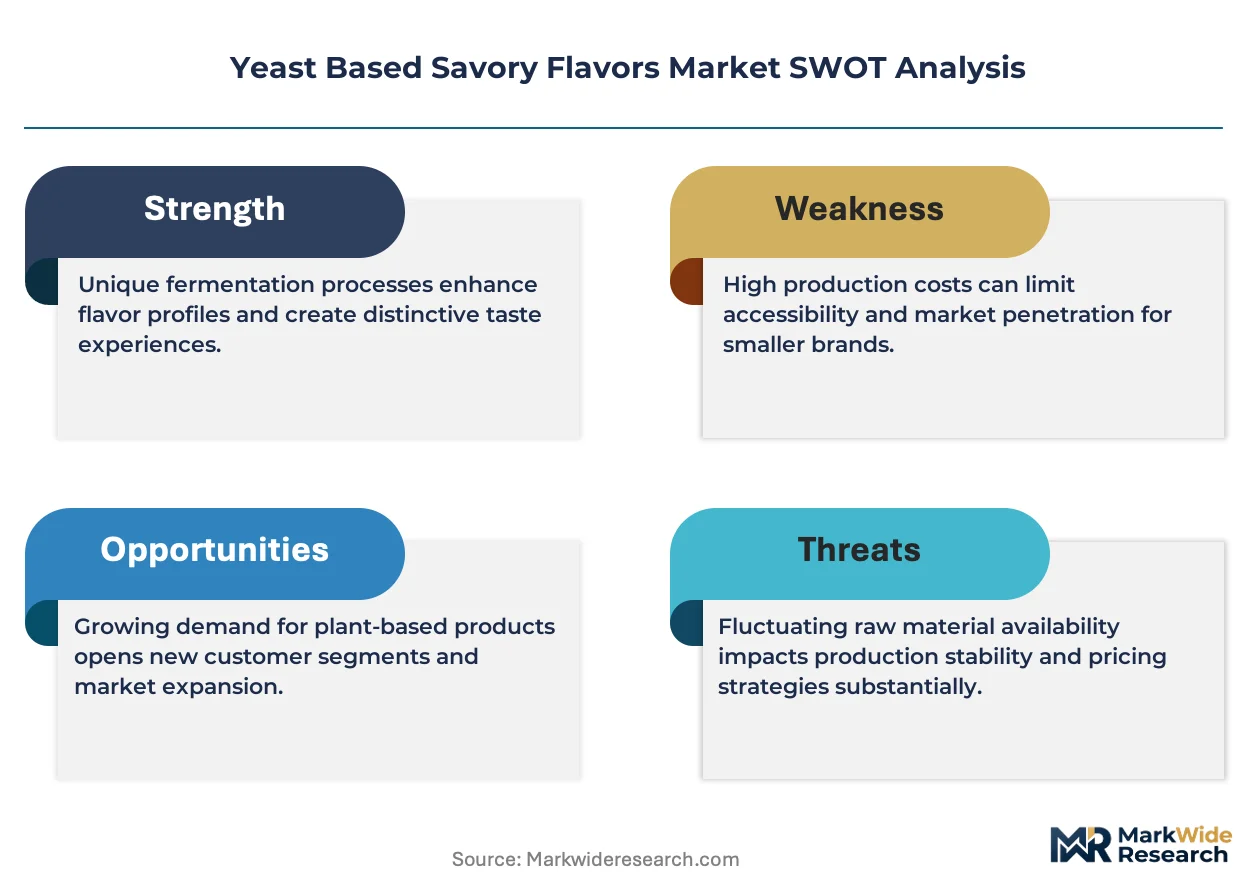
Clean-label sodium reduction mandates from food manufacturers are compressing formulation cycles and forcing yeast extract suppliers to accelerate enzymatic hydrolysis R&D pipelines.
Growth Catalysts
- EU sodium reduction frameworks:Front-of-pack labeling rules in France and the United Kingdom are compelling processed food manufacturers to reformulate with yeast-derived umami potentiators.
- Plant-based meat analogs:Food technologists in Germany are integrating specialized yeast extracts to replicate savory depth in alternative protein matrices without synthetic additives.
- Aqueous enzymatic hydrolysis:This extraction method is displacing solvent-based processes to satisfy REACH compliance while preserving nucleotide integrity in finished flavor compounds.
Market Restraints
- Molasses and sugar beet input volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, squeezing margin structures for yeast cultivation operations.
- Supply concentration in Rhineland-Palatinate:A cluster of major fermentation facilities creates geographic risk exposure for downstream flavor compound availability.
- Hydrolysis degree standardization gaps:Inconsistent glutamic acid equivalent measurement protocols across laboratories complicate cross-supplier formulation consistency.
Strategic Opportunities
- Ready-meal sauce bases:Liquid yeast paste formats are capturing premium positioning in French and British retail channels as clean-label alternatives to hydrolyzed vegetable proteins.
- EFSA novel food approval pathways:Streamlined evaluation frameworks for fermentation-derived ingredients are accelerating market entry timelines for specialized yeast strains.
- Direct procurement by contract caterers:Institutional foodservice operators are bypassing traditional distribution layers to secure customized savory yeast bases for centralized kitchen operations.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with simultaneous expertise in flavor chemistry and GMP compliance command premium compensation and extended recruitment timelines.
- Legacy seasoning matrix integration:Dry-blending equipment originally configured for synthetic flavor systems requires retrofitting to handle hygroscopic yeast extract powders without agglomeration.
- Dual certification complexity:Simultaneous organic and kosher accreditation for yeast cultivation facilities extends validation timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Based Savory Flavors Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Yeast, Nutritional Yeast, Yeast Extracts, Yeast Spreads Application: Bakery Products, Snacks, Sauces, Soups End User: Food Manufacturers, Restaurants, Retailers, Catering Services Form: Granular, Powdered, Liquid, Paste |
| Companies Covered | Lallemand, Ajinomoto, Angel Yeast, Lesaffre Group, Sensient Technologies, Archer Daniels Midland, Kerry Group, Leiber GmbH, Savory Systems International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Based Savory Flavors Market Evolving Landscape
Enzymatic precision is replacing thermal processing as the dominant production paradigm, with downstream consequences for equipment investment patterns and supplier capability requirements.
Precision enzymatic hydrolysis is overtaking traditional autolysis methods in commercial yeast extract production. Food manufacturers in the United Kingdom and Germany are specifying enzyme-catalyzed processes for their superior control over peptide molecular weight distribution. This technology is overtaking commodity-grade extracts in premium clean-label contracts by enabling consistent sodium reduction without bitterness development.
REACH solvent restrictions are constraining extraction process design across European manufacturing facilities. ECHA enforcement of volatile organic compound limits is accelerating capital redeployment toward aqueous processing infrastructure. Yeast extract producers in France and Germany are responding by retrofitting extraction lines with membrane filtration systems that eliminate ethanol-based separation steps.
Subscription-based flavor formulation services are restructuring buyer-supplier relationships in the yeast savory flavor segment. Multinational food manufacturers are displacing spot purchasing with multi-year development partnerships that embed technical staff at supplier R&D facilities. This model is most visible in German and British plant-based protein ventures seeking co-developed proprietary yeast bases for differentiated product positioning.
Yeast Based Savory Flavors Market Segmentation
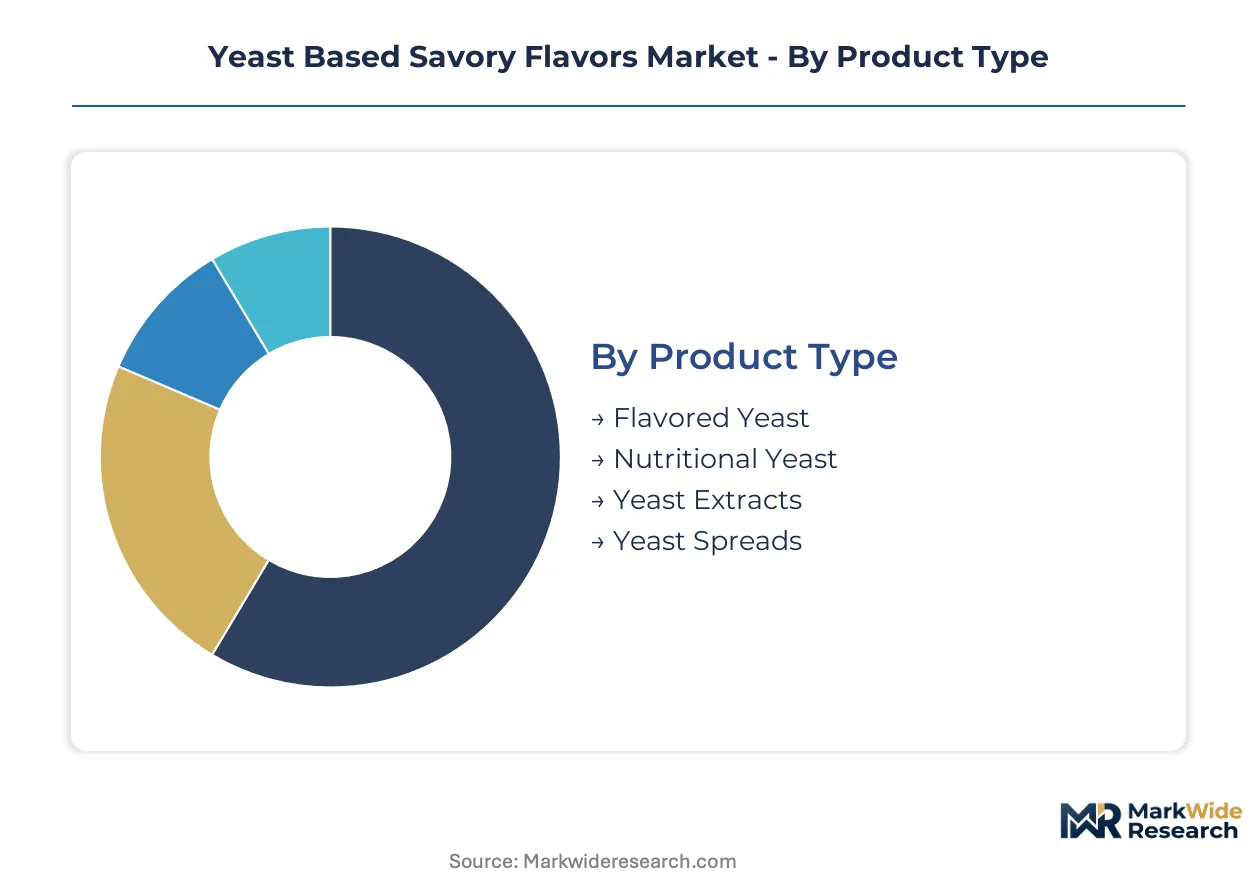
Yeast savory flavor procurement varies sharply by segment, with REACH compliance burdening liquid paste extraction while powdered formats face simpler dry-blending standards. Food manufacturers impose distinct certification requirements on each category, reshaping supplier qualification timelines and capital allocation priorities.
Product Type:
EFSA novel food pathways and organic certification complexity fragment compliance burdens across this category, with specialized yeast strains demanding strain-level safety evaluations while commodity extracts navigate self-affirmed GRAS routes.
- Yeast Extracts:Hydrolyzed and autolyzed concentrates containing 5-12% glutamic acid equivalents by dry weight. Demand concentrates in German and British sodium-reduction reformulations driven by front-of-pack labeling mandates. Aqueous enzymatic hydrolysis is displacing solvent extraction to satisfy ECHA volatile organic compound limits.
- Nutritional Yeast:Inactivated whole-cell preparations valued for B-vitamin fortification and clean-label positioning. German plant-based meat analog producers specify specialized nutritional yeast portfolios for savory depth without synthetic additives. Dual organic-kosher accreditation extends facility validation timelines substantially.
- Flavored Yeast:Yeast bases enhanced with natural flavor compounds during fermentation or post-processing.
- Yeast Spreads:Concentrated paste formats for direct consumer or foodservice application.
Leading the category by volume: Yeast Extracts. Expanding most quickly: Nutritional Yeast.
Application:
Cost tier stratification separates premium sauce formulations from commodity snack seasonings, with aqueous extraction premiums captured in liquid-dependent applications.
- Sauces:Liquid yeast paste formats dominate clean-label positioning in French and British retail channels as alternatives to hydrolyzed vegetable proteins. Premium positioning reflects aqueous enzymatic processing costs and membrane filtration infrastructure requirements.
- Snacks:Powdered yeast extracts lead dry-blending applications due to extended shelf stability and seasoning matrix compatibility. Food manufacturers in Germany specify enzyme-catalyzed processes for superior peptide molecular weight control.
- Soups:Concentrated yeast bases for institutional and retail broth formulations.
- Bakery Products:Yeast-derived flavor potentiators for savory bread and cracker applications.
Capturing premium margins: Sauces. Scaling fastest: Snacks.
End User:
Procurement patterns diverge sharply between centralized manufacturing and distributed foodservice, with contract caterers increasingly bypassing traditional distribution tiers.
- Food Manufacturers:Dominant channel commanding multi-year development partnerships with embedded technical staff at supplier R&D facilities. Subscription-based flavor formulation services are restructuring these relationships beyond commodity spot purchasing.
- Catering Services:Institutional operators securing customized savory yeast bases for centralized kitchen operations through direct procurement. French and British contract caterers lead this bypass trend.
- Restaurants:Chain operators expanding direct procurement of proprietary yeast bases for menu differentiation.
- Retailers:Private-label and branded product development through supplier collaboration.
Controlling procurement volume: Food Manufacturers. Gaining share fastest: Catering Services.
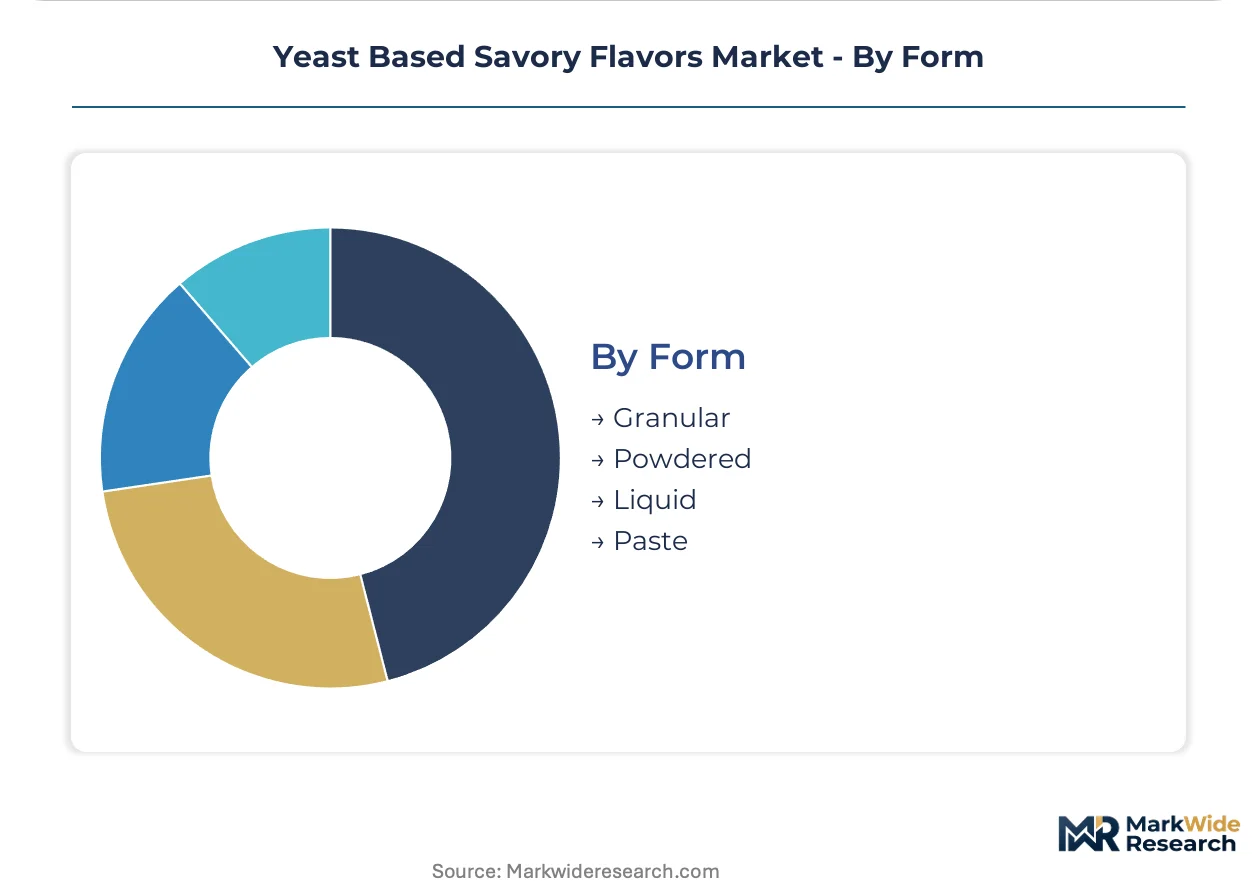
Form:
Supply concentration in Rhineland-Palatinate fermentation clusters creates geographic risk exposure for downstream availability, with form selection determining extraction infrastructure requirements.
- Powdered:Leading volume consumption due to extended shelf stability and ease of dry-blending into seasoning matrices. Legacy equipment retrofitting challenges persist for hygroscopic powder handling without agglomeration.
- Liquid:Capturing premium positioning in sauce and ready-meal applications requiring aqueous enzymatic hydrolysis. REACH solvent restrictions accelerate capital redeployment toward membrane filtration systems eliminating ethanol-based separation.
- Granular:Intermediate format for controlled dissolution in specific processing environments.
- Paste:High-concentration format for industrial sauce base and foodservice applications.
Holding volume leadership: Powdered. Climbing the fastest: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European fermentation clusters while consumption spreads across reformulating food manufacturers in multiple jurisdictions. Germany and France host the dominant extraction infrastructure. The United Kingdom, Netherlands, and Spain represent the principal demand expansion zones.
Germany
Plant-based meat analog developers in Berlin and Hamburg drive specialized nutritional yeast procurement for clean-label savory depth. EFSA novel food approval pathways accelerate strain-level safety evaluations for fermentation-derived ingredients. The Rhineland-Palatinate fermentation corridor anchors continental supply security for downstream flavor compound availability.
France
Front-of-pack Nutri-Score labeling compels processed food reformulation with yeast-derived umami potentiators in Paris-region manufacturing facilities. ANSM and DGCCRF enforcement of sodium reduction mandates tightens formulation standards for retail sauce applications. The Grand Est region hosts aqueous enzymatic hydrolysis retrofitting to satisfy ECHA volatile organic compound limits.
United Kingdom
Subscription-based flavor formulation services restructure procurement relationships beyond commodity spot purchasing in London-headquartered multinational food manufacturers. FSA guidance on clean-label definitions shapes R&D pipeline alignment for yeast extract suppliers. Manchester and Birmingham processing facilities lead dry-blending equipment adaptation for hygroscopic powder handling.
Netherlands
Wageningen University-corporate partnerships accelerate precision enzymatic hydrolysis development for peptide molecular weight control. Dutch sodium reduction frameworks mirror French and British labeling pressures on processed food manufacturers. The Randstad logistics hub enables just-in-time distribution to German and Belgian reformulation facilities.
Spain
Barcelona and Madrid-based contract caterers expand direct procurement of customized savory yeast bases for centralized kitchen operations. Spanish food manufacturers leverage EFSA streamlined evaluation frameworks to accelerate specialized strain market entry timelines. Catalonia's packaging innovation cluster supports liquid paste format premium positioning in Mediterranean retail channels.
Yeast Based Savory Flavors Market Competitive Landscape
Top-tier vendors anchor long-term supply contracting with multinational food manufacturers, while mid-tier specialists occupy subscription-based formulation service niches. The vendor base stratifies across fermentation infrastructure scale, backward integration depth, and enzymatic hydrolysis capability tiers. Three archetypes dominate: integrated fermentation-to-flavor compounders, specialized yeast cultivation houses, and flavor formulation service providers. Capacity expansion in aqueous extraction infrastructure and multi-year development partnerships represent the dominant competitive moves reshaping buyer-supplier relationships.
Within the integrated fermentation tier, Lallemand and Lesaffre Group occupy positions exemplifying global infrastructure leverage for supply security. Angel Yeast anchors the specialized cultivation archetype, representing Chinese-origin expertise in nutritional yeast portfolios. Kerry Group sits within the formulation service provider tier, exemplifying deep backward integration into yeast cultivation and downstream compounding capabilities.
| Leading Market Players |
|---|
| Lallemand |
| Ajinomoto |
| Angel Yeast |
| Lesaffre Group |
| Sensient Technologies |
| Archer Daniels Midland |
| Kerry Group |
| Leiber GmbH |
| Savory Systems International |
| Others |
Value Network & Pricing Analysis
Molasses and sugar beet feedstock costs cascade through yeast cultivation economics into downstream pricing tiers, with agricultural commodity volatility squeezing margin structures for fermentation operators serving European flavor compound manufacturers. REACH solvent restrictions compound extraction costs, pushing aqueous enzymatic hydrolysis premiums into liquid paste formats while powdered extracts retain standard-grade positioning.
Pricing Analysis
Cost-down pressure on standard-grade yeast extracts accelerates because food manufacturers in Germany and France are consolidating procurement volumes under multi-year subscription contracts. Pricing stratifies across premium aqueous-extracted liquid pastes, standard enzymatic hydrolysis powders, and economy-grade autolyzed concentrates. Certification tier—dual organic-kosher versus commodity GRAS—drives 15-25 point spreads between adjacent tiers. Contract caterers exhibit highest price sensitivity due to thin foodservice margins, while multinational food manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Freight costs from Rhineland-Palatinate fermentation clusters to British and French processing facilities have risen with fuel price volatility, compressing landed margins for liquid paste formats with shorter shelf windows. Supply concentrates in Germany, France, and the Netherlands, with Grand Est and Rhineland-Palatinate anchoring extraction infrastructure. Raw material draws from Ukrainian sugar beet, Brazilian molasses, and domestic German barley malt. Single-source vulnerability in the Rhineland-Palatinate corridor creates geographic risk exposure. Distribution runs through Randstad logistics hubs into just-in-time delivery networks for reformulating manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where ECHA REACH solvent restrictions and EFSA novel food frameworks erect regulatory moats favoring capitalized incumbents with aqueous extraction infrastructure and strain-level safety documentation capabilities.
For Market Incumbents: To counter emerging enzymatic precision specialists from Wageningen-corporate partnerships, secure backward integration into yeast cultivation through long-term molasses supply contracts with Ukrainian and Brazilian agricultural cooperatives. Expand membrane filtration capacity in Grand Est to capture REACH-compliant liquid paste premiums. Embed technical staff at buyer R&D facilities to lock in multi-year formulation partnerships before subscription models commoditize.
For New Entrants and Emerging Players: Contract caterers in Barcelona and Madrid represent the most penetrable buyer archetype, bypassing traditional distribution tiers through direct procurement of customized savory yeast bases for centralized kitchen operations. Target Spanish food manufacturers leveraging streamlined EFSA evaluation frameworks for faster specialized strain market entry. Position as formulation service providers rather than commodity suppliers to avoid head-to-head fermentation scale disadvantages.
For Investors and Strategic Acquirers: Accelerated capital redeployment toward aqueous processing infrastructure by French and German producers is the leading indicator that enzymatic hydrolysis capability gaps will consolidate into acquisition premiums. Five-to-ten year viability favors integrated fermentation-to-flavor compounders with REACH-compliant extraction assets and embedded buyer technical partnerships. Watch for EFSA novel food approval velocity as the signal distinguishing scalable strain platforms from commodity extract operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Enzymatic Hydrolysis Capacity Expansion | REACH compliance eliminates solvent extraction, favoring membrane filtration investments in Grand Est and Rhineland-Palatinate. |
| Backward Integration into Yeast Cultivation | Captive molasses supply from Ukrainian cooperatives insulates margin structures from agricultural commodity cycles. |
| Subscription-Based Formulation Partnerships | Embedded technical staff at Lallemand and Kerry Group R&D facilities lock in multinational food manufacturer procurement. |
| Dual Organic-Kosher Certification Investment | Eight-to-fourteen month validation timelines create barrier-to-entry moats for compliant players serving clean-label demand. |
| Direct Procurement Channel Development | Barcelona and Madrid contract caterers bypass distribution tiers, capturing margin pool from traditional wholesale layers. |
Research Methodology
Multi-period observation of enzymatic hydrolysis adoption rates, REACH compliance capital deployment, and EFSA novel food approval timelines anchored the trend analysis, supplemented by interviews with fermentation plant managers, procurement leads at German and British food manufacturers, flavor chemists at yeast extract suppliers, and regulatory affairs specialists navigating EFSA frameworks. Secondary validation drew from ECHA enforcement disclosures, EFSA scientific opinions, customs trade data for molasses and yeast extract flows, and SEC filings of publicly traded flavor compounders. Bottom-up volume modeling triangulated against top-down expenditure estimates from food manufacturer R&D budget disclosures.
Input-output matrices mapped fermentation feedstock costs through extraction technology tiers to finished flavor compound pricing, with segmentation dimensions spanning product type, application, end-user procurement pattern, and form factor. CAGRs derived from regression analysis of historical volume trajectories against sodium reduction mandate implementation schedules and plant-based meat analog formulation adoption curves. Industry-specific forecast inputs included EFSA novel food approval velocity indices and REACH solvent restriction enforcement intensity metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to agricultural commodity volatility, EFSA regulatory reinterpretation, and fermentation scale-up talent scarcity. Forecasts reflect documented assumptions about ECHA enforcement continuity and EFSA streamlined evaluation pathway permanence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Flavanones Market