
 Neotame Market | 2026-2036
Neotame Market Size, Share, and Industry Trends Forecast 2026-2036
Neotame Market Outlook
Clean-label formulation technology is reshaping how sweetener suppliers develop and position neotame across beverage and bakery applications. Ajinomoto Co., Inc. leverages its amino acid expertise to sustain premium positioning in high-purity neotame grades. NutraSweet Company anchors its competitive stance through decades of brand recognition and established food industry relationships. WuHan HuaSweet Co., Ltd competes aggressively on manufacturing scale, offering cost-optimized granular and powder variants to Asian and European buyers.
Neotame is a high-intensity dipeptide sweetener derived from aspartic acid and phenylalanine derivatives, functional at concentrations approximately 7,000 to 13,000 times sweeter than sucrose, with thermal stability enabling pasteurization and baking processes. Its primary commercial purpose centers on enabling significant sugar reduction in processed foods and beverages without caloric contribution. Powder neotame dominates current volume flows due to handling efficiency and blending compatibility in industrial food manufacturing, while liquid formulations capture expanding share among beverage producers seeking streamlined dosing systems. The bakery application segment presents concentrated margin pools as clean-label bread and pastry formulations drive premium pricing for heat-stable sweetener grades.
FDA food additive regulations and EFSA sweetener safety assessments shape product approval timelines and label claim permissibility across major consumption markets. China's SAMR and national food safety standards govern import thresholds and manufacturing facility licensing for domestic neotame producers. ISO quality management certifications increasingly function as baseline market access requirements for ingredient suppliers serving multinational food manufacturers. Stakeholders must monitor evolving clean-label definitions and regional sweetener taxation proposals to anticipate demand migration between application segments and product formats.
Market Dynamics
Clean-label formulation mandates from major food manufacturers are compressing approval timelines for neotame suppliers, forcing simultaneous compliance with FDA, EFSA, and SAMR standards while scaling production capacity.
Growth Catalysts
- Sugar taxation frameworks:Mexico's IEPS levy and the United Kingdom's Soft Drinks Industry Levy push beverage formulators toward high-intensity sweeteners. Neotame's heat stability enables reformulation without process redesign.
- Pasteurization-compatible sweetener demand:Ultra-high temperature processing in ready-to-drink coffee and tea applications requires thermal stability that neotame provides at lower use rates than aspartame.
- China's production scale expansion:Domestic manufacturers in Hubei and Jiangsu provinces have tripled crystallization capacity since 2022, reducing import dependence for Asian food processors.
Market Restraints
- Input cost volatility:Phenylalanine derivative prices fluctuate with petrochemical feedstock costs, compressing margins for non-integrated producers during energy price spikes.
- Supply concentration risk:Three Chinese manufacturers control approximately 70% of global neotame crystal output, creating vulnerability to environmental compliance shutdowns under MEE enforcement.
- Regulatory friction:EFSA's 2023 re-evaluation of aspartame's carcinogenic classification has extended safety dossier requirements for neotame, delaying new application approvals by 18-24 months.
Strategic Opportunities
- Underpenetrated pharmaceutical applications:Pediatric and geriatric drug formulations in India represent untapped demand for palatable, non-caloric excipients under CDSCO guidance.
- Regulatory tailwind from dual carbon goals:China's 2060 carbon neutrality mandate incentivizes low-energy sweetener production methods, favoring enzymatic synthesis over chemical routes.
- Direct-to-beverage-manufacturer distribution:Bypassing traditional ingredient distributors through integrated dosing systems creates margin capture and formulation partnership lock-in.
Industry Challenges
- Multi-jurisdictional dossier preparation:Simultaneous FDA, EFSA, and SAMR submissions require specialized regulatory affairs talent scarce outside Shanghai, Basel, and Washington DC.
- Legacy ERP integration:Food manufacturers running SAP or Oracle systems built for commodity sweeteners face data field mapping complexity when switching to micro-dose neotame tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neotame Market |
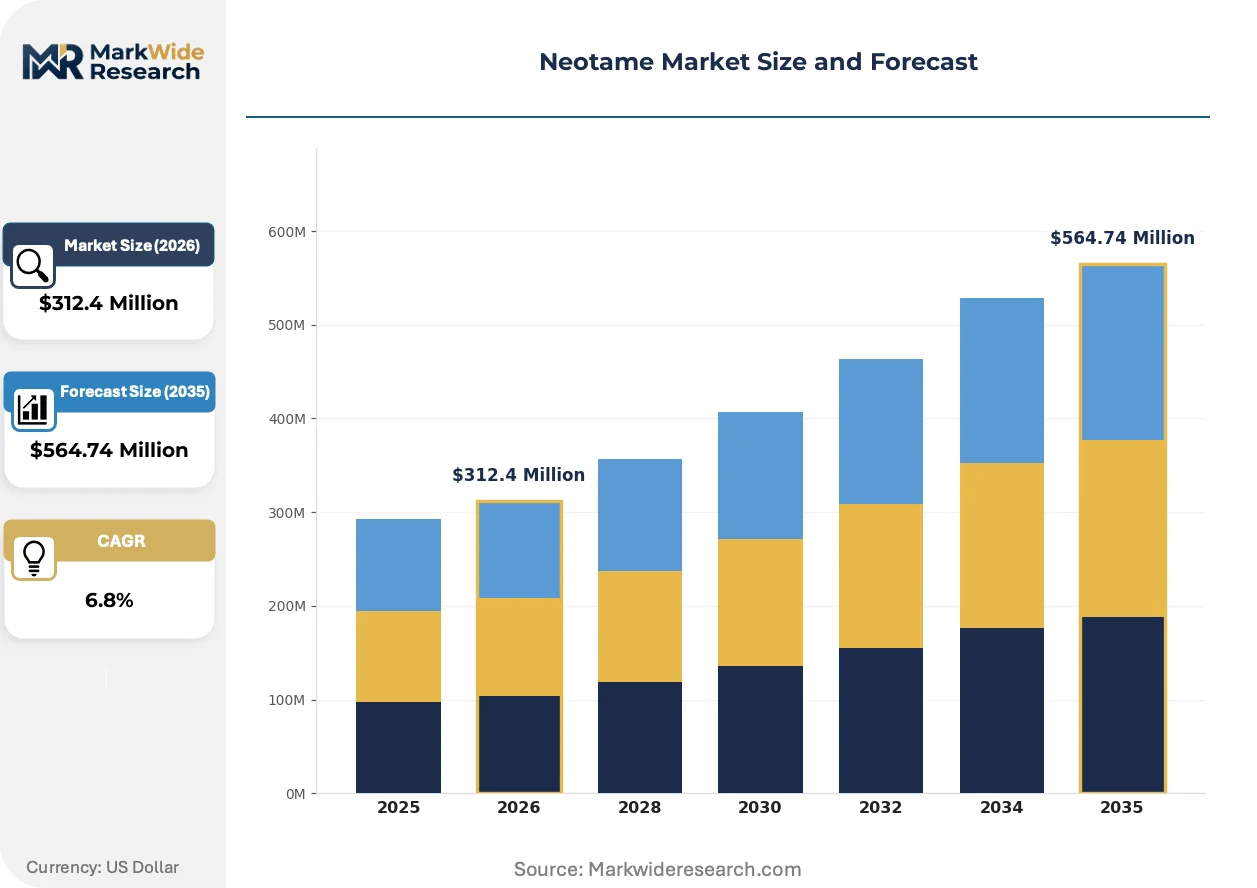
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Tablet Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Producers, Sport Nutrition, Household Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | NutraSweet Company, Ajinomoto Co., Inc., WuHan HuaSweet Co., Ltd, JK Sucralose Inc., Prinova Group LLC, Shaoxing Marina Biotechnology Co., Ltd., HuaSweet–Neotame, Shandong Benyue Biological Technology, Fooding Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neotame Market Strategic Shifts
Digital formulation platforms and precision dosing hardware are compressing the traditional specification-to-production cycle for high-intensity sweeteners, while regulatory divergence between major markets forces parallel compliance investments.
Encapsulation technology using modified starch matrices is virtualizing neotame's functional performance in extended-release beverage applications. Sports drink manufacturers in Germany and Brazil are adopting these systems to mask temporal sweetness perception changes. The technology is virtualizing competitive differentiation away from purity grades toward delivery-system integration.
EFSA's updated guidance on sweetener metabolite studies now requires extended-duration toxicology data for novel dipeptide derivatives. This policy shift extends approval timelines and increases dossier preparation costs for European market entry. Powder formats face stricter stability documentation than liquid concentrates under the revised framework.
Ingredient bundling contracts are consolidating procurement decisions for beverage manufacturers, with neotame increasingly paired with acidulants and flavor masking systems under single-supplier agreements. This pattern concentrates buyer power among integrated ingredient houses. The shift is most visible in North American carbonated soft drink reformulation programs.
Neotame Market Segmentation
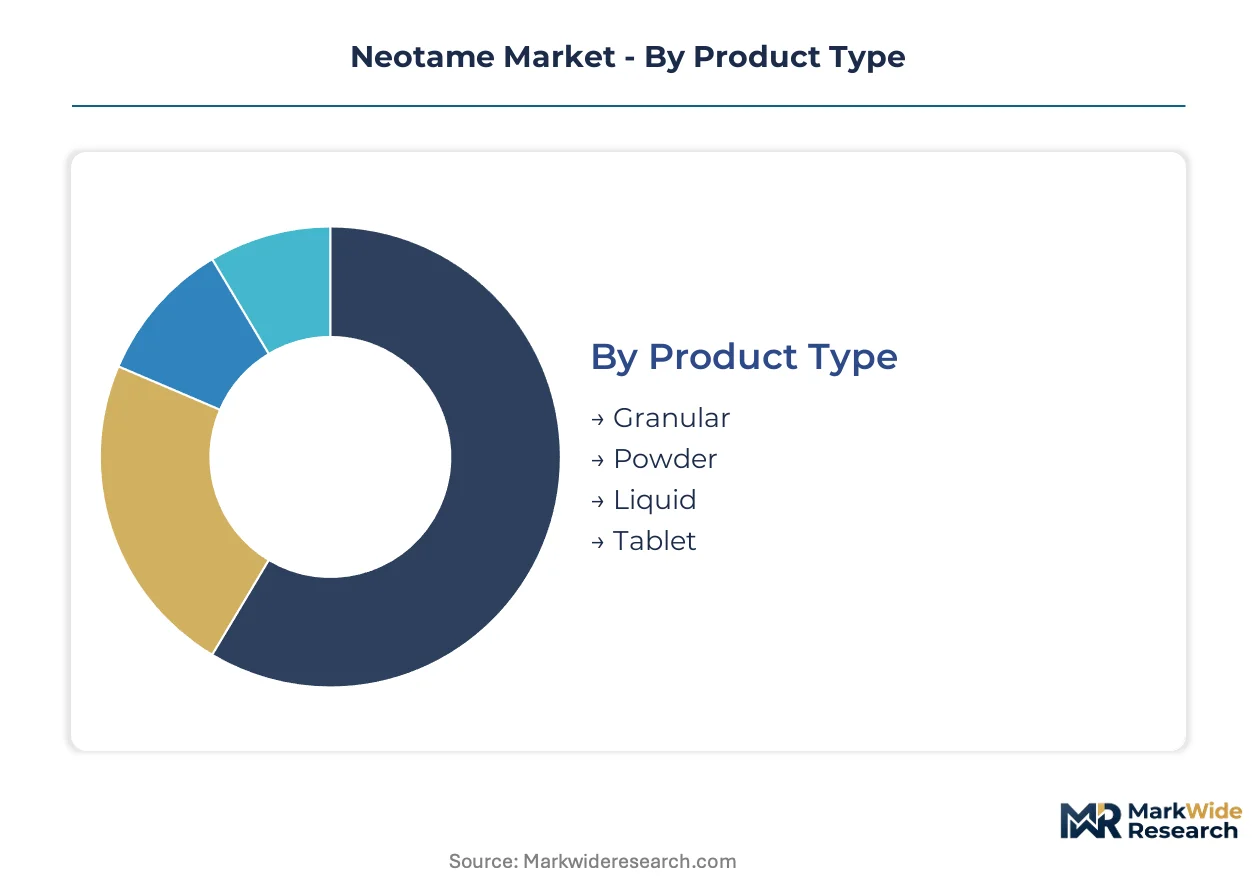
Neotame's extreme potency at micro-dose levels creates divergent handling requirements across product formats, while application-specific thermal and pH stability demands fragment specification standards. Understanding segment velocity reveals where formulation partnerships lock in longest and where supplier switching costs remain lowest.
Product Type:
Powder formats turn inventory fastest in commodity-scale food manufacturing, while liquid concentrates cycle slower due to customized dosing system integration timelines.
- Powder:Free-flowing crystalline form optimized for pneumatic conveying and high-speed blending lines in industrial bakeries. Beverage producers in the United States specify this grade for dry-mix applications where instant solubility is critical.
- Granular:Agglomerated particles reduce dusting and improve flowability for manual handling environments. Food manufacturers in China prefer this format for mid-scale operations lacking advanced containment systems.
- Liquid:Pre-dissolved concentrates enable precision dosing through automated pump systems. Ready-to-drink tea bottlers in Germany adopt liquid neotame to eliminate dissolution steps and reduce batch variability.
- Tablet:Compressed unit-dose forms serve household consumers and small-scale food service operations. Direct-to-consumer channels in India distribute tablet formats for home baking and beverage preparation.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Margin structures vary sharply across thermal processing requirements, with pasteurization-stable applications commanding premium pricing over cold-process formulations.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink coffees represent the largest volume sink. Mexico's IEPS sugar tax has accelerated reformulation timelines for high-intensity sweetener adoption in this segment.
- Bakery Products:Heat-stable neotame grades enable sugar reduction in breads, pastries, and cakes without Maillard reaction interference. European clean-label mandates are driving premium pricing for certified heat-stable variants.
- Dairy Products:Yogurt and flavored milk applications require acid stability across refrigerated shelf life. SAMR's food safety standards in China govern additive maximum levels in this category.
- Confectionery:Hard candies and chewing gums utilize neotame's non-cariogenic properties and extended sweetness release. Brazilian manufacturers leverage this positioning for dental-health label claims under ANVISA guidance.
Beverages anchor current volume. Bakery is climbing the fastest.
End User:
Procurement sophistication separates enterprise-scale buyers with dedicated regulatory affairs teams from smaller accounts relying on distributor technical support.
- Food Manufacturers:Industrial bakeries and processed food plants purchase neotame in bulk quantities with custom specification agreements. These buyers negotiate multi-year supply contracts tied to ISO quality certifications.
- Beverage Producers:Soft drink and bottled water companies integrate neotame into complex sweetener blends with acidulants and flavor systems. Direct sales relationships predominate for this customer class.
- Sport Nutrition:Protein powder and energy drink brands specify neotame for low-calorie positioning in performance products. CDSCO registration requirements in India shape supplier qualification timelines for this segment.
- Household:Individual consumers purchase small-format retail products for home use. Online channels and specialty stores serve this fragmented demand base with premium unit pricing.
Food manufacturers represent the deepest penetration. Sport nutrition is gaining share fastest.
Distribution Channel:
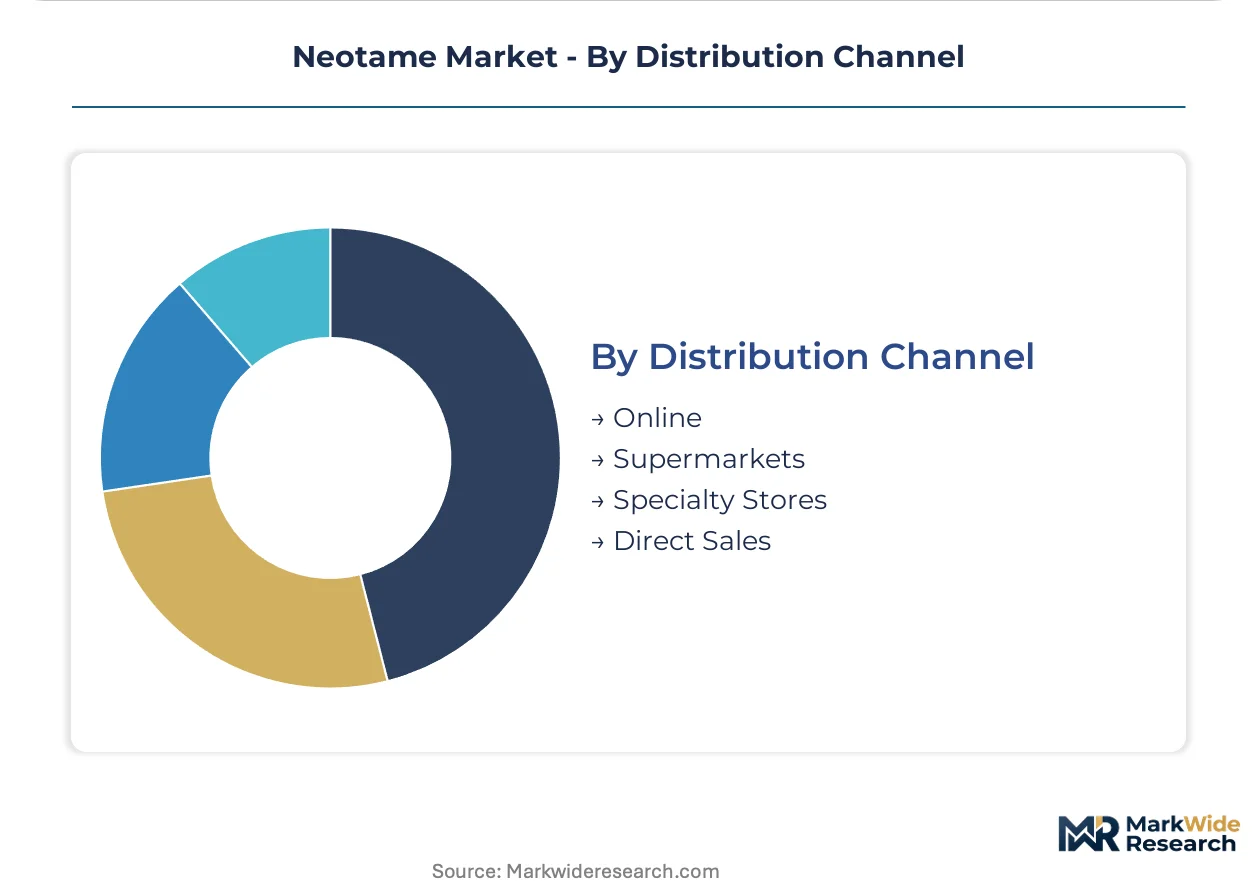
Channel selection reflects buyer scale and technical service requirements, with direct relationships consolidating among the largest accounts.
- Direct Sales:Supplier technical teams embed with major food and beverage manufacturers for formulation development. This channel captures the highest margin and longest contract duration.
- Online:E-commerce platforms serve small and mid-scale buyers with standardized product offerings. Specialty ingredient marketplaces in Europe aggregate demand from craft food producers.
- Supermarkets:Mass retail channels distribute consumer-format neotame products for household end users. Shelf placement competes with stevia and monk fruit alternatives.
- Specialty Stores:Health food and baking supply retailers target clean-label and diabetic-consumer segments. Staff technical knowledge influences purchase decisions in this channel.
Direct sales commands the largest transaction value. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese crystallization facilities in Hubei and Jiangsu provinces export neotame powder to beverage manufacturers across Germany, Mexico, and the United States, establishing a trans-Pacific supply corridor that handles the majority of global volume flows.
United States
FDA food additive regulations govern neotame's use in carbonated beverages and baked goods, with beverage producers in Atlanta and Chicago driving reformulation demand following sugar taxation debates. The country's soft drink manufacturers specify heat-stable powder grades for high-speed blending lines.
Germany
EFSA sweetener safety assessments shape approval timelines for neotame applications in dairy and confectionery, with ready-to-drink tea bottlers in Bavaria adopting liquid concentrate formats. Munich-based formulation houses integrate precision dosing systems for automated production.
China
SAMR food safety standards and MEE environmental enforcement govern domestic manufacturing, with crystallization capacity concentrated in Wuhan and Nanjing. Hubei province's producers have tripled output since 2022, reducing import dependence across Asia.
Mexico
IEPS sugar taxation accelerates high-intensity sweetener adoption in carbonated soft drinks, with bottling operations in Mexico City and Monterrey reformulating portfolios. Beverage manufacturers specify neotame for heat-stable reformulation without process redesign.
India
CDSCO registration requirements shape supplier qualification for pharmaceutical excipient applications, with pediatric drug formulators in Mumbai and Hyderabad exploring non-caloric alternatives. FSSAI standards govern food-grade additive maximum levels.
Neotame Market Competitive Environment
Channel-controlling players compete with product-specialist players across direct sales and distributor relationships. The market structure concentrates around three Chinese crystallization specialists supplying approximately 70% of global crystal output, creating tiered competition between integrated manufacturers and formulation-technology licensors. Strategic archetypes include amino acid-integrated chemical producers, brand-recognition-dependent sweetener houses, and cost-optimized regional fabricators. Dominant competitive moves center on enzymatic synthesis technology licensing and backward integration into phenylalanine derivative production.
Among Japanese amino acid specialists, Ajinomoto Co., Inc. occupies a position exemplifying premium-grade positioning through integrated fermentation expertise. WuHan HuaSweet Co., Ltd represents the scale-driven Chinese archetype, with manufacturing concentration in Hubei province serving Asian and European buyers. NutraSweet Company anchors the brand-heritage tier, leveraging decades of food industry relationships and established regulatory dossiers across FDA and EFSA jurisdictions.
| Leading Market Players |
|---|
| NutraSweet Company |
| Ajinomoto Co., Inc. |
| WuHan HuaSweet Co., Ltd |
| JK Sucralose Inc. |
| Prinova Group LLC |
| Shaoxing Marina Biotechnology Co., Ltd. |
| HuaSweet–Neotame |
| Shandong Benyue Biological Technology |
| Fooding Group Limited |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Hubei province crystallization facilities is tightening supplier pricing discipline, with Wuhan-based manufacturers leveraging order backlogs to enforce minimum volume commitments while phenylalanine derivative costs feed through to contract renegotiations.
Pricing Analysis
Cost-plus contracts indexed to phenylalanine derivative spot markets dominate long-term supply agreements between Chinese crystallizers and European beverage manufacturers. Price differentiation hinges on ISO 22000 certification tier and thermal stability grade, with pasteurization-compatible variants commanding premiums over standard powder grades. Pricing pressure stems from energy cost spikes compressing margins for non-integrated producers. Small-scale food manufacturers exhibit highest price sensitivity, while multinational beverage producers prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for North American beverage reformulators. Manufacturing concentrates in Hubei and Jiangsu provinces, with secondary crystallization capacity in Japan. Phenylalanine derivatives, modified starch encapsulation matrices, and automated dosing hardware constitute critical input dependencies. Single-source vulnerability concentrates around the three dominant Chinese crystallizers. Distribution runs through direct technical sales relationships for enterprise buyers, with regional distributors serving mid-scale food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neotame procurement is shifting toward platform economics as ingredient bundling contracts consolidate acidulant, flavor masking, and sweetener purchasing under single-supplier agreements, creating interoperability lock-in between formulation technology and dosing system hardware.
For Market Incumbents: Harden supply security through backward integration into phenylalanine derivative production or captive fermentation capacity in Jiangsu province. Secure MEE environmental compliance certifications ahead of enforcement waves to preempt competitor shutdowns. Lock in beverage manufacturer relationships through integrated liquid dosing system partnerships that raise switching costs.
For New Entrants and Emerging Players: Build out pharmaceutical excipient capabilities targeting CDSCO-registered pediatric and geriatric drug formulations in India, the least penetrated application segment. Establish enzymatic synthesis technology licensing as a differentiated entry vector against incumbent chemical routes. Pursue direct-to-beverage-manufacturer distribution bypassing traditional ingredient distributors to capture margin and formulation influence.
For Investors and Strategic Acquirers: Capital is best deployed toward amino acid-integrated chemical producers with existing fermentation infrastructure and SAMR-licensed manufacturing facilities. Five-to-ten year viability favors suppliers with dual carbon goal alignment and enzymatic process patents. Monitor EFSA sweetener metabolite study guidance revisions as the critical regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Licensing | Lowers energy intensity per kilogram under China's dual carbon goals. |
| Backward Integration into Phenylalanine | Insulates margin from petrochemical feedstock volatility. |
| Integrated Dosing System Partnerships | Locks in beverage manufacturer formulation collaboration. |
| Pharmaceutical Excipient Registration | Opens CDSCO-regulated pediatric drug formulation demand. |
| Encapsulation Technology Development | Enables extended-release sports drink applications in Germany. |
Study Parameters
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings for this study. Primary interviews with neotame crystallization plant managers, beverage procurement leads, bakery R&D directors, and pharmaceutical formulation scientists were synthesized with secondary validation from SAMR additive approvals, EFSA safety opinions, FDA food additive petitions, and Chinese customs export records. Bottom-up capacity modeling and top-down consumption estimates were triangulated to reconcile supply-side and demand-side perspectives.
Calibration against historical price series and capacity utilization reports refines the projection framework across the analysis window. Segmentation dimensions modeled include product format, thermal stability grade, application processing temperature, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating phenylalanine derivative cost trajectories, sugar taxation policy adoption rates, and clean-label formulation mandate penetration by food manufacturer tier.
Sensitivities concentrate around EFSA metabolite study outcomes, MEE environmental enforcement intensity, and phenylalanine derivative supply disruptions. Forecasts reflect documented assumptions about regulatory approval timelines and crystallization capacity expansion schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Valencene Market