
 Black Beer Market | 2026-2036
Black Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Black Beer Market Intelligence
Asset-light contract brewing and taproom leasing models is rewriting competitive entry economics for dark beer specialists. BrewDog leverages its Scottish manufacturing footprint to sustain vertical integration across stout and porter production. Heineken N.V. anchors European black lager distribution through controlled on-trade channels. The Boston Beer Company differentiates via R&D intensity in specialty dark ale formulations.
Black beer comprises roasted malt or barley-derived beverages with color intensity exceeding 40 European Brewing Convention units, produced through kilned or roasted grain addition prior to mashing to achieve bitter-chocolate flavor profiles and elevated viscosity for cold-weather consumption. Stout occupies the dominant value position among product types due to Guinness heritage and craft replication, while black lager represents the fastest-growing format as lager-drinking regions develop dark variants. Distribution through brewpubs captures the highest margin pool by eliminating wholesale intermediaries, though retail channels sustain volume scale for porter and dark ale portfolios.
Germany's BfR, the US TTB labeling authority, and the EU's Food Information to Consumers Regulation collectively govern additive disclosure, alcohol content verification, and nutritional labeling standards that shape cross-border market access for dark beer portfolios. The EU Green Deal packaging requirements are forcing brewers to redesign glass weight and recycled content specifications for stout and porter bottles. Stakeholders must monitor how carbon accounting rules reshape malt sourcing decisions before committing to long-term roasting capacity investments.
Market Dynamics
Roasted malt supply concentration in Germany and the Czech Republic is tightening input access for craft brewers expanding dark beer portfolios. BfR additive scrutiny and EU Green Deal packaging mandates are forcing simultaneous reformulation and container redesign across European production networks.
Growth Catalysts
- EU Green Deal packaging rules:Recycled glass mandates accelerate bottle lightweighting investments, reducing per-unit freight costs for stout and porter shipments across member states.
- Craft brewery density in Bavaria:Reinheitsgebot heritage creates trained malt-roasting labor pools that lower technical barriers for dark beer specialists entering contract production.
- Nitrogen infusion systems:Widget and inline nitrogenation technologies replicate draught texture in packaged formats, extending stout consumption occasions beyond on-trade.
Market Restraints
- Barley price volatility:Climate stress on European harvests concentrates malt cost risk with three dominant suppliers controlling specialty roasting capacity.
- TTB formula approval timelines:US market entry requires 6-12 month waits for roasted additive disclosures, delaying seasonal dark beer launches.
- Hard seltzer substitution:Flavored malt beverage alternatives capture trial-seeking drinkers in 21-29 demographic, compressing black lager adoption windows.
Strategic Opportunities
- India FSSAI craft classification:Emerging microbrewery licensing in Maharashtra and Karnataka creates first-mover positioning for dark ale portfolios in warm-climate markets.
- Alcohol-free stout segment:Dealcoholization membrane advances enable sub-0.5% ABV variants targeting Middle Eastern markets with MOHAP import pathways.
- Brewpub direct distribution:Taproom leasing models bypass wholesale markup, capturing 40-60 point margin improvements on limited-release porter series.
Industry Challenges
- Roasting technician scarcity:Kiln operation expertise concentrates with retiring German maltsters, forcing knowledge transfer investments or automated roast curve replication.
- REACH chemical registration:Novel hop extracts and flavor modifiers require ECHA dossier preparation, extending R&D-to-market timelines by 18-24 months.
- Legacy ERP integration:Batch traceability requirements for BfR audits clash with older brewery management systems, demanding middleware development for malt lot tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Beer Market |
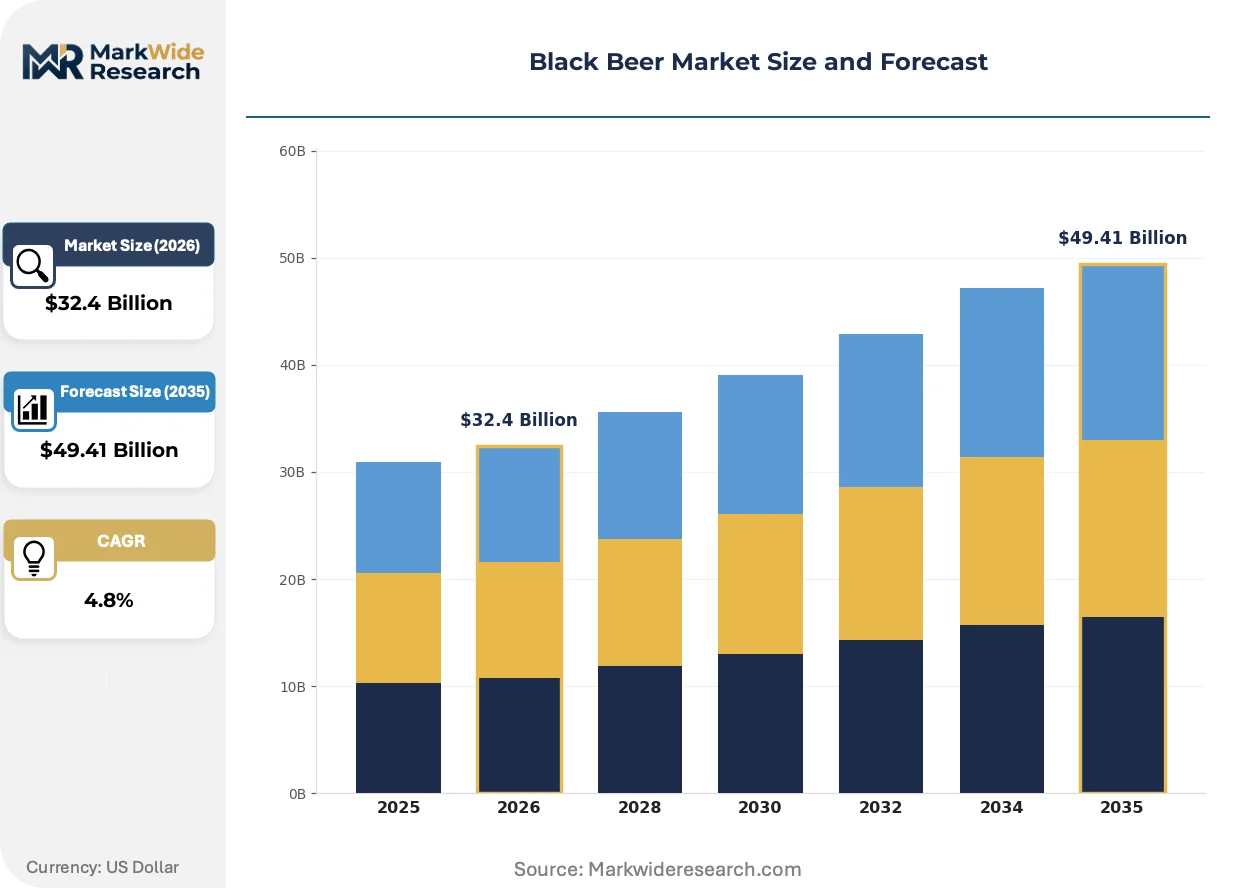
| Market Size in 2026 | $32.4 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stout, Porter, Black Lager, Dark Ale Distribution Channel: Retail, Online, Wholesale, Brewpubs Consumer Type: Casual Drinkers, Craft Beer Enthusiasts, Specialty Stores, Occasional Consumers Alcohol Content: Low Alcohol, Mid Alcohol, High Alcohol, Non-Alcoholic |
| Companies Covered | Anheuser-Busch InBev SA/NV, Heineken N.V., The Boston Beer Company, Carlsberg Breweries A/S, Asahi Group Holdings Ltd., Diageo Plc, BrewDog, Sapporo Breweries Ltd., New Belgium Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Beer Market Strategic Shifts & Innovations
Digital brewing platforms and precision fermentation are compressing traditional R&D cycles for dark beer formulation. Sustainability mandates and ingredient provenance demands are simultaneously reshaping supply base relationships and consumer communication strategies.
Inline spectroscopy combined with AI-driven roast curve optimization is virtualizing quality control workflows. Mid-sized craft breweries in Belgium and the Netherlands deploy these systems to replicate master maltster judgment without dedicated sensory panels. The technology is virtualizing capital requirements that previously separated regional players from industrial-scale consistency.
REACH chemical authorization deadlines for process aids are forcing additive substitution programs across European dark beer production. ECHA's 2024 updated guidance on enzymatic processing aids triggers reformulation sprints ahead of sunset dates. Stout and porter specialists with legacy caramel coloring dependencies face compressed compliance timelines versus lager-centric competitors with simpler roast-malt-only formulations.
Direct-to-consumer subscription models are displacing traditional retail discovery for limited-release dark ales. Urban craft enthusiasts in London, Berlin, and Amsterdam prioritize curated monthly shipments over supermarket browsing. The shift concentrates brand relationship investment in fulfillment infrastructure rather than slotting fee negotiations, with brewpub members capturing lifetime value through exclusive barrel-aged releases.
Black Beer Market Segmentation
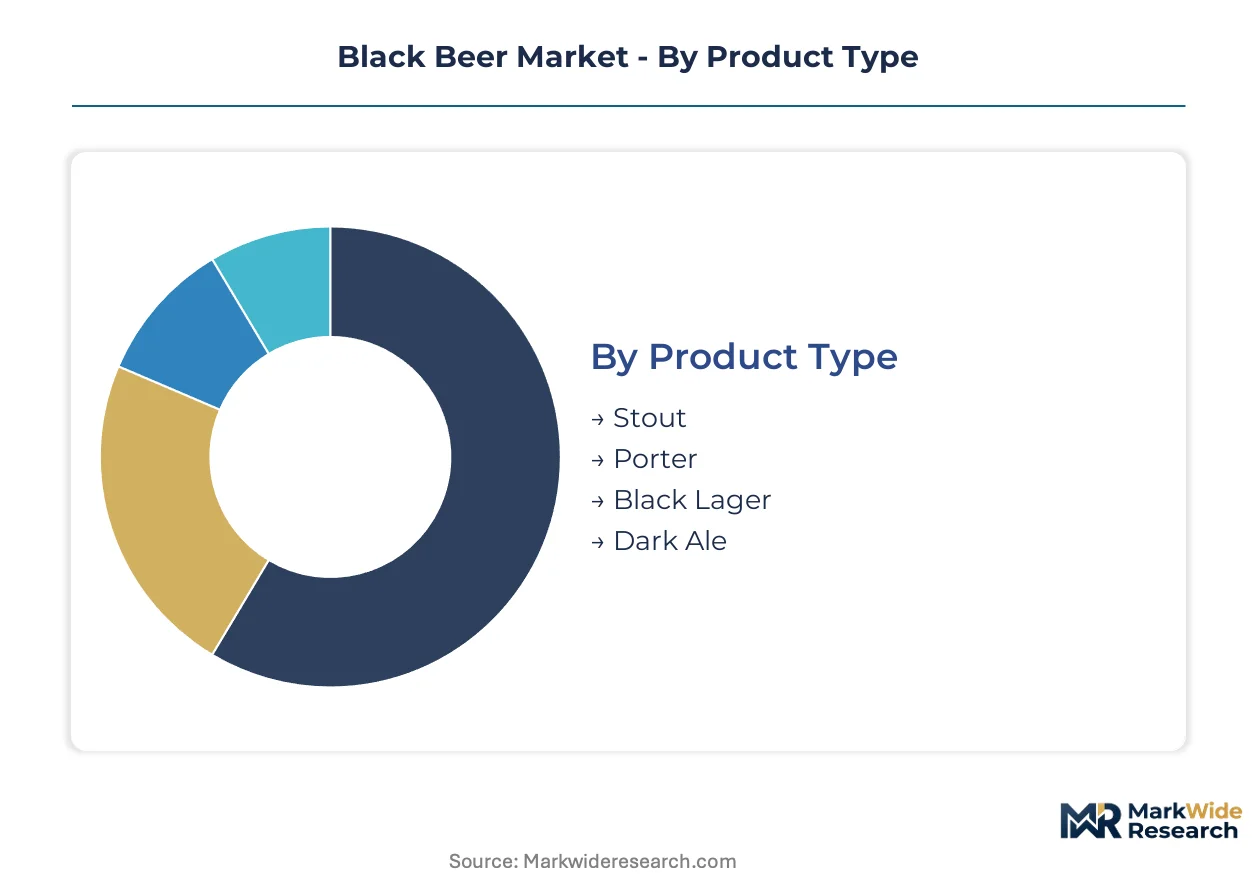
Black beer producers configure production lines and service networks around distinct consumption occasions and technical specifications. Each segment demands specialized roasting protocols, packaging formats, and channel relationships that reshape margin capture and capital deployment priorities.
Product Type:
After-sales intensity concentrates in draft dispensing systems and nitrogen widget replacement programs for premium formats, driving recurring service revenue beyond initial bottle sales.
- Stout:Kilned roasted barley formulations exceed 40 EBC color units with nitrogenated texture profiles. Demand clusters in Germany and Ireland where draught heritage sustains on-trade premium pricing and seasonal barrel-aging programs.
- Porter:Historical English brewing tradition yields lighter-bodied dark ales with chocolate malt complexity. Craft replication in Bavaria and London brewpubs is accelerating small-batch distribution through direct-to-consumer subscription channels.
- Black Lager:Cold-fermented dark variants bridge lager-drinking preferences with roasted flavor profiles.
- Dark Ale:Top-fermented specialty formulations target experimental craft segments with adjunct inclusions.
Stout holds the largest share; momentum sits with black lager as traditional lager markets develop dark variants.
Distribution Channel:
Channel selection determines working capital intensity, with brewpub direct sales compressing cash conversion cycles versus retail distribution with extended payment terms.
- Retail:Supermarket and liquor store placements sustain volume scale for packaged stout and porter portfolios. Shelf-space negotiations in German and Czech chains demand trade marketing investment that erodes margin for mid-sized producers.
- Brewpubs:Taproom direct distribution eliminates wholesale intermediaries and captures highest-margin pool. Urban clusters in Berlin, London, and Amsterdam concentrate enthusiast demand for limited-release dark ale series.
- Online:Subscription and e-commerce platforms enable geographic expansion without distributor relationships.
- Wholesale:Traditional three-tier distribution remains essential for volume penetration in regulated markets.
Brewpubs deliver peak margin per hectoliter; online channels are gaining share fastest among craft-forward urban demographics.
Consumer Type:
Consumer segmentation shapes recipe development cycles, with enthusiast segments demanding rapid innovation cadences that strain production scheduling.
- Craft Beer Enthusiasts:Educated drinkers prioritize provenance transparency and experimental flavor profiles. Concentration in Amsterdam, Copenhagen, and Manchester drives demand for barrel-aged porter and single-origin dark ale releases with documented malt sourcing.
- Casual Drinkers:Mainstream consumers seek approachable dark beer introductions through familiar brand extensions. German and Austrian markets show strongest penetration where black lager variants bridge traditional lager preferences.
- Specialty Stores:Curated retail buyers influence portfolio composition through selective distribution agreements.
- Occasional Consumers:Seasonal and holiday-driven purchasers concentrate demand in winter months.
Craft enthusiasts command premium pricing power; casual drinkers represent the steepest expansion trajectory for format simplification and accessibility.
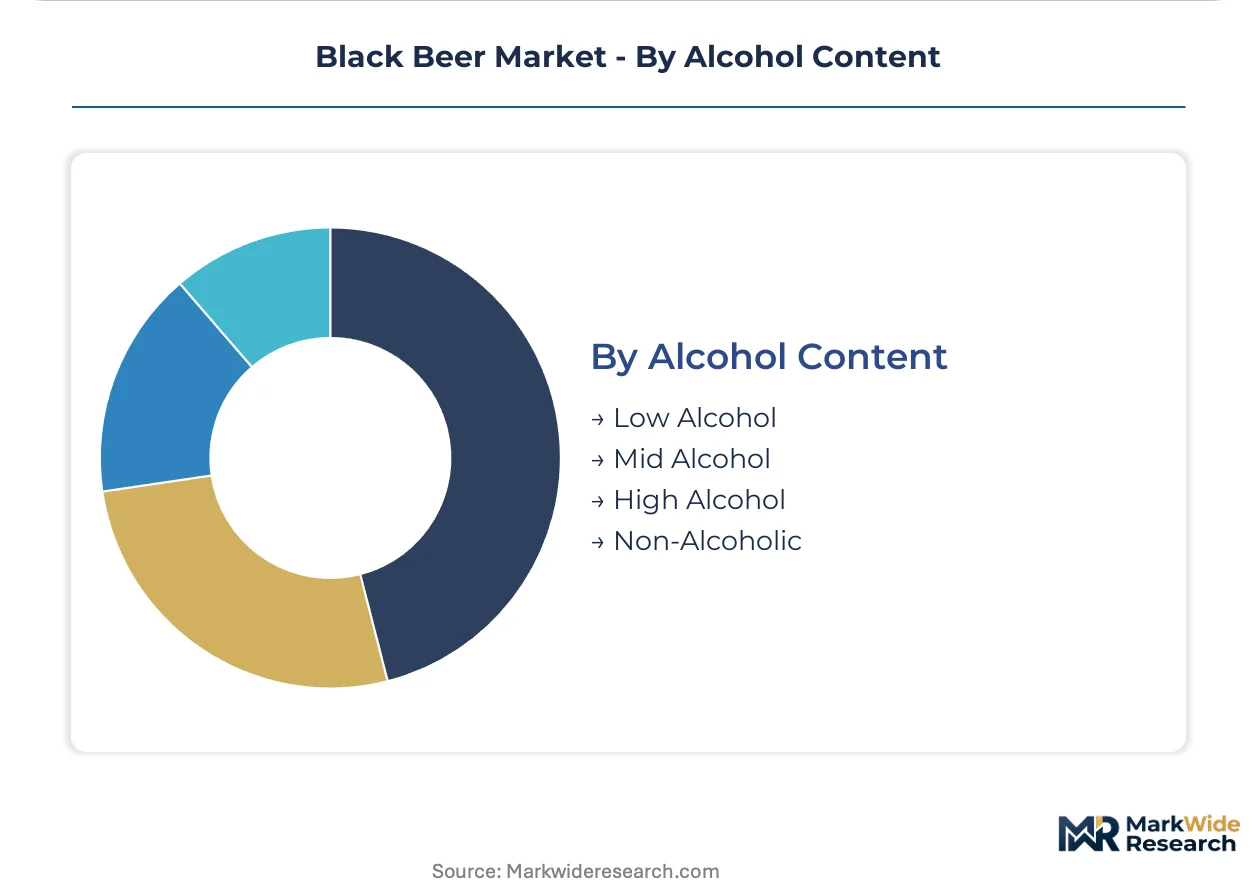
Alcohol Content:
Regulatory classification thresholds determine labeling requirements and tax treatment, with mid-alcohol formulations facing complex compliance across German BfR and US TTB jurisdictions.
- Mid Alcohol:Standard 4-6% ABV formulations dominate commercial volume and balance flavor intensity with sessionability. German Reinheitsgebot-compliant production and Czech brewing traditions sustain category standardization across European markets.
- Non-Alcoholic:Dealcoholization membrane technology enables sub-0.5% ABV stout variants. MOHAP import pathways in UAE and Saudi Arabia are opening first-mover positioning for alcohol-free dark beer portfolios in Middle Eastern markets.
- Low Alcohol:Reduced-strength variants target health-conscious segments with modified fermentation protocols.
- High Alcohol:Imperial and barrel-aged expressions command super-premium positioning with extended aging requirements.
Mid alcohol maintains volume leadership; non-alcoholic formats are climbing the fastest on regulatory-enabled market access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brewers capture 40-60 point margin premiums through Reinheitsgebot heritage positioning, while Indian microbreweries face compressed pricing power under state-level excise fragmentation. This asymmetry shapes capital deployment patterns across dark beer production networks.
Germany
Bavaria's craft brewery density sustains stout and porter demand through trained malt-roasting labor pools. BfR guidance on food-contact materials tightens additive disclosure standards for brewing formulations. Munich and Berlin clusters concentrate nitrogenated widget production for export-ready dark lager portfolios.
United States
TTB formula approval timelines delay seasonal dark beer launches by 6-12 months, constraining innovation cadences. The three-tier distribution system fragments wholesale access for porter specialists. Pacific Northwest malt roasting capacity anchors supply for craft stout producers in Oregon and Washington.
India
FSSAI craft classification enables microbrewery licensing in Maharashtra and Karnataka, opening warm-climate positioning for dark ale portfolios. State excise variation fragments pricing power across sub-national markets. Mumbai and Bangalore brewpub clusters drive direct-to-consumer subscription adoption for limited-release porters.
United Kingdom
London and Manchester urban craft enthusiasts prioritize curated dark beer shipments over supermarket discovery. REACH chemical authorization deadlines for enzymatic processing aids trigger reformulation investments ahead of 2024 sunset dates. Scottish manufacturing footprints support vertical integration across stout production for export markets.
United Arab Emirates
MOHAP import pathways enable alcohol-free stout positioning in Middle Eastern markets through sub-0.5% ABV variants. Dealcoholization membrane advances compress production costs for non-alcoholic dark beer formats. Dubai hospitality clusters drive on-trade premiumization for black lager introductions.
Black Beer Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with formulation and roasting expertise. The vendor base organizes around three structural tiers: multinational brewers with controlled distribution networks, regional craft specialists with taproom direct models, and contract manufacturers serving asset-light entrants. Two competitive moves dominate: brewpub leasing models that bypass wholesale markups, and nitrogen infusion technology licensing that replicates draught texture in packaged formats.
Within the multinational tier, Heineken N.V. and Anheuser-Busch InBev SA/NV anchor European and global dark lager distribution through controlled on-trade channels. Among craft specialists, BrewDog exemplifies vertical integration from Scottish manufacturing footprints, while The Boston Beer Company occupies a position defined by R&D intensity in specialty formulations. These three represent distinct archetypes: network-controlled distribution, captive production geography, and innovation-led portfolio construction.
| Leading Market Players |
|---|
| Anheuser-Busch InBev SA/NV |
| Heineken N.V. |
| The Boston Beer Company |
| Carlsberg Breweries A/S |
| Asahi Group Holdings Ltd. |
| Diageo Plc |
| BrewDog |
| Sapporo Breweries Ltd. |
| New Belgium Brewing Company |
| Others |
Cost & Logistics Intelligence
Barley price volatility driven by climate stress on European harvests determines both the spread between craft and mass-market pricing tiers and the geographic configuration of roasting capacity investments. Three dominant malt suppliers control specialty roasting operations, concentrating cost risk and forcing brewers to choose between long-term contract premiums or spot market exposure.
Pricing Analysis
Craft beer enthusiasts anchor a three-tier pricing structure across premium, standard, and economy levels in the black beer market. Price differentiation hinges on provenance transparency and nitrogen infusion certification, with barrel-aged releases commanding substantial premiums over base stout formulations. Cost compression in the mid-alcohol segment is intensifying because German BfR additive scrutiny extends R&D-to-market timelines. Casual drinkers in German and Austrian markets exhibit highest price sensitivity, while craft enthusiasts in Amsterdam and Copenhagen demonstrate lowest elasticity for limited-release porter series.
Supply Chain Analysis
Extended payment terms from German and Czech maltsters strain working capital for craft brewers expanding dark beer portfolios. Roasted malt supply concentrates in Germany, the Czech Republic, and Belgium, with specialty kilning operations drawing from heritage barley varieties and precision fermentation inputs. Single-source vulnerability runs through nitrogen widget manufacturing, where two component suppliers serve the European stout packaging market. Distribution runs through brewpub direct channels in Berlin, London, and Amsterdam, bypassing wholesale markups that erode margin in retail supermarket placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The black beer market sits at a winter-demand cyclical recovery driven by cold-weather consumption patterns that intensify premium dark beer purchasing. This cyclicality rewards brewers with flexible contract brewing capacity and nitrogenated packaging readiness.
For Market Incumbents: Pre-empt hard seltzer substitution threats by accelerating alcohol-free stout development for Middle Eastern markets through MOHAP import pathways. Consolidate roasting technician expertise through automated roast curve replication investments that offset retiring German maltster knowledge gaps. Channel control through taproom leasing models captures 40-60 point margin improvements versus wholesale-dependent competitors.
For New Entrants and Emerging Players: Indian microbrewery licensing in Maharashtra and Karnataka offers first-mover positioning for dark ale portfolios in warm-climate markets with limited incumbent craft density. Direct-to-consumer subscription models bypass slotting fee negotiations with German and Czech retail chains. The most penetrable entry angle targets craft enthusiasts in Mumbai and Bangalore brewpub clusters with documented single-origin malt sourcing narratives.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors contract manufacturing platforms with asset-light brewing infrastructure. Long-term viability over the next decade rests on nitrogen infusion technology licensing and dealcoholization membrane capabilities rather than traditional malt roasting assets. The signal to watch is FSSAI regulatory expansion into additional Indian states, which would indicate addressable market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealcoholization Technology Licensing | MOHAP import pathways in UAE and Saudi Arabia unlock non-alcoholic stout positioning in previously inaccessible markets. |
| Taproom Leasing Model Expansion | Berlin, London, and Amsterdam urban clusters concentrate enthusiast demand for highest-margin direct distribution. |
| Automated Roast Curve Replication | Inline spectroscopy with AI optimization virtualizes quality control without dedicated sensory panels or retiring technician dependency. |
| Subscription Fulfillment Infrastructure | Curated monthly shipments displace supermarket discovery for limited-release dark ale series in craft-forward demographics. |
| REACH Compliance Reformulation | ECHA sunset deadlines for enzymatic processing aids force additive substitution programs ahead of competitor timelines. |
Research Approach
A spread of perspectives from craft brewery founders, malt roasting technicians, TTB regulatory consultants, brewpub operators, and nitrogen packaging engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against BfR guidance documents, EU Green Deal packaging directives, FSSAI microbrewery licensing records, and ECHA REACH chemical authorization databases. Bottom-up volume modeling from individual brewery capacity and top-down category sizing from trade flow data were triangulated to establish market boundaries.
Demand-supply balance framing anchored the projection methodology across the analysis window, with segmentation modeled by product type, distribution channel, consumer archetype, and alcohol content tier. CAGRs were derived from historical growth pattern analysis and forward-looking capacity expansion announcements. Key forecast inputs included barley harvest yield projections from German and Czech agricultural ministries and nitrogen widget production capacity disclosures from packaging equipment manufacturers.
Practitioners should monitor BfR additive disclosure tightening, EU recycled glass mandate implementation timelines, and Indian state-level excise harmonization for early signals of forecast deviation. The analysis reflects assumptions about continued craft brewery density growth in Bavaria and sustained TTB formula approval delays. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
UK Tequila Market