
 Cocamidopropyl Betaine Market | 2026-2036
Cocamidopropyl Betaine Market Size, Share, and Industry Trends Forecast 2026-2036
Cocamidopropyl Betaine Market Analysis
Specialty cosmetics formulators is unwinding legacy reliance on mass-market household brands for CAPB procurement. Solvay leverages its integrated fatty acid chain to secure feedstock cost advantages across European operations. Galaxy Surfactants anchors its position through dedicated amphoteric surfactant capacity serving Asian personal care exporters. Stepan competes on technical service depth, embedding application laboratories near North American customer bases.
Cocamidopropyl betaine is an amphoteric surfactant synthesized from coconut oil fatty acids and dimethylaminopropylamine, typically supplied at concentrations between 30% and 35% active matter in aqueous solution with sodium chloride as a viscosity modifier. The compound functions primarily as a foam booster, viscosity builder, and mildness agent in rinse-off personal care products where it mitigates irritation from anionic primary surfactants. Liquid formulations dominate volume throughput due to handling efficiency in automated batching systems, though powder grades command margin premiums in solid detergent tablet applications. Personal care applications absorb the dominant share of value through high-specification cosmetic grades, while agricultural adjuvant uses represent a faster-growing outlet driven by glyphosate formulation compatibility requirements.
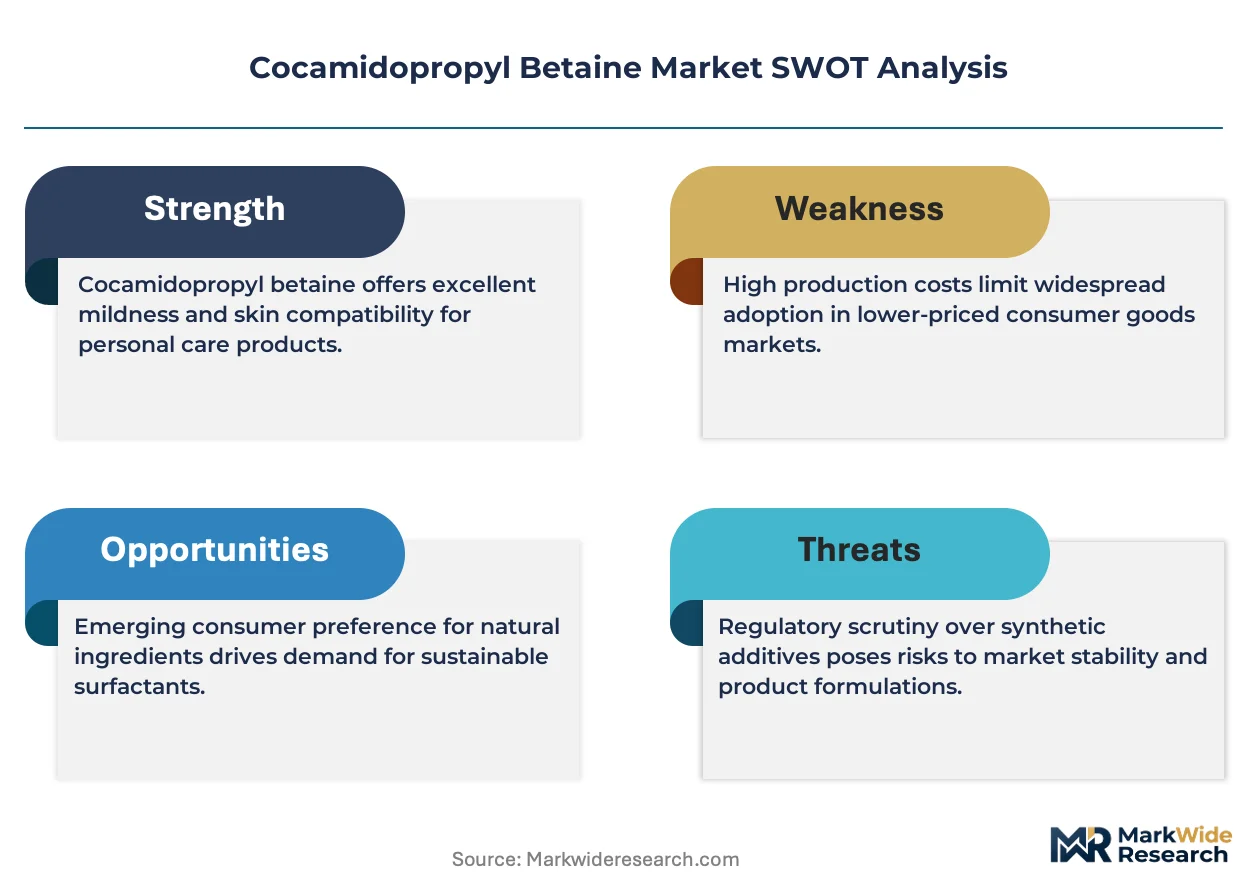
REACH registration mandates in Europe and EPA Safer Choice criteria in the United States enforce progressively lower limits on amidoamine and DMAPA residuals, forcing purification technology upgrades across manufacturing networks. BIS certification requirements in India and FDA cosmetic ingredient oversight in the United States add layered compliance burdens for exporters serving multiple jurisdictions. Stakeholders must monitor regulatory divergence on nitrosamine precursor thresholds, as divergent maximum residue limits threaten to fragment product specifications and complicate inventory pooling strategies across regional supply nodes.
Market Dynamics
Sulfate-free formulation mandates from personal care brands are compressing procurement timelines for amphoteric surfactant systems. REACH amidoamine residual limits and EPA Safer Choice criteria force simultaneous purification upgrades across multi-jurisdictional supply networks.
Growth Catalysts
- REACH Purity Thresholds:Tighter amidoamine limits in Europe accelerate technical-grade CAPB replacement with cosmetic-grade material. Specialty formulators capture margin expansion from compliance-driven specification upgrades.
- Sulfate-Free Personal Care:Rinse-off cosmetic brands eliminate sodium lauryl sulfate, embedding CAPB as primary mildness agents. Foam-boosting functionality preserves consumer sensory expectations through formulation transition.
- India Contract Manufacturing:Domestic personal care toll producers expand amphoteric surfactant consumption serving export-oriented beauty brands. BIS certification requirements anchor local supply chain development.
Market Restraints
- Coconut Oil Feedstock Volatility:Fatty acid derivative pricing tracks tropical commodity swings. Philippine and Indonesian supply disruptions transmit directly to CAPB production economics.
- Amidoamine Purification Costs:Residual reduction to sub-0.5% levels demands membrane filtration or molecular distillation capex. Mid-scale manufacturers face stranded asset risk from single-technology bets.
- Biosurfactant Substitution:Rhamnolipid and sophorolipid fermentation processes achieve commercial scale in agricultural adjuvant applications. Personal care grade parity remains 3-5 years distant.
Strategic Opportunities
- Agricultural Adjuvant Compatibility:Glyphosate formulation stability requirements favor CAPB amphoteric characteristics. Brazilian and Argentinian crop protection distributors represent underpenetrated demand nodes.
- Powder Grade Solid Detergents:Tablet and pod format growth in automatic dishwashing and laundry creates premium positioning for anhydrous CAPB derivatives. Handling efficiency in automated packaging lines drives specification pull.
- EU Green Deal Biodegradability:Ready biodegradability mandates under detergent regulation favor coconut-derived surfactants. CAPB suppliers with carbon-14 verification protocols access preferential procurement channels.
Industry Challenges
- Cross-Jurisdictional Compliance Synchronization:Divergent nitrosamine precursor thresholds between FDA cosmetic guidance and REACH registration create specification fragmentation. Inventory pooling across regional nodes requires grade segregation.
- Specialized Process Engineering Talent:Amphoteric surfactant synthesis expertise concentrates in legacy European and North American technical centers. Asian capacity expansion faces recruitment friction for DMAPA handling and quaternization control specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocamidopropyl Betaine Market |
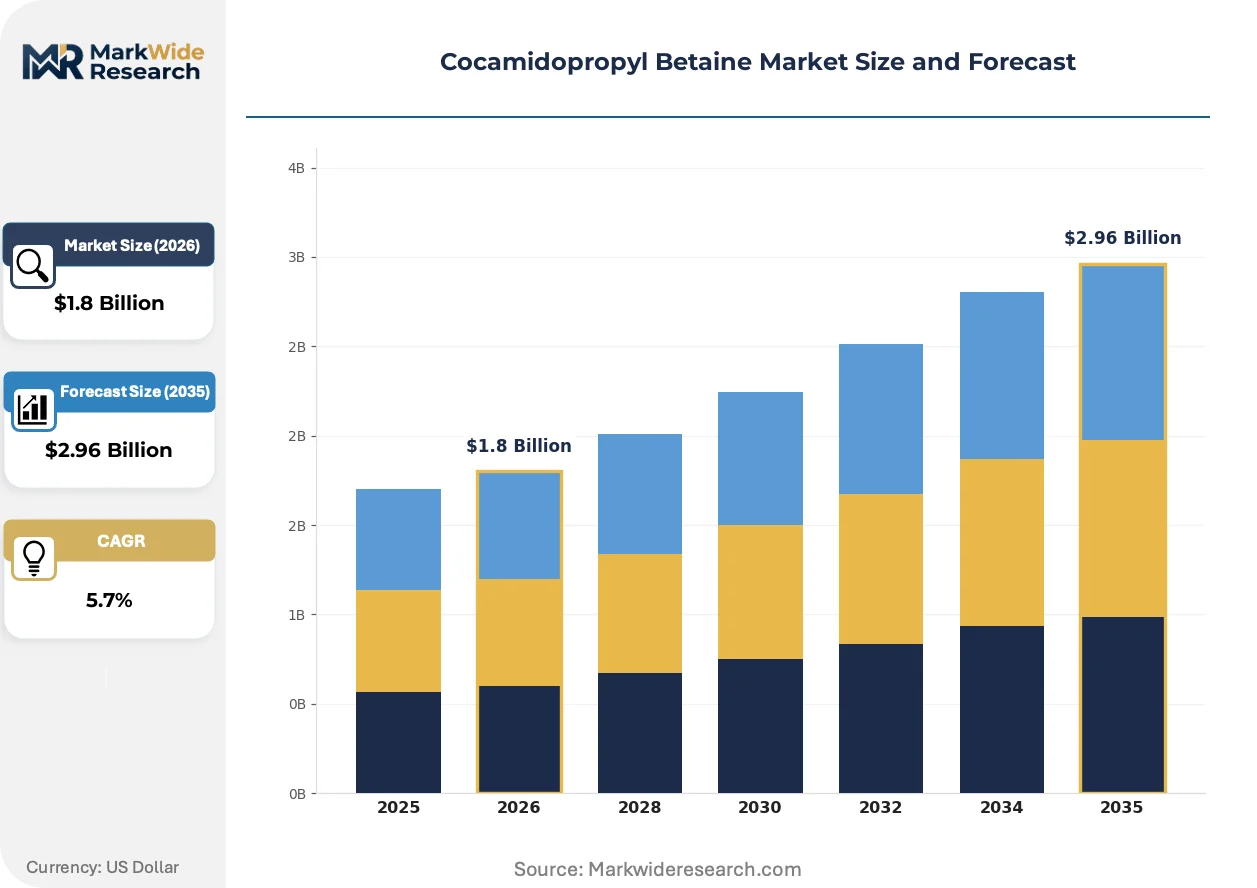
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Granule Application: Personal Care, Household Cleaning, Industrial Cleaning, Agricultural End User: Cosmetics Manufacturers, Cleaning Product Companies, Agrochemical Firms, Textile Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Lubrizol, KAO Chemicals, Solvay, Galaxy Surfactants, Stepan, Clariant, Evonik, Croda, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocamidopropyl Betaine Market Emerging Trajectories
Membrane filtration and continuous processing technologies are compressing purification economics while regulatory convergence pressures residual thresholds downward. Formulation science advances embed CAPB in novel delivery systems beyond conventional rinse-off applications.
Continuous membrane filtration systems are displacing batch vacuum distillation for amidoamine residual reduction. Specialty surfactant houses in Germany and the Netherlands deploy ceramic nanofiltration modules achieving sub-0.3% residual levels at 40% lower energy intensity. This displacement enables cosmetic-grade output from mid-scale reactors previously constrained to technical specifications.
EPA Safer Choice Master Criteria revision tightens aquatic toxicity thresholds for surfactant precursors. Manufacturers serving US institutional cleaning channels reformulate to meet direct release authorization. Agricultural adjuvant blenders face parallel pressure as state-level 303(d) listings expand impaired watershed designations.
Beauty brand technical teams now specify amidoamine and DMAPA residuals by individual molecule rather than aggregate class. Contract manufacturers in India and Mexico requalify supplier bases against certificate-of-analysis line-item requirements. This behavioral shift fragments procurement volumes across multiple qualified sources per manufacturing site.
Cocamidopropyl Betaine Market Segmentation
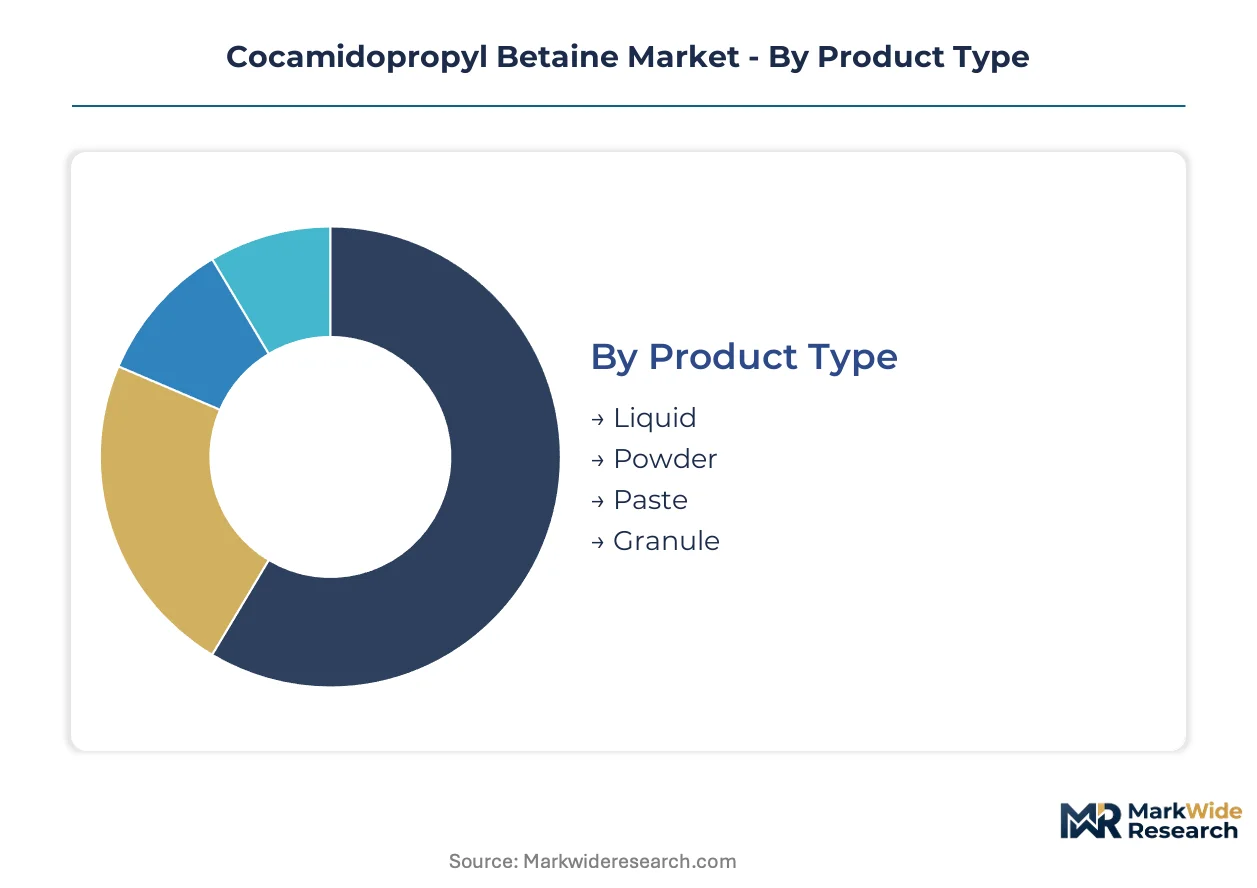
Segmentation in the CAPB market reflects divergent purity requirements and handling economics across end-use channels. Cosmetic-grade specifications command premium positioning through REACH and FDA compliance, while technical grades serve volume-driven industrial applications.
Product Type:
Liquid formulations dominate automated batching channels in personal care contract manufacturing, while solid formats penetrate detergent tablet and pod packaging lines.
- Liquid:Supplied at 30-35% active matter in aqueous solution with sodium chloride viscosity modification. Bulk tanker deliveries serve German and Dutch surfactant compounders operating continuous production lines.
- Powder:Anhydrous derivatives command margin premiums in automatic dishwashing and laundry tablet applications where moisture sensitivity threatens formulation stability. Handling efficiency in high-speed packaging equipment drives specification pull from Procter & Gamble and Unilever supply chains.
- Paste:Intermediate viscosity grades suit semi-automatic mixing operations in mid-scale cosmetics manufacturing.
- Granule:Free-flowing formats target solid detergent producers seeking dust-free handling characteristics.
By volume, liquid leads. By growth pace, powder is gaining share fastest through solid-format detergent expansion.
Application:
Cost tiers separate cosmetic-grade CAPB from technical specifications, with purification intensity determining margin capture across use cases.
- Personal Care:Rinse-off cosmetics absorb the dominant value share through high-specification grades mitigating anionic surfactant irritation. Sulfate-free formulation mandates from L'Oréal and Estée Lauder procurement teams embed CAPB as primary mildness agents.
- Household Cleaning:Institutional and consumer detergents utilize technical-grade material where foam boosting supersedes skin mildness requirements. EPA Safer Choice criteria tighten aquatic toxicity thresholds for US institutional channels.
- Industrial Cleaning:Metal degreasing and parts washing applications prioritize cost efficiency over residual specifications.
- Agricultural:Glyphosate formulation compatibility requirements favor CAPB amphoteric characteristics for drift reduction and leaf surface wetting. Brazilian crop protection distributors represent underpenetrated demand nodes.
Personal care generates the highest margins per kilogram. Agricultural adjuvant applications show the steepest expansion trajectory through herbicide formulation growth.
End User:
Customer sophistication varies from certificate-of-analysis line-item scrutiny among cosmetics formulators to bulk volume contracting by industrial cleaners.
- Cosmetics Manufacturers:Specialty formulators specify amidoamine and DMAPA residuals by individual molecule rather than aggregate class, fragmenting procurement volumes across multiple qualified sources per manufacturing site.
- Cleaning Product Companies:Mass-market household brands unwind legacy reliance on integrated surfactant supply, accelerating third-party CAPB procurement.
- Agrochemical Firms:Glyphosate blenders seek formulation stability through amphoteric surfactant compatibility.
- Textile Producers:Scouring and wet processing applications utilize CAPB for fiber lubrication and antistatic properties.
Cosmetics manufacturers impose the most stringent qualification requirements. Agrochemical firms are expanding procurement most aggressively.
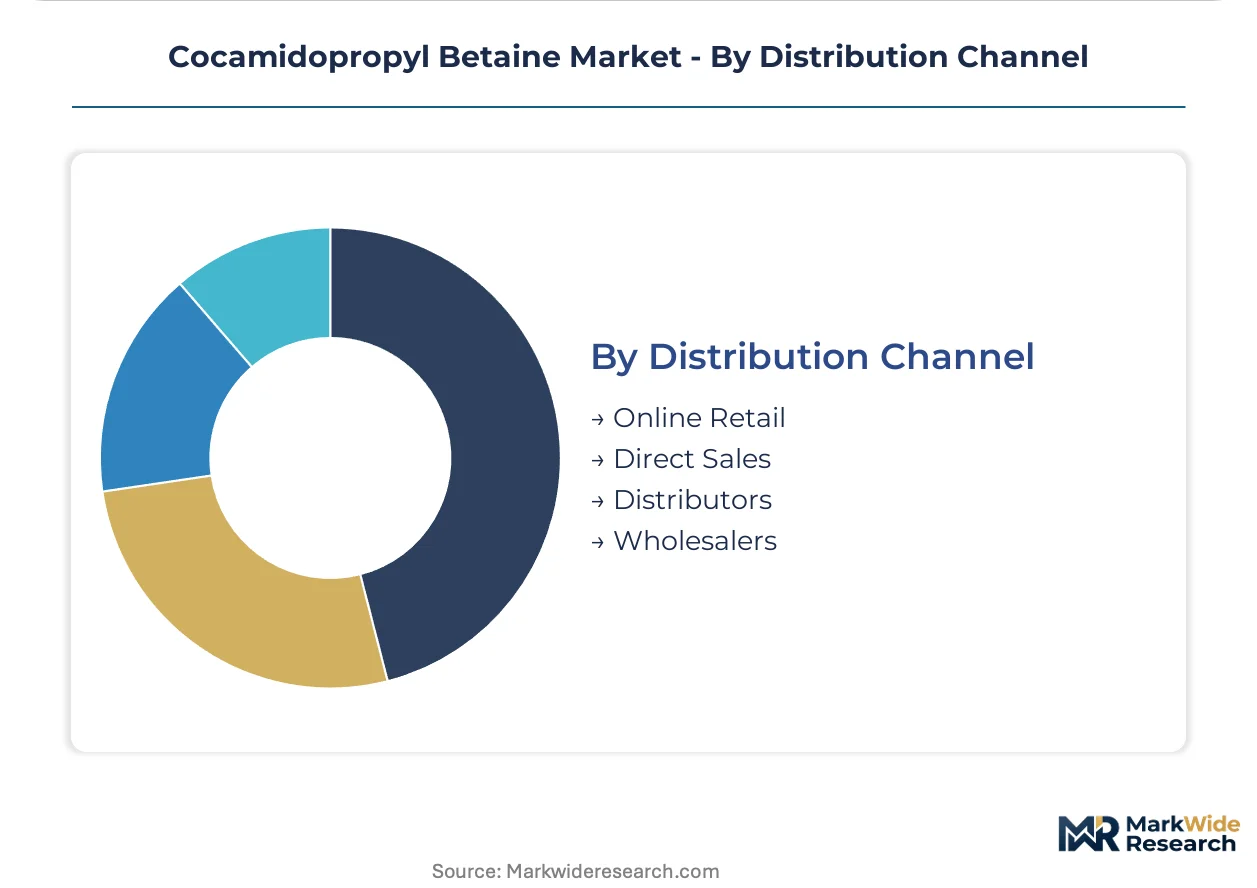
Distribution Channel:
Supply concentration in European and North American manufacturing clusters shapes logistics economics for geographically dispersed demand.
- Direct Sales:Multinational personal care brands negotiate frame contracts with Solvay, Stepan, and Galaxy Surfactants for dedicated capacity allocation and technical service embedding.
- Distributors:Regional chemical distributors serve mid-scale cosmetics manufacturers and industrial cleaners requiring smaller lot sizes and local inventory positioning.
- Online Retail:E-procurement platforms capture spot demand from research institutions and specialty formulators seeking rapid sample qualification.
- Wholesalers:Bulk commodity traders handle technical-grade volumes for agricultural and industrial applications with less stringent specification requirements.
Direct sales anchor the highest volume throughput. Online retail channels are climbing the fastest through digital procurement adoption among specialty formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics formulators and agricultural blenders concentrate procurement power across five national markets where regulatory stringency and manufacturing scale intersect. Each geography presents distinct compliance architectures and supply chain configurations.
United States
Personal care brands in New Jersey and California drive sulfate-free formulation adoption, embedding CAPB as primary mildness agents. EPA Safer Choice criteria tighten aquatic toxicity thresholds for surfactant precursors. The New Jersey chemical corridor hosts Stepan application laboratories embedding technical service near customer batching operations.
Germany
REACH amidoamine residual mandates accelerate cosmetic-grade substitution for technical-grade material across Rhine-Ruhr surfactant compounders. ECHA registration requirements enforce progressively lower DMAPA limits through 2025-2030 review cycles. Leverkusen and Ludwigshafen clusters concentrate membrane filtration technology deployment for sub-0.3% residual achievement.
India
Domestic contract manufacturers serving export-oriented beauty brands expand amphoteric surfactant consumption through Maharashtra and Gujarat toll production facilities. BIS certification requirements anchor local supply chain qualification protocols. Mumbai-Pune industrial corridor attracts Galaxy Surfactants dedicated capacity serving Asian personal care exporters.
Brazil
Agricultural adjuvant blenders seek glyphosate formulation compatibility through CAPB amphoteric characteristics for drift reduction. ANVISA cosmetic ingredient oversight parallels FDA stringency for imported personal care materials. São Paulo state crop protection distributors represent underpenetrated demand nodes for herbicide formulation growth.
China
Yangtze River Delta surfactant producers scale amphoteric capacity serving domestic sulfate-free personal care brands. NMPA cosmetic ingredient registration and GB standards compliance create dual-track qualification requirements for export-bound versus domestic-consumption grades. Shanghai chemical parks concentrate continuous processing technology adoption.
Cocamidopropyl Betaine Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates and specialty surfactant houses with captive fatty acid supply. Structure concentrates around three tiers: multinational chemical majors with backward integration into coconut oil derivatives, mid-scale regional specialists with purification technology focus, and toll manufacturers serving contract formulation demand. Dominant competitive moves include membrane filtration technology licensing for residual reduction and geographic expansion through dedicated amphoteric capacity in Asian manufacturing clusters.
Within the integrated petrochemical tier, Solvay leverages its European fatty acid chain position, while Stepan anchors North American technical service depth through embedded application laboratories. Galaxy Surfactants occupies the Asian specialist position with dedicated amphoteric capacity serving export-oriented personal care brands. BASF and Evonik represent diversified chemical majors where surfactant portfolios sit within broader performance materials divisions. Croda and Clariant exemplify specialty ingredient houses competing on cosmetic-grade certification depth rather than commodity scale.
| Leading Market Players |
|---|
| Lubrizol |
| KAO Chemicals |
| Solvay |
| Galaxy Surfactants |
| Stepan |
| Clariant |
| Evonik |
| Croda |
| BASF |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for cosmetic-grade CAPB concentrate pricing power among European membrane filtration specialists, compressing margin capture for mid-scale technical-grade producers. REACH amidoamine residual mandates and coconut oil feedstock volatility transmit directly through contract structures, fragmenting procurement across qualified supplier pools.
Pricing Analysis
Membrane filtration versus batch vacuum distillation pricing gaps separate cosmetic-grade premiums from technical-grade commoditization. Three-tier pricing structure across cosmetic, technical, and agricultural grades reflects purification intensity and certification depth. Price differentiation centers on REACH cosmetic-grade certification and EPA Safer Choice listing status. Pricing pressure intensifies in technical grades as biosurfactant alternatives achieve agricultural adjuvant parity. Agricultural blenders exhibit highest price sensitivity; sulfate-free cosmetics manufacturers absorb premium positioning.
Supply Chain Analysis
Philippines and Indonesia anchor coconut oil fatty acid supply for European and Asian CAPB synthesis networks. Manufacturing draws from dimethylaminopropylamine (DMAPA) and coconut fatty acid derivative feedstocks. Single-source vulnerability concentrates in Philippine coconut oil supply disruptions from climate events. Distribution runs through bulk tanker deliveries to German and Dutch compounders, regional distributors for mid-scale cosmetics manufacturers, and direct frame contracts for multinational personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection manifests through formulation science interoperability: CAPB specification databases now integrate directly with beauty brand product lifecycle management systems, creating API-layer value capture for data-enabled suppliers.
For Market Incumbents: Fortify membrane filtration technology licensing positions against ceramic nanofiltration module commoditization. Secure captive coconut fatty acid supply through Philippine and Indonesian toll processing agreements. Defensive moves center on REACH cosmetic-grade certification depth and embedded application laboratory technical service near North American customer batching operations. Threat vector: biosurfactant fermentation scale-up in agricultural adjuvant channels. For New Entrants and Emerging Players: Technical-grade to cosmetic-grade purification service gaps in Indian and Mexican contract manufacturing clusters offer white-space entry. Target BIS-certified toll production facilities serving export-oriented beauty brands. Penetrate through certificate-of-analysis line-item qualification protocols that fragment incumbent procurement volumes. Go-to-market angle: rapid sample qualification via e-procurement platforms for specialty formulators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors where surfactant portfolios sit within broader performance materials divisions. Long-term viability frames CAPB as sulfate-free formulation infrastructure with agricultural adjuvant optionality. Target archetype: mid-scale European specialists with membrane filtration technology and stranded cosmetic-grade capacity. Signal to watch: EPA Safer Choice Master Criteria revision timing for aquatic toxicity threshold tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Ceramic nanofiltration deployment enables sub-0.3% amidoamine residual achievement at lower energy intensity. |
| Backward Integration into Coconut Fatty Acids | Philippine and Indonesian toll processing agreements secure feedstock cost advantages against commodity swings. |
| REACH Cosmetic-Grade Certification Investment | ECHA registration compliance opens premium procurement channels for sulfate-free personal care formulations. |
| Long-term Supply Agreement with Agrochemical Distributors | Brazilian and Argentinian glyphosate blender contracts anchor agricultural adjuvant volume growth. |
| Joint Venture in Asian Manufacturing Clusters | Maharashtra and Gujarat toll production facilities serve export-oriented beauty brand contract manufacturing demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Plant managers at European and Asian CAPB manufacturing facilities, procurement leads at L'Oréal and Estée Lauder formulation centers, distribution channel partners in German and Dutch chemical clusters, and technical R&D directors at specialty surfactant houses provided operational data. Secondary validation drew from ECHA REACH registration databases, EPA Safer Choice listed product registries, BIS certification records, and customs trade data for coconut fatty acid derivatives. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Across the analysis window, forecasts reflect analytical frameworks segmenting by product type (liquid, powder, paste, granule), application (personal care, household cleaning, industrial cleaning, agricultural), and end user sophistication tier. CAGRs derive from regression analysis against sulfate-free formulation adoption curves and agricultural adjuvant volume expansion. Industry-specific inputs include REACH amidoamine residual limit phase-in schedules and glyphosate formulation compatibility testing protocols.
Underlying assumptions cover REACH and EPA regulatory convergence timelines, with deviation risk concentrated in nitrosamine precursor threshold divergence between jurisdictions. Coconut oil commodity price volatility and biosurfactant fermentation scale-up pace represent additional forecast revision triggers. Recalibration cycles align with material shifts in ECHA registration review cycles and EPA Safer Choice Master Criteria revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Powder Defoamers Market
Surfactants
Superwetting Surfactants Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Global Rhamnolipid Market
Surfactants
Zeolite for Detergents Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Lauramide DEA Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Emulsifying Wax Market
Surfactants
Selenium Sulphide Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market